
 Pencil Sharpeners Market | 2026-2036
Pencil Sharpeners Market Size, Share, and Industry Trends Forecast 2026-2036
Pencil Sharpeners Market Analysis
CE marking is consolidating the cost-of-entry calculus for European manufacturers of electric and battery-operated sharpeners. Dahle GmbH & Co. KG leverages its German engineering heritage to dominate industrial-grade manual sharpeners for professional draftsmen. Staedtler Mars GmbH & Co. KG anchors its position through in-house production of precision-milled steel cutting cylinders. Faber-Castell AG differentiates via vertical control over cedar-cased pencil ecosystems that bundle premium sharpeners.
A pencil sharpener is a mechanical device that removes wood and graphite from a pencil tip through rotary or planar abrasion, typically employing helical or flat blade geometries with cutting angles between 20 and 30 degrees to achieve conical or chisel-point profiles for writing, drafting, or artistic shading. Manual sharpeners retain the largest installed base due to zero power dependency and minimal unit cost, while electric variants capture the fastest growth trajectory in high-volume institutional settings where throughput speed governs procurement decisions. Metal-bodied sharpeners command durable goods positioning and replacement-part revenue streams, whereas plastic housings compete on color customization and lightweight portability for student segments.
The EU's REACH regulation restricts phthalate content in plastic housings, while the US Consumer Product Safety Commission governs blade exposure and small-part ingestion risks for school-grade products. Japan's METI enforces JIS standards for blade hardness and dimensional consistency that shape export eligibility for Asian manufacturers. Stakeholders must monitor evolving material compliance timelines and decide whether to absorb certification costs or cede regulated segments to incumbent specialists.
Market Dynamics
REACH compliance is compressing plastic housing formulations across European supply chains, forcing manufacturers to reformulate phthalate-free polymers or abandon student-grade segments to Asian competitors with alternative material platforms.
Growth Catalysts
- Heritage stationery clusters:German manufacturing districts around Nuremberg and Stein concentrate precision-milling capabilities for helical steel cylinders, drawing institutional procurement toward CE-marked suppliers.
- Electric throughput advantages:Battery-operated sharpeners with auto-stop sensors are displacing manual units in high-volume school districts where janitorial labor costs exceed equipment amortization.
- Art supply retail expansion:Specialty retailers are dedicating linear footage to premium sharpening stations that bundle replacement blade cartridges with cedar-cased pencil assortments.
Market Restraints
- Steel price volatility:Cold-rolled Swedish steel for cutting cylinders faces input cost swings that erode margin on metal-bodied premium units.
- Substitution by mechanical pencils:Drafting professionals in Japanese technical institutes are migrating to 0.5mm lead advancement systems that eliminate sharpening entirely.
- REACH certification timelines:ECHA registration dossiers for alternative plasticizers extend product launch cycles by 18-24 months for reformulated housings.
Strategic Opportunities
- India's education infrastructure:State-level textbook procurement in Maharashtra and Karnataka is bundling manual sharpeners with standardized examination kits for rural secondary schools.
- Repairable design mandates:France's repairability index legislation creates preference for metal-bodied sharpeners with field-replaceable blade cartridges over sealed plastic units.
- Museum and conservation channels:Archival-grade sharpening stations with adjustable cutting angles are penetrating institutional conservation labs that service graphite-based artworks.
Industry Challenges
- Blade hardness calibration:JIS-standard Rockwell testing requires capital investment in metallurgical laboratories that smaller Taiwanese contract manufacturers lack.
- Multi-jurisdiction labeling:Simultaneous compliance with CE marking, FCC electromagnetic emissions, and Japan's Electrical Appliance and Material Safety Law fragments packaging and documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pencil Sharpeners Market |
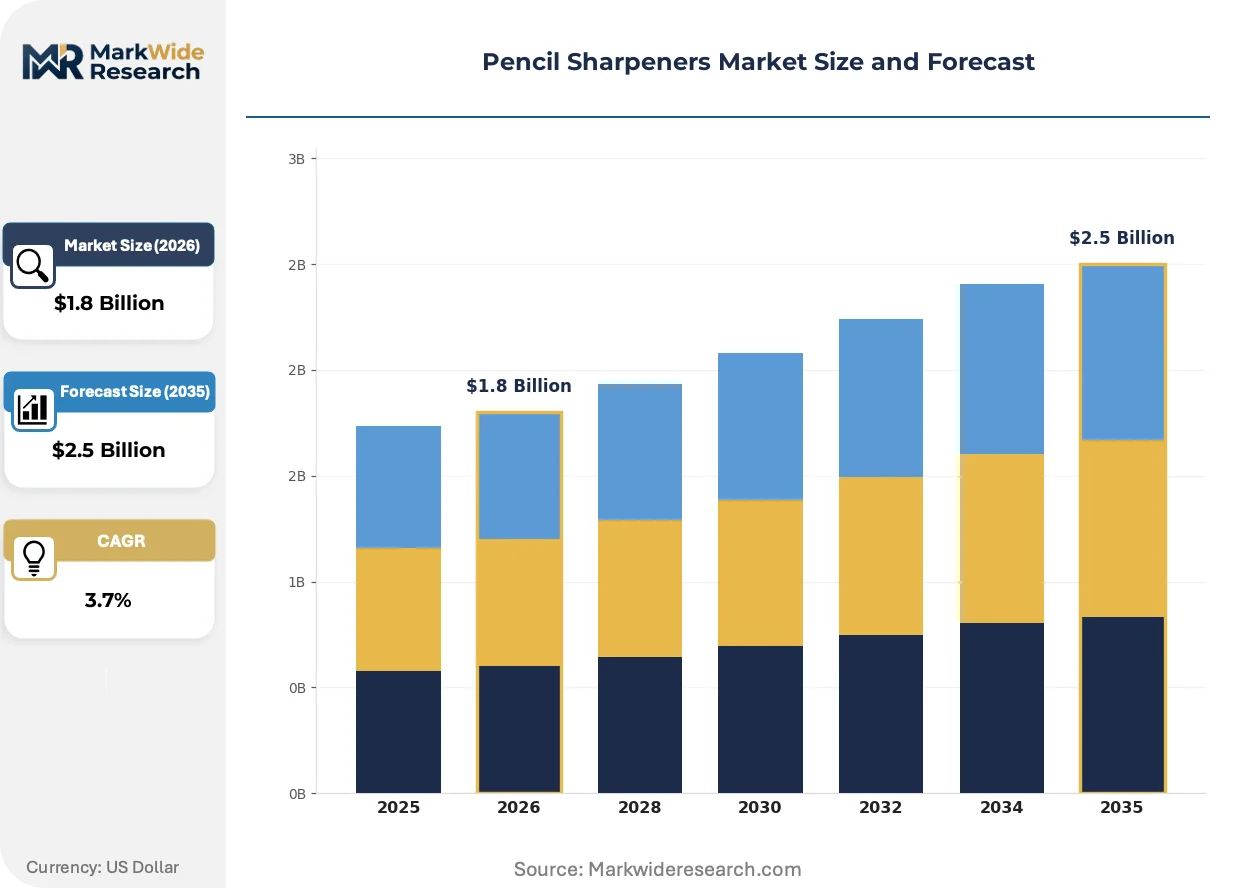
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Manual, Electric, Battery-operated, Dual-action Application: School, Office, Art, Crafting Material: Plastic, Metal, Wood, Composite End User: Students, Professionals, Artists, Hobbyists |
| Companies Covered | Dahle GmbH & Co. KG, Kum Limited, Staedtler Mars GmbH & Co. KG, CARL Manufacturing Co., Ltd., MAPED SAS, Faber-Castell AG, Newell Brands Inc., Bostitch Office, Acme United Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pencil Sharpeners Market Emerging Trajectories
Helical blade geometry and sensor-integrated motor controls are converging to redefine performance benchmarks, while regulatory material bans and circular-economy mandates reshape product architecture decisions.
Helical steel cutting cylinders with precision-ground 23-degree cutting angles are unifying professional and educational segments around a single blade specification. Art supply retailers in Berlin and Vienna are standardizing display assortments on this geometry. The convergence is compressing demand for legacy flat-blade planar sharpeners into discount channels.
REACH Annex XVII restrictions on phthalate plasticizers are forcing housing material transitions toward bio-based polyamides or aluminum extrusions. German manufacturers with in-house polymer compounding capabilities are capturing shelf space from Asian competitors dependent on legacy PVC formulations. The regulatory friction is segmenting the market between certified premium metal bodies and uncertified economy plastic units.
Institutional procurement through cooperative purchasing agreements is consolidating school district demand toward pre-qualified vendor lists with documented compliance histories. Regional education service centers in Texas and California are displacing individual school-level purchasing authority. The concentration is visible most acutely in US K-12 segments where liability concerns dominate vendor selection criteria.
Pencil Sharpeners Market Segmentation
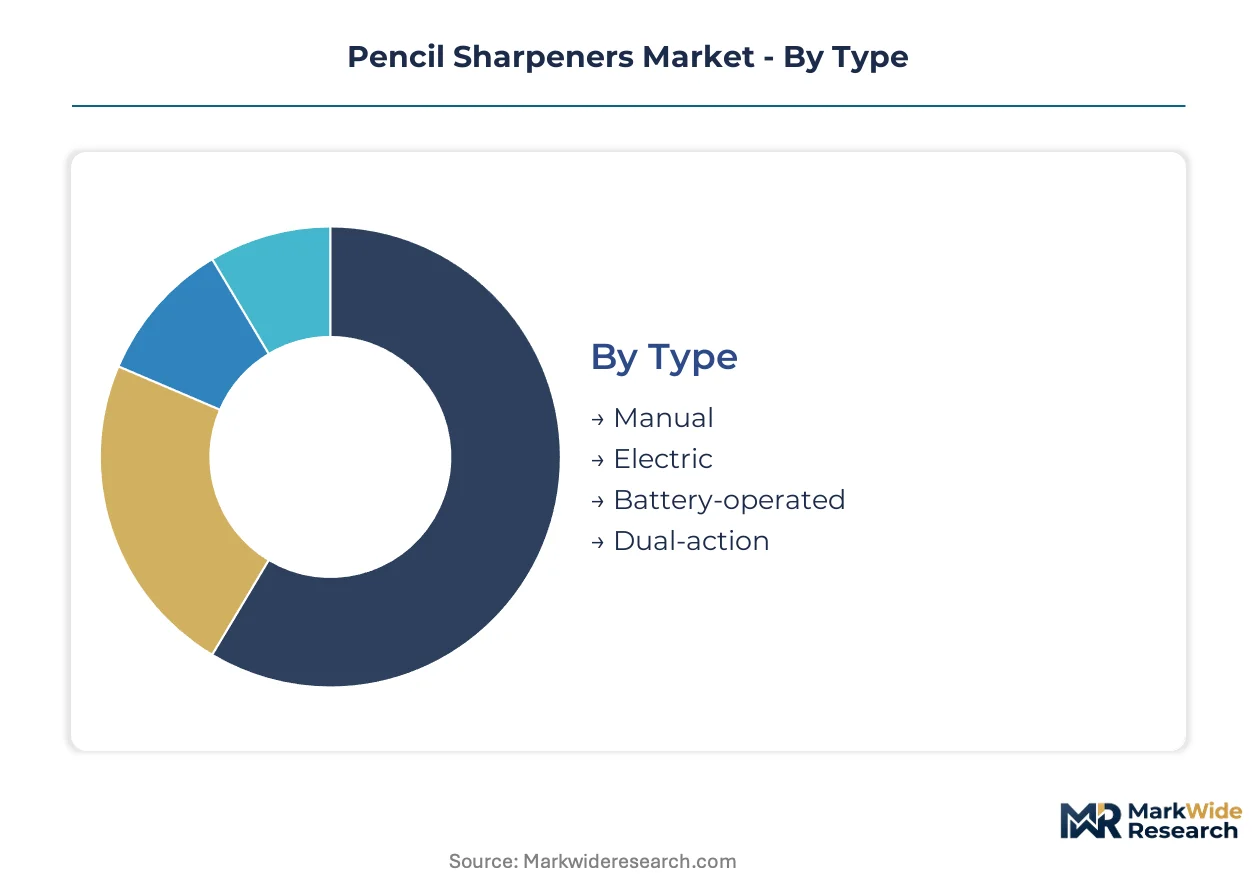
Pencil sharpener procurement splits sharply between high-volume institutional buyers prioritizing unit cost and low replacement frequency, and premium segments where blade precision and housing durability command price premiums. Segmentation reveals how material choices and power dependencies create distinct margin architectures across educational, professional, and artistic use cases.
Type:
Volume concentration favors zero-power mechanisms, while premium pricing attaches to motorized throughput capabilities.
- Manual:Helical steel cutting cylinders in die-cast zinc housings deliver 20-30 degree cutting angles without electrical dependency. Demand clusters in rural Indian secondary schools where Maharashtra and Karnataka state procurement bundles sharpeners with standardized examination kits, constrained by grid reliability concerns and janitorial labor availability.
- Electric:Sensor-integrated motor controls with auto-stop functionality achieve throughput speeds that displace manual units in high-volume North American school districts. Texas and California regional education service centers consolidate procurement toward pre-qualified vendor lists where documented compliance histories override unit cost considerations.
- Battery-operated:Portable power architectures serve mobile drafting professionals and field surveyors requiring sharpening capability without mains access.
- Dual-action:Hybrid mechanisms switching between manual and electric modes capture transitional segments upgrading from hand-cranked legacy equipment.
Mature deployment sits with Manual. Newer deployment is concentrated in Electric.
Application:
Institutional procurement patterns diverge between liability-driven standardization and specialty retail curation.
- School:K-12 procurement through cooperative purchasing agreements dominates volume, with US Consumer Product Safety Commission blade exposure standards and small-part ingestion rules shaping vendor selection. California and Texas education service centers displace individual school-level purchasing authority through consolidated pre-qualification.
- Art:Specialty retailers in Berlin and Vienna dedicate linear footage to premium sharpening stations bundling replacement blade cartridges with cedar-cased pencil assortments. Adjustable cutting angles for graphite-based artwork conservation command institutional laboratory procurement.
- Office:Corporate facilities management prioritizes electric throughput where janitorial labor costs exceed equipment amortization schedules.
- Crafting:Hobbyist segments drive color customization and lightweight portability requirements favoring plastic housing formulations.
Procurement standardization is most advanced in School. Art exhibits the steepest expansion trajectory through specialty retail channel development.
Material:
Regulatory friction is segmenting supply between certified premium metal bodies and uncertified economy plastic units.
- Metal:Cold-rolled Swedish steel cutting cylinders in aluminum or zinc die-cast housings generate replacement-part revenue streams and field-serviceable architectures. France's repairability index legislation creates explicit preference for metal-bodied units with replaceable blade cartridges over sealed plastic alternatives.
- Plastic:Phthalate-free polymer formulations compete on color customization and unit weight for student segments, though ECHA registration dossiers for alternative plasticizers extend product launch cycles.
- Wood:Cedar and hardwood housings serve premium gift and heritage stationery positioning, particularly in German manufacturing clusters around Nuremberg.
- Composite:Bio-based polyamides and fiber-reinforced formulations emerge as REACH-compliant alternatives to legacy PVC housings.
Regulatory compliance investment concentrates in Metal. Cost-driven volume production remains anchored in Plastic.
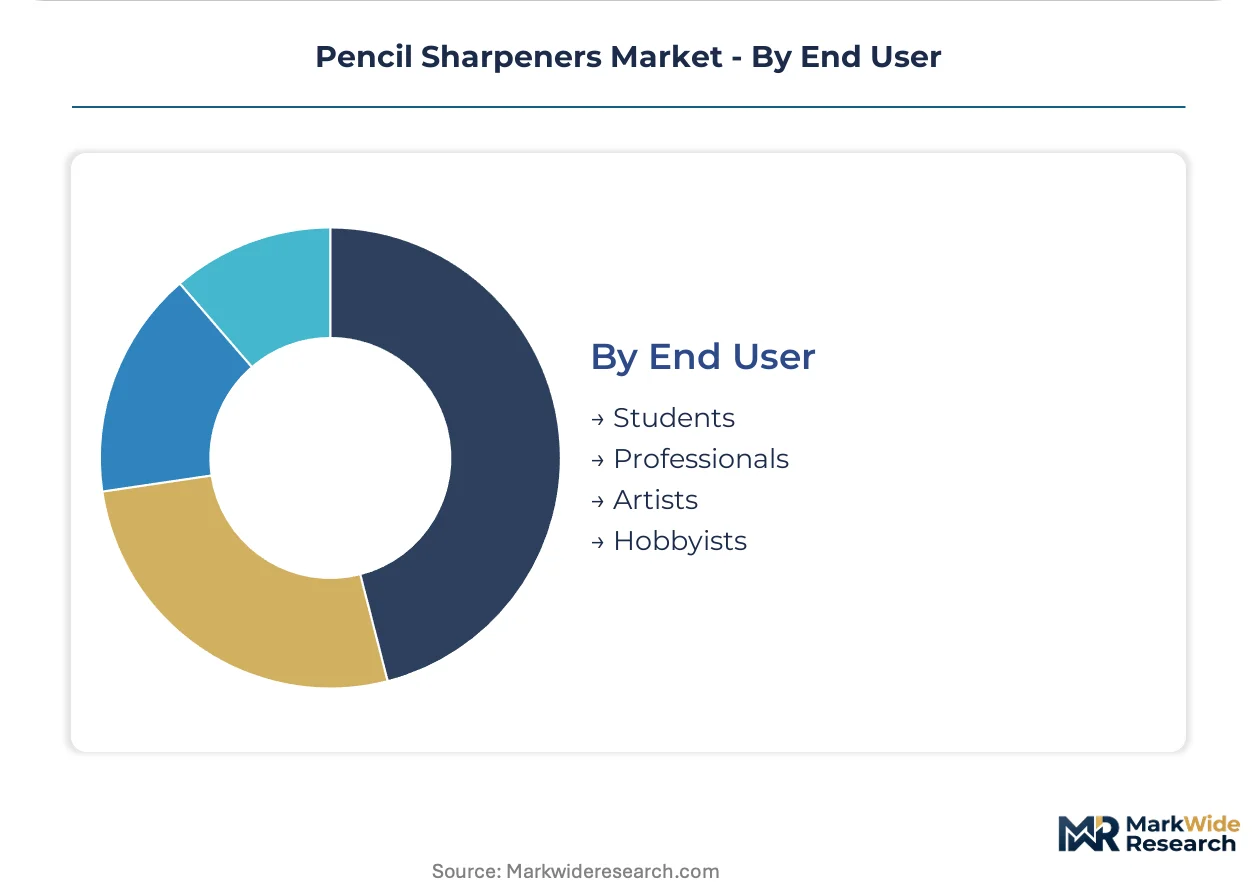
End User:
Skill level and use intensity determine willingness to absorb premium pricing for precision and durability.
- Students:Price-sensitive volume procurement through state-level textbook bundling in India and cooperative purchasing in North America prioritizes unit cost over blade longevity.
- Professionals:Drafting technicians and architects require 23-degree cutting angle consistency for technical drawing precision, with JIS-standard Rockwell hardness certification influencing vendor selection.
- Artists:Graphite-based artwork conservation labs demand archival-grade sharpening stations with adjustable angle settings for collection maintenance.
- Hobbyists:Crafting enthusiasts drive demand for portable, color-customizable units with minimal capital commitment.
Volume concentration aligns with Students. Margin expansion concentrates in Artists through conservation channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Nuremberg, Stein, and Hamburg anchor German precision manufacturing heritage, drawing institutional procurement toward CE-marked suppliers with documented REACH compliance histories.
Germany
Heritage stationery manufacturing clusters in Bavaria and Franconia concentrate helical steel cylinder production for professional draftsmen. ECHA registration requirements for phthalate-free plasticizers extend product launch cycles for reformulated housings. Nuremberg-based fabricators dominate industrial-grade manual sharpeners through in-house metallurgical capabilities.
United States
Regional education service centers in Texas and California consolidate K-12 procurement toward pre-qualified vendor lists with CPSC blade exposure documentation. FCC electromagnetic emissions standards fragment packaging workflows for battery-operated imports. Midwest school districts prioritize electric throughput where janitorial labor costs exceed equipment amortization.
Japan
METI-enforced JIS standards for blade hardness and dimensional consistency shape export eligibility for Asian contract manufacturers. Technical institutes in Tokyo and Osaka migrate toward 0.5mm lead advancement systems that eliminate sharpening demand. Nagoya-based suppliers maintain Rockwell testing laboratories for metallurgical certification.
India
State-level textbook procurement in Maharashtra and Karnataka bundles manual sharpeners with standardized examination kits for rural secondary schools. BIS quality certification requirements constrain informal sector participation in institutional channels. Tamil Nadu plastic molding clusters compete on unit cost for student-grade color-customized housings.
France
Repairability index legislation creates explicit preference for metal-bodied sharpeners with field-replaceable blade cartridges over sealed plastic alternatives. ANSM material safety oversight tightens specifications for classroom-deployed products. Parisian art supply retailers dedicate linear footage to premium sharpening stations bundling replacement cartridges.
Pencil Sharpeners Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct margin architectures. The vendor base stratifies between heritage German engineering houses, Asian contract manufacturers, and North American office supply distributors. Three archetypes dominate: vertically integrated stationery conglomerates with captive cedar-pencil ecosystems, precision-milling specialists with in-house metallurgical laboratories, and scale-driven distributors leveraging cooperative purchasing agreements. Capacity expansion in helical blade geometries and strategic partnerships for REACH-compliant polymer compounding represent the dominant competitive vectors.
Among German precision-engineering houses, Dahle GmbH & Co. KG and Staedtler Mars GmbH & Co. KG occupy positions anchored by multi-generational manufacturing heritage in Franconia. Faber-Castell AG exemplifies the vertically integrated archetype through upstream control over cedar-cased pencil production. Kum Limited and CARL Manufacturing Co., Ltd. represent Asian specialists navigating JIS certification requirements for blade hardness consistency. MAPED SAS and Newell Brands Inc. sit within the scale-driven distribution tier, leveraging pre-qualified vendor status with Texas and California education service centers.
| Leading Market Players |
|---|
| Dahle GmbH & Co. KG |
| Kum Limited |
| Staedtler Mars GmbH & Co. KG |
| CARL Manufacturing Co., Ltd. |
| MAPED SAS |
| Faber-Castell AG |
| Newell Brands Inc. |
| Bostitch Office |
| Acme United Corporation |
| Others |
Supply Flow & Price Mechanics
Regional education service centers in Texas and California anchor procurement concentration toward pre-qualified vendor lists with documented compliance histories, compressing price negotiation leverage for non-certified suppliers and institutionalizing contract-based long-term offtake agreements over spot purchasing.
Pricing Analysis
Short lead-time premiums attach to CE-marked helical steel cutting cylinders from German manufacturing clusters, while spot inventory discounts emerge for uncertified Asian plastic-housed units awaiting ECHA registration. Price differentiation stratifies across REACH-certified metal bodies, phthalate-free polymer mid-tier, and economy PVC alternatives. Cost compression in student-grade segments intensifies because Tamil Nadu molding clusters compete on unit weight and color customization. Procurement officers at Maharashtra state textbook bundling programs exhibit highest price sensitivity, whereas Parisian art supply retailers absorb premiums for archival-grade adjustable stations.
Supply Chain Analysis
Cold-rolled Swedish steel for precision-milled cutting cylinders rests on Scandinavian metallurgical suppliers, while aluminum extrusion and zinc die-cast housing feedstock concentrates in German and Chinese foundries. Bio-based polyamide formulations for REACH-compliant housings draw from specialized European polymer compounders. Single-source vulnerability sits with helical blade geometry equipment, where Nuremberg-based fabricators control precision-milling capital. Distribution runs through cooperative purchasing agreements at US regional education service centers, specialty art supply retailers in Berlin and Vienna, and state-level textbook procurement channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII phthalate restrictions have erected an 18-24 month product launch barrier that compliant German manufacturers exploit to deepen incumbent positioning against reformulation-lagged Asian competitors.
For Market Incumbents: To counter margin erosion from Tamil Nadu plastic molding clusters, deepen in-house polymer compounding capabilities for bio-based polyamide housings and secure captive supply of cold-rolled Swedish steel through long-term metallurgical mill agreements. Anchor channel control via pre-qualified vendor status with Texas and California education service centers. For New Entrants and Emerging Players: Launch via direct partnerships with Maharashtra and Karnataka state textbook procurement programs, targeting rural secondary school manual sharpener bundling where grid reliability concerns exclude electric alternatives. Exploit white space in museum conservation channel penetration for archival-grade adjustable stations. For Investors and Strategic Acquirers: The window for entry favors precision-milling specialists with in-house Rockwell testing laboratories and documented JIS certification histories. Monitor ECHA registration dossier approval velocity as the inflection signal for alternative plasticizer viability and competitive re-entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Polymer Compounding | ECHA-registered bio-based polyamide formulations unlock European student-grade shelf access against PVC-dependent competitors. |
| Helical Blade Capacity Expansion | Precision-milled 23-degree cutting angle equipment captures art supply retailer standardization in Berlin and Vienna. |
| Pre-Qualified Vendor Certification | Documented CPSC compliance histories secure cooperative purchasing agreement access at Texas and California education service centers. |
| Repairable Design Architecture | Field-replaceable blade cartridges align with France's repairability index legislation preference for metal-bodied units. |
| Conservation Channel Partnership | Adjustable-angle sharpening stations penetrate institutional laboratories servicing graphite-based artwork collections. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with stationery manufacturing executives, regional education procurement officers, art supply retail category managers, and metallurgical testing laboratory directors. ECHA registration dossiers, BIS quality certification records, JIS standard documentation, and US CPSC product safety reports provided compliance tracking foundations. Bottom-up volume modeling across manual, electric, battery-operated, and dual-action type segments triangulated against top-down value estimates from heritage manufacturer revenue disclosures.
Data-stream reconciliation balanced unit shipment projections with pricing stratification across metal, plastic, wood, and composite material tiers. Segmentation dimensions spanned type, application, material, and end-user skill level, with geographic regulatory cluster overlays for CE marking, REACH compliance, and JIS certification pathways. CAGRs were derived from trend extrapolation of procurement pattern shifts, substitution elasticity estimates for mechanical pencils, and channel concentration trajectories at cooperative purchasing agreements.
Steel price volatility, ECHA registration timeline delays, and migration rates toward 0.5mm lead advancement systems in Japanese technical institutes are the dominant revision risks to volume and value assumptions. Forecasts embed documented compliance cost absorption decisions and vendor consolidation patterns at institutional procurement levels. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Stationery Market
Office Supplies
Dictionary Pen Market
Office Supplies
Custom Binders Market
Office Supplies
GCC School Stationery Supplies Market
Office Supplies
Printer Ink Cartridge Market
Office Supplies
Cutter Staplers Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
Thumb Hole Book Page Holder Market
Office Supplies
Flash Cards and USB Flash Drives Market
Office Supplies
Stationery Products Market
Office Supplies
Business Card Holder Market
Office Supplies
Erasable Ink Pen Market
Office Supplies
Letter Opener Market
Office Supplies
Global Office Stationery Market
Office Supplies
Mechanical Pencil Leads Market
Office Supplies
Global Stationery and Supplies Market