
 Writing Instruments Market | 2026-2036
Writing Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Writing Instruments Market Analysis
Refill subscription programs and ink-replacement services is shifting how writing instruments generate recurring revenue beyond the initial sale. Pilot Corporation leverages its proprietary gel-ink technology to sustain premium positioning in professional segments. BIC anchors mass-market volume through controlled distribution across discount retail channels in North America and Europe. STAEDTLER specializes in artist-grade graphite and pigment formulations that differentiate its offerings from commodity competitors.
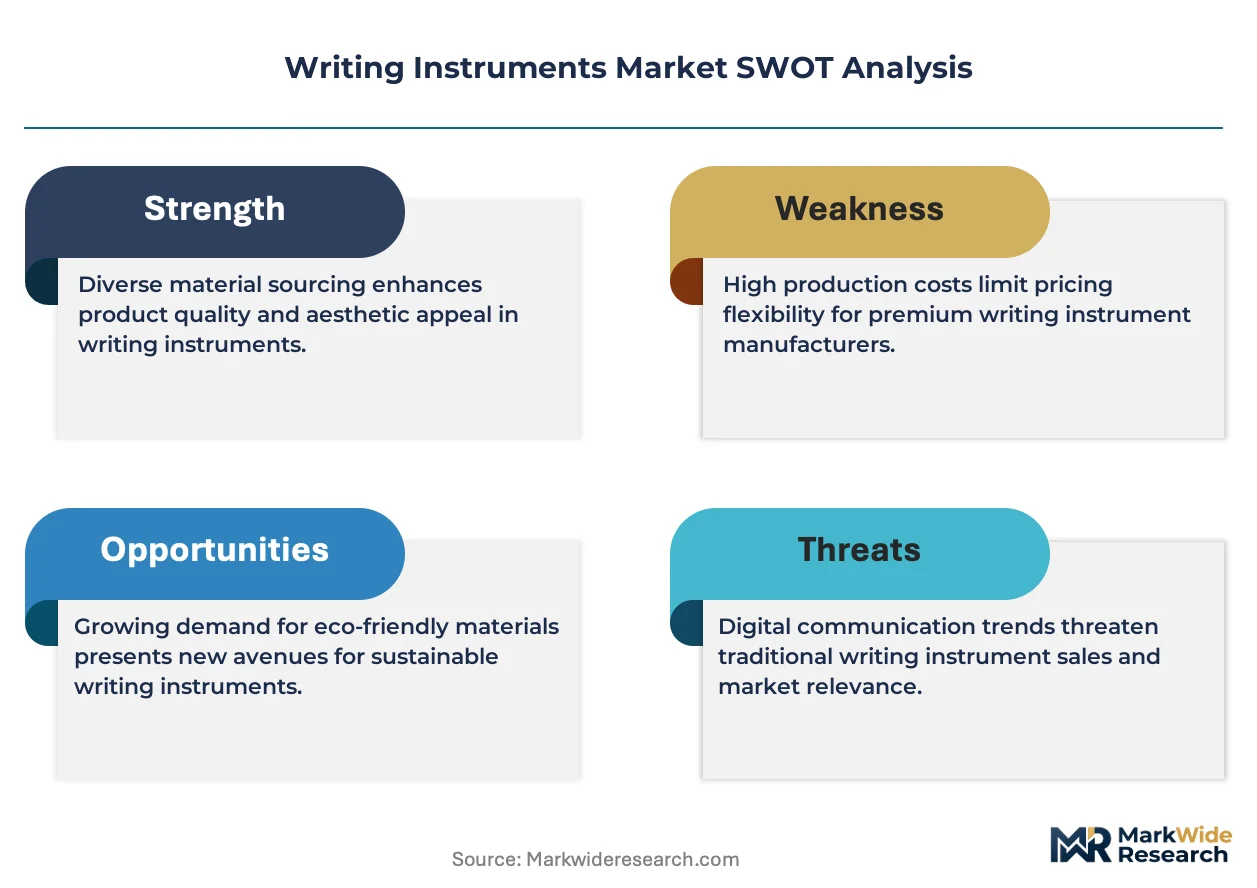
Writing instruments comprise handheld devices that deposit pigment-based or dye-based fluids onto substrates through ball-bearing, capillary, or nib-fed mechanisms, with tip specifications typically ranging from 0.5 mm to 1.6 mm and ink viscosity calibrated for specific paper grades. Ballpoint pens occupy the largest volume tier due to universal office and educational adoption, while fountain pens retain concentrated margin pools among enthusiast and luxury buyers. Biodegradable materials represent the fastest-growing material category as corporate procurement policies prioritize plastic reduction, though plastic still dominates unit economics at scale.
The EU REACH regulation and the US Consumer Product Safety Commission govern chemical composition limits in inks and coatings, directly constraining formulation choices for manufacturers accessing these markets. India's BIS certification mandates product safety testing for imported writing instruments, creating compliance thresholds that shape competitive entry. Japan's METI standards for stationery quality reinforce technical benchmarks that Mitsubishi Pencil and Pentel navigate in their domestic production. Stakeholders must monitor evolving extended producer responsibility frameworks in Europe and Asia-Pacific that could mandate collection and recycling infrastructure investment.
Market Dynamics
Biodegradable material substitution is compressing plastic-dependent supply chains as corporate procurement mandates in Germany, Japan, and the United States force formulation chemistry redesigns across gel-ink and ballpoint manufacturing.
Growth Catalysts
- EU REACH chemical compliance:Manufacturers reformulating solvent-free inks gain preferential access to European public-sector tenders and educational institution contracts.
- India's school enrollment expansion:Government-funded stationery programs in Uttar Pradesh and Maharashtra sustain bulk orders for affordable ballpoint pens.
- Refill mechanism innovation:Cartridge-standardized fountain pen systems reduce per-use cost for enthusiast collectors and corporate gift segments.
Market Restraints
- Petroleum-derived resin volatility:Polypropylene and ABS feedstock price swings compress margin predictability for barrel and cap injection molders.
- Zhejiang and Guangdong production concentration:Overreliance on China's eastern coastal manufacturing clusters exposes buyers to port congestion and labor availability shocks.
- Digital stylus substitution:Active pen adoption in tablet-based education and remote work environments erodes discretionary spending on traditional writing instruments.
Strategic Opportunities
- Indonesia's underserved archipelago:Fragmented retail distribution across 17,000 islands creates whitespace for direct-to-school subscription logistics.
- Extended producer responsibility mandates:France's AGEC law and forthcoming EU-wide collection targets reward early investment in closed-loop recycling infrastructure.
- 3D-printed grip customization:Ergonomic scanning and additive manufacturing convergence enables premium personalization for occupational therapy and left-handed user segments.
Industry Challenges
- Cross-border chemical notification:Divergent substance registry requirements between ECHA, EPA TSCA, and China's MEE extend product launch timelines by 8-14 months.
- Legacy mold asset stranding:Conventional plastic barrel tooling lacks retrofit compatibility with PLA and bio-based polymer feedstocks, forcing capital-intensive replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Writing Instruments Market |
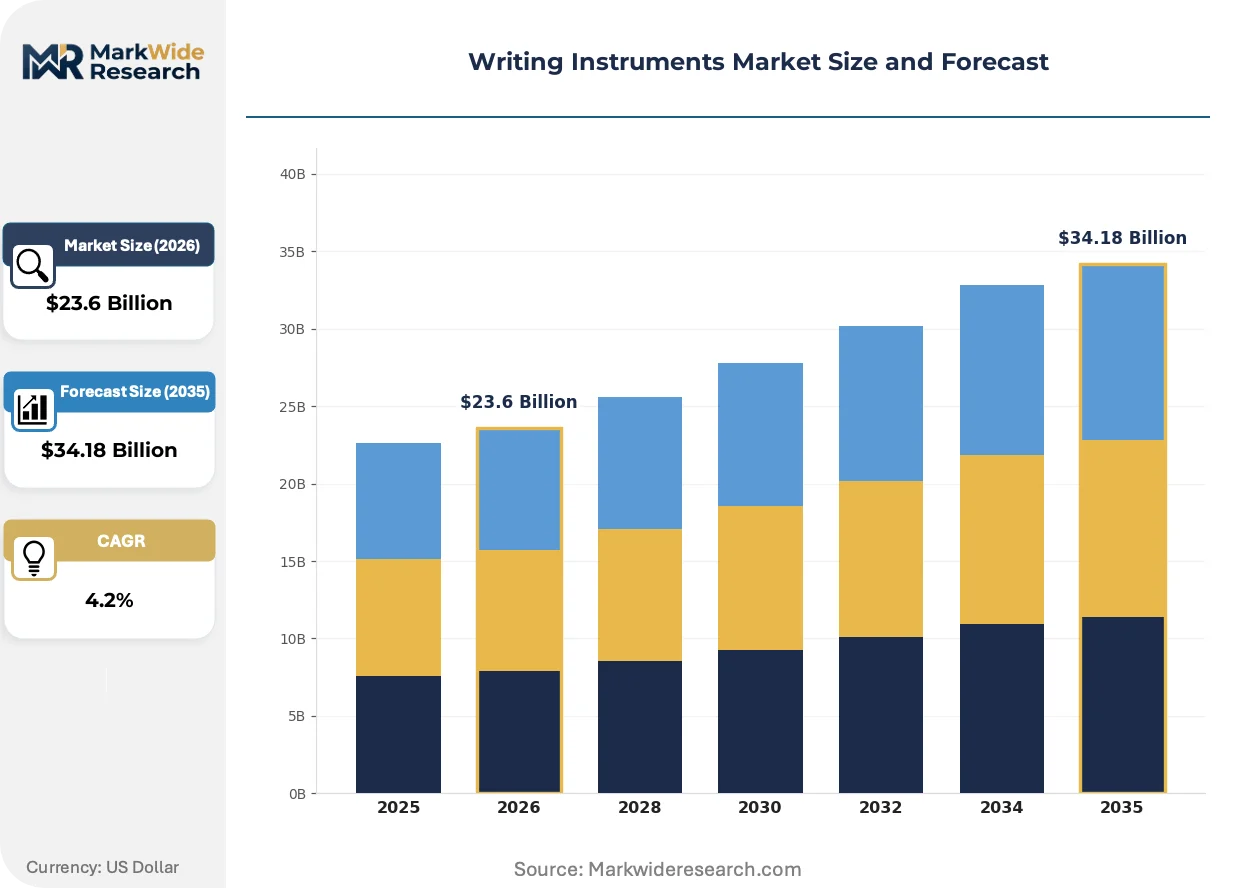
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $34.18 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballpoint Pens, Fountain Pens, Rollerball Pens, Markers Material: Plastic, Metal, Wood, Biodegradable End User: Students, Professionals, Artists, Businesses Usage: Office Use, Personal Use, Art & Design, Educational |
| Companies Covered | Faber-Castell, Hindustan Pencils Private Limited, Newell Brands, Inc., STAEDTLER, Pilot Corporation, BIC, Linc Pen and Plastics Private Limited, Pentel Co., Ltd., Mitsubishi Pencil Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Writing Instruments Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry constraints are simultaneously enabling premium positioning and threatening commodity volume economics across pen and pencil manufacturing.
Algae-derived ink bases are absorbing petroleum solvent displacement pressure from European formulators. Pilot batches from Dutch and German specialty chemical suppliers demonstrate viscosity stability matching conventional dye solutions. Corporate stationery buyers in the Netherlands and Scandinavia are absorbing price premiums of 12-18% for bio-ink certification, compressing demand for standard formulations in these markets.
REACH Annex XVII restrictions on phthalate plasticizers and heavy metal pigments are forcing reformulation of colored gel inks across all export-oriented manufacturers. The industrial consequence is a 24-month qualification cycle for new pigment-dispersant combinations. Artist-grade colored pencil and fineliner segments in Germany and France are most affected, with manufacturers accelerating partnerships with ECHA-registered pigment houses to maintain SKU breadth.
Subscription-based replenishment models are replacing institutional bulk purchasing in North American and Western European corporate segments. Channel disruption concentrates in Fortune 500 facility management procurement, where managed print services vendors are bundling writing instrument restocking with toner and paper contracts. This pattern is most visible in technology and financial services verticals with centralized procurement functions in Boston, London, and Singapore.
Writing Instruments Market Segmentation
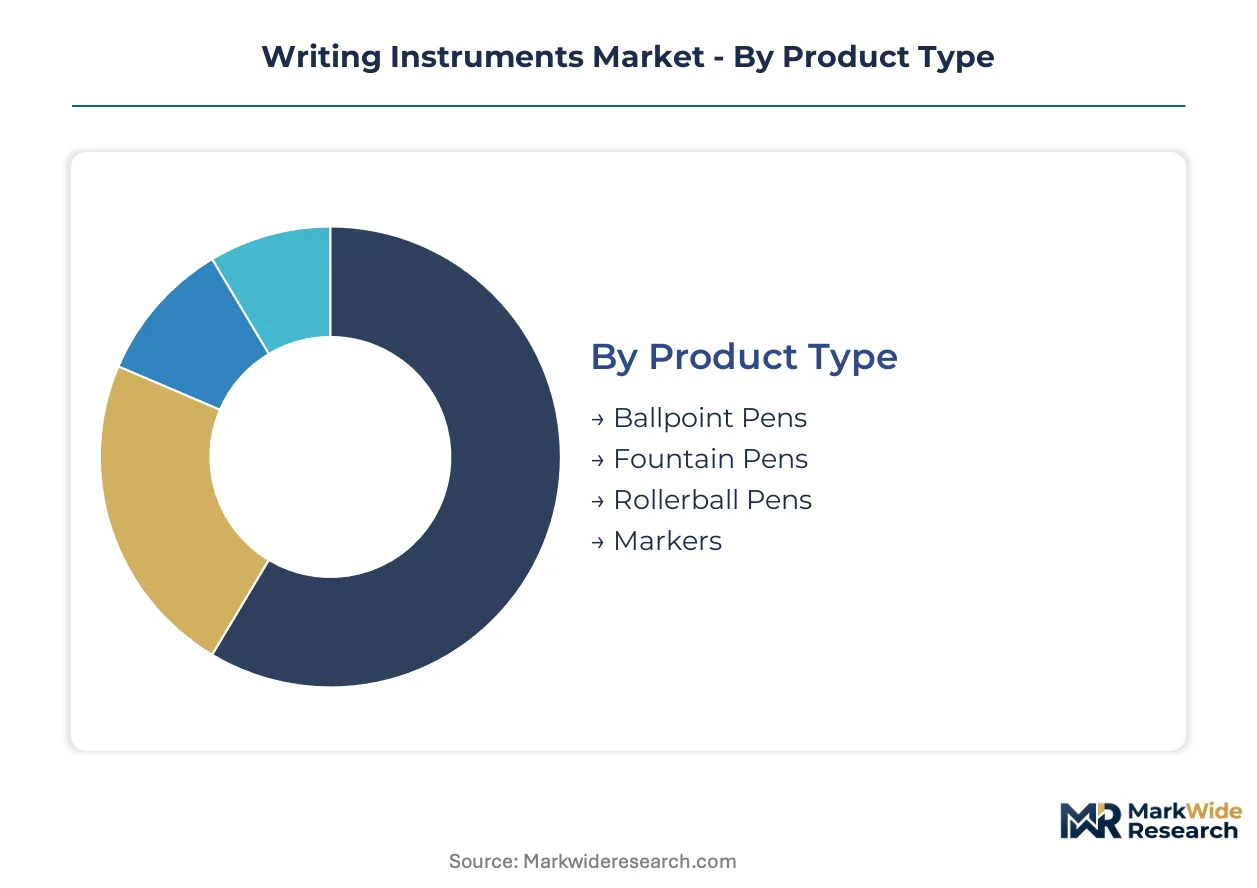
Writing instruments serve fundamentally different performance requirements across education, corporate procurement, and creative applications. Segmentation reveals how ink chemistry, barrel construction, and distribution channels align with distinct buyer willingness-to-pay thresholds and usage intensity patterns.
Product Type:
Price sensitivity and replacement frequency determine which mechanism buyers select for specific tasks.
- Ballpoint Pens:Oil-based ink formulations deliver reliable flow across varied paper grades without bleed-through. Schools in India and corporate bulk buyers in Germany prioritize this segment for cost predictability and minimal maintenance requirements.
- Fountain Pens:Nib-fed liquid ink systems require cartridge or converter refilling, creating recurring revenue attachments. Collector segments in Japan and executive gift markets absorb premium positioning through limited-edition resin bodies and 14k gold nibs.
- Rollerball Pens:Water-based liquid ink achieves finer line weights than ballpoint alternatives. Professional service firms specify these for client-facing documentation.
- Markers:Alcohol and solvent-based formulations serve permanent labeling and artistic applications. Industrial procurement in US manufacturing clusters sustains volume.
Ballpoint pens lead on scale; biodegradable material variants gain momentum fastest.
Material:
Corporate sustainability mandates and durability expectations split procurement decisions between cost efficiency and environmental positioning.
- Plastic:Polypropylene and ABS injection molding dominates unit economics at scale. Zhejiang manufacturing clusters supply barrels and caps for global mass-market distribution.
- Metal:Brass and aluminum construction signals durability in promotional and premium corporate gift segments. Laser engraving compatibility drives B2B customization demand.
- Wood:Maple and cedar bodies target artisan positioning with natural grain variation. Small-batch German and Japanese manufacturers command collector premiums.
- Biodegradable:PLA and algae-derived polymers absorb petroleum displacement pressure from EU procurement policies. Netherlands facility managers accept 15-20% price premiums for certified compostable certification.
Plastic retains volume leadership; biodegradable materials expand most quickly.
End User:
Usage intensity and brand sensitivity vary dramatically across institutional versus individual purchase contexts.
- Students:High replacement rates and loss tolerance favor disposable pricing. India's government-funded stationery programs in Uttar Pradesh and Maharashtra sustain bulk orders.
- Professionals:Reliability and status signaling drive selection for client-facing and signature applications. Law and financial services verticals concentrate demand in London, New York, and Singapore.
- Artists:Pigment lightfastness and nib responsiveness determine technical suitability. Germany's artist-grade colored pencil and fineliner segments face REACH-driven reformulation cycles.
- Businesses:Centralized procurement bundles writing instruments with facility management contracts. Fortune 500 technology firms in Boston and Seattle pilot subscription replenishment models.
Students generate highest unit volume; businesses show steepest expansion trajectory.
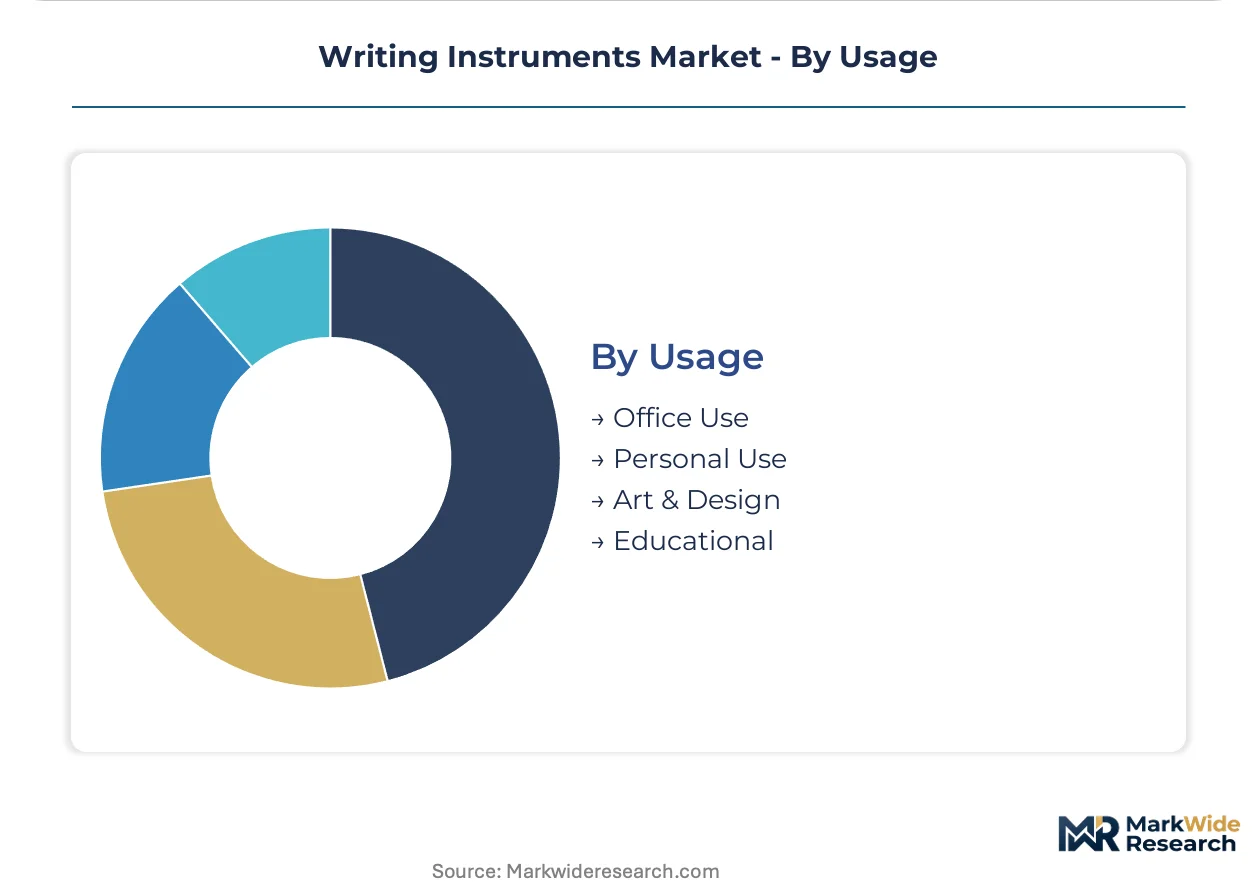
Usage:
Application context dictates performance specifications and replacement cadence.
- Office Use:Standardized black and blue ink colors dominate for document compliance. Corporate procurement mandates in Germany and Japan prioritize solvent-free formulations.
- Personal Use:Aesthetic customization and writing experience quality drive discretionary selection. Collector communities in Japan sustain limited-edition release cycles.
- Art & Design:Pigment concentration and blendability determine professional acceptance. ECHA-registered pigment partnerships protect SKU breadth in German and French markets.
- Educational:Safety certification and affordability constraints shape institutional purchasing. India's BIS certification requirements filter import competition.
Educational usage leads on scale; art and design commands premium margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate to jurisdictions with lower compliance costs for ink formulation and barrel materials. Cost-of-compliance gaps between REACH-regulated Europe and emerging Asian production hubs are accelerating facility migration and partnership restructuring.
China
Zhejiang and Guangdong provinces host concentrated injection molding and ink formulation capacity serving both domestic consumption and export markets. The Ministry of Ecology and Environment (MEE) substance registry requirements extend product launch timelines for foreign brands accessing Chinese distribution. Ningbo manufacturing clusters specialize in polypropylene barrel production at scale-driven unit economics.
Germany
Corporate procurement mandates in Bavaria and North Rhine-Westphalia prioritize solvent-free ink certifications and biodegradable material compliance. The Federal Motor Transport Authority (KBA) does not regulate writing instruments, but ECHA REACH Annex XVII restrictions on phthalate plasticizers force reformulation of colored gel inks. Frankfurt and Hamburg distribution hubs manage European public-sector tender fulfillment.
India
Uttar Pradesh and Maharashtra government-funded stationery programs sustain bulk orders for affordable ballpoint pens serving school enrollment expansion. Bureau of Indian Standards (BIS) certification mandates product safety testing for imported writing instruments, filtering competitive entry from unqualified suppliers. Mumbai and Delhi-NCR serve as import clearance and redistribution nodes for domestic brands.
Japan
Tokyo and Osaka metropolitan areas concentrate collector demand for limited-edition fountain pen releases and premium graphite formulations. Ministry of Economy, Trade and Industry (METI) quality standards reinforce technical benchmarks that domestic manufacturers navigate in their home market. Nagoya industrial corridors maintain precision nib machining and resin body production capabilities.
United States
Fortune 500 facility management procurement in Boston and Seattle pilots subscription-based writing instrument replenishment bundled with office supply contracts. EPA TSCA chemical notification requirements diverge from ECHA standards, extending multi-market product launch coordination. Midwest distribution networks serve mass-market retail channels with volume-driven plastic pen imports.
Writing Instruments Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium positioning concentrated among Japanese and German heritage brands while volume production clusters in Chinese OEM facilities. The vendor base organizes into three tiers: integrated chemical-to-retail operators, component-specialized fabricators, and private-label assemblers. Dominant competitive moves include backward integration into captive ink formulation capacity and geographic licensing partnerships to bypass tariff exposure.
Within the heritage-brand tier, Pilot Corporation and STAEDTLER exemplify premium positioning through proprietary technology differentiation, while BIC anchors mass-market scale through controlled discount retail distribution. Among Asian specialists, Mitsubishi Pencil Co., Ltd. and Pentel Co., Ltd. occupy positions defined by domestic market quality benchmarks and export-oriented technical specifications. Faber-Castell represents European artisan-grade positioning through natural material integration and limited-production craft positioning.
| Leading Market Players |
|---|
| Faber-Castell |
| Hindustan Pencils Private Limited |
| Newell Brands, Inc. |
| STAEDTLER |
| Pilot Corporation |
| BIC |
| Linc Pen and Plastics Private Limited |
| Pentel Co., Ltd. |
| Mitsubishi Pencil Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists across Japan and Germany anchor premium pricing discipline through controlled distribution networks, while Zhejiang-based contract manufacturers compete on volume economics that compress margins for unbranded exporters serving European educational procurement.
Pricing Analysis
Capacity additions in China's eastern coastal provinces are reshaping price floors for commodity ballpoint pens, forcing margin compression on undifferentiated exporters. Three-tier pricing structure across premium, standard, and economy levels separates collector-grade fountain pens from corporate gift tiers and disposable school supplies. Price differentiation rests on REACH compliance certification and gel-ink viscosity stability. Cost compression in the standard tier is intensifying because petroleum-derived resin feedstock volatility erodes contract predictability. Students in India's government-funded programs exhibit highest price sensitivity; Japanese collector segments absorb 40-60% premiums for limited-edition releases.
Supply Chain Analysis
Dual-sourcing requirements from European public-sector tender rules now mandate ink formulation qualification across at least two independent pigment houses, extending supplier onboarding timelines. Geographic supply concentrates in China, Germany, and Japan, with Zhejiang injection molders feeding mass-market demand and Nagoya precision machinists serving nib fabrication. Raw material dependencies draw from polypropylene resin, dye-based ink solvents, and 14k gold nib blanks. Single-source vulnerability concentrates in algae-derived bio-ink bases, where Dutch and German specialty chemical suppliers dominate pilot-scale output. Distribution runs through Frankfurt and Hamburg hubs for European institutional fulfillment, with Mumbai and Delhi-NCR managing Indian import clearance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Writing instrument manufacturing functions as a geographic-arbitrage play where REACH compliance costs in Europe run 15-25% above Zhejiang production economics, creating margin expansion for early bio-material investors.
For Market Incumbents: Lock in backward integration into captive ink formulation capacity before ECHA pigment registry requirements harden supplier exclusivity. Defend channel control through direct-to-school subscription logistics in Indonesia's fragmented archipelago, where port congestion and labor availability shocks threaten unintegrated competitors. Prioritize PLA and algae-derived polymer R&D to offset petroleum resin volatility. For New Entrants and Emerging Players: Launch via direct-to-school subscription models in Indonesia's 17,000-island market, where centralized procurement has not yet consolidated. Target India's BIS-certified import gap with affordable ballpoint lines for Uttar Pradesh and Maharashtra government programs. Exploit 3D-printed grip customization whitespace for left-handed and occupational therapy segments in North American corporate procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among Chinese OEM assemblers lacking REACH-compliant ink chemistry, creating distressed entry points before EU extended producer responsibility mandates reshape asset values. Five-to-ten-year viability hinges on bio-material patent portfolios and closed-loop recycling infrastructure ownership. Watch for France's AGEC law enforcement intensity as the signal indicating regulatory arbitrage window closure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Ink Formulation | ECHA-registered pigment partnerships protect SKU breadth against REACH Annex XVII restrictions. |
| Direct-to-School Subscription Logistics | Indonesia's archipelago fragmentation creates whitespace beyond conventional retail distribution reach. |
| Bio-Material Patent Portfolio Buildout | Algae-derived ink bases absorb petroleum displacement pressure from Netherlands and Scandinavian procurement. |
| Closed-Loop Recycling Infrastructure Investment | France's AGEC law rewards early movers with preferential public-sector tender access. |
| 3D-Printed Grip Customization Capability | Ergonomic scanning convergence enables premium positioning for occupational therapy segments. |
Methodological Framework
Bottom-up educational and corporate procurement modeling reconciled against top-down ink formulation and barrel production tracking forms the analytical core of this study. Primary interviews with plant managers at Zhejiang injection molding clusters, procurement leads at German facility management firms, distribution channel partners in Mumbai and Delhi-NCR, and technical R&D directors at Japanese precision nib manufacturers combined with secondary validation. Secondary sources include customs and trade data from India's DGFT, ECHA substance registry filings, SEC 10-K disclosures from listed stationery manufacturers, and BIS certification databases. Triangulation between demand-side institutional purchasing patterns and supply-side capacity utilization rates ensures coherence.
Input-output matrices map barrel resin consumption, nib machining hours, and ink formulation batch yields against end-use segment demand across the projection horizon. Segmentation dimensions modeled include product mechanism type, material composition tier, end-user archetype, and regional regulatory cluster. CAGRs derive from slope-intercept fitting of historical production volumes against enrollment and employment growth proxies. Industry-specific forecast inputs incorporate REACH reformulation cycle durations and BIS certification backlog estimates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden phthalate plasticizer bans or port congestion shocks in China's eastern coastal manufacturing clusters. Deviation in algae-derived ink base scale-up timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Office Supplies Market
Office Supplies
Diaries & Planners Market
Office Supplies
Copiers Market
Office Supplies
Pencil Sharpeners Market
Office Supplies
Stationery Products Market
Office Supplies
School Stationery Supplies Market
Office Supplies
Greetings Cards Market
Office Supplies
Flash Cards and USB Flash Drives Market
Office Supplies
Printer Ink Cartridge Market
Office Supplies
Latin America School Stationery Supplies Market
Office Supplies
Cutter Staplers Market
Office Supplies
Stationery Market
Office Supplies
Acrylic Marker Pen Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
Business Card Holder Market
Office Supplies
Marker Pens Market