
 Diaries & Planners Market | 2026-2036
Diaries & Planners Market Size, Share, and Industry Trends Forecast 2026-2036
Diaries & Planners Market Insights
Corporate procurement of branded diaries and planners is hardening around wellness-focused employers seeking structured employee engagement tools. Moleskine anchors its position through direct-to-enterprise channels that bypass traditional retail intermediaries. Papier differentiates via customizable layouts that serve boutique agency and startup buyer segments. Clever Fox competes on functional density, packing habit trackers and goal frameworks into compact formats that resonate with productivity-system subscribers.
Diaries and planners comprise bound or spiral-assembled leaves of ruled, dotted, or blank paper stock, typically between 80 and 120 gsm, designed for handwritten scheduling, task logging, and reflective journaling across personal and professional contexts. Daily planners and bullet journals command the fastest-growing structural positions, with bullet journals attracting maker-culture consumers who reject rigid pre-formatting while daily planners retain institutional procurement contracts. Leather and recycled materials split the material margin pool, with recycled stocks gaining shelf space under retailer sustainability mandates and leather sustaining price premiums in gift and luxury channels.
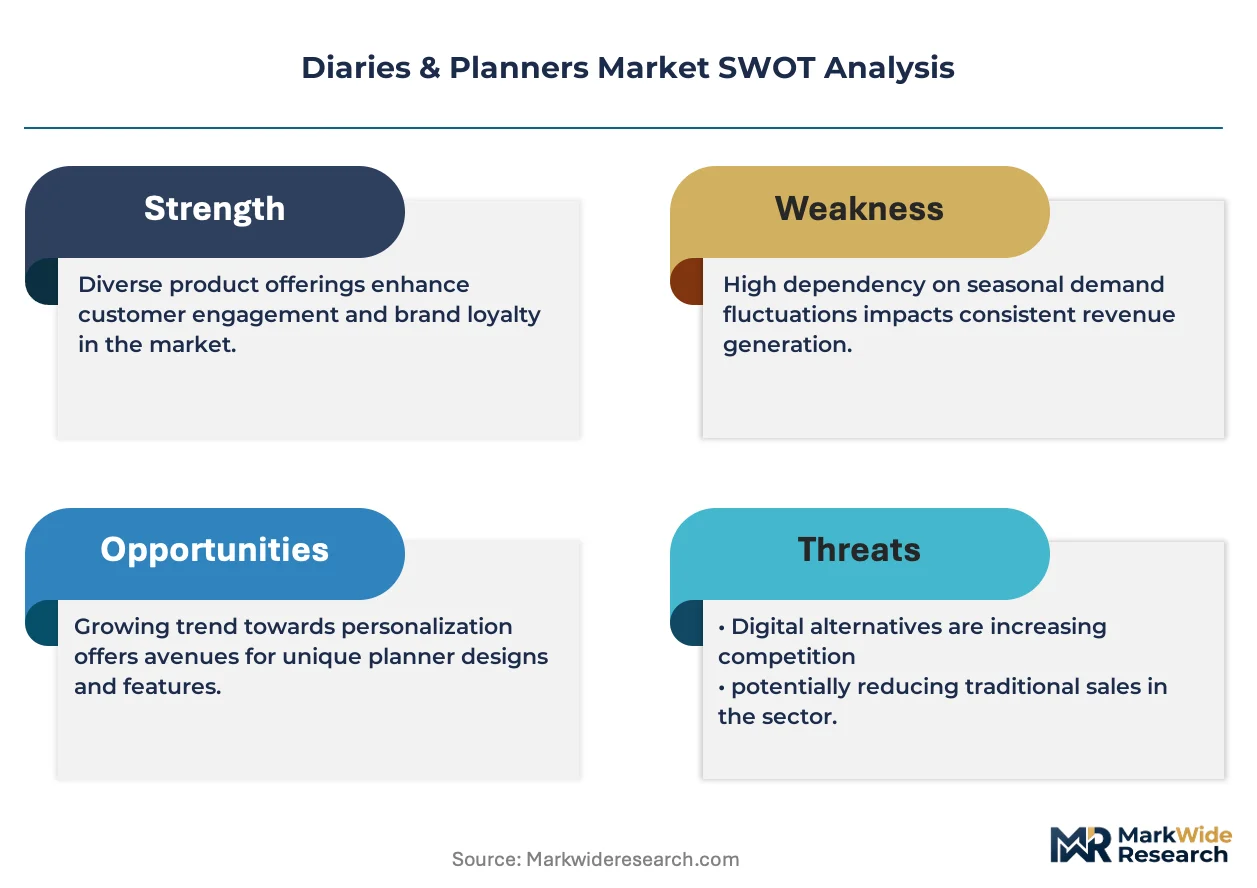
FDA oversight of inks and adhesives in consumer goods, EPA guidelines on paper bleaching and wastewater discharge, and EU REACH restrictions on chemical treatments in leather tanning collectively elevate compliance costs for cross-border suppliers. The EU Green Deal's packaging rules and extended producer responsibility frameworks now require traceable fiber sourcing for products sold in member states. Stakeholders must monitor whether digital-native competitors with app-integrated notebooks can convert subscription users back to physical formats before brand loyalty calcifies around hybrid workflows.
Market Dynamics
The EU Green Deal's extended producer responsibility mandates are forcing paper mills and binding manufacturers to reengineer supply chains around traceable fiber sourcing and biodegradable adhesives, compressing margins for non-compliant suppliers while advantaging certified producers.
Growth Catalysts
- Corporate wellness mandates:Employers in Germany and France now embed structured planning tools into productivity frameworks, creating institutional procurement pipelines for premium formats.
- REACH chemical restrictions:EU regulations on leather tanning processes accelerate migration toward plant-based binding materials and recycled paper stocks.
- Bullet journal maker culture:Artisan communities on social platforms drive demand for unformatted dot-grid notebooks that reject rigid pre-printed layouts.
Market Restraints
- Pulp price volatility:Nordic softwood fiber costs fluctuate with energy market shocks, squeezing margin predictability for 80-120 gsm stock producers.
- Digital calendar substitution:Enterprise SaaS scheduling platforms capture task-management workflows that physical planners once owned.
- Single-supplier leather concentration:Italian tannery clusters dominate premium cover sourcing, creating geographic vulnerability to regulatory disruption.
Strategic Opportunities
- Biodegradable binding chemistry:Adhesive innovators developing starch-based spine compounds can capture shelf space under retailer sustainability mandates.
- Direct-to-enterprise channels:Bypassing wholesale distributors allows margin capture from corporate gift programs and onboarding kit procurement.
- Underpenetrated Nordic markets:Sweden and Denmark show lagging per-capita consumption relative to Germany, suggesting white space for localized format launches.
Industry Challenges
- Cross-border compliance fragmentation:FDA ink oversight, EPA bleaching guidelines, and EU REACH restrictions create divergent certification timelines for multi-territory suppliers.
- Hybrid workflow integration:Physical format producers struggle to embed QR-linked digital companion tools that match app-native competitor functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diaries & Planners Market |
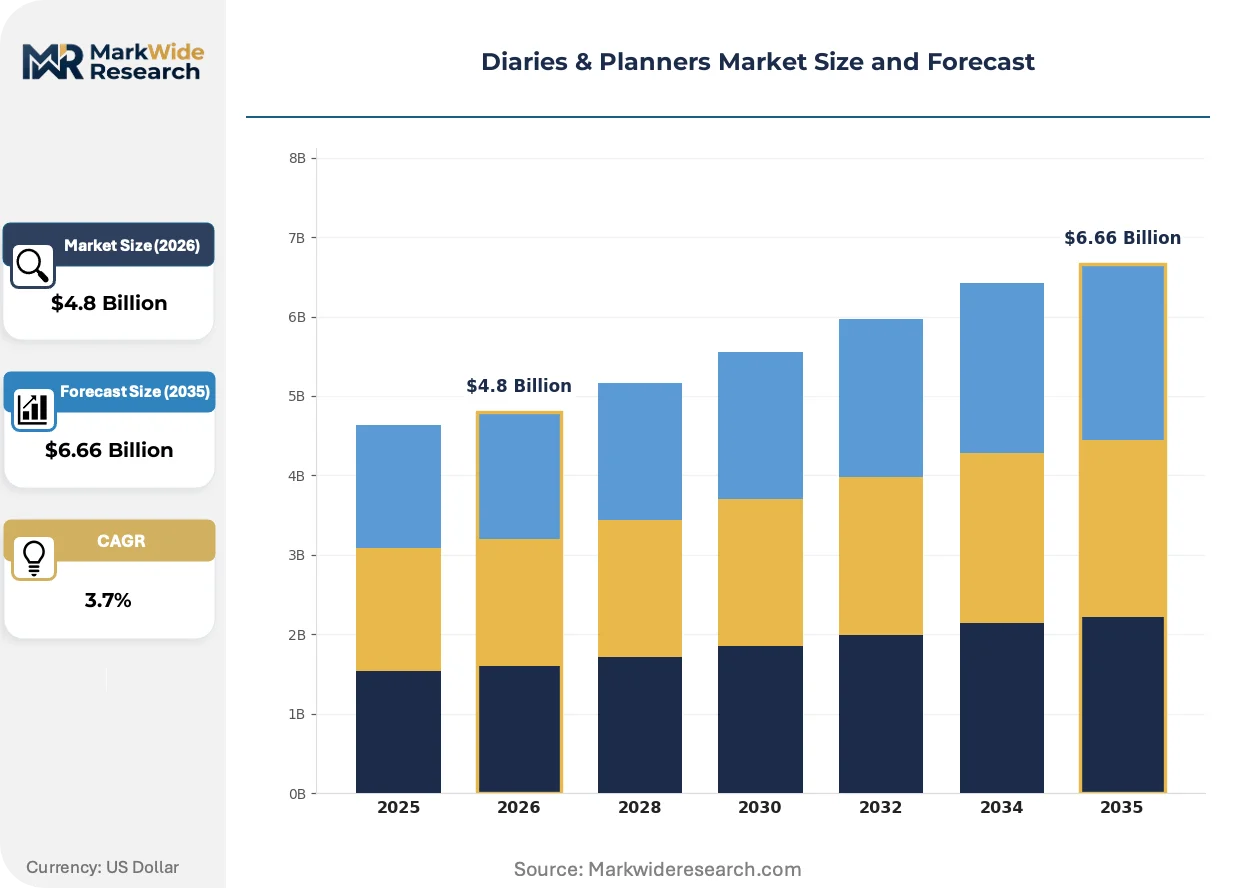
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Daily Planners, Academic Planners, Bullet Journals, Travel Diaries Material: Paper, Leather, Recycled Materials, Plastic Covers Size: A5, A4, Pocket Size, Custom Size Feature: Customizable Layout, Eco-Friendly, Spiral Bound, Digital Integration |
| Companies Covered | Aspinal of London, Pineider, Moleskine, MiGoals, Appointed, Papier, Cartier, Passion Planner, Clever Fox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diaries & Planners Market Trends and Innovations
Product development trajectories in diaries and planners center on material substitution, regulatory compliance engineering, and channel restructuring that bypasses traditional retail intermediaries.
Stone paper derived from calcium carbonate is rewriting durability expectations for outdoor and travel-oriented formats. Adventure tourism operators and field research organizations are adopting these waterproof, tear-resistant notebooks at triple the rate of conventional stock. The technology is compressing demand for laminated page protectors and specialized weatherproof covers.
EU Green Deal packaging waste directives are mandating recycled content minimums and end-of-life recyclability labeling for consumer goods sold in member states. Paper mills in Portugal and Spain are retooling pulping lines to handle post-consumer fiber streams. Gift and luxury channels face the steepest reformulation costs due to foil stamping and ribbon marker incompatibilities with standard recycling streams.
Buyer concentration among boutique agencies and startup clusters is disintermediating traditional stationery wholesalers. Direct fulfillment from binderies to corporate procurement offices now captures a growing share of B2B volume. This pattern is most visible in Berlin and Amsterdam, where employer branding teams source customized onboarding kits outside conventional retail channels.
Diaries & Planners Market Segmentation
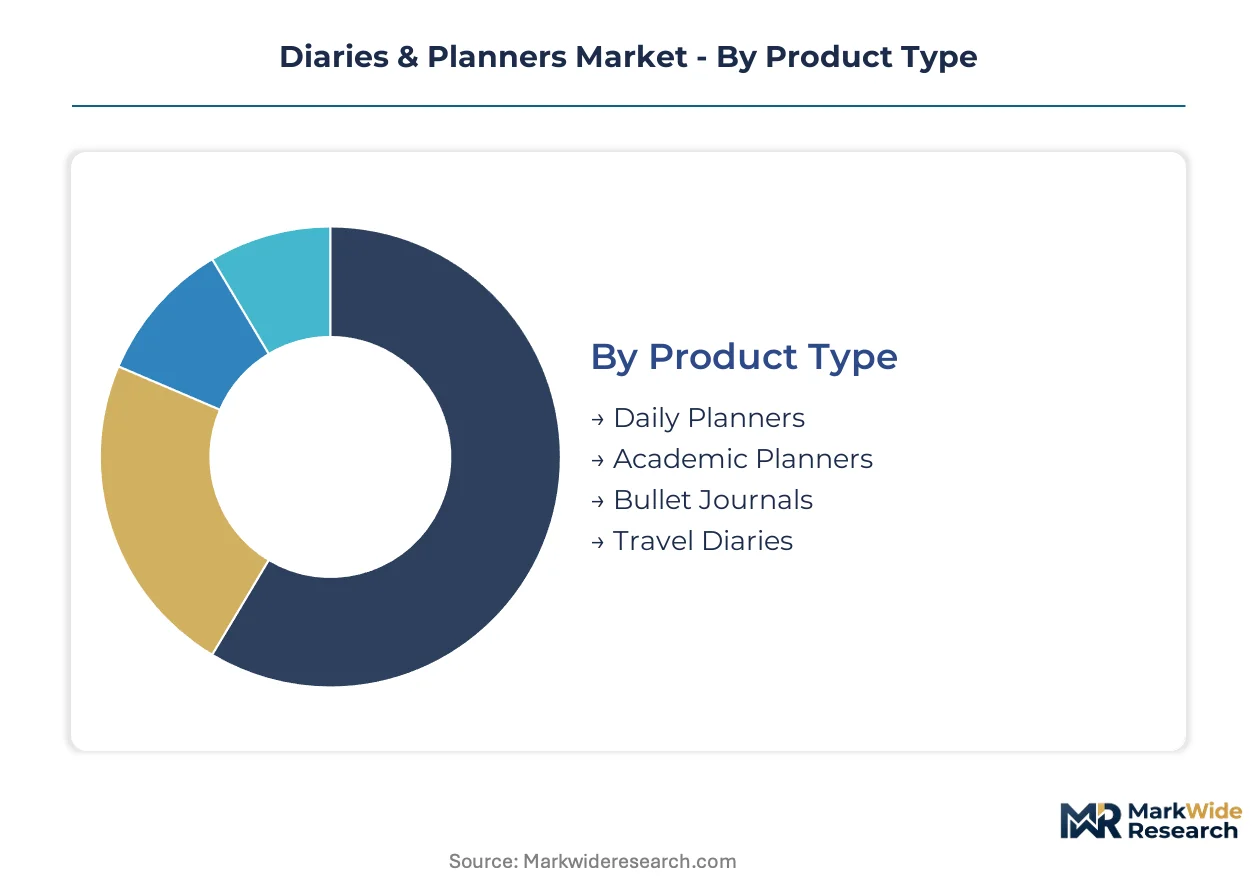
Product configuration in diaries and planners determines procurement channel access and margin structure. Format specifications shape whether buyers source through retail, direct-to-enterprise, or specialty stationery channels.
Product Type:
Standalone formats dominate personal use while embedded systems serve institutional procurement pipelines with standardized layouts.
- Daily Planners:Pre-structured 365-page layouts with hourly slots and priority matrices. Corporate wellness programs in Germany and France embed these into employee productivity frameworks, creating recurring institutional procurement contracts.
- Bullet Journals:Unformatted dot-grid notebooks that reject rigid pre-printed layouts. Maker-culture communities on social platforms drive demand, with artisan consumers customizing indexing systems and habit trackers.
- Academic Planners:Semester-aligned scheduling grids targeting educational institutions.
- Travel Diaries:Compact formats with map inserts and itinerary sections for tourism operators.
Volume placements concentrate in Daily Planners; the faster expansion belongs to Bullet Journals.
Material:
Cost tier stratification separates premium gift channels from mass-market retail, with sustainability mandates reshaping mid-tier sourcing.
- Paper:80-120 gsm ruled, dotted, or blank stock bound with spiral or adhesive spines. Nordic softwood fiber costs fluctuate with energy market shocks, squeezing margin predictability for stock producers.
- Recycled Materials:Post-consumer fiber streams and biodegradable bindings. EU Green Deal packaging waste directives mandate minimum recycled content, advantaging certified Portuguese and Spanish paper mills.
- Leather:Italian tannery clusters dominate premium cover sourcing, creating geographic vulnerability to REACH chemical restrictions on tanning processes.
- Plastic Covers:Polypropylene and PVC variants for durability-focused outdoor use.
Revenue concentrates in Paper formats; Recycled Materials are climbing the fastest as retailer sustainability mandates harden.
Size:
Application context drives format selection, with portability requirements separating mobile professionals from desk-based users.
- A5:Mid-format dimensions balancing portability with writing surface. Boutique agencies and startup clusters in Berlin and Amsterdam source customized A5 formats for employer branding and onboarding kits.
- Pocket Size:Compact dimensions for field use and travel. Adventure tourism operators adopt these at elevated rates for guest documentation and itinerary logging.
- A4:Full-page formats for detailed project planning and meeting notes.
- Custom Size:Bespoke dimensions for corporate gift programs and specialty retail.
Procurement volume clusters in A5; Pocket Size formats are gaining share fastest among mobile workforce segments.
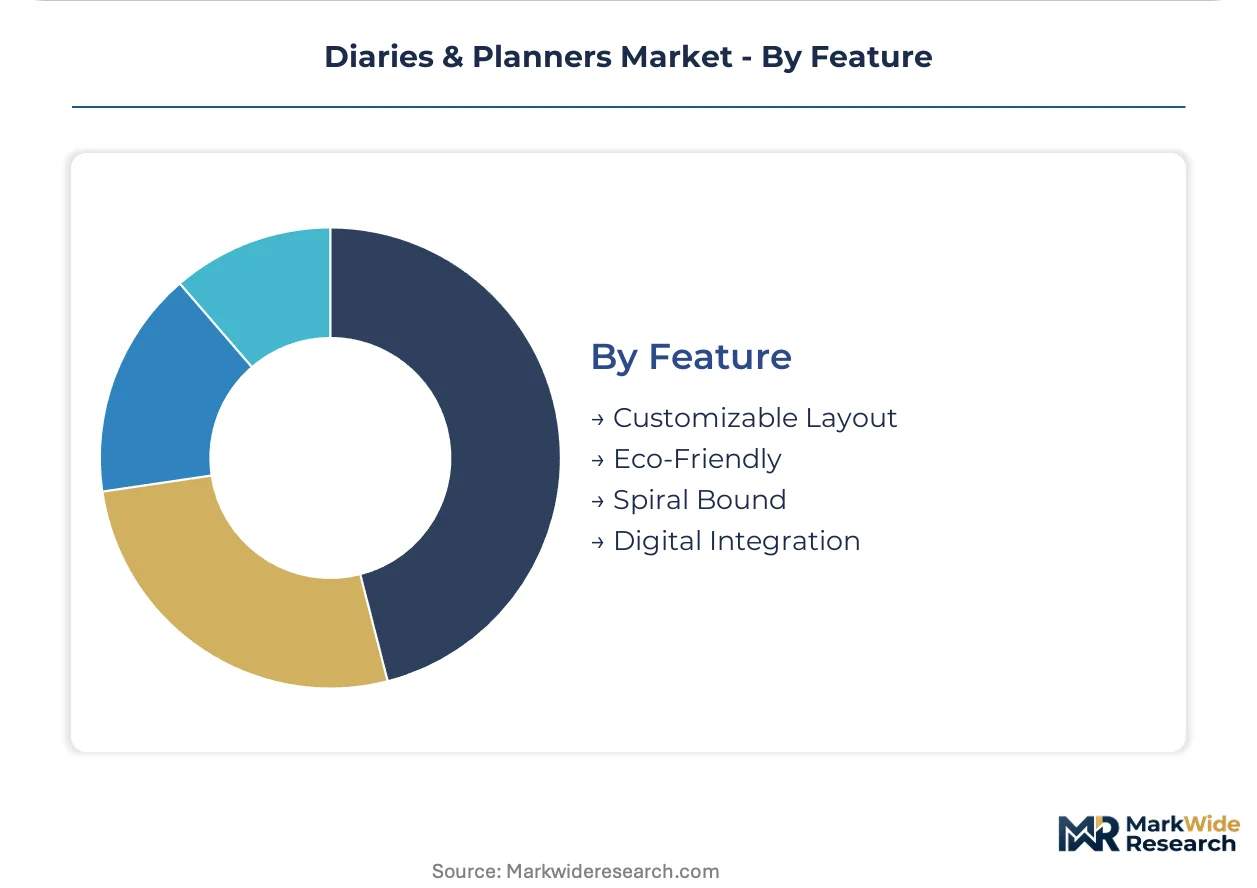
Feature:
Customer type determines feature prioritization, with enterprise buyers demanding standardization while individual consumers seek personalization.
- Customizable Layout:Modular page designs allowing user-defined sections. Papier and comparable specialists serve boutique agency buyers with configurable templates that bypass traditional retail intermediaries.
- Digital Integration:QR-linked companion tools and app synchronization. Physical format producers struggle to match app-native competitor functionality, creating vulnerability to hybrid workflow migration.
- Eco-Friendly:FSC certification, soy-based inks, and plastic-free packaging for sustainability-mandated procurement.
- Spiral Bound:Wire-o and coil bindings allowing flat-lying pages for left-handed users and desktop reference.
Feature development investment concentrates in Customizable Layout; Digital Integration represents the steepest expansion trajectory as producers race to capture hybrid workflow users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic softwood fiber from Swedish and Finnish forests anchors paper stock supply for premium formats, while Italian tannery clusters dominate leather cover sourcing. Demand concentrates in Western European corporate procurement hubs and North American direct-to-consumer channels.
Germany
Corporate wellness programs in Berlin and Munich embed structured planners into employee productivity frameworks, creating institutional procurement pipelines. EU Green Deal packaging waste directives mandate traceable fiber sourcing for products sold nationwide. The Rhine-Ruhr industrial corridor hosts paper mills retooling pulping lines to handle post-consumer fiber streams.
United States
Boutique agencies and startup clusters in Austin and Brooklyn drive demand for customizable layouts that bypass traditional retail intermediaries. FDA oversight of inks and adhesives elevates compliance costs for cross-border suppliers. Direct fulfillment from binderies to corporate procurement offices in Chicago and Los Angeles captures growing B2B volume.
France
Employer branding teams in Paris source customized onboarding kits featuring premium stationery formats. REACH chemical restrictions on leather tanning processes accelerate migration toward plant-based binding materials. The Auvergne-Rhône-Alpes region concentrates specialty paper finishing operations serving luxury gift channels.
United Kingdom
Maker-culture communities in London and Manchester drive demand for unformatted dot-grid notebooks that reject rigid pre-printed layouts. Extended producer responsibility frameworks require end-of-life recyclability labeling for consumer goods. Birmingham-based distributors are restructuring supply chains around certified recycled content minimums.
Italy
Gift and luxury channels in Milan and Florence sustain price premiums for leather-bound formats despite reformulation costs from foil stamping incompatibilities. EU REACH restrictions on chemical treatments in tanning compress margins for non-compliant suppliers. Tuscan tannery clusters face geographic vulnerability to regulatory disruption as REACH enforcement tightens.
Diaries & Planners Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-enterprise channels and material innovation arcs. The vendor base stratifies across three tiers: heritage luxury houses, mid-market format specialists, and digital-native customizable platforms. Two dominant competitive moves define current positioning: bypassing wholesale distributors to capture corporate gift program margins, and reengineering supply chains around biodegradable adhesives and traceable fiber sourcing.
Within the heritage luxury tier, Aspinal of London and Pineider exemplify European craftsmanship positioning anchored in leather-bound formats. Moleskine occupies a position representing the bridge between cult stationery status and scaled enterprise penetration. Papier exemplifies the digital-native customizable platform archetype, serving boutique agency buyers with configurable templates.
| Leading Market Players |
|---|
| Aspinal of London |
| Pineider |
| Moleskine |
| MiGoals |
| Appointed |
| Papier |
| Cartier |
| Passion Planner |
| Clever Fox |
| Others |
Pricing and Supply Chain Analysis
Nordic softwood fiber costs fluctuate with energy market shocks, compressing margin predictability for 80-120 gsm stock producers and forcing tiered pricing separation between certified sustainable grades and conventional paper stocks. Italian tannery clusters sustain leather cover premiums despite REACH compliance costs, while Portuguese mills capture mid-market share through post-consumer fiber certifications.
Pricing Analysis
Service bundling separates premium leather-bound formats with customization support from unbundled economy spiral-bound variants lacking after-sales layout consultation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade stratification, with FSC and EU Ecolabel tiers commanding measurable premiums over uncertified stock. Pricing pressure stems from pulp price volatility in Nordic markets, squeezing margin predictability for mid-tier producers. Corporate procurement offices show lowest price sensitivity due to wellness program budgets, while individual consumers in mass retail channels exhibit highest elasticity.
Supply Chain Analysis
Freight cost differentials between Mediterranean port access and inland European distribution favor Portuguese and Spanish mills over Nordic suppliers serving central European binderies. Raw material sourcing concentrates in Sweden and Finland for softwood pulp, Italy for leather tanning, and Portugal for recycled fiber processing. Single-supplier vulnerability sits with Tuscan tannery clusters facing REACH chemical restriction enforcement. Distribution runs through direct-to-enterprise channels capturing corporate gift program volume alongside traditional stationery wholesalers serving retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as producers pursue captive fiber sourcing to secure margin control against pulp price volatility and regulatory compliance costs.
For Market Incumbents: Hedge against digital substitution by embedding QR-linked companion tools into physical formats before hybrid workflow loyalty calcifies around app-native competitors. Secure backward integration into certified recycled fiber streams in Portugal and Spain to preempt EU Green Deal traceability mandates. Channel control through direct-to-enterprise procurement relationships protects margin from wholesale distributor compression.
For New Entrants and Emerging Players: Launch via direct fulfillment to boutique agency clusters in Berlin and Amsterdam where employer branding teams source customized onboarding kits outside conventional retail intermediaries. Target underpenetrated Nordic markets in Sweden and Denmark with localized format launches sized for mobile workforce portability requirements. White space sits in biodegradable adhesive innovation for spine compounds meeting retailer sustainability mandates.
For Investors and Strategic Acquirers: Distressed-cycle entries favor certified paper mills with EU Ecolabel accreditation in Iberian markets facing working capital pressure from Green Deal retooling requirements. Long-term viability hinges on hybrid workflow integration capabilities spanning physical-digital companion tools. Watch bullet journal maker-culture adoption rates on social platforms as inflection indicator for unformatted dot-grid demand trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Binding Chemistry Investment | Starch-based spine compounds capture shelf space under EU retailer sustainability mandates. |
| Direct-to-Enterprise Channel Development | Bypassing wholesale distributors captures margin from corporate wellness program procurement. |
| Traceable Fiber Supply Integration | Portuguese and Spanish mill partnerships secure compliance with EU Green Deal extended producer responsibility. |
| Hybrid Workflow Tool Development | QR-linked digital companions counter app-native competitor subscription retention. |
| Customizable Layout Platform Launch | Configurable templates serve boutique agency buyers rejecting rigid pre-printed formats. |
Research Methodology
Trade publications, customs records, and EU regulatory filings formed the secondary backbone for supply chain mapping and compliance timeline assessment. Primary interviews with paper mill procurement directors, bindery operations managers, corporate wellness program coordinators, and stationery category buyers at major retailers validated volume assumptions and pricing tier structures. Bottom-up and top-down triangulation reconciled production capacity data with end-use demand signals across corporate gift, retail, and direct-to-enterprise channels.
Bottom-up modeling anchored forecasts in segment-level volume and value trajectories, while top-down validation cross-checked against macroeconomic indicators and consumer discretionary spending patterns. Segmentation dimensions included product type, material certification tier, size format, and feature configuration across the analysis window. CAGRs derived from historical growth rate analysis adjusted for regulatory intervention timing and substitution elasticity parameters. Forecast inputs incorporated pulp price volatility indices and REACH enforcement probability assessments.
Pulp price shocks, digital calendar substitution acceleration, and REACH chemical restriction tightening are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions about corporate wellness program adoption curves and hybrid workflow integration success rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Cutter Staplers Market
Office Supplies
Marker Pens Market
Office Supplies
Dictionary Pen Market
Office Supplies
Acrylic Marker Pen Market
Office Supplies
Stamp Pad Market
Office Supplies
Erasable Ink Pen Market
Office Supplies
Office Supplies Market
Office Supplies
School Stationery Supplies Market
Office Supplies
Stationery Products Market
Office Supplies
Perforated File Market
Office Supplies
Stationery Market
Office Supplies
Business Card Holder Market
Office Supplies
Copiers Market
Office Supplies
Greetings Cards Market
Office Supplies
Flash Cards and USB Flash Drives Market
Office Supplies
Latin America School Stationery Supplies Market