
 Perforated File Market | 2026-2036
Perforated File Market Size, Share, and Industry Trends Forecast 2026-2036
Perforated File Market Insights
EU Green Deal material traceability requirements is expanding demand for recyclable paper and cardboard perforated files across European corporate buyers. Esselte Corporation leverages its Nordic manufacturing footprint to supply FSC-certified binder lines to enterprise accounts. Fellowes Brands competes through ergonomic organizer designs that target home-office segments in North America. Staples Inc. controls retail shelf placement through private-label expanding file programs in its brick-and-mortar network.
Perforated files are document storage devices incorporating pre-punched holes aligned to standard ring mechanisms, typically manufactured from kraft paper, polypropylene, or recycled cardboard substrates through die-cutting and thermal bonding processes. Their primary commercial purpose is systematic paper organization within vertical filing systems across administrative environments. Paper-based folders retain dominant volume share in educational institutions where budget constraints limit plastic adoption, while vinyl organizers command premium positioning in legal practices requiring durable, moisture-resistant document handling. Custom-size segments are gaining traction among architectural firms and engineering consultancies managing oversized technical drawings.
EPA guidelines on recycled content procurement influence federal and state-level purchasing specifications in the United States, while REACH chemical restrictions in Europe reshape plasticizer formulations used in polypropylene binder production. BIS certification requirements in India mandate dimensional accuracy for A4 and Legal formats sold through institutional channels. Stakeholders must monitor evolving extended producer responsibility frameworks that increasingly assign collection and recycling obligations to original manufacturers rather than downstream distributors.
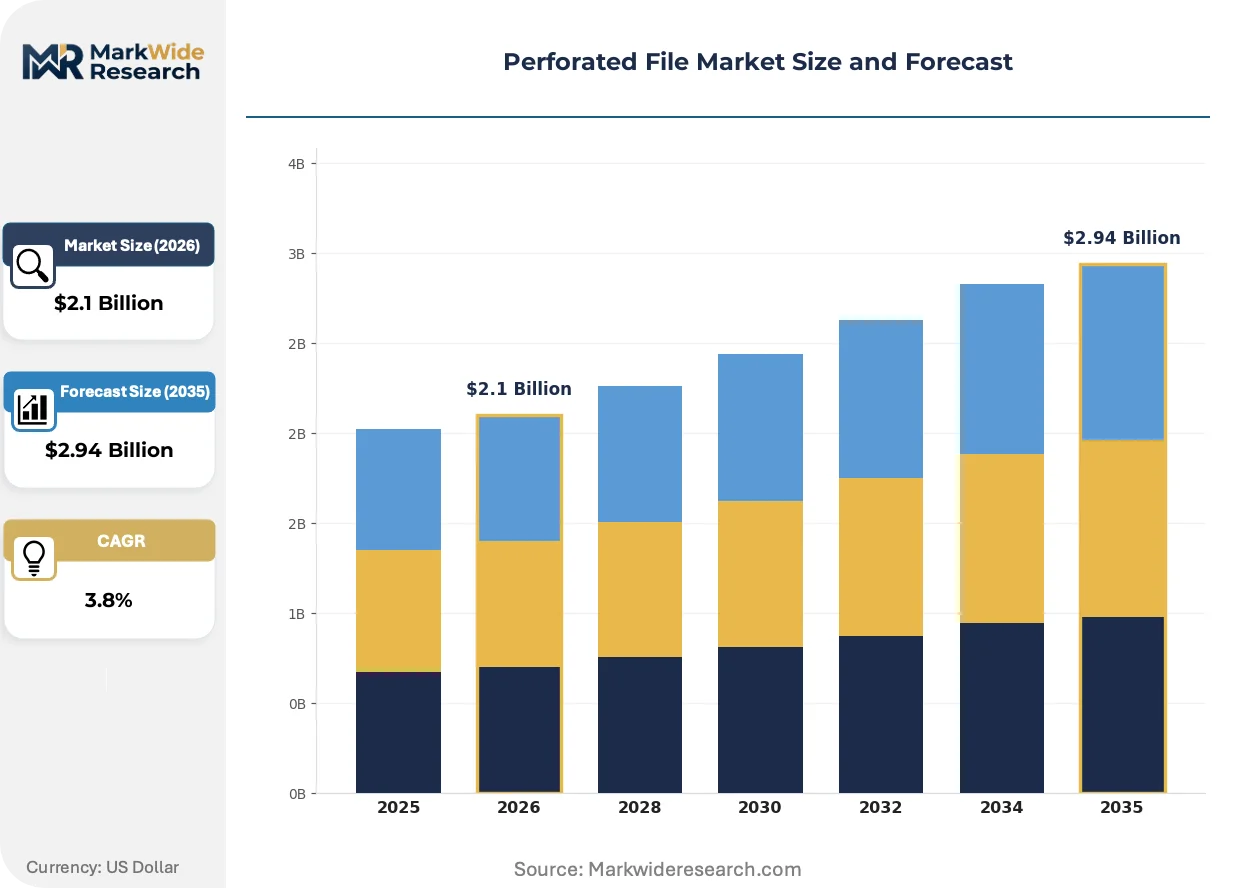
Market Dynamics
REACH chemical restrictions are forcing polypropylene binder manufacturers across Europe to reformulate plasticizers and accelerate substrate substitution toward kraft paper and recycled cardboard alternatives.
Growth Catalysts
- EU Green Deal traceability mandates:Corporate procurement departments in Germany and France now require FSC-certified document management products, expanding certified paper file volumes through institutional channels.
- India's organized retail expansion:Commercial stationery distributors in Mumbai and Delhi now stock BIS-certified perforated files, connecting manufacturers directly to enterprise accounts previously served by informal vendors.
- Thermal bonding automation:Die-cutting equipment upgrades in Nordic manufacturing facilities are reducing unit production costs for custom-size architectural file formats.
Market Restraints
- Pulp price volatility:Kraft paper input costs fluctuate with Nordic softwood supply disruptions, compressing margins for mid-tier manufacturers dependent on spot market purchasing.
- Polypropylene formulation complexity:ECHA's evolving SVHC candidate list creates compliance uncertainty for plastic binder producers, extending R&D cycles before product launch.
- Digital document substitution:Cloud-based contract management platforms in legal and financial services are reducing physical file consumption in premium vinyl segments.
Strategic Opportunities
- Architectural custom formats:Engineering consultancies in Germany and Japan require oversized perforated files for technical drawings, a segment with limited specialized supply.
- Extended producer responsibility frameworks:France's AGEC law and similar mechanisms assign collection obligations to manufacturers, creating first-mover advantage for integrated recycling operators.
- Home-office ergonomic positioning:North American remote workers are purchasing premium organizer systems through direct-to-consumer channels, bypassing traditional office supply distributors.
Industry Challenges
- REACH compliance timeline compression:Plasticizer substitution testing requires 18-24 month validation cycles, delaying product refreshes for polypropylene-dependent portfolios.
- Legacy filing system integration:Enterprise customers in government and healthcare maintain vertical filing infrastructure incompatible with new standard hole patterns without capital equipment replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perforated File Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binder, Folder, Organizer, Expanding File Material: Plastic, Paper, Cardboard, Vinyl Size: A4, Letter, Legal, Custom End User: Offices, Schools, Libraries, Home Users |
| Companies Covered | Esselte Corporation, GBC, Fellowes Brands, Staples Inc., 3M Company, Avery Dennison Corporation, Leitz, Bantex, ACCO Brands Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perforated File Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to reshape substrate composition across perforated file manufacturing, while distribution channels fragment between traditional retail and specialized direct supply.
Recycled cardboard substrates with enhanced moisture resistance are expanding into legal practice document handling, displacing vinyl in mid-tier applications where durability requirements have softened. Large German law firms now specify these formats for case file archiving, reducing plastic dependency while maintaining structural integrity. This substrate migration is compressing the addressable market for conventional polypropylene binders in professional services.
EPA recycled content procurement guidelines are reshaping federal and state purchasing specifications across the United States, mandating minimum post-consumer material thresholds for office supply contracts. Federal agencies in Washington and state procurement offices in California now require documentation of supply chain recycling rates. Paper-based file manufacturers with certified closed-loop systems capture disproportionate share of these institutional tenders.
Enterprise purchasing departments are consolidating vendor relationships and demanding volume-based pricing transparency previously reserved for commodity categories. Large German automotive suppliers and Indian pharmaceutical exporters now negotiate direct supply agreements with manufacturers, bypassing traditional wholesale distributors. This concentration is most visible in Mumbai's commercial stationery sector, where organized retail chains have absorbed independent dealer networks.
Perforated File Market Segmentation
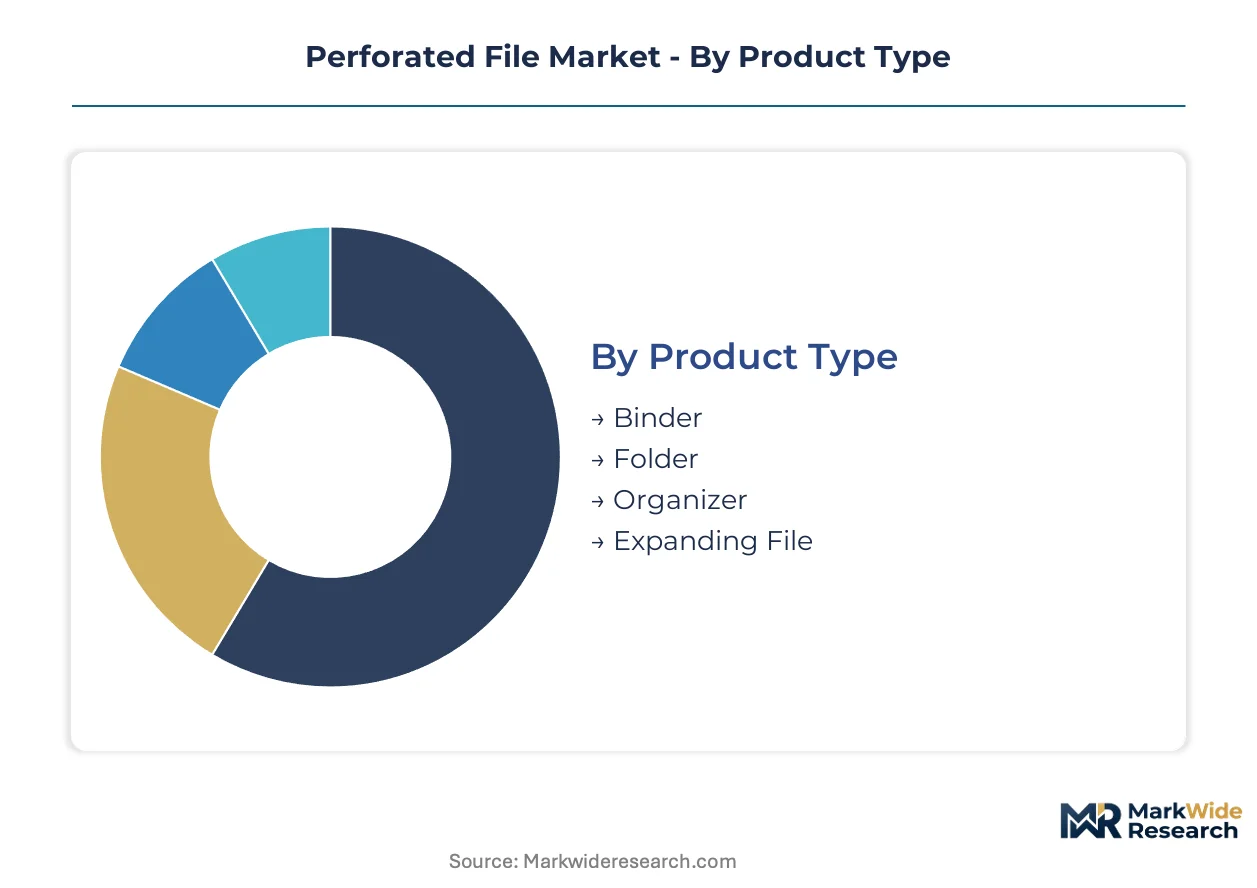
Perforated file segmentation reflects divergent compliance burdens across substrate types and end-use environments. Certification requirements from ECHA, EPA, and BIS reshape procurement specifications and manufacturing priorities differently for each category.
Product Type:
FSC certification dominates paper-based segments while polypropylene binders face REACH plasticizer scrutiny. Ergonomic design patents matter most for organizers targeting home-office channels.
- Binder:Ring mechanisms incorporate steel or polypropylene components with pre-punched alignment slots. German automotive suppliers and Indian pharmaceutical exporters negotiate direct supply agreements for certified binder volumes, bypassing wholesale distributors entirely.
- Folder:Kraft paper and recycled cardboard substrates require FSC chain-of-custody documentation for EU institutional tenders. Educational institutions in India specify BIS-certified folders where budget constraints limit plastic adoption.
- Organizer:Ergonomic designs with indexed dividers command premium positioning in North American home-office segments. Fellowes Brands competes through specialized configurations.
- Expanding File:Accordion-pleated construction accommodates bulk document storage in legal practices. Staples Inc. controls retail placement through private-label programs.
Leading the category by volume: Binder. Growing fastest: Organizer.
Material:
Substrate selection determines regulatory exposure and margin structure across manufacturing footprints.
- Plastic:Polypropylene formulations face ECHA SVHC candidate list uncertainty, extending R&D cycles. Reformulation timelines stretch 18-24 months for compliant plasticizer alternatives.
- Paper:Kraft paper input costs fluctuate with Nordic softwood supply disruptions. EPA recycled content guidelines mandate minimum post-consumer thresholds for US federal contracts.
- Cardboard:Enhanced moisture-resistant variants displace vinyl in mid-tier legal applications. Large German law firms now specify these formats for case file archiving.
- Vinyl:Premium moisture-resistant positioning persists in legal practices requiring durable document handling. Digital substitution from cloud platforms compresses addressable demand.
Highest certification burden: Plastic. Fastest substrate shift: Cardboard.
Size:
Dimensional standardization varies by regional filing infrastructure and document format conventions.
- A4:ISO 216 standard dominates European and Asian institutional procurement. BIS certification in India mandates dimensional accuracy for A4 formats sold through commercial channels.
- Letter:US customary format aligns with federal and state government vertical filing systems. Legacy infrastructure compatibility constraints limit format migration.
- Legal:Extended length accommodates contract documents and court filings. Law firms maintain specialized storage infrastructure for this format.
- Custom:Architectural and engineering consultancies in Germany and Japan require oversized formats for technical drawings. Die-cutting automation in Nordic facilities reduces production costs for these specialized dimensions.
Dominant procurement volume: A4. Steepest expansion trajectory: Custom.
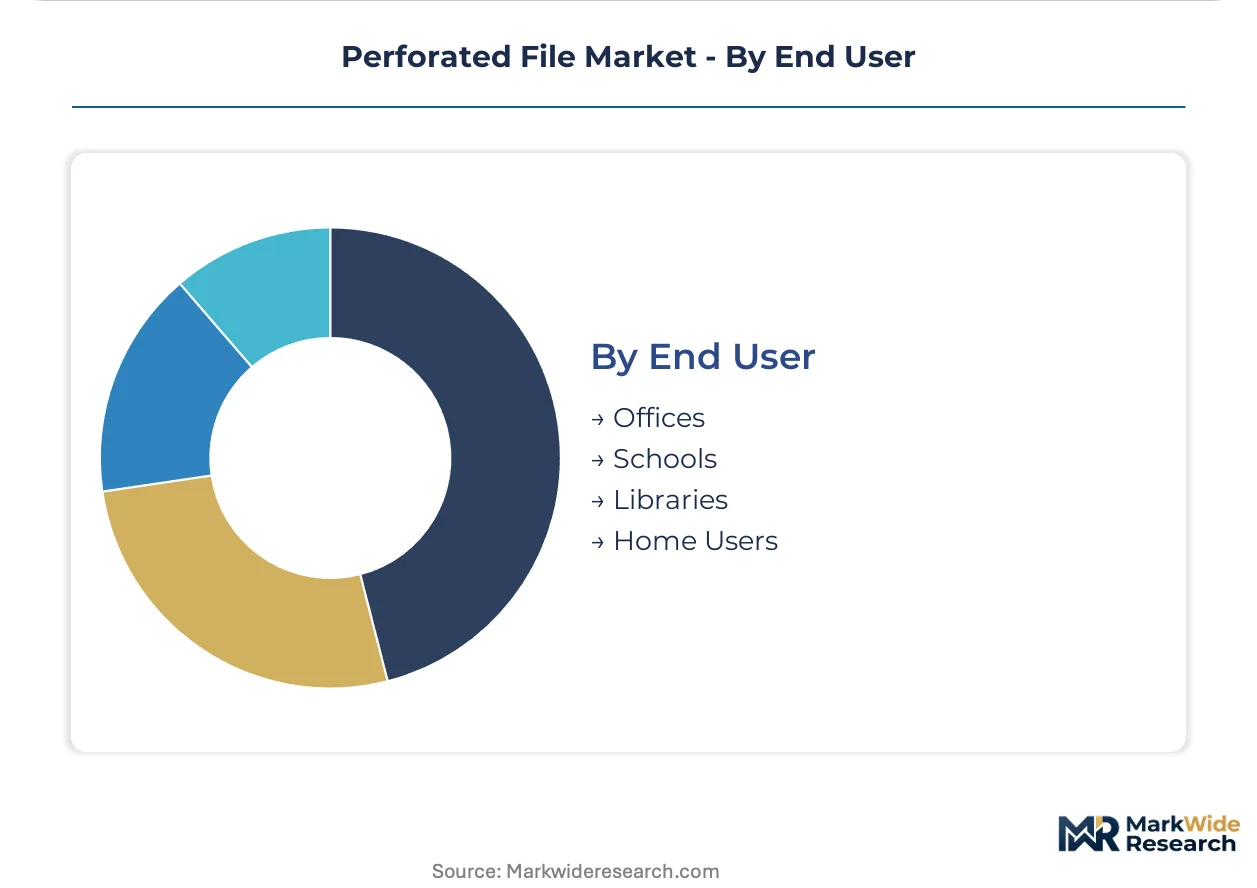
End User:
Budget authority and compliance sophistication vary sharply across institutional versus individual purchasers.
- Offices:Corporate procurement departments consolidate vendor relationships and demand volume-based pricing transparency. EU Green Deal traceability mandates expand FSC-certified document management requirements.
- Schools:Budget constraints limit plastic adoption and prioritize paper-based folders. Public sector procurement cycles align with academic calendar purchasing windows.
- Libraries:Archival durability specifications favor acid-free substrates with extended lifespan ratings. Preservation standards drive material selection over cost minimization.
- Home Users:Remote workers purchase premium organizer systems through direct-to-consumer channels, bypassing traditional office supply distributors. Ergonomic features command price premiums in this segment.
Largest institutional volume: Offices. Fastest channel shift: Home Users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's commercial stationery sector anchors procurement expansion for perforated files, with organized retail chains absorbing independent dealer networks and connecting manufacturers directly to enterprise accounts.
United States
Federal agencies in Washington and state procurement offices in California mandate EPA recycled content thresholds for office supply contracts. Paper-based file manufacturers with certified closed-loop systems capture disproportionate institutional tender share. The Pacific Northwest hosts concentration of kraft paper suppliers serving document management product fabricators.
Germany
REACH chemical restrictions force polypropylene binder manufacturers to reformulate plasticizers and accelerate substrate substitution toward kraft paper alternatives. Large automotive suppliers negotiate direct supply agreements for certified binder volumes, bypassing wholesale distributors entirely. Bavaria's manufacturing corridor hosts die-cutting automation facilities reducing production costs for custom-size architectural formats.
India
BIS certification requirements mandate dimensional accuracy for A4 and Legal formats sold through institutional channels in Mumbai and Delhi. Commercial stationery distributors now stock certified perforated files, connecting manufacturers to enterprise accounts previously served by informal vendors. Maharashtra's organized retail expansion absorbs independent dealer networks.
Japan
Engineering consultancies in Nagoya and Osaka require oversized perforated files for technical drawings, a segment with limited specialized supply. METI standards influence material specifications for document management products in corporate procurement. The Kansai region concentrates demand from architectural firms managing oversized format requirements.
France
AGEC law assigns extended producer responsibility collection obligations to manufacturers, creating first-mover advantage for integrated recycling operators. Corporate procurement departments require FSC-certified document management products, expanding certified paper file volumes. Paris-based legal practices now specify moisture-resistant recycled cardboard formats for case file archiving.
Perforated File Market Competitive Landscape
The competitive structure tilts toward diversified office supply conglomerates with established retail distribution networks. Mid-tier specialists compete on substrate certification and custom-format capabilities. Three archetypes dominate: Nordic manufacturers leveraging FSC-certified supply chains, North American brands targeting home-office ergonomics, and integrated retailers controlling private-label shelf placement. Capacity expansion in die-cutting automation and strategic partnerships for recycled material sourcing represent the dominant competitive moves.
Among Nordic-based manufacturers, Esselte Corporation occupies a position exemplifying certified supply chain integration, while Fellowes Brands represents the ergonomic design specialization targeting remote work segments. Staples Inc. anchors the retail-integrated archetype through private-label program control.
| Leading Market Players |
|---|
| Esselte Corporation |
| GBC |
| Fellowes Brands |
| Staples Inc. |
| 3M Company |
| Avery Dennison Corporation |
| Leitz |
| Bantex |
| ACCO Brands Corporation |
| Others |
Pricing and Supply Chain Analysis
Kraft paper pulp costs originating from Nordic softwood suppliers cascade through three distinct pricing tiers before reaching end buyers, with FSC-certified grades commanding premiums in German corporate procurement while spot-market-dependent manufacturers absorb margin compression in the mid-tier standard segment.
Pricing Analysis
Certification-grade anchoring determines price positioning across the perforated file market, with FSC chain-of-custody documentation and BIS dimensional accuracy compliance serving as the primary value-based differentiators in EU and Indian institutional tenders respectively. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded levels stratifies the market, with volume-scale negotiations and after-sales bundling of ergonomic accessories providing secondary differentiation. Pricing pressure stems from pulp price volatility in Nordic supply disruptions, compressing margins for manufacturers lacking long-term fiber supply agreements. Educational institutions in India exhibit highest price sensitivity due to budget-constrained procurement cycles, while German automotive suppliers demonstrate lowest sensitivity given compliance-driven specification requirements.
Supply Chain Analysis
Domestic-content mandates under France's AGEC law and EPA recycled content procurement guidelines are reshaping sourcing patterns toward localized certified fiber processing and closed-loop recycling infrastructure. Manufacturing concentration centers on Germany, India, and Vietnam, with kraft paper, polypropylene resin, and steel ring mechanisms representing the critical input dependencies. Single-source vulnerability in Nordic softwood pulp supply creates structural exposure for paper-based file manufacturers. Distribution runs through organized retail chains in Mumbai and Delhi, direct supply agreements with German automotive suppliers, and Staples Inc.'s private-label brick-and-mortar network in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The perforated file market functions as a cost-of-compliance arena where REACH plasticizer restrictions and extended producer responsibility frameworks erect regulatory moats favoring incumbent players with certified supply chains and integrated recycling capabilities.
For Market Incumbents: Extend FSC-certified product lines into architectural custom formats to capture underserved engineering consultancy demand in Germany and Japan, while accelerating die-cutting automation investments in Nordic facilities to defend margin position against pulp cost volatility. Digital document substitution from cloud-based contract management platforms threatens vinyl segment volumes, requiring substrate diversification toward moisture-resistant recycled cardboard for legal practice archiving. For New Entrants and Emerging Players: Launch via direct-to-consumer ergonomic organizer channels targeting North American remote workers, bypassing traditional wholesale distributor networks controlled by established retail conglomerates. The home-office segment offers lowest certification barriers and highest price premium capture, with Fellowes Brands' design patent positioning revealing white-space opportunity in indexed divider configurations. For Investors and Strategic Acquirers: ECHA's SVHC candidate list expansion is the leading indicator that polypropylene-dependent manufacturers face 18-24 month product refresh delays, creating acquisition opportunity for integrated paper-based substrate operators with compliant formulation pipelines. Long-term viability favors vertically integrated recyclers under France's AGEC collection obligations and similar extended producer responsibility frameworks emerging across EU member states. The signal to monitor is BIS certification mandate expansion beyond current A4 and Legal formats into custom architectural dimensions.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Certification Expansion | Captures EU Green Deal procurement mandates from German corporate and French government accounts. |
| Die-Cutting Automation Investment | Reduces unit costs for custom-size architectural formats serving Nagoya engineering consultancies. |
| Recycled Cardboard Formulation | Displaces vinyl in Paris legal practices while meeting AGEC extended producer responsibility requirements. |
| Direct Supply Agreement Negotiation | Bypasses Mumbai wholesale distributors to capture Indian pharmaceutical exporter volume consolidation. |
| Ergonomic Design Patent Filing | Secures premium positioning in North American home-office channels through Fellowes Brands competitive response. |
Research Methodology
Trade association filings from the European Federation of Office Stationery Manufacturers, EPA procurement guideline documentation, and BIS certification registry data formed the secondary backbone, supplemented by customs records tracking kraft paper and polypropylene resin flows. Primary interviews with procurement directors at German automotive suppliers, category managers at Mumbai organized retail chains, and regulatory affairs leads at Nordic manufacturing facilities validated demand assumptions. Bottom-up and top-down triangulation reconciled production capacity data with institutional tender volumes across the analysis window.
Bottom-up modeling aggregated segment-level volume trajectories across substrate types, end-user environments, and dimensional formats, while top-down approaches cross-referenced macroeconomic indicators with office supply expenditure patterns. Product type, material composition, size standardization, and end-user procurement sophistication served as the core segmentation dimensions. CAGRs were derived from regression analysis of historical procurement cycles and regulatory implementation timelines, with pulp price indices and REACH compliance cost curves representing industry-specific forecast inputs.
Pulp supply disruption severity, ECHA SVHC list expansion timing, and digital document platform adoption velocity are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions regarding certification mandate enforcement consistency and recycling infrastructure buildout rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Erasable Ink Pen Market
Office Supplies
Copiers Market
Office Supplies
Diaries & Planners Market
Office Supplies
Marker Pens Market
Office Supplies
Custom Binders Market
Office Supplies
Stamp Pad Market
Office Supplies
Thumb Hole Book Page Holder Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
Office Supplies Market
Office Supplies
Europe School Stationery Supplies Market
Office Supplies
Writing Instruments Market
Office Supplies
Malaysia Stationery Market
Office Supplies
Greetings Cards Market
Office Supplies
GCC School Stationery Supplies Market
Office Supplies
Latin America School Stationery Supplies Market
Office Supplies
Stationery Market