
 Stamp Pad Market | 2026-2036
Stamp Pad Market Size, Share, and Industry Trends Forecast 2026-2036
Stamp Pad Market Analytics
Multi-source procurement among corporate stationery buyers is expanding as organizations diversify vendor relationships to mitigate supply disruptions. Trodat leverages its European manufacturing footprint to sustain broad distribution across commercial channels. Shachihata anchors premium positioning in East Asia through precision-engineered self-inking mechanisms. Colop competes on modular refillable systems that reduce long-term operational costs for high-volume users.
A stamp pad is a handheld device containing an absorbent substrate saturated with ink, designed to transfer uniform impressions onto paper or compatible surfaces through contact with a separate rubber or polymer stamp. The substrate typically employs open-cell foam or compressed felt with controlled porosity measured in pores per inch to regulate ink release rates and prevent bleeding or uneven coverage. Self-inking pads lead unit volume due to integrated retraction mechanisms that eliminate separate ink storage, while pre-inked formulations capture margin concentration through extended impression counts before replenishment. Traditional felt-based products retain entrenched demand among educational institutions where low unit cost outweighs convenience features.
EPA regulations governing volatile organic compound emissions in ink formulations constrain solvent selection for domestic manufacturers, while REACH chemical registration requirements in Europe limit certain dye precursors in imported products. Japan's Ministry of Economy, Trade and Industry (METI) maintains JIS standards for document permanence that influence export specifications for regional suppliers. Stakeholders must monitor evolving chemical restriction schedules across these jurisdictions to anticipate reformulation costs and qualify alternative pigment systems before compliance deadlines tighten.
Market Dynamics
REACH chemical registration requirements in Europe are forcing reformulation of dye precursors across stamp pad manufacturing bases, compelling suppliers to qualify alternative pigment systems ahead of compliance deadlines while maintaining document permanence standards.
Growth Catalysts
- Self-inking mechanism adoption:Integrated retraction systems eliminate separate ink storage for high-frequency users in government offices and notary services, reducing per-impression handling time.
- METI JIS standards for document permanence:Japan's export specifications create qualified supplier status for regional manufacturers serving archival and legal documentation markets.
- Educational institution procurement cycles:Annual bulk purchasing agreements from K-12 systems sustain volume demand for traditional felt-based formats where low unit cost dominates selection criteria.
Market Restraints
- Petroleum-derived foam substrate volatility:Open-cell foam production depends on polyether polyol feedstock pricing tied to crude oil fluctuations, compressing margin stability for absorbent substrate manufacturers.
- East Asian precision component concentration:Self-inking retraction mechanisms rely on specialized spring and ratchet assemblies concentrated in Japanese and Taiwanese supplier networks, exposing buyers to single-source risk.
- Digital signature substitution:Adobe Acrobat Sign and DocuSign platforms displace wet-ink documentation in corporate contract workflows, eroding commercial stationery demand.
Strategic Opportunities
- India's PLI scheme for stationery manufacturing:Production-linked incentives for domestic manufacturing equipment create localized assembly opportunities for export-oriented suppliers.
- Pre-inked polymer formulations:Micro-encapsulated ink reservoirs extend impression counts tenfold over traditional saturation methods, capturing premium positioning in legal and financial services.
- Pharmaceutical serialization compliance:FDA track-and-trace mandates for drug packaging create demand for permanent lot-code stamping on secondary packaging lines.
Industry Challenges
- Pigment chemistry expertise scarcity:Formulation chemists with volatile organic compound compliance experience command premium compensation, constraining R&D staffing for mid-tier manufacturers.
- REACH pre-registration timelines:European Chemicals Agency notification windows for new dye precursors extend 18-24 months, delaying product launches for reformulated ink systems.
- Legacy equipment compatibility:Pre-inked cartridge geometries vary across Trodat, Colop, and Shachihata platforms, fragmenting aftermarket refill demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stamp Pad Market |
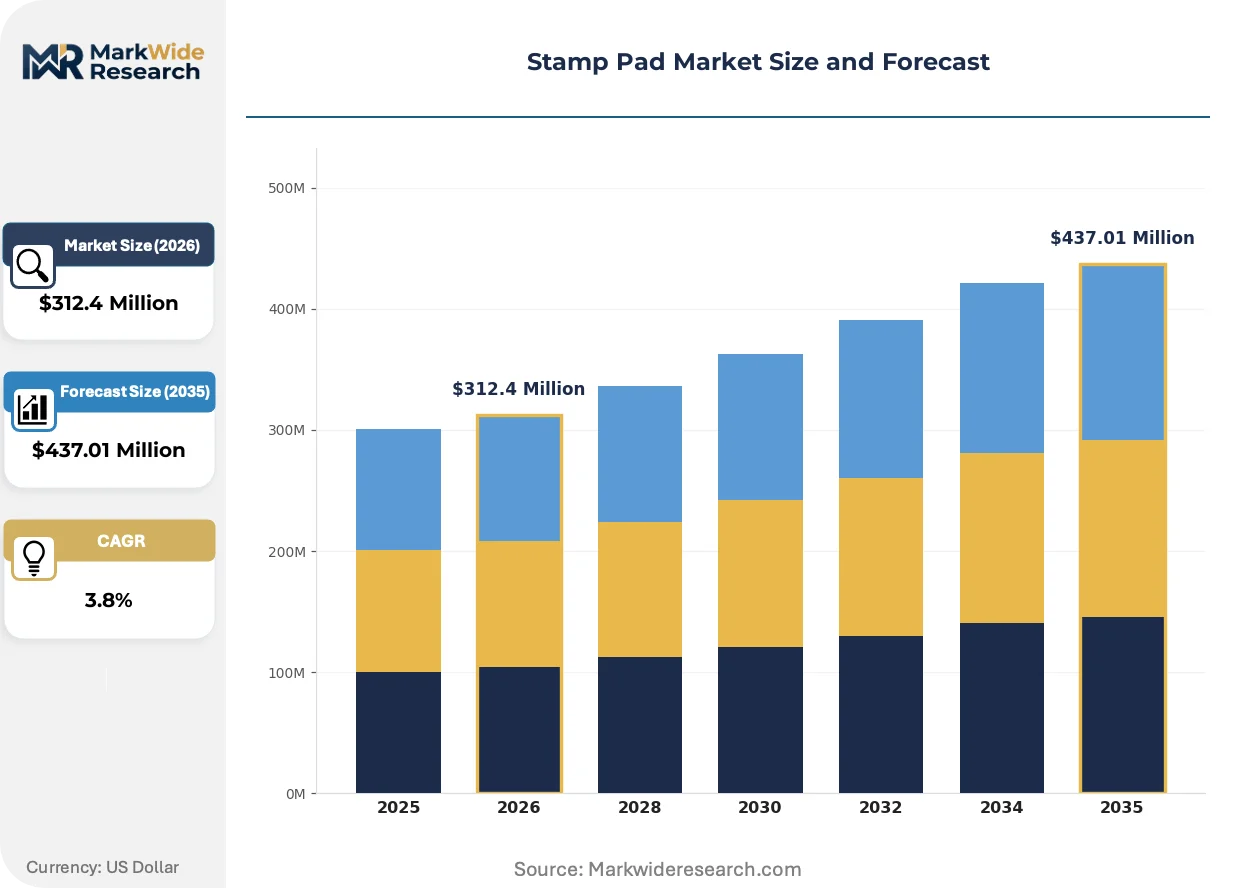
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Inking, Traditional, Pre-Inked, Refillable Material: Foam, Felt, Rubber, Fabric End User: Retailers, Offices, Artisans, Educational Institutions Size: Small, Medium, Large, Extra Large |
| Companies Covered | Shachihata, Trodat, Colop, Tsukineko, Pelikan, Shiny, Cosco, Avery, Speedball, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stamp Pad Market Evolving Landscape
Photopolymer plate technology is electrifying stamp pad manufacturing by enabling laser-etched micro-texture control over ink release rates. This shift permits substrate engineers to tune porosity gradients precisely rather than relying on uniform foam density.
Water-based acrylic emulsion formulations are displacing solvent-borne systems as EPA volatile organic compound emissions thresholds tighten for domestic ink production. Formulators at US manufacturing sites now prioritize coalescing agents with sub-50 g/L VOC content to maintain compliance without sacrificing dry time performance on uncoated paper stocks.
REACH authorization procedures for aromatic amine dye precursors are restructuring European supply chains for colored ink formulations. German and French distributors now demand full substance identity documentation from Asian pigment suppliers, shifting procurement qualification burden upstream to raw material handlers.
Corporate stationery buyers are consolidating vendor relationships into multi-year framework agreements with integrated e-procurement portals. Japanese trading houses and German office supply cooperatives now require API-enabled inventory visibility, replacing fax-based reorder cycles with automated consumption-triggered replenishment.
Stamp Pad Market Segmentation
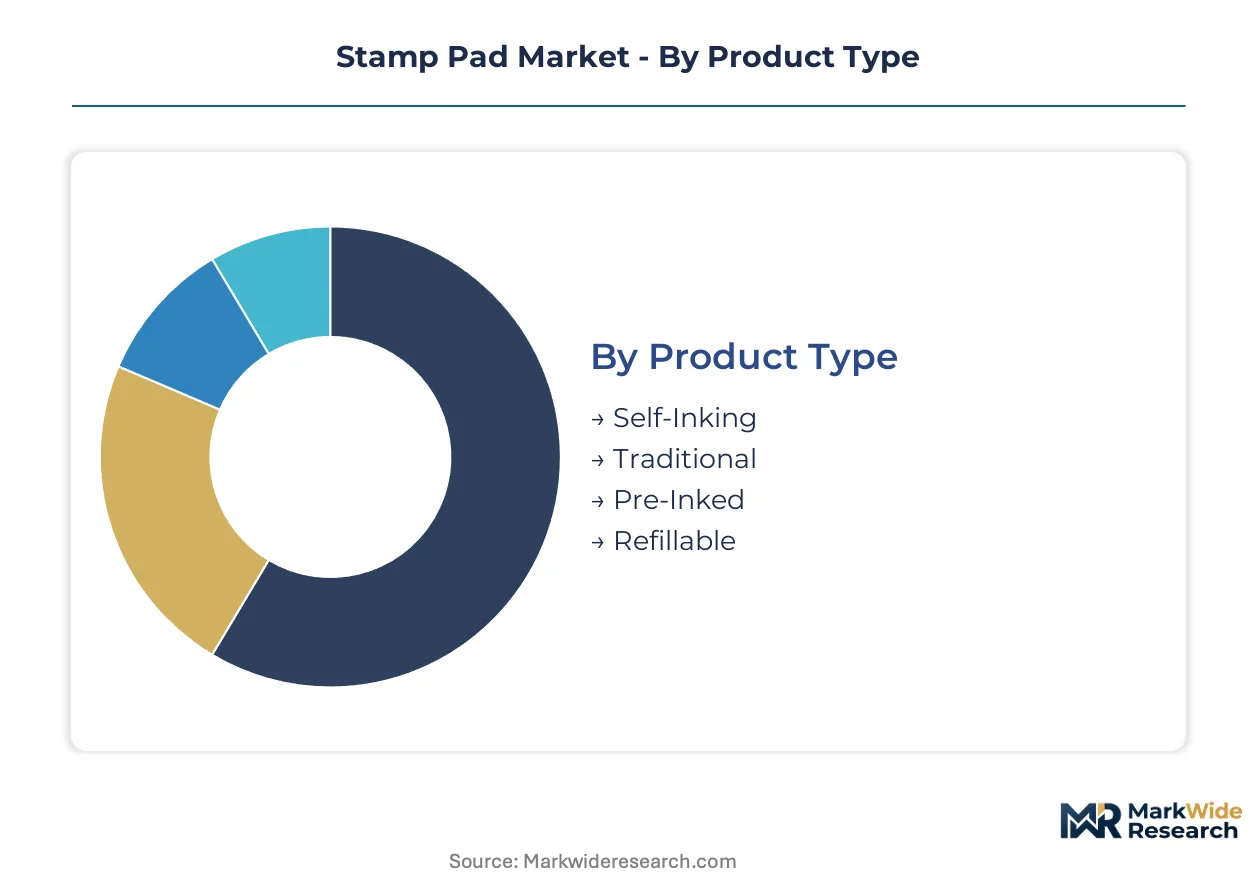
Stamp pad procurement patterns diverge sharply across product configurations, substrate materials, and institutional end-users. Regulatory compliance burdens and impression-volume economics drive distinct purchasing behaviors within each segment cluster.
Product Type:
REACH chemical registration and EPA volatile organic compound thresholds apply unevenly across mechanism designs, with integrated ink systems facing stricter substance documentation requirements than traditional open-pad formats.
- Self-Inking:Integrated retraction mechanisms house micro-cellular foam reservoirs within precision-molded housings. Government offices in Germany and Japan sustain recurring procurement through METI JIS-qualified suppliers for archival documentation workflows.
- Traditional:Open-cell foam or felt substrates require separate ink saturation, offering lowest unit cost for price-sensitive buyers. Educational institutions in the United States favor this format for classroom craft supplies where replacement frequency outweighs convenience premiums.
- Pre-Inked:Polymer gel matrices encapsulate pigment in laser-etched micro-pores, delivering extended impression counts. Legal services in Switzerland and Austria specify these for notarial seal applications demanding document permanence certification.
- Refillable:Modular cartridge systems permit substrate replacement without housing disposal, reducing long-term material consumption. Corporate stationery cooperatives in France prioritize these for sustainability reporting under EU Green Deal procurement guidelines.
Leading the category by volume: Self-Inking. Growing fastest: Pre-Inked.
Material:
Substrate chemistry determines compliance pathway breadth, with petroleum-derived foams facing REACH authorization scrutiny while natural fiber alternatives navigate BIS textile standards in India.
- Foam:Open-cell polyether structures regulate ink release through controlled porosity measured in pores per inch. Japanese precision manufacturers dominate supply for self-inking mechanism integration.
- Felt:Compressed wool or synthetic fiber mats offer uniform saturation for traditional pad formats. German educational distributors specify FSC-certified fiber sourcing for public sector tenders.
- Rubber:Solid elastomer substrates serve specialized industrial marking applications requiring solvent resistance. Automotive parts suppliers in Michigan and Stuttgart specify nitrile-blend compositions for grease-resistant lot coding.
- Fabric:Woven textile surfaces accommodate water-based acrylic formulations for craft and artistic use. Artisan cooperatives in Rajasthan and Oaxaca drive demand for hand-block printing compatibility.
Foam commands the greatest production volume. Fabric exhibits the steepest expansion trajectory among specialty material niches.
End User:
Procurement scale and compliance sophistication stratify across institutional buyer types, with government offices demanding full supply chain documentation while retail channels prioritize margin and turnover velocity.
- Retailers:Stationery chains and office supply distributors stock breadth-oriented assortments across price tiers. French and Italian retail cooperatives consolidate vendor relationships through multi-year framework agreements with automated replenishment triggers.
- Offices:Corporate and government administrative units specify durability-rated products for high-frequency impression workflows. Japanese municipal governments require METI JIS certification for all document-authentication stamps.
- Artisans:Individual craft practitioners and small studios prioritize substrate compatibility with specialty inks and hand tools. Brooklyn and Berlin maker communities sustain demand for customizable fabric-surface pads.
- Educational Institutions:K-12 systems and universities procure through annual bulk purchasing cycles with stringent cost-per-unit thresholds. Texas and California school districts specify traditional felt formats for art department budgets.
Offices generate the highest absolute demand. Artisans represent the most fragmented procurement pattern with lowest per-account volume.
Size:
Impression-area dimensions correlate with end-use application scale, from pocket-sized notary seals to industrial packaging-line daters requiring extended coverage.
- Small:Sub-25mm impression areas suit personal signature stamps and mobile notary applications. Swiss banking compliance officers specify these for client document authentication.
- Medium:25-50mm formats balance portability with logo visibility for standard business correspondence. German Mittelstand manufacturers standardize on this dimension for invoice and shipping document marking.
- Large:50-100mm coverage accommodates departmental seals and certification stamps. Japanese construction inspectors utilize these for building permit documentation.
- Extra Large:Exceeding 100mm impression width, these serve industrial batch-coding and pharmaceutical serialization. FDA track-and-trace mandates drive specification for secondary packaging lines in New Jersey and North Carolina pharmaceutical clusters.
Medium formats dominate unit shipments. Extra Large commands the highest per-unit pricing and is gaining share fastest in regulated packaging applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyether polyol feedstock availability in the United States and petroleum-derived foam substrate production in Japan anchor geographic procurement patterns for stamp pad manufacturing bases.
United States
Corporate stationery buyers and pharmaceutical packaging lines drive demand for pre-inked and extra-large formats. EPA volatile organic compound emissions thresholds constrain solvent selection for domestic ink formulators. New Jersey and North Carolina pharmaceutical clusters specify permanent lot-code stamping equipment for FDA track-and-trace compliance on secondary packaging lines.
Germany
Government offices and Mittelstand manufacturers sustain recurring procurement of self-inking and medium-format products. REACH chemical registration requirements at the European Chemicals Agency force reformulation of dye precursors ahead of compliance deadlines. Stuttgart and Hamburg host precision component suppliers for retraction mechanisms serving archival documentation workflows.
Japan
METI JIS standards for document permanence create qualified supplier status for regional manufacturers. Municipal governments require certification for all document-authentication stamps. Tokyo and Osaka precision engineering clusters dominate supply of specialized spring and ratchet assemblies for self-inking mechanisms.
India
Educational institutions and artisan cooperatives generate volume demand for traditional felt-based and fabric-surface formats. BIS textile standards govern natural fiber alternatives for substrate materials. Rajasthan hand-block printing communities and Maharashtra stationery distributors drive specialty and bulk procurement respectively.
Switzerland
Banking compliance officers and notarial services specify small-format and pre-inked products for client document authentication. Swissmedic documentation requirements influence export specifications for permanent ink formulations. Zurich and Geneva financial centers sustain premium-tier demand for document permanence certification.
Stamp Pad Market Competitive Landscape
Global majors compete with regional champions across precision engineering capabilities and regulatory compliance expertise. The vendor base stratifies into three tiers: integrated mechanism manufacturers with captive substrate production, specialized ink formulators with pigment chemistry depth, and regional assemblers serving price-sensitive educational markets. Two strategic archetypes dominate competitive positioning: precision-engineered self-inking specialists and modular refillable system providers. Capacity expansion in East Asian component clusters and strategic partnerships with European chemical distributors represent the dominant competitive moves.
Among precision-engineered mechanism specialists, Shachihata and Trodat occupy positions at the premium tier, with the former exemplifying East Asian manufacturing depth and the latter representing European regulatory compliance integration. Colop anchors the modular refillable archetype, sitting within the sustainability-focused procurement channel serving corporate stationery cooperatives. These three entities collectively illustrate the competitive spectrum spanning integrated retraction technology, regulatory qualification, and circular economy positioning.
| Leading Market Players |
|---|
| Shachihata |
| Trodat |
| Colop |
| Tsukineko |
| Pelikan |
| Shiny |
| Cosco |
| Avery |
| Speedball |
| Others |
Value Network & Pricing Analysis
EU Green Deal procurement guidelines gate qualified supply and premium-tier pricing access, forcing manufacturers to document circular-economy compliance before entering corporate stationery cooperatives in France and Germany. Buyers with sustainability mandates command preferential pricing leverage, while uncertified suppliers face margin compression in public sector tenders.
Pricing Analysis
Service-bundling separates premium-tier positioning: Trodat and Shachihata include METI JIS certification documentation and extended mechanism warranties in enterprise contracts, while economy-tier competitors unbundle these features for price-sensitive educational procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and impression-volume economics. Cost compression in traditional felt-based formats is intensifying because petroleum-derived foam feedstock volatility feeds through substrate manufacturing. Educational institutions in Texas and California exhibit highest price sensitivity; pharmaceutical packaging lines in New Jersey show lowest sensitivity due to FDA compliance requirements.
Supply Chain Analysis
Dual-sourcing requirements from German Mittelstand manufacturers and Japanese municipal governments mandate multi-supplier qualification for precision spring and ratchet assemblies. Geographic supply concentrates in Japan, Taiwan, and Germany for self-inking retraction mechanisms, while open-cell foam substrates draw from domestic production in the United States and Japan. Raw material dependencies center on polyether polyol feedstocks, laser-etched photopolymer plates, and aromatic amine dye precursors. Single-source vulnerability in East Asian precision component networks exposes buyers to disruption. Distribution runs through stationery cooperatives and trading houses with API-enabled inventory visibility replacing legacy fax-based reorder cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized pigment chemistry expertise scarcity props pricing power for qualified suppliers, as REACH pre-registration timelines and EPA VOC compliance requirements constrain new formulation development.
For Market Incumbents: Deploy backward integration into captive substrate production to defend margin position against petroleum feedstock volatility. Shachihata and Trodat should accelerate JIS and REACH certification investments to lock out mid-tier competitors from archival documentation workflows. Control channel relationships with European office supply cooperatives to block private-label entrants. For New Entrants and Emerging Players: The price-point gap between premium self-inking systems and economy traditional pads offers entry space for modular refillable formats targeting sustainability-focused corporate procurement in France. White-space targets include India's PLI-supported domestic assembly for export-oriented suppliers and artisan-directed fabric-surface pads in Rajasthan and Oaxaca. A direct-to-maker-community go-to-market angle bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: ECHA authorization delays for new dye precursors are the leading indicator that pigment chemistry capabilities will command scarcity premiums. Long-term viability favors vertically integrated manufacturers with in-house formulation expertise and mechanism engineering depth. Target acquisition archetype: mid-tier ink formulators with EPA compliance experience and untapped capacity for pre-inked polymer gel matrices. Watch for consolidation signals when REACH notification backlogs exceed 24 months.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive foam manufacturing insulates margins from polyether polyol price swings at German and Japanese facilities. |
| REACH Pre-Registration Acceleration | Early ECHA notification secures market access ahead of compliance deadlines for reformulated pigment systems. |
| API-Enabled E-Procurement Partnership | Automated inventory visibility with French and German cooperatives replaces fax-based reorder cycles. |
| Pre-Inked Polymer Formulation Launch | Micro-encapsulated ink reservoirs capture premium positioning in Swiss notarial and legal services markets. |
| India PLI Scheme Localization | Domestic assembly equipment qualification opens export-oriented production for regional stationery distributors. |
Research Methodology
Multi-period observation of procurement cycle timing, regulatory notification backlogs, and feedstock price movements anchored the trend analysis, supplemented by interviews with ink formulation chemists, precision component engineers, stationery cooperative procurement directors, and educational supply chain managers. Secondary validation drew from EPA VOC emissions filings, ECHA REACH registration databases, METI JIS certification records, and customs trade data for polyether polyol imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting distributed volume and value estimates across product type, substrate material, end-user institution, and impression-size dimensions. Self-inking mechanism adoption curves, pre-inked polymer penetration rates, and digital signature substitution thresholds informed growth trajectory modeling throughout the forecast period. CAGRs derived from regression analysis of historical procurement patterns and regulatory compliance cost pass-through elasticity.
Underlying measurement precision varies by segment; self-inking and pre-inked categories carry tighter precision than fragmented artisan channels. Forecasts reflect assumptions about REACH authorization timelines, petroleum feedstock stability, and digital documentation substitution rates. Deviation in ECHA notification processing speed or East Asian component supply continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Writing Instruments Market
Office Supplies
Europe School Stationery Supplies Market
Office Supplies
Flash Cards and USB Flash Drives Market
Office Supplies
Office Supplies Market
Office Supplies
Copiers Market
Office Supplies
Stationery Market
Office Supplies
School Stationery Supplies Market
Office Supplies
Cutter Staplers Market
Office Supplies
GCC School Stationery Supplies Market
Office Supplies
Stationery Products Market
Office Supplies
Letter Opener Market
Office Supplies
Business Card Holder Market
Office Supplies
Printer Ink Cartridge Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
Global Office Peripherals and Products Market
Office Supplies
Pencil Sharpeners Market