
 Electronic Musical Instruments Market | 2026-2036
Electronic Musical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Musical Instruments Market Analysis
The premium synthesizer segment is repositioning around boutique modular architectures and limited-run analog circuits while commodity digital pianos and entry-level drum machines compete on cost and distribution footprint. Yamaha leverages its integrated semiconductor foundry partnerships to sustain proprietary chip architectures across digital piano lines. Roland anchors its professional tier through deep specialization in hybrid analog-digital sound engines for studio and stage applications.
Electronic musical instruments comprise electromechanical and solid-state devices that generate, modify, or reproduce musical tones through oscillators, digital signal processors, and firmware-controlled interfaces, typically operating across frequency ranges from 20 Hz to 20 kHz with 16- to 24-bit resolution for professional applications. These systems serve commercial purposes spanning live performance reinforcement, commercial music production, and institutional pedagogy. Synthesizers command the highest margin pools among product types due to software subscription attach rates and expansion module ecosystems. Digital pianos represent the volume anchor for educational institutions and hobbyist segments, while software-based instruments are displacing hardware samplers in project studio configurations.
FCC certification requirements in the United States govern electromagnetic emissions from digital instruments with wireless connectivity, while EU REACH and RoHS frameworks restrict hazardous substances in circuit assemblies and solder formulations, effectively filtering supplier bases for brands selling into European markets. China's GB standards and MIIT type-approval processes create parallel compliance tracks for domestic distribution and export manufacturing. Stakeholders must monitor divergence between regional electromagnetic compatibility standards and substance restrictions as firmware update cycles compress and connected instruments proliferate across price tiers.
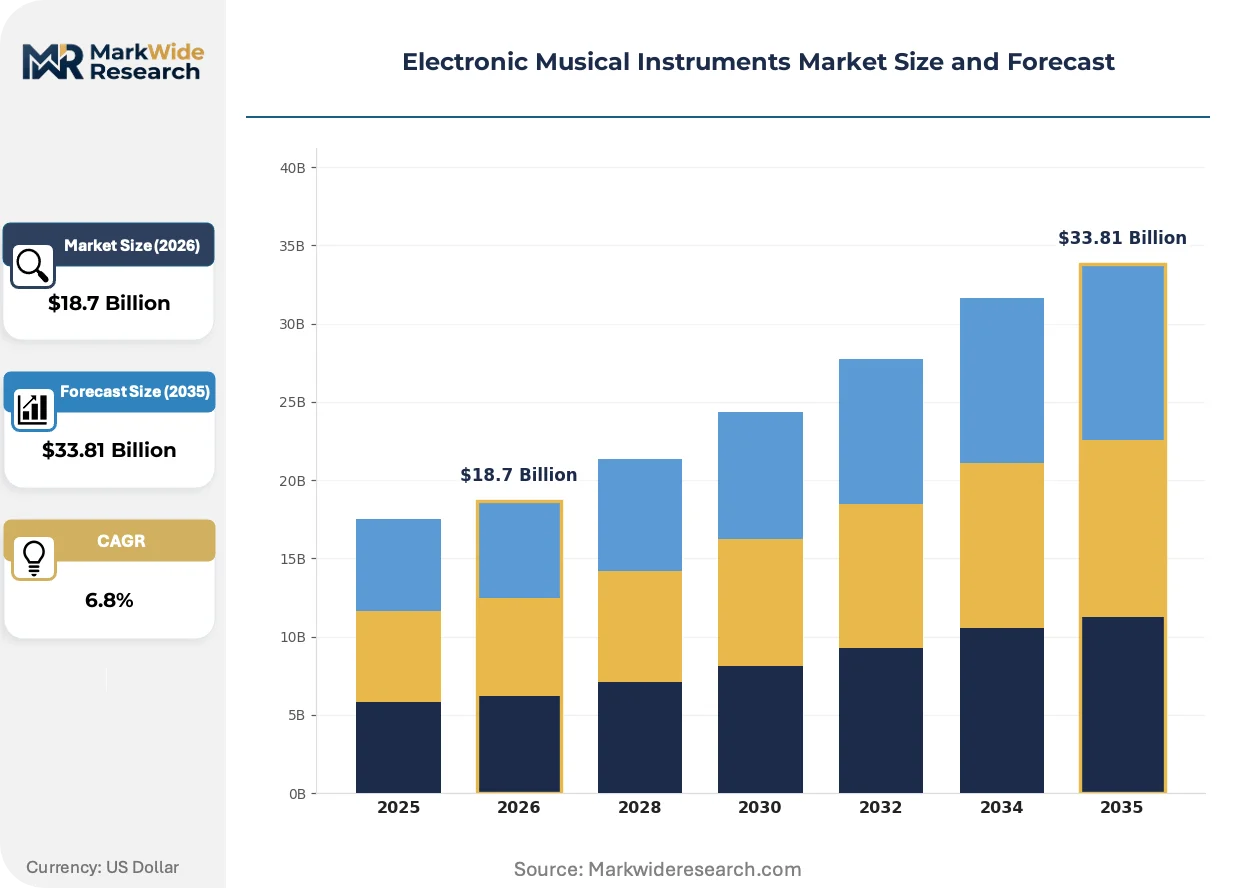
Market Dynamics
The convergence of hybrid analog-digital architectures with cloud-connected firmware ecosystems is compressing product refresh cycles and redistributing margin pools from hardware sales toward software subscription attach rates across professional and prosumer segments.
Growth Catalysts
- EU Green Deal compliance:REACH and RoHS substance restrictions on circuit assemblies are accelerating supplier consolidation, favoring manufacturers with captive semiconductor partnerships and certified green component pipelines.
- Project studio proliferation:Home-based music production setups are expanding demand for compact hybrid workstations with integrated audio interfaces and DAW control surfaces.
- China's domestic brand elevation:MIIT type-approval processes and GB standards compliance are enabling Chinese OEMs to transition from contract assembly to proprietary instrument design for domestic and export markets.
Market Restraints
- Semiconductor supply concentration:Proprietary chip architectures for digital signal processing depend on foundry capacity concentrated in Taiwan and South Korea, creating input volatility for synthesizer and digital piano manufacturers.
- FCC certification friction:Electromagnetic emissions testing for wireless-enabled instruments extends product launch timelines by four to eight months for US market entry.
- Software instrument substitution:Native Instruments and Ableton plugin ecosystems are displacing hardware samplers and grooveboxes in sub-$500 price tiers.
Strategic Opportunities
- India's institutional education market:CBSE and state board curriculum mandates for music education are creating procurement pipelines for digital pianos and classroom keyboard labs in tier-two cities.
- Spatial audio convergence:Integration of ambisonic encoding engines with traditional synthesizer architectures is opening theatrical and immersive installation applications.
- Direct-to-artist distribution:Social commerce platforms and artist-owned storefronts are bypassing traditional retail channels for limited-run modular components and boutique analog circuits.
Industry Challenges
- Analog circuit engineering scarcity:Specialized talent for discrete component voicing and voltage-controlled oscillator calibration is concentrated among retiring European and Japanese technicians.
- Multi-jurisdiction certification overlap:Divergent electromagnetic compatibility standards between FCC, CE marking, and China's MIIT require parallel testing protocols that strain mid-tier R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Musical Instruments Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthesizers, Drum Machines, Digital Pianos, Samplers End User: Professional Musicians, Hobbyists, Music Producers, Educational Institutions Technology: Analog, Digital, Software, Hybrid Application: Live Performance, Studio Recording, Music Education, Sound Design |
| Companies Covered | Gibson Brands, Guangzhou Pearl River Piano Group Co., Ltd., Yamaha, Beijing Hsinghai Piano Group Limited, Medeli Electronics (Shanghai) Co., Ltd., Roland, Fender Musical Instruments Corporation, Shanghai Huaxin Musical Instrument Co., Ltd., KORG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Musical Instruments Market Emerging Trajectories
Generative algorithms and machine-learning-based sound design tools are embedding into hardware workflows, shifting creative agency from manual patch programming toward probabilistic parameter exploration and automated timbre matching.
Machine-learning-powered timbre matching is automating the translation of acoustic instrument samples into synthesizable parameter sets. Professional composers in film and game scoring are adopting these tools to accelerate mockup-to-final production pipelines. This compression of sound design labor is reallocating studio budgets from hourly engineering rates toward software licensing and cloud compute subscriptions.
EU REACH substance restrictions on lead-free solder formulations and halogenated flame retardants are forcing PCB fabricators to qualify alternative metallurgy and substrate materials. Instrument manufacturers serving European markets must revalidate thermal cycling performance and reworkability under these revised material standards. Premium synthesizer brands with vertically integrated fabrication capabilities are absorbing compliance costs more efficiently than assembly-dependent competitors.
Educational institutions are consolidating vendor relationships through multi-year fleet purchasing agreements that bundle instruments, curriculum software, and instructor certification. This procurement concentration is displacing transactional retail purchases in K-12 and university segments. The shift is most pronounced in US public school districts and UK academy trusts where centralized procurement offices negotiate enterprise terms directly with Yamaha, Roland, and Korg education divisions.
Electronic Musical Instruments Market Segmentation
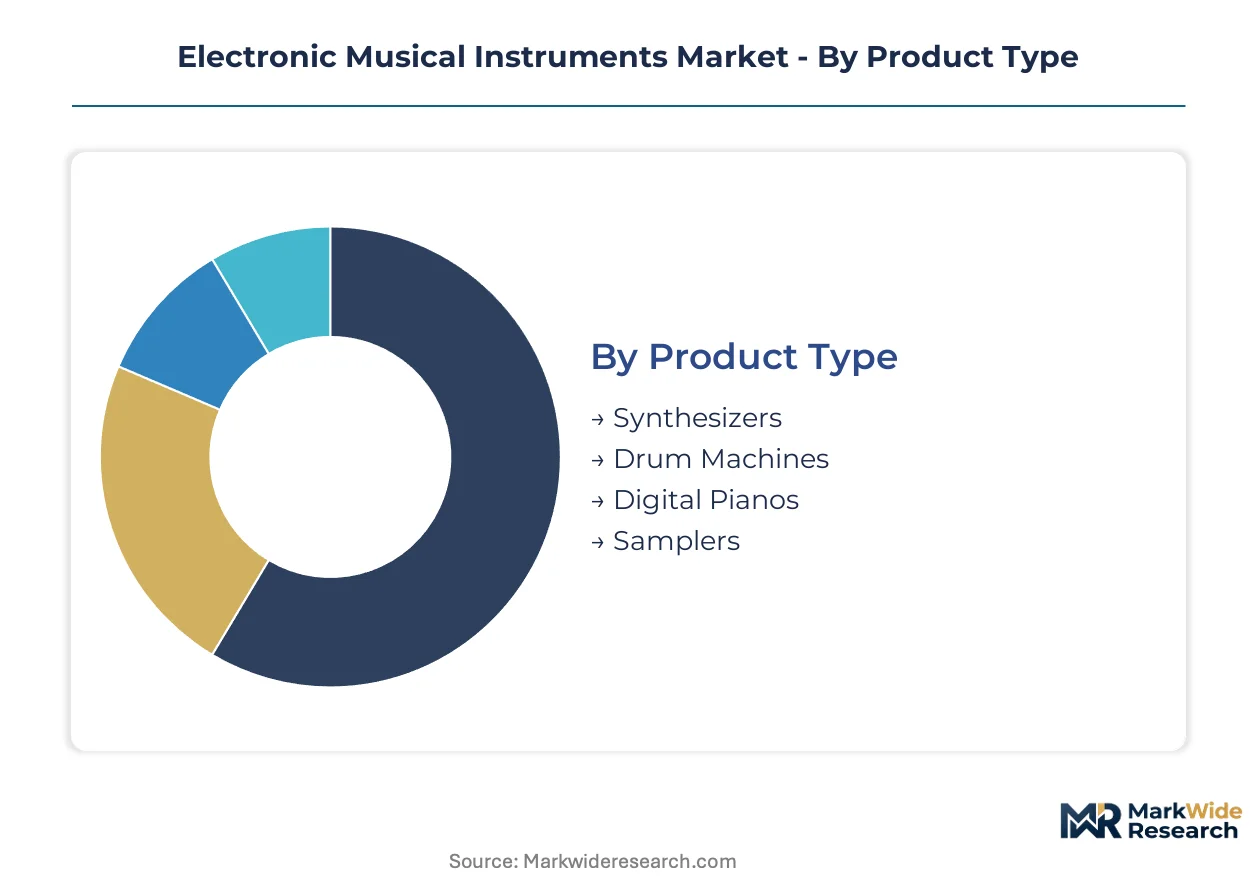
Segmentation in electronic musical instruments determines which compliance pathways manufacturers must navigate. FCC certification for wireless-enabled products, EU REACH substance restrictions, and China's MIIT type-approval create divergent qualification burdens across product categories and end-use applications.
Product Type:
FCC electromagnetic emissions testing applies most stringently to wireless-enabled synthesizers and samplers, while digital pianos with basic I/O face lighter certification loads. REACH and RoHS substance tracking affects all categories but concentrates in modular synthesizers with complex PCB assemblies.
- Synthesizers:Voltage-controlled oscillators, digital signal processors, and firmware-controlled modulation matrices generate tones across 20 Hz to 20 kHz with 16- to 24-bit resolution. Professional studios in the United States are expanding purchases of hybrid analog-digital workstations, though semiconductor supply concentration in Taiwan and South Korea creates input volatility for proprietary chip architectures.
- Digital Pianos:Weighted hammer-action keybeds with sampled acoustic piano libraries and integrated amplification systems. Educational institutions in India and the United States are consolidating procurement through multi-year fleet agreements, displacing transactional retail purchases in K-12 segments.
- Drum Machines:Sequenced percussion synthesis with pattern storage and MIDI synchronization capabilities.
- Samplers:Digital audio recording and playback engines with time-stretching and pitch-shifting algorithms.
Digital pianos sit at the top of the volume ranking, with synthesizers climbing the fastest.
End User:
Cost tier stratification separates professional-grade equipment with premium pricing from entry-level instruments competing on distribution footprint. Certification and feature depth scale directly with target customer investment capacity.
- Professional Musicians:Touring and studio artists requiring road-worthy construction, low-latency performance, and deep parameter control. Demand concentrates in hybrid analog-digital architectures with cloud-connected firmware ecosystems.
- Music Producers:Project studio operators integrating hardware with DAW workflows through audio interfaces and control surfaces. Home-based production setups are expanding demand for compact workstations with integrated connectivity.
- Hobbyists:Entry-level players purchasing through mass retail and direct-to-consumer channels.
- Educational Institutions:K-12 districts and universities negotiating enterprise procurement terms with bundled curriculum software and instructor certification.
Educational institutions anchor volume procurement, while music producers are gaining share fastest through project studio proliferation.
Technology:
Application context determines which technology platforms dominate—live performance favors stability and immediacy, while studio recording prioritizes sonic flexibility and integration depth.
- Hybrid:Combined analog signal paths with digital control and preset storage, bridging voltage-controlled oscillator warmth with firmware recall. Professional studios in the United States are driving demand for hybrid workstations, though analog circuit engineering scarcity among retiring European and Japanese technicians constrains supply.
- Digital:Fully solid-state tone generation through DSP algorithms and wavetable synthesis. China's domestic manufacturers are upgrading from OEM assembly to branded digital instrument design, enabled by MIIT type-approval processes and GB standards compliance.
- Analog:Discrete component circuits with voltage-controlled oscillators, filters, and amplifiers.
- Software:Computer-based instruments operating as plugins within DAW environments.
Digital technology holds the volume base, with hybrid architectures showing the steepest expansion trajectory.
Application:
Margin structure varies sharply by use case—sound design commands premium pricing for specialized tools, while music education operates on compressed margins through institutional procurement concentration.
- Studio Recording:Multi-track production environments requiring pristine audio conversion, extensive I/O, and seamless DAW integration. Software-based instruments are displacing hardware samplers in project studio configurations below five hundred dollars.
- Live Performance:Stage-ready instruments prioritizing durability, immediate playability, and reliable MIDI synchronization. Spatial audio convergence with ambisonic encoding engines is opening theatrical and immersive installation applications.
- Music Education:Classroom and individual instruction settings with simplified interfaces and curriculum alignment.
- Sound Design:Specialized timbre creation for film, game, and multimedia scoring.
Studio recording leads by revenue contribution, with sound design expanding most quickly through generative algorithm adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese analog circuit engineers and German precision manufacturing technicians anchor the industry's geographic talent base, with these specialized workforces concentrated in legacy industrial clusters around Hamamatsu and Nuremberg.
United States
Professional studios in Los Angeles and Nashville are expanding purchases of hybrid analog-digital workstations. FCC certification requirements govern electromagnetic emissions from wireless-enabled instruments, extending product launch timelines. Austin's technology corridor hosts emerging direct-to-artist distribution platforms for boutique modular components.
China
Domestic manufacturers are upgrading from OEM assembly to branded instrument design for domestic and export markets. MIIT type-approval processes and GB standards compliance enable this transition. Shenzhen and Guangzhou clusters concentrate production of digital pianos and entry-level synthesizers serving educational procurement pipelines.
Japan
Specialized talent for discrete component voicing and voltage-controlled oscillator calibration remains concentrated among aging technicians in Hamamatsu. METI industrial policy supports precision manufacturing heritage. Tokyo and Osaka anchor R&D for proprietary semiconductor architectures in professional-tier instruments.
Germany
EU REACH and RoHS substance restrictions on circuit assemblies are accelerating supplier consolidation among manufacturers serving European markets. ECHA compliance frameworks filter supplier bases for brands distributing across the continent. Nuremberg and Berlin clusters specialize in boutique modular synthesizer design and limited-run analog circuits.
India
CBSE and state board curriculum mandates for music education are creating procurement pipelines for digital pianos and classroom keyboard labs. BIS standards govern electronic product safety for domestic distribution. Mumbai and Bangalore tier-two cities concentrate institutional purchasing through multi-year fleet agreements.
Electronic Musical Instruments Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the electronic musical instruments sector. Foundry-dependent manufacturers with captive semiconductor partnerships absorb compliance costs more efficiently than assembly-reliant competitors. Three archetypes dominate: vertically integrated heritage brands with proprietary chip architectures, modular specialists focused on boutique analog circuits, and scale-driven OEMs serving educational procurement channels. Strategic moves concentrate on backward integration into semiconductor sourcing and direct-to-artist distribution bypassing traditional retail.
Within the heritage integrated tier, Yamaha Corporation exemplifies the foundry-partnership model, while Roland Corporation occupies a position bridging professional studio and live performance applications. Among China-based OEMs transitioning to branded design, Guangzhou Pearl River Piano Group Co., Ltd. and Medeli Electronics (Shanghai) Co., Ltd. represent the scale-driven educational procurement archetype.
| Leading Market Players |
|---|
| Gibson Brands |
| Guangzhou Pearl River Piano Group Co., Ltd. |
| Yamaha |
| Beijing Hsinghai Piano Group Limited |
| Medeli Electronics (Shanghai) Co., Ltd. |
| Roland |
| Fender Musical Instruments Corporation |
| Shanghai Huaxin Musical Instrument Co., Ltd. |
| KORG |
| Others |
Supply Flow & Price Mechanics
Copper and rare earth element price indices cascade through PCB fabrication and magnet production costs, compressing margins at the entry tier while premium synthesizer manufacturers absorb volatility through captive semiconductor partnerships and multi-year component offtake agreements.
Pricing Analysis
Bundled hardware-software subscriptions versus unbundled transactional hardware sales split the pricing architecture across customer tiers. Three-tier pricing structure across premium, standard, and economy levels separates road-worthy hybrid workstations from classroom digital pianos and entry-level grooveboxes. Price differentiation hinges on certification grade—FCC and CE marking tiers add four to eight months to launch timelines—and after-sales service bundling through multi-year fleet agreements. Cost compression in the sub-five-hundred-dollar tier intensifies because software instrument substitution from Native Instruments and Ableton plugin ecosystems erodes hardware sampler viability. Educational institutions exhibit highest price sensitivity through centralized procurement offices, while professional studios demonstrate lowest sensitivity when sourcing hybrid analog-digital architectures.
Supply Chain Analysis
Container freight rates from Taiwan and South Korea to Los Angeles and Rotterdam directly impact landed costs for semiconductor-dependent manufacturers. Foundry capacity concentrates in Taiwan and South Korea, with Japan anchoring precision analog component fabrication. Proprietary DSP chip architectures draw from silicon wafer supplies, lead-free solder formulations under EU REACH restrictions, and halogenated flame retardant alternatives. Single-source vulnerability sits with Taiwan Semiconductor Manufacturing capacity allocation for synthesizer-grade audio converters. Distribution runs through direct-to-artist social commerce platforms for boutique modular components and enterprise fleet agreements for educational procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU REACH substance restrictions and RoHS solder formulation mandates are accelerating supplier consolidation and favoring manufacturers with certified green component pipelines.
For Market Incumbents: Anchor hybrid analog-digital workstation positioning through backward integration into semiconductor sourcing partnerships that buffer Taiwan foundry volatility. Deepen certification investment across FCC, CE marking, and MIIT type-approval tracks to extend product launch timelines as competitive moats. Defend against software instrument substitution by expanding firmware subscription attach rates and expansion module ecosystems that lock professional studio customers into proprietary architectures.
For New Entrants and Emerging Players: Capture India's institutional education procurement pipelines where CBSE and state board curriculum mandates for music education concentrate demand in tier-two cities. Exploit direct-to-artist distribution bypassing traditional retail channels through social commerce platforms and artist-owned storefronts for limited-run modular components. White-space opportunity sits with spatial audio convergence integrating ambisonic encoding engines into theatrical and immersive installation applications underserved by heritage brands.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated heritage brands possessing captive semiconductor partnerships and proprietary chip architectures that absorb EU Green Deal compliance costs more efficiently than assembly-dependent competitors. Long-term viability across the projection horizon favors manufacturers with backward integration into foundry relationships and certified green component pipelines. Acquisition target archetype: boutique modular specialists with aging European and Japanese analog circuit engineering talent. Signal to watch: divergence between regional electromagnetic compatibility standards as firmware update cycles compress and connected instruments proliferate.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Partnership | Secures foundry allocation from TSMC and Samsung Foundry for proprietary DSP architectures. |
| EU REACH Compliance Certification | Enables market access under ECHA substance restrictions on lead-free solder and flame retardants. |
| Direct-to-Artist Distribution Platform | Bypasses traditional retail through social commerce and artist-owned storefronts for boutique components. |
| Spatial Audio Engine Integration | Opens theatrical and immersive installation applications through ambisonic encoding convergence. |
| Educational Fleet Procurement Agreement | Locks multi-year revenue through bundled instruments, curriculum software, and instructor certification. |
Methodological Framework
Coverage spans the United States, China, Japan, Germany, and India, with primary inputs from each market cluster combining interviews with product development executives at heritage brands, procurement directors at educational institutions, analog circuit engineering specialists, and distribution channel partners. Secondary validation draws from FCC equipment authorization databases, ECHA REACH registration dossiers, MIIT type-approval filings, and customs trade records for electronic musical instrument components. Bottom-up and top-down triangulation cross-references manufacturer shipment data with end-user procurement patterns across studio, educational, and live performance segments.
Granularity-level modeling operates at the intersection of product type, technology architecture, end-user segment, and application context, with hybrid analog-digital systems receiving discrete parameterization. Value and volume trajectories across the analysis window derive from segment-specific CAGRs weighted by semiconductor input cost elasticity and regulatory compliance burden differentials. Industry-specific forecast inputs include foundry capacity utilization rates from Taiwan and South Korea, EU REACH substance restriction phase-in schedules, and CBSE curriculum mandate implementation timelines for music education procurement.
Underlying measurement precision varies by segment; synthesizers and hybrid workstations carry tighter precision than entry-level digital pianos and drum machines due to concentrated manufacturer reporting and professional studio purchasing transparency. Forecasts reflect assumptions regarding sustained foundry capacity allocation, stable regulatory enforcement trajectories, and continued software instrument substitution pressure in sub-premium tiers. Stakeholders should weight assumptions against their own operating context, particularly semiconductor sourcing exposure and geographic certification burden.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Musical Instruments
Woodwind Instruments Market
Musical Instruments
Digital Ensemble Pianos Market
Musical Instruments
Electric Violin Market
Musical Instruments
Classical Guitar Market
Musical Instruments
Drum Sets Market
Musical Instruments
Violin Market
Musical Instruments
Bass Guitar Market
Musical Instruments
Guitar Market
Musical Instruments
Smart Musical Instrument Market
Musical Instruments
Electric Guitar Market
Musical Instruments
Kids Musical Instrument Market
Musical Instruments
Global Piano Market
Musical Instruments
Digital Piano Market