
 Cutter Staplers Market | 2026-2036
Cutter Staplers Market Size, Share, and Industry Trends Forecast 2026-2036
Cutter Staplers Market Outlook
Ambulatory surgical centers are redrawing procurement patterns for cutter staplers as outpatient volumes shift away from inpatient settings. Medtronic leverages its broad laparoscopic portfolio to sustain institutional contracts across North American hospital networks. Johnson & Johnson anchors its position through Ethicon's stapling franchise, which dominates open and minimally invasive procedure segments. B. Braun competes in the European market with specialized articulating devices for bariatric and thoracic applications.
Cutter staplers are mechanical devices that simultaneously transect tissue and apply staggered rows of metallic staples to create hemostatic closures, typically constructed from surgical-grade stainless steel with titanium or polymer staple cartridges designed for single-patient use. Electric and pneumatic variants now lead hospital procurement as facilities prioritize ergonomic firing mechanisms and consistent staple formation across variable tissue thicknesses. The manual segment retains share in cost-constrained settings, while heavy-duty configurations command premium positioning in bariatric surgery where tissue loads exceed standard parameters. Composite material innovations in staple line reinforcement are reshaping product differentiation as manufacturers seek reduced anastomotic leak rates.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and market access requirements for cutter stapler manufacturers. ISO 13485 quality management systems and ASTM International material standards govern manufacturing consistency across production facilities. Stakeholders must monitor evolving reimbursement codes for outpatient stapling procedures and anticipate how FDA guidance on reprocessed single-use devices will influence disposable versus reusable portfolio investments.
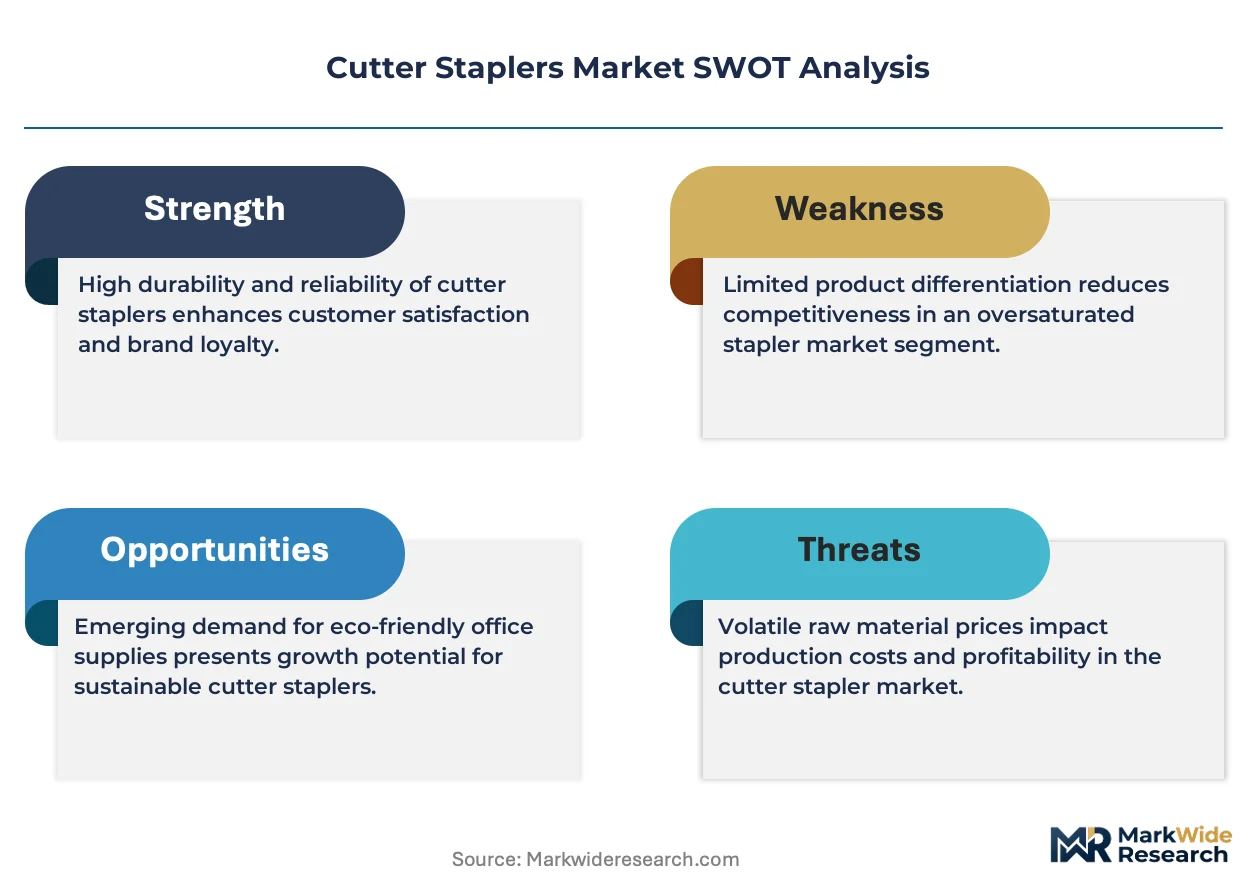
Market Dynamics
Disposable cutter stapler systems are displacing reusable alternatives as ambulatory surgical centers scale outpatient procedures and FDA tightens validation protocols for reprocessed devices.
Growth Catalysts
- Outpatient Migration:Ambulatory surgical centers in the United States are expanding surgical volumes as payers steer reimbursable procedures away from inpatient settings, accelerating single-use device procurement.
- EU MDR Compliance:The European Union's Medical Device Regulation imposes stricter conformity assessment requirements for reusable stapler reprocessing, tilting procurement toward validated disposable systems.
- Minimally Invasive Surgery:Laparoscopic and robotic platforms are broadening the addressable procedure base for cutter staplers across bariatric, thoracic, and colorectal applications.
Market Restraints
- Titanium Price Volatility:Surgical-grade titanium staple raw material costs fluctuate with aerospace and defense demand cycles, compressing margin predictability for cartridge manufacturers.
- Supply Concentration:Surgical-grade stainless steel sourcing concentrates in German and Chinese metallurgical facilities, exposing device assemblers to regional production disruptions.
- Reusable Device Persistence:Cost-constrained hospital systems in emerging markets continue deploying reprocessed staplers, delaying full conversion to premium disposable platforms.
Strategic Opportunities
- India Surgical Infrastructure:Government hospital modernization under the Ayushman Bharat scheme is expanding operating theater capacity in tier-2 and tier-3 cities, creating first-time demand for standardized stapling systems.
- Staple Line Reinforcement:Composite buttressing materials integrated with polymer cartridges are demonstrating measurable leak-rate reductions in bariatric anastomoses, commanding premium positioning.
- Direct-to-Facility Distribution:Manufacturers are bypassing traditional distributor networks to contract directly with multi-hospital systems, capturing margin and tightening utilization data feedback loops.
Industry Challenges
- Biocompatibility Certification:ISO 10993 testing timelines for novel polymer staple materials extend product development cycles by 18-24 months, delaying market entry against incumbent titanium platforms.
- Reprocessing Liability:Hospitals face escalating malpractice exposure from surgical site infections linked to inadequately sterilized reusable staplers, complicating capital equipment retention decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutter Staplers Market |
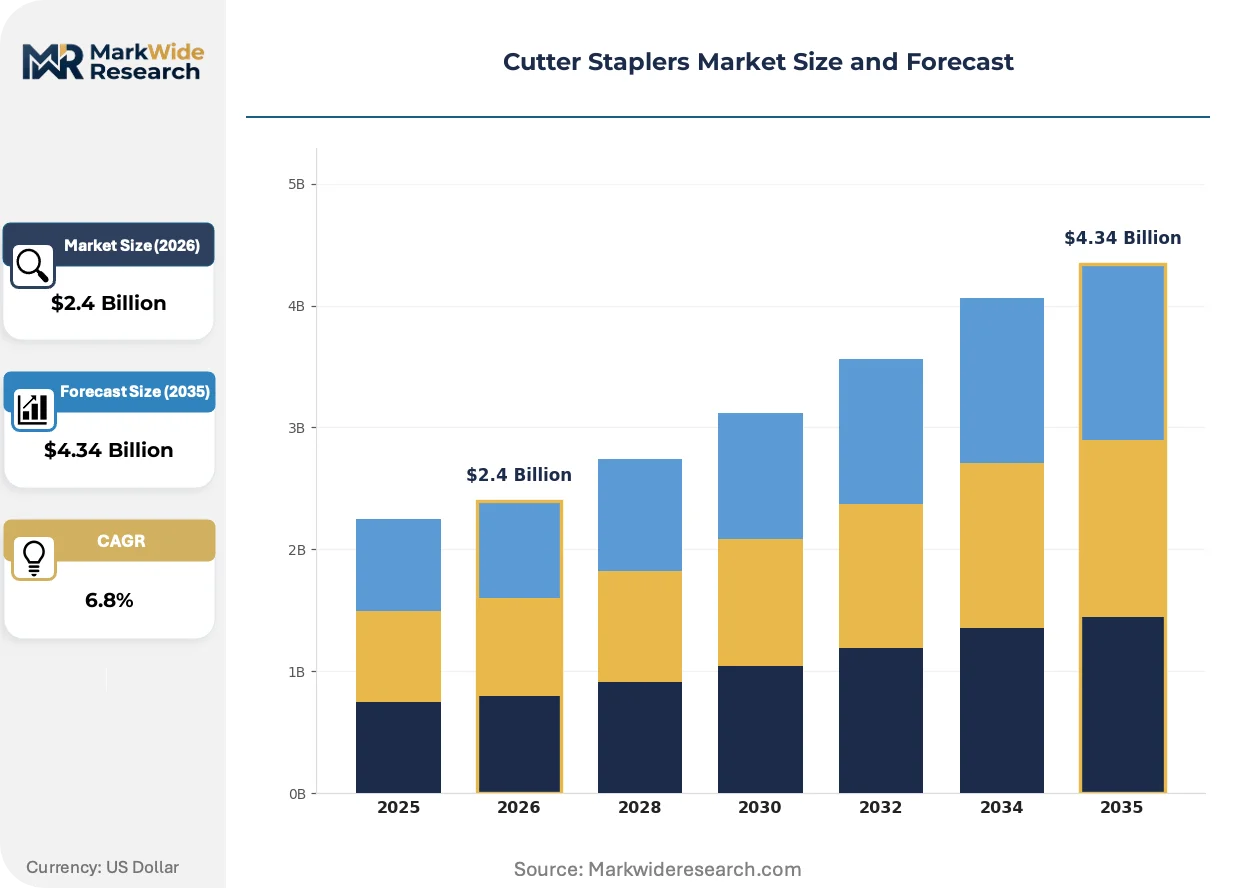
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Pneumatic, Heavy-Duty Application: Office Use, Educational, Industrial, Home End User: Businesses, Schools, Manufacturers, Home Users Material: Plastic, Metal, Composite, Recycled |
| Companies Covered | Medtronic, Johnson & Johnson, B. Braun, Intuitive Surgical, Purple Surgical, Lepu Medical, Victor Medical Instruments, Meril Life Sciences, Frankenman International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutter Staplers Market Strategic Shifts
Electromechanical firing mechanisms and intelligent tissue-sensing algorithms are redefining performance benchmarks across surgical stapling platforms.
Battery-powered electric staplers are supplanting manual and pneumatic alternatives in high-volume hospital networks. United States academic medical centers are prioritizing these devices for ergonomic consistency and reduced operator fatigue during lengthy laparoscopic cases. The technology is compressing training curves for surgical residents while standardizing staple formation across variable tissue thicknesses.
EU MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up data collection for implantable stapling components. Manufacturers must now maintain active registries tracking anastomotic leak rates and device malfunctions. Thoracic surgery applications face the steepest compliance burden given the criticality of staple line integrity in pulmonary resections.
Chinese hospitals are consolidating purchasing authority through provincial procurement consortia, displacing fragmented department-level buying. Multi-hospital systems in Jiangsu and Guangdong provinces now negotiate centralized contracts for laparoscopic instrument suites. This concentration is compressing price realization for premium-tier staplers while elevating volume commitments for suppliers.
Cutter Staplers Market Segmentation
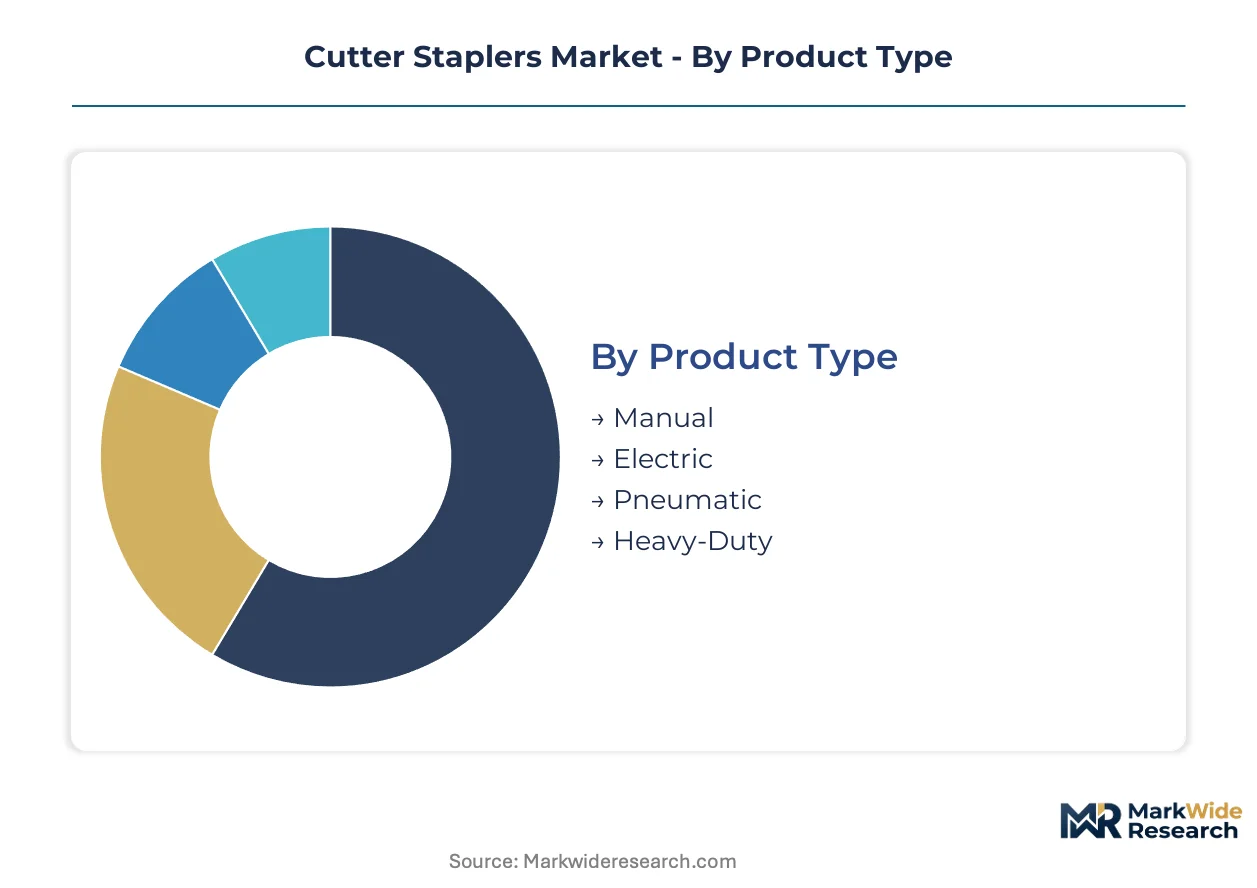
Cutter stapler segmentation reveals distinct substitution dynamics across mechanical, electromechanical, and pneumatic platforms. Procurement patterns diverge sharply between inpatient surgical networks and ambulatory settings, with material composition and firing mechanism driving portfolio investment decisions.
Product Type:
Electric and pneumatic variants face intensifying substitution pressure from manual alternatives in cost-constrained procurement environments, while heavy-duty configurations defend position through irreplaceable performance in bariatric applications.
- Manual:Spring-loaded mechanical firing systems constructed from surgical-grade stainless steel housings with disposable titanium staple cartridges. Demand concentrates in Indian tier-2 and tier-3 hospitals under Ayushman Bharat modernization, where capital equipment budgets prioritize reliability over ergonomic features.
- Electric:Battery-powered electromechanical platforms incorporating intelligent tissue-sensing algorithms and standardized firing force across variable tissue thicknesses. United States academic medical centers are prioritizing these devices for reduced operator fatigue during extended laparoscopic procedures.
- Pneumatic:Compressed-gas actuated systems delivering consistent staple formation through regulated pressure delivery. German thoracic surgery suites specify these platforms for pulmonary resection reliability under EU MDR surveillance mandates.
- Heavy-Duty:Reinforced firing mechanisms engineered for tissue loads exceeding standard stapler parameters in bariatric and metabolic surgery applications.
Manual staplers anchor the volume base while electric platforms gain share at the steepest rate across high-volume hospital networks.
Application:
Application segmentation tracks procedure migration from inpatient to ambulatory settings, with office-based interventions representing the most contested expansion frontier.
- Office Use:Compact stapler configurations optimized for outpatient dermatologic and minor surgical procedures. Chinese provincial procurement consortia in Jiangsu and Guangdong are consolidating purchasing authority for these systems.
- Educational:Training-grade staplers with visible firing mechanisms and reduced staple counts for surgical resident instruction. United States residency programs specify these for laparoscopic skills laboratories.
- Industrial:Non-medical heavy-duty stapling systems for manufacturing and packaging applications with distinct regulatory pathways from surgical devices.
- Home:Consumer-grade stapling equipment for domestic document and craft applications outside medical device classification.
Educational applications anchor institutional procurement volumes while office use climbs fastest as ambulatory surgical centers expand service lines.
End User:
End user concentration reflects diverging procurement authority between consolidated hospital systems and fragmented individual purchasers.
- Businesses:Corporate procurement of industrial stapling systems for logistics and document management operations.
- Schools:Educational institutions acquiring training devices for vocational and medical technology programs.
- Manufacturers:Original equipment manufacturers integrating stapler subsystems into surgical instrument platforms under ISO 13485 quality management.
- Home Users:Individual consumers purchasing retail-grade stapling equipment through distributor and direct-to-consumer channels.
Manufacturers dominate upstream component demand while businesses drive the steepest expansion in industrial applications.
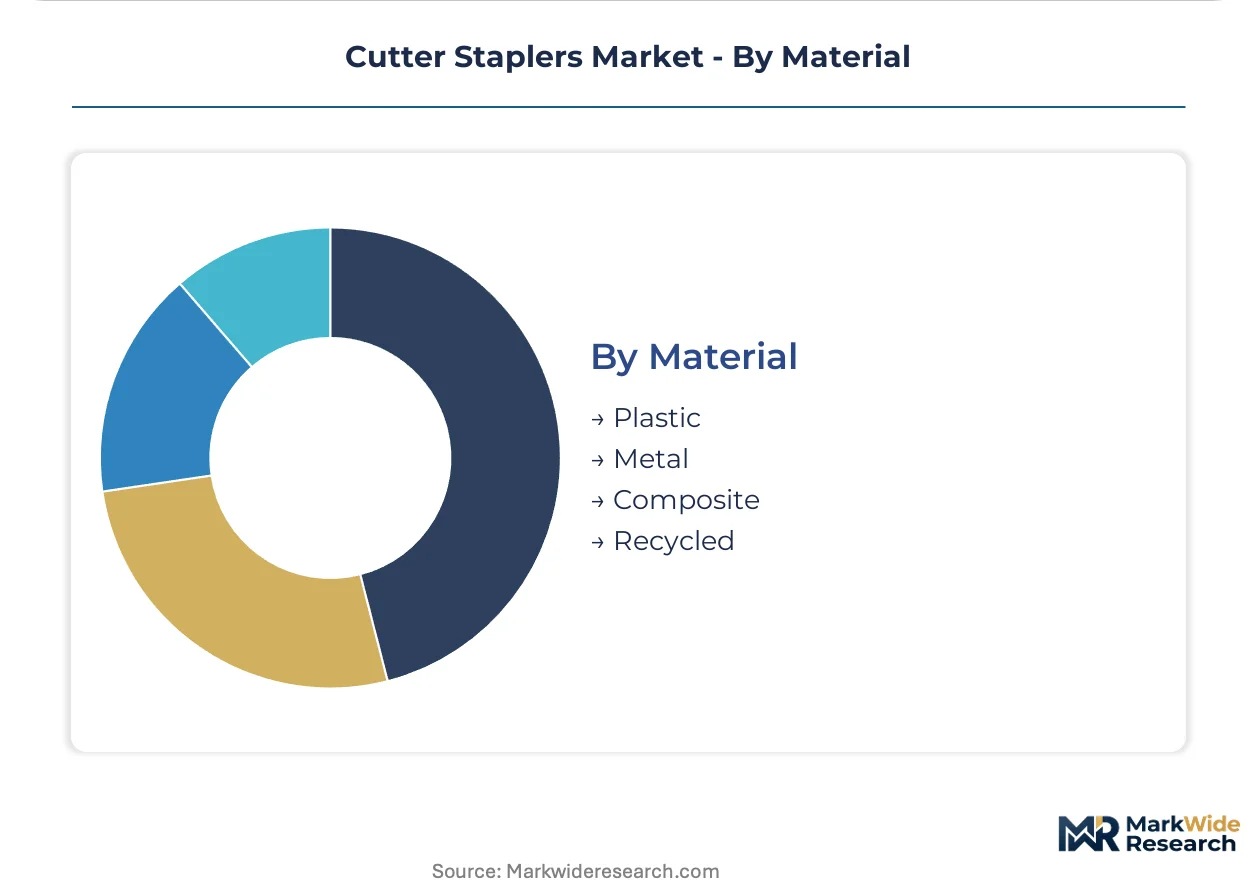
Material:
Material selection governs biocompatibility certification timelines and supply chain exposure to metallurgical concentration risks.
- Plastic:Polymer housings and cartridge components reducing device weight and manufacturing cost. FDA 510(k) clearance pathways accommodate these materials with streamlined biocompatibility testing under ISO 10993.
- Metal:Surgical-grade stainless steel and titanium staple formations. German and Chinese metallurgical facilities concentrate sourcing, exposing assemblers to regional production disruptions.
- Composite:Reinforced polymer matrices with integrated staple line buttressing materials. EU MDR Article 10 post-market surveillance requirements mandate systematic clinical follow-up for these implantable configurations.
- Recycled:Post-consumer and post-industrial material incorporation in non-critical housing components.
Metal constructions anchor surgical-grade demand while composite materials expand most quickly through premium positioning in leak-rate reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export surgical-grade stainless steel components to United States hospital networks and Chinese assembly facilities, establishing the primary trade corridor for cutter stapler raw materials.
United States
Ambulatory surgical centers in Texas and Florida are expanding outpatient bariatric volumes as Medicare reimbursement shifts favor same-day procedures. FDA 510(k) clearance pathways require systematic biocompatibility documentation for titanium staple cartridges. The Minneapolis-St. Paul corridor anchors Medtronic's institutional contract negotiations with multi-hospital systems.
Germany
Thoracic surgery suites in Bavaria specify pneumatic stapling platforms for pulmonary resection reliability under EU MDR surveillance mandates. ECHA chemical safety assessments govern polymer cartridge material registrations across the single market. The Tuttlingen surgical instrument cluster concentrates precision metalworking capacity for European device assemblers.
China
Provincial procurement consortia in Jiangsu and Guangdong are consolidating purchasing authority for laparoscopic instrument suites. NMPA registration requirements now mandate domestic clinical trial data for imported stapling systems. The Yangtze River Delta manufacturing belt hosts assembly operations serving both domestic hospital networks and Southeast Asian export markets.
India
Ayushman Bharat hospital modernization is expanding operating theater capacity in tier-2 cities across Maharashtra and Karnataka. CDSCO medical device rules impose quality management system requirements on imported stapler cartridges. The Mumbai-Pune pharmaceutical corridor is diversifying into surgical device distribution infrastructure.
Japan
Academic medical centers in Tokyo and Osaka are prioritizing electromechanical staplers for robotic-assisted surgery integration. PMDA pharmaceutical and medical device agency reviews emphasize post-market surveillance data for implantable staple components. The Chubu region around Nagoya maintains precision machining capabilities for surgical instrument subassemblies.
Cutter Staplers Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and regulatory navigation capabilities. The vendor base concentrates around three tiers: diversified medical technology conglomerates with institutional contract scale, regional specialists with procedure-specific articulating devices, and emerging Asian manufacturers with cost-optimized disposable platforms. Strategic moves center on direct-to-facility distribution bypassing traditional intermediaries, and composite material integration for staple line reinforcement commanding premium positioning.
Within the diversified conglomerate tier, Medtronic plc and Johnson & Johnson occupy positions defined by broad laparoscopic portfolio breadth and Ethicon stapling franchise heritage respectively. B. Braun Melsungen AG exemplifies the European specialist archetype with focused articulating device development. Among Asia-Pacific entrants, Lepu Medical Technology (Beijing) Co., Ltd. and Meril Life Sciences Pvt. Ltd. represent private manufacturers scaling disposable platform production for cost-sensitive procurement environments. Victor Medical Instruments Co., Ltd. anchors Chinese domestic supply capabilities. Purple Surgical S.L. and Frankenman International Ltd. occupy mid-tier positions bridging regional specialization with selective geographic expansion.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| B. Braun |
| Intuitive Surgical |
| Purple Surgical |
| Lepu Medical |
| Victor Medical Instruments |
| Meril Life Sciences |
| Frankenman International |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for titanium staple cartridges signal how German and Chinese metallurgical concentration translates directly into pricing leverage for device assemblers. Buyers face asymmetric cost pass-through when aerospace demand spikes absorb surgical-grade titanium supply, compressing margin buffers across disposable platform portfolios.
Pricing Analysis
Electric-to-manual pricing gaps of roughly three-to-one separate current-generation electromechanical platforms from prior-generation spring-loaded alternatives, with next-generation intelligent tissue-sensing devices commanding additional premiums. Three-tier pricing structure across premium, standard, and economy levels organizes procurement: premium tiers bundle ergonomic firing mechanisms with composite buttressing materials, standard tiers target high-volume hospital networks with validated disposable cartridges, and economy tiers serve cost-constrained Indian tier-2 facilities under Ayushman Bharat modernization. Cost compression in the economy tier is intensifying because provincial Chinese procurement consortia consolidate purchasing authority and extract volume discounts. Ambulatory surgical centers in the United States exhibit lowest price sensitivity due to reimbursement favorability, while Indian government hospitals demonstrate highest sensitivity given fixed capital equipment budgets.
Supply Chain Analysis
German stainless steel export licensing to United States hospital networks constitutes a chokepoint that can disrupt cartridge assembly timelines when ECHA chemical safety assessments delay polymer registrations. Surgical-grade titanium draws from German metallurgical facilities, Chinese Yangtze River Delta processing centers, and limited Japanese specialty alloy producers. Raw material dependencies center on aerospace-grade titanium sponge, surgical stainless steel bar stock, and medical-grade polymer resins. Single-source vulnerability concentrates in Tuttlingen precision metalworking capacity for European device assemblers. Distribution runs through regional surgical instrument distributors in mature markets, while direct-to-facility contracts are displacing traditional intermediaries in consolidated United States hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable cutter stapler incumbents face substitution defense imperatives as reusable device reprocessing technologies advance and FDA validation protocols tighten. Suture-based anastomosis techniques and emerging energy-sealing platforms threaten premium positioning in select procedure categories.
For Market Incumbents: Consolidate institutional contract scale through multi-hospital system direct purchasing agreements that capture utilization data and tighten replenishment loops. Anchor backward integration into polymer cartridge manufacturing to defend margin position against titanium price volatility. Prioritize EU MDR Article 10 compliance infrastructure to sustain market access as surveillance requirements intensify for implantable staple components.
For New Entrants and Emerging Players: Lead with cost-optimized manual platforms targeting Indian tier-2 and tier-3 cities where Ayushman Bharat theater expansion creates first-time demand absent entrenched supplier relationships. Penetrate the educational segment through visible-firing training devices for United States residency programs, where procurement cycles are shorter and brand loyalty is unformed. Pursue provincial procurement consortium qualification in Jiangsu and Guangdong as the fastest channel to volume scale.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core stapling franchises amid portfolio rationalization. Long-term viability hinges on electromechanical platform transition completion and composite material integration capabilities. Monitor FDA guidance trajectory on reprocessed single-use devices as the critical inflection signal for disposable versus reusable portfolio valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment unlocks access to Bavarian thoracic surgery suites and German hospital networks. |
| Hospital System Partnership | Direct contracting with Texas and Florida ambulatory surgical centers secures outpatient bariatric volume commitments. |
| Software Companion Development | Intelligent tissue-sensing algorithms differentiate electromechanical platforms in United States academic medical centers. |
| Reimbursement Strategy | Medicare same-day procedure codes determine procurement authority for outpatient stapling systems. |
| Backward Integration | In-house polymer cartridge production insulates margin from titanium price volatility and supply concentration. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and ambulatory surgical center administrators. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement code filings, and provincial Chinese procurement consortium award records. Bottom-up procedure volume estimates were triangulated against top-down manufacturer shipment data to anchor market sizing.
Across the analysis window, projections incorporate product type substitution dynamics, application migration from inpatient to ambulatory settings, and end-user consolidation patterns. Segmentation dimensions modeled include firing mechanism technology, procedure category, material composition, and geographic procurement authority concentration. CAGRs were derived from procedure volume elasticity to demographic trends and surgical platform adoption curves. Forecast inputs specifically incorporate EU MDR compliance cost burdens and Chinese provincial procurement centralization timelines.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR surveillance regimes; material policy shifts would require re-modeling. Scenario risks include titanium price spike persistence beyond aerospace demand cycles and NMPA domestic clinical trial mandates that delay imported system registrations. Practitioners should keep alternative scenarios live as reimbursement code evolution and reprocessing liability litigation develop.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Global Office Peripherals and Products Market
Office Supplies
Perforated File Market
Office Supplies
Custom Binders Market
Office Supplies
Europe School Stationery Supplies Market
Office Supplies
Copiers Market
Office Supplies
Malaysia Stationery Market
Office Supplies
Thumb Hole Book Page Holder Market
Office Supplies
Stationery Market
Office Supplies
Diaries & Planners Market
Office Supplies
Marker Pens Market
Office Supplies
Greetings Cards Market
Office Supplies
Writing and Marking Instruments Market
Office Supplies
Acrylic Marker Pen Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
Dictionary Pen Market
Office Supplies
Flash Cards and USB Flash Drives Market