
 Business Card Holder Market | 2026-2036
Business Card Holder Market Size, Share, and Industry Trends Forecast 2026-2036
Business Card Holder Market Outlook
Subscription-based personalization services for engraved metal and leather holders is realigning how brands monetize repeat engagement. Montblanc leverages its heritage craftsmanship to command premium positioning in direct-to-consumer channels. Samsonite anchors its portfolio through corporate bulk procurement relationships with Fortune 500 accounts. Secrid differentiates via patented card-protection mechanisms that justify sustained price premiums across European markets.
A business card holder is a rigid or semi-rigid container engineered to store, display, and protect standard-format business cards, typically constructed from leather, metal, plastic, or fabric substrates with dimensions conforming to ISO 7810 ID-1 specifications. Leather variants dominate value pools due to perceived durability and executive gifting associations, while metal constructions are capturing fastest growth through minimalist design trends and RFID-blocking integration. Slim and mini size configurations are expanding share as pocket-carry preferences shift toward reduced bulk, and promotional design segments serve event marketing and hospitality verticals with high volume turnover but compressed margins.
REACH in the European Union restricts chromium VI and certain azo dyes in leather tanning, while FDA guidelines in the United States govern plastic contact materials for food-adjacent promotional distributions. China's GB standards and SAMR oversight enforce heavy-metal limits in metal alloy components used for domestic and export production. Stakeholders must monitor regulatory divergence across these jurisdictions to preempt supply chain disruption and align material certification with destination-market requirements.
Market Dynamics
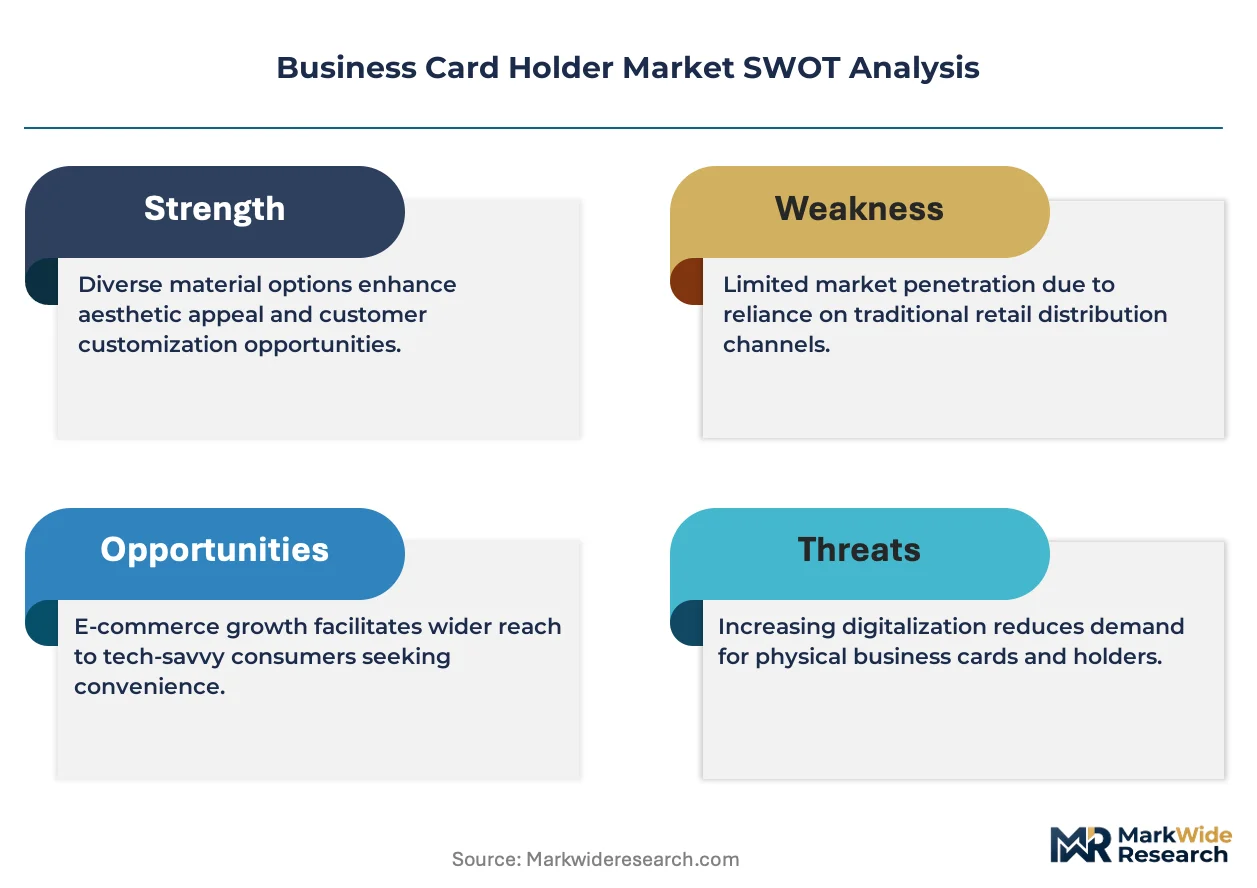
REACH compliance in the European Union is forcing wholesale material substitution across leather tanning and metal alloy sourcing, compressing supplier margins while elevating certified producers. Corporate gifting programs at professional services firms sustain volume demand even as individual purchasing softens.
Growth Catalysts
- REACH Phase-Out Mandates:Chromium VI restrictions in EU leather tanning are accelerating certified vegetable-tanned leather adoption among premium manufacturers seeking regulatory insulation.
- RFID-Blocking Integration:Contactless payment security concerns are driving metal holder designs with embedded Faraday shielding into executive procurement specifications.
- China Manufacturing Clusters:Guangdong and Zhejiang production agglomerations deliver cost-competitive metal stamping and leather finishing at scale for export markets.
Market Restraints
- Chrome Tanning Input Volatility:Chromium sulfate price swings and REACH substitution timelines compress margin predictability for mid-tier leather producers.
- Single-Source Metal Alloy Dependence:Concentrated stainless steel supply from specific Chinese mill clusters creates vulnerability to SAMR environmental enforcement actions.
- Digital Contact Substitution:LinkedIn and NFC-enabled smartphone exchange protocols erode physical card necessity among technology sector professionals.
Strategic Opportunities
- Subscription Personalization Services:Engraved metal and leather holder membership models create recurring revenue streams beyond one-time gifting cycles.
- EU Green Deal Alignment:Bio-based polyurethane and mycelium leather alternatives qualify for public procurement preferences and CSRD reporting benefits.
- Event Hospitality Vertical:Promotional design segments serve trade show and hotel concierge applications with high volume turnover and brand exposure value.
Industry Challenges
- Multi-Jurisdiction Certification Complexity:Simultaneous REACH, FDA, and GB standard compliance requires parallel testing protocols and extended product development timelines.
- Leather Craftsmanship Talent Scarcity:Hand-finishing expertise attrition in Italian and French ateliers limits capacity expansion for heritage-positioned brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Card Holder Market |
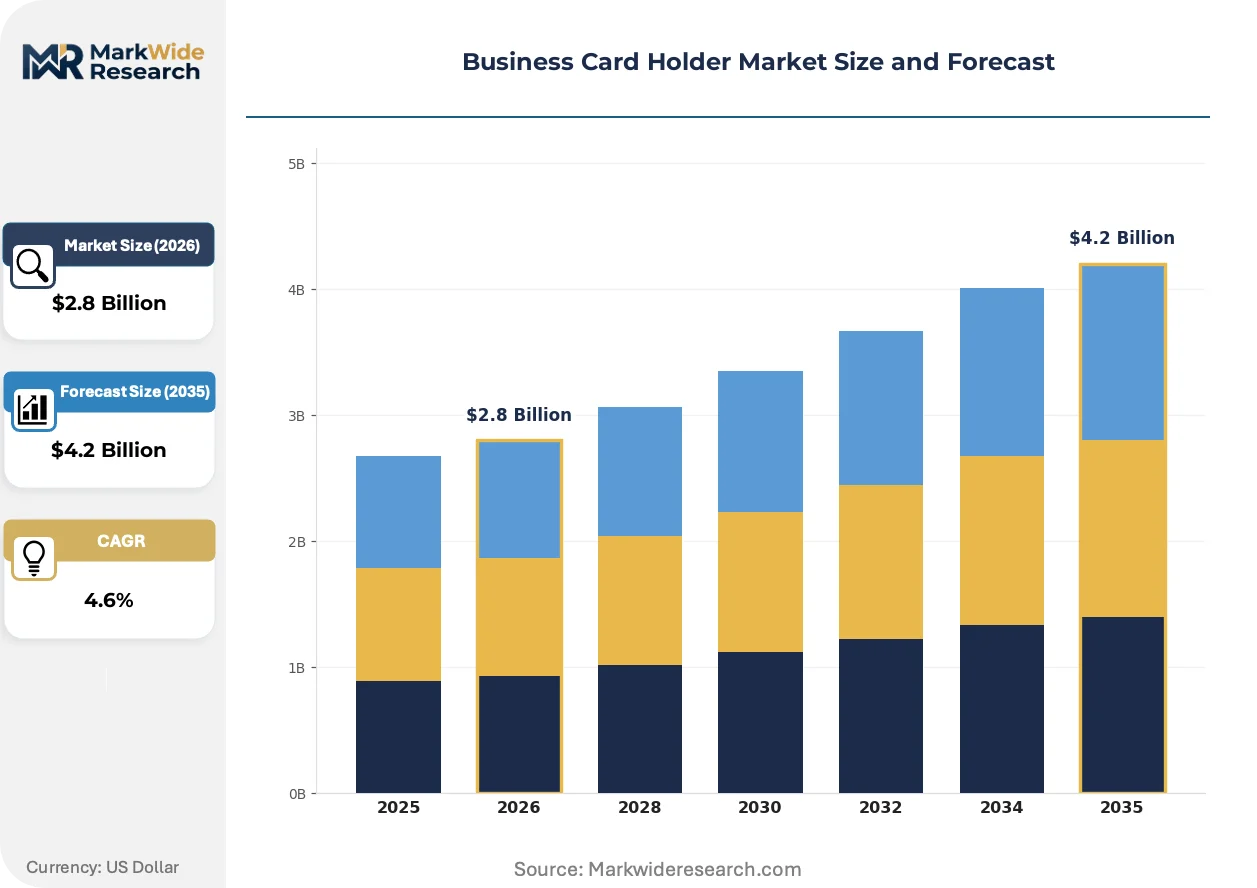
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Leather, Plastic, Metal, Fabric Size: Standard, Mini, Oversized, Slim Design: Classic, Modern, Vintage, Promotional Distribution Channel: Online, Retail, Wholesale, Custom |
| Companies Covered | Montblanc, Louis Vuitton, Samsonite, Tumi, Bellroy, Fossil, Hugo Boss, Gucci, Secrid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Card Holder Market Strategic Shifts
Material science breakthroughs and regulatory stringency are converging to redefine product architecture and sourcing strategy across all price tiers.
RFID-blocking metal composites are rewriting security expectations for pocket-carry accessories. Financial services and legal sector procurement teams now specify electromagnetic shielding as standard. This capability compression is collapsing the premium attached to standalone security accessories into base product specifications.
REACH authorization list expansion is redirecting tanning chemistry investments toward bio-based alternatives. ECHA substance evaluation cycles are lengthening compliance timelines for traditional chromium processes. Italian and Spanish tanneries are accelerating vegetable-tanning capacity to secure EU market access.
Direct-to-corporate gifting platforms are displacing wholesale distributor relationships. Professional services firms now contract directly with manufacturers for annual engraving and fulfillment programs. This channel compression is most advanced in Germany and the United Kingdom where procurement centralization has matured.
Business Card Holder Market Segmentation
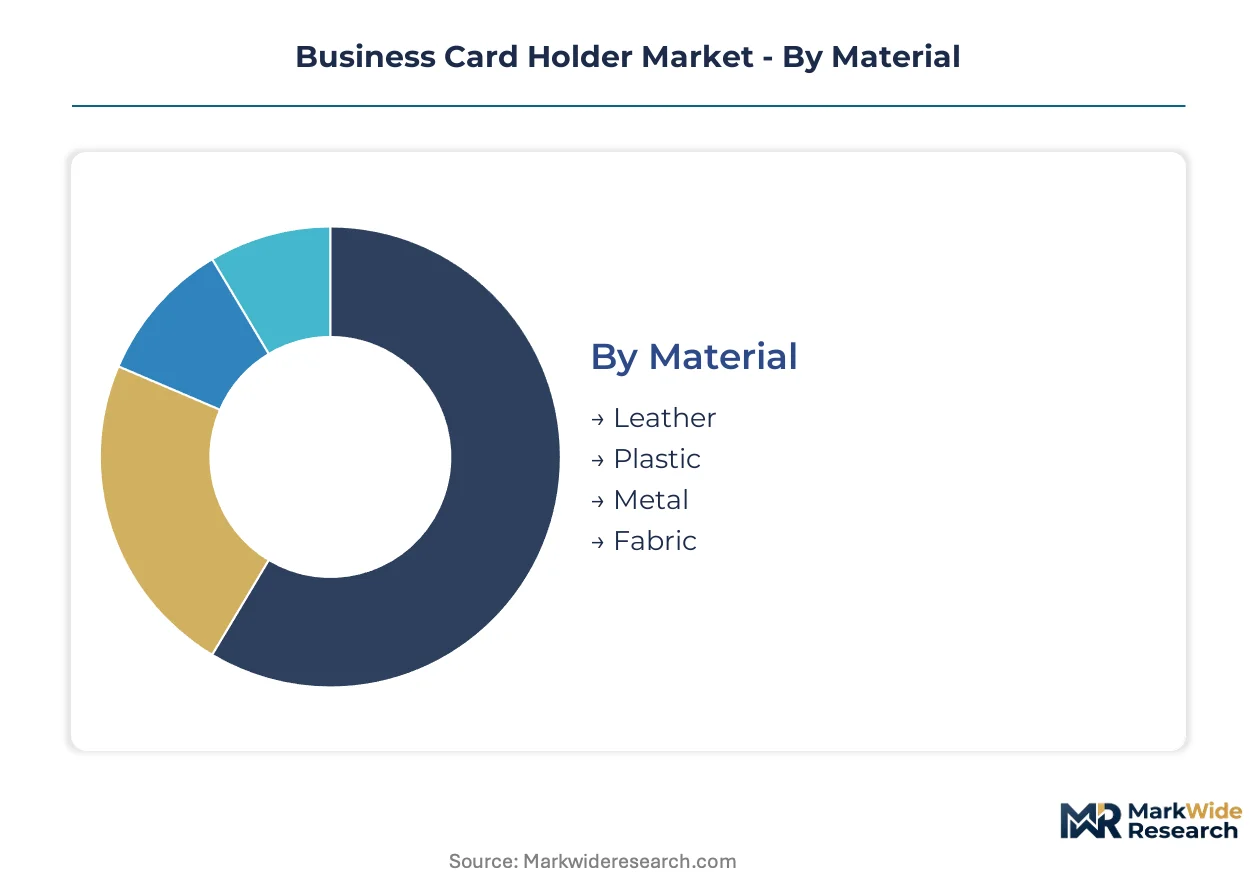
Material composition determines regulatory pathway complexity for business card holders, with leather and metal variants facing distinct certification burdens across EU, US, and Chinese markets. Size and design configurations align with pocket-carry ergonomics and corporate gifting protocols. Distribution channel selection shapes margin structure and customer acquisition economics.
Material:
REACH mandates for chromium VI in leather tanning and GB heavy-metal limits for metal alloys create divergent compliance timelines across material categories.
- Leather:Vegetable-tanned and chrome-tanned variants dominate premium positioning. Italian and Spanish tanneries are accelerating certified vegetable-tanning capacity to secure EU market access amid ECHA substance evaluation cycles. Corporate gifting programs at professional services firms sustain volume demand for executive-grade leather finishes.
- Metal:Stainless steel and aluminum constructions integrate RFID-blocking Faraday shielding as standard specification. Guangdong and Zhejiang production clusters deliver cost-competitive metal stamping at scale. Financial services procurement teams now specify electromagnetic shielding for pocket-carry security.
- Plastic:ABS and polycarbonate substrates serve promotional and hospitality verticals with compressed margins. FDA guidelines govern plastic contact materials for food-adjacent distributions in US markets.
- Fabric:Nylon and canvas variants target lightweight travel and casual professional use cases with minimal regulatory burden.
Leather sits at the top of the volume ranking, with metal climbing the fastest.
Size:
Pocket-carry ergonomics and card capacity requirements segment demand across dimensional configurations with distinct price positioning.
- Standard:ISO 7810 ID-1 conforming dimensions accommodate 20-30 cards with rigid structural support. Corporate bulk procurement programs favor this configuration for uniform branding deployment.
- Slim:Sub-10mm thickness profiles target minimalist design preferences in technology and creative sectors. This format is expanding share as pocket-carry preferences shift toward reduced bulk.
- Mini:Compact 5-10 card capacity serves mobile professionals prioritizing portability over storage volume.
- Oversized:Extended dimensions accommodate non-standard card formats and multi-functional storage for executive use cases.
Standard configurations maintain volume leadership, while slim formats are gaining share fastest among urban professionals.
Design:
Aesthetic positioning determines channel strategy and customer lifetime value with heritage craftsmanship commanding sustained price premiums.
- Classic:Traditional silhouettes with hand-finishing associations target legal and financial services gifting protocols. Italian atelier capacity constraints limit expansion for heritage-positioned brands.
- Modern:Minimalist geometries with clean lines align with technology sector professional preferences and direct-to-consumer marketing efficiency.
- Vintage:Distressed finishes and retro styling serve personal gifting occasions with emotional resonance but irregular purchase cycles.
- Promotional:Logo-centric, high-volume production serves trade show and hotel concierge applications with brand exposure value but compressed unit economics.
Classic design sits at the top of the volume ranking, with modern styling climbing the fastest among younger professional demographics.
Distribution Channel:
Channel selection determines margin capture and customer relationship depth with direct models displacing traditional wholesale intermediaries.
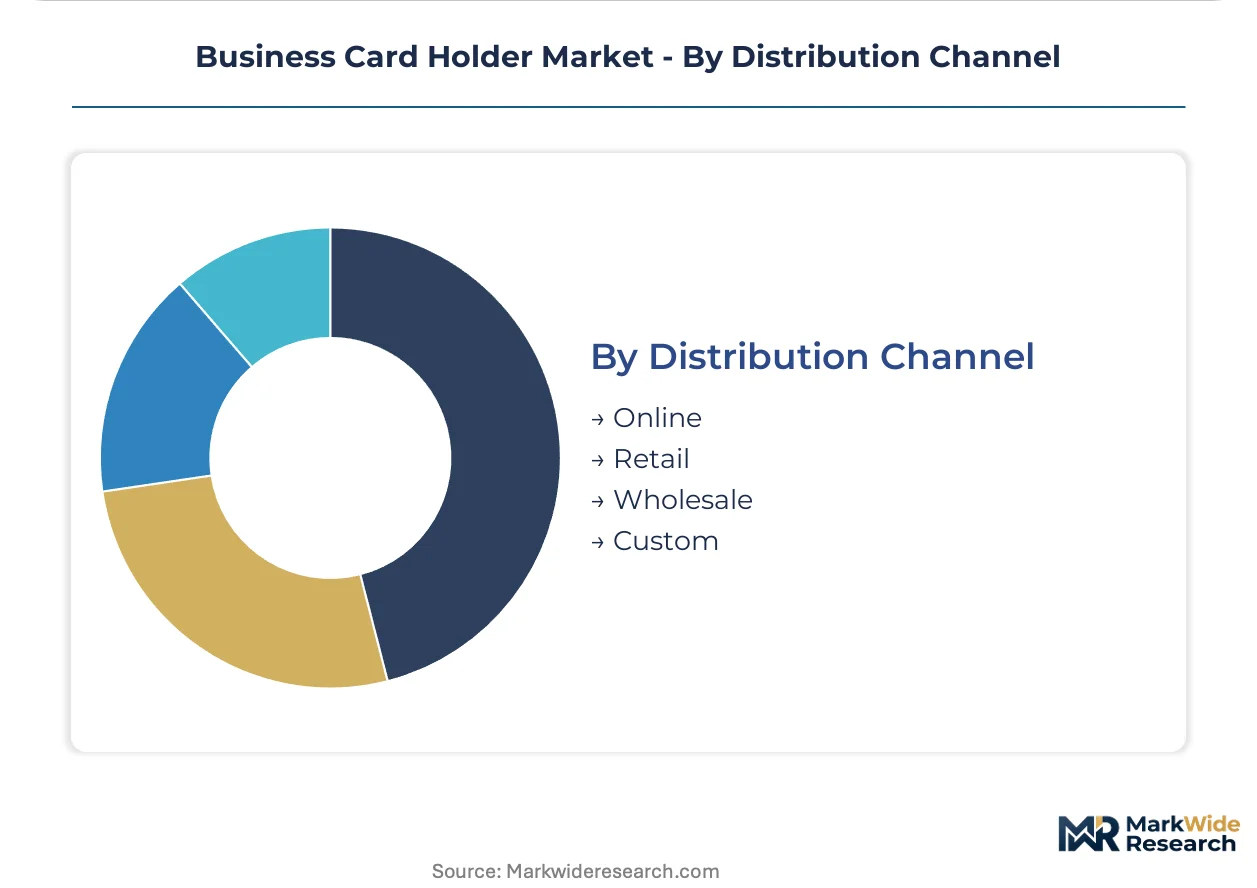
- Online:Direct-to-consumer and marketplace platforms enable personalization services and subscription revenue models. This channel is displacing wholesale distributor relationships in Germany and the United Kingdom.
- Retail:Specialty stationery and luxury goods storefronts provide tactile evaluation for premium leather and metal variants.
- Wholesale:Distributor networks serve fragmented corporate procurement with volume aggregation but eroding margin share.
- Custom:Direct-to-corporate gifting platforms contract with manufacturers for annual engraving and fulfillment programs with centralized procurement.
Custom channel configurations sit at the top of the volume ranking for corporate accounts, with online distribution climbing the fastest for individual purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands manufacturing volume leadership while Germany anchors premium consumption through corporate procurement centralization. The United States sustains demand via professional services gifting protocols. Regulatory divergence across these markets reshapes material sourcing and certification requirements.
China
Guangdong and Zhejiang manufacturing clusters deliver cost-competitive metal stamping and leather finishing at scale for export markets. SAMR oversight enforces GB heavy-metal limits in metal alloy components for domestic and export production. Shenzhen-based fabricators are accelerating RFID-blocking metal composite output to meet financial sector procurement specifications.
Germany
Corporate gifting programs at professional services firms sustain volume demand for executive-grade leather finishes. ECHA substance evaluation cycles under REACH are lengthening compliance timelines for traditional chromium processes. Frankfurt and Munich procurement offices are contracting directly with manufacturers for annual engraving and fulfillment programs.
United States
Financial services and legal sector procurement teams specify electromagnetic shielding as standard for pocket-carry security. FDA guidelines govern plastic contact materials for food-adjacent promotional distributions. New York and Chicago professional services clusters are driving direct-to-corporate gifting platform adoption.
Italy
Heritage craftsmanship associations command sustained price premiums in classic design segments. REACH authorization list expansion is redirecting tanning chemistry investments toward vegetable-tanned alternatives. Tuscan tanneries are accelerating certified vegetable-tanning capacity to secure EU market access amid regulatory pressure.
United Kingdom
Procurement centralization has matured most advanced direct-to-manufacturer contracting for annual corporate gifting. ECHA compliance requirements filter through UK supply chains post-regulatory alignment. London professional services clusters are displacing wholesale distributor relationships through centralized gifting platform adoption.
Business Card Holder Market Competitive Environment
Top-tier vendors anchor heritage luxury positioning, while mid-tier specialists compete on material innovation and regulatory compliance speed. The market structure fragments across three tiers: heritage maisons with atelier capacity constraints, mid-tier brands with manufacturing scale advantages, and promotional fabricators serving high-volume hospitality verticals. Strategic archetypes include craftsmanship-heritage defenders, metal-composite technology licensors, and corporate gifting platform operators. Dominant competitive moves encompass direct-to-corporate channel compression and REACH-certified material portfolio diversification.
Within the heritage craftsmanship tier, Montblanc and Louis Vuitton exemplify positioning built on atelier associations and executive gifting protocol penetration. Samsonite occupies a position bridging corporate bulk procurement relationships with Fortune 500 accounts and mid-tier accessibility. These three anchors represent divergent pathways for margin defense: Montblanc through direct-to-consumer heritage premium, Louis Vuitton through luxury ecosystem integration, and Samsonite through procurement centralization capture.
| Leading Market Players |
|---|
| Montblanc |
| Louis Vuitton |
| Samsonite |
| Tumi |
| Bellroy |
| Fossil |
| Hugo Boss |
| Gucci |
| Secrid |
| Others |
Value Chain & Pricing Dynamics
Vegetable-tanning chemistry transitions in Italian and Spanish tanneries are compressing unit economics for premium leather variants while concentrating certified supply among heritage ateliers with sunk compliance investments. This bifurcation is elevating price floors for REACH-compliant outputs and squeezing mid-tier producers dependent on chrome-tanning inputs facing ECHA authorization uncertainty.
Pricing Analysis
Capacity additions in Guangdong and Zhejiang are reshaping price floors for metal-stamped RFID-blocking holders, forcing premium positioning through certification differentiation rather than base manufacturing cost. Three-tier pricing structure across premium, standard, and economy levels stratifies by vegetable-tan certification grade and electromagnetic shielding specification. Cost compression in promotional plastic segments is intensifying because FDA-compliant resin sourcing commands premium over standard ABS. Corporate procurement teams show lowest price sensitivity for engraved leather with CSRD-aligned bio-based credentials, while hospitality bulk buyers negotiate aggressively on volume.
Supply Chain Analysis
Hand-finishing expertise attrition in Tuscan and French ateliers is constraining expansion capacity for heritage-positioned brands dependent on artisan labor pools. Supply concentrates in China for metal alloy stamping and component assembly, in Italy and Spain for vegetable-tanned leather finishing, and in Vietnam for synthetic fabric cutting. Raw material flows draw from chromium sulfate processors in South Africa, stainless steel mills in Shanxi province, and mycelium leather cultivators in Netherlands pilot facilities. Single-source vulnerability runs through concentrated Chinese mill clusters subject to SAMR environmental enforcement. Distribution runs through direct-to-corporate gifting platforms displacing wholesale intermediaries in Germany and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Procurement specifications at financial services and legal sector firms are hardening toward RFID-blocking and REACH-certified vegetable-tanned standards, filtering volume toward compliant suppliers with sunk certification investments.
For Market Incumbents: To counter digital contact substitution via LinkedIn and NFC-enabled smartphone protocols, anchor defensive positioning through backward integration into certified tannery capacity and exclusive direct-to-corporate channel control. Lock in multi-year engraving and fulfillment contracts with professional services procurement offices in Frankfurt, Munich, and London. Prioritize atelier capacity preservation through apprenticeship pipelines addressing leather craftsmanship talent scarcity.
For New Entrants and Emerging Players: Sustainability-focused professional services boutiques represent an underserved buyer archetype with willingness-to-pay premiums for mycelium leather and bio-based polyurethane alternatives qualifying for CSRD reporting benefits. Target event hospitality verticals with promotional design segments serving trade show and hotel concierge applications. Enter through subscription personalization services for engraved metal holders creating recurring revenue beyond one-time gifting cycles.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier metal-composite fabricators with SAMR-compliant alloy sourcing and dormant RFID-blocking patent portfolios. Long-term viability hinges on regulatory compliance speed rather than brand heritage, favoring targets with parallel REACH-FDA-GB testing capabilities. Watch ECHA substance evaluation cycle acceleration as inflection indicator for chrome-tanning asset impairment risk.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Certified Material Portfolio Diversification | Secures EU market access amid ECHA authorization list expansion for chromium compounds. |
| Direct-to-Corporate Gifting Platform Launch | Displaces wholesale intermediaries in Germany and United Kingdom procurement centralization. |
| RFID-Blocking Patent Licensing Program | Monetizes Faraday shielding specifications now standard in financial services procurement. |
| Vegetable-Tanning Capacity Acquisition | Captures scarce Italian and Spanish atelier output facing heritage brand demand concentration. |
| Subscription Personalization Service Rollout | Converts one-time corporate gifting into recurring revenue with annual engraving cycles. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with leather goods procurement managers, corporate gifting platform operators, tannery compliance officers, and professional services facilities administrators with secondary validation against ECHA substance evaluation databases, SAMR enforcement disclosures, FDA plastic contact material guidelines, and customs trade flow records. Bottom-up demand modeling triangulated against top-down market sizing across material, size, design, and distribution channel dimensions.
Historical reference periods anchored volume and value trajectories across the modeling period, with forward projections calibrated to observed procurement specification shifts and regulatory compliance timeline acceleration. Segmentation dimensions modeled include material composition, dimensional configuration, aesthetic positioning, and channel structure, supplemented by certification tier and electromagnetic shielding specification. CAGRs derived from regression analysis of annual procurement volume flows and price realization trends, with inputs from tanning chemistry investment cycles and metal alloy sourcing concentration patterns.
Underlying measurement precision varies by segment; leather and metal variants with established certification pathways carry tighter precision than emerging bio-based alternatives with nascent production scale. Forecasts reflect assumptions around ECHA authorization timeline adherence, SAMR enforcement intensity continuity, and corporate gifting program budget stability. Material deviation in regulatory cycle acceleration, chrome-tanning input cost volatility, or digital contact substitution adoption rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Stationery Market
Office Supplies
Writing and Marking Instruments Market
Office Supplies
Custom Binders Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
Global Office Peripherals and Products Market
Office Supplies
Stationery Products Market
Office Supplies
Copiers Market
Office Supplies
Letter Opener Market
Office Supplies
Global Office Stationery Market
Office Supplies
Erasable Ink Pen Market
Office Supplies
Thumb Hole Book Page Holder Market
Office Supplies
Europe School Stationery Supplies Market
Office Supplies
Writing Instruments Market
Office Supplies
Student Stationery Market
Office Supplies
Marker Pens Market
Office Supplies
Perforated File Market