
 Stationery Market | 2026-2036
Stationery Market Size, Share, and Industry Trends Forecast 2026-2036
Stationery Market Analytics
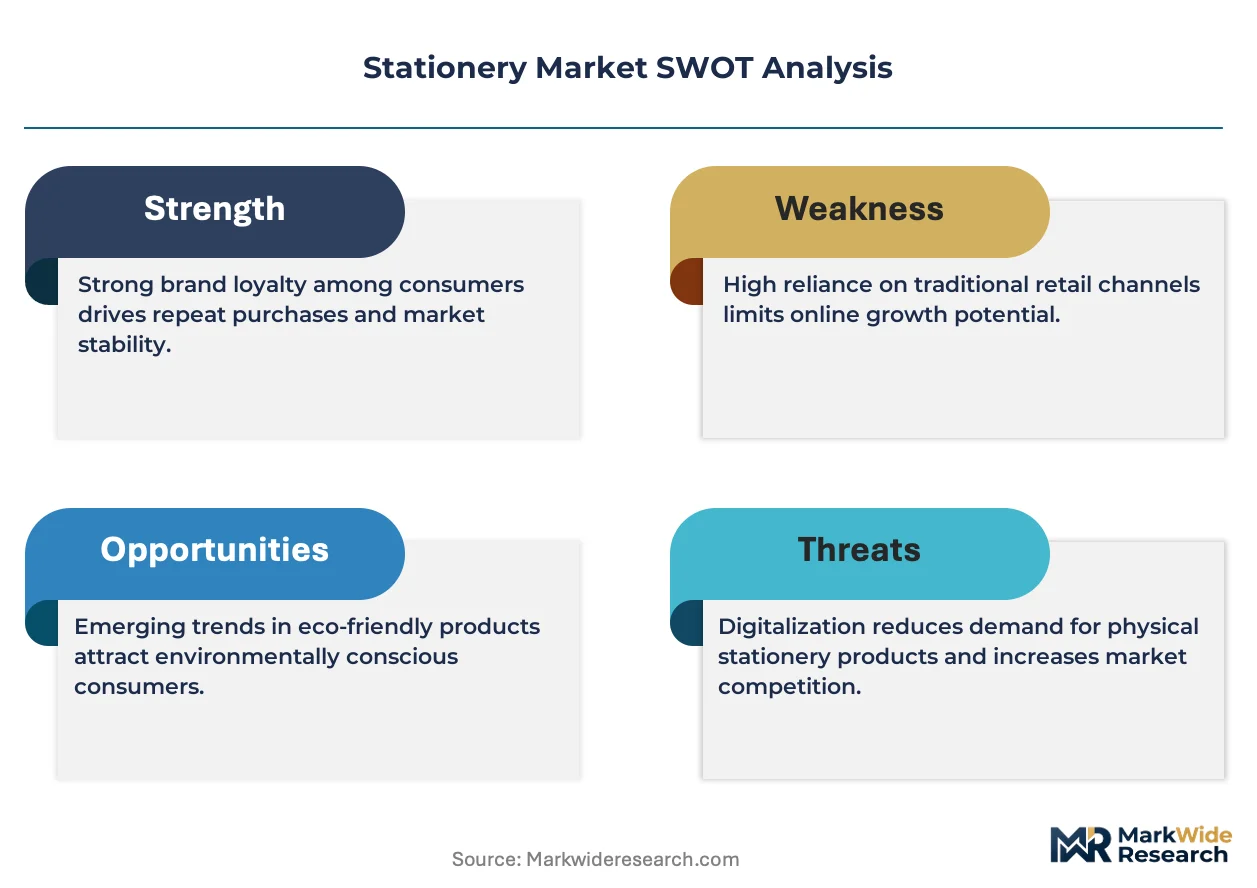
Recycled paper pulp is rebalancing cost structures for notebook manufacturers against virgin fiber volatility. Faber-Castell AG leverages its captive forestry operations in Brazil to secure certified wood supplies for pencil production. Shanghai M&G Stationery dominates domestic distribution through direct school procurement contracts across Chinese provinces. Deli Group Co. Ltd. anchors its competitive position with integrated plastic resin compounding for pen barrel manufacturing.
Stationery encompasses writing instruments, paper goods, and organizational supplies engineered to specific grammage, ink viscosity, and point-size tolerances for communication and creative tasks. Notebook production typically employs 60–120 gsm wood-free or recycled paper, bound through spiral wire, perfect glue, or thread stitching to withstand repeated handling. Pens and pencils command the largest revenue share within product type segmentation, while markers gain share in art and craft applications where pigment load and nib durability differentiate performance tiers. Paper material sourcing faces margin pressure from certified chain-of-custody requirements, whereas plastic and metal alternatives expand in premium gift and technical instrument segments.
FDA regulates ink formulations for incidental skin contact under cosmetic safety guidelines in the United States, while REACH restricts phthalate plasticizers in pen grips and marker solvents across European markets. China's GB standards mandate soluble heavy metal limits in student-use colored pencils, directly shaping export compliance costs for manufacturers serving multiple jurisdictions. Stakeholders must monitor evolving extended producer responsibility frameworks for plastic writing instruments, as these programs will determine which material formats retain channel access and which face disposal surcharges.
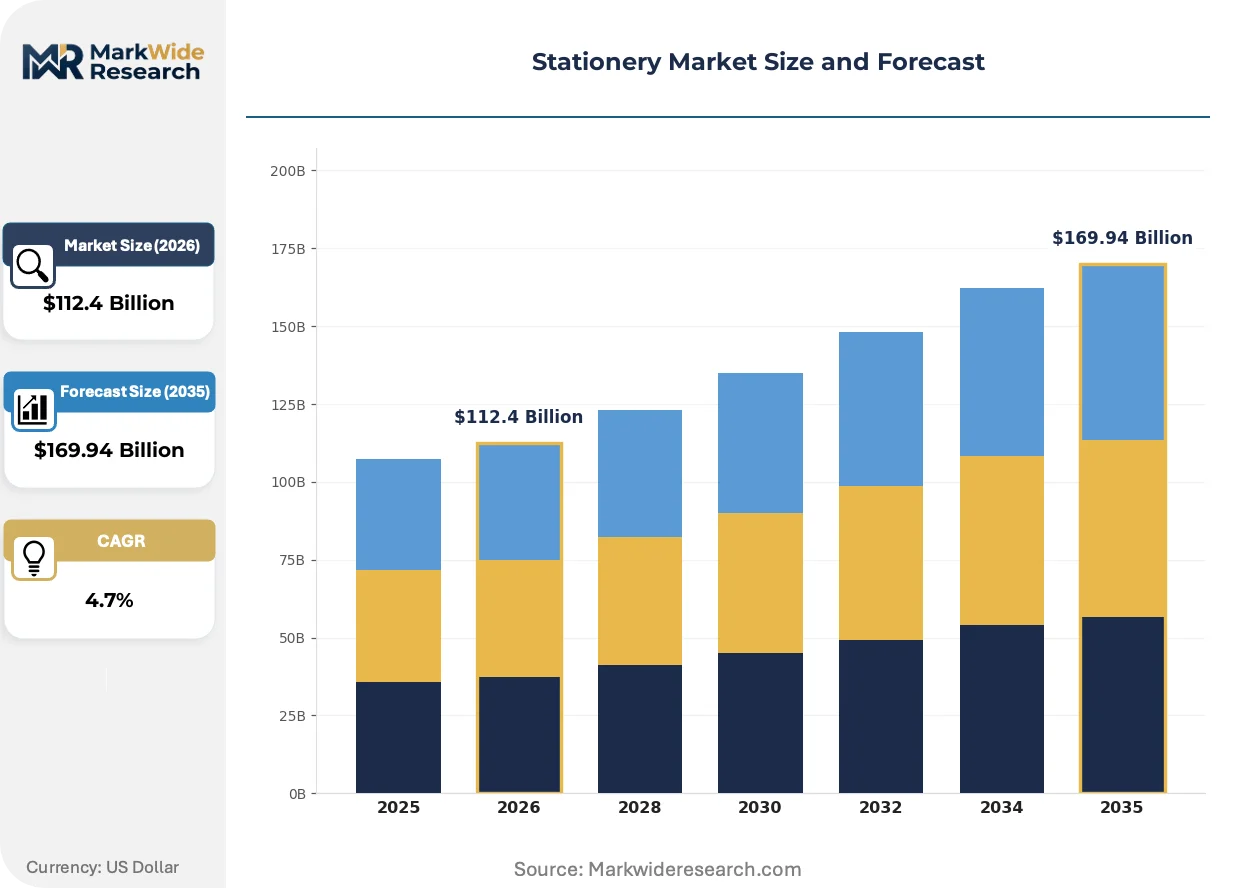
Market Dynamics
EU Ecodesign criteria for paper-based products are redirecting procurement toward certified recycled stock, compressing margins for virgin fiber-dependent producers while advantaging integrated recyclers.
Growth Catalysts
- Hybrid learning stabilization:Educational institutions in India are consolidating enrollment-driven volume purchasing of notebooks and writing instruments as post-pandemic instructional models settle.
- REACH phthalate restrictions:European regulatory pressure on plasticizer content in pen grips is accelerating substitution toward bio-based alternatives and silicone compounds.
- Certified chain-of-custody mandates:Forest Stewardship Council and Programme for the Endorsement of Forest Certification sourcing requirements are concentrating demand toward integrated pulp-to-paper producers.
Market Restraints
- Virgin pulp price volatility:Hardwood and softwood fiber costs swing with Brazilian and Indonesian harvest cycles, destabilizing notebook manufacturer input cost planning.
- China GB heavy metal compliance:Soluble lead, cadmium, and chromium limits in student-use colored pencils impose testing and reformulation burdens on export-oriented factories.
- Digital substitution pressure:Tablet and stylus penetration in secondary education and administrative workflows erodes addressable demand for traditional writing instruments.
Strategic Opportunities
- Indian government school procurement:Sarva Shiksha Abhiyan and state-level education department tenders create predictable volume anchors for domestic and regional suppliers.
- Extended producer responsibility frameworks:France and Germany are piloting take-back schemes for plastic writing instruments that reward modular, recyclable designs with channel access.
- Art supply premiumization:Pigment load and nib durability specifications in professional marker segments command price multiples over standard consumer grades.
Industry Challenges
- Cross-jurisdiction formulation complexity:Manufacturers serving US FDA cosmetic safety guidelines, EU REACH restrictions, and China GB standards simultaneously face incompatible compliance timelines and testing protocols.
- Recycled fiber quality variance:De-inked pulp yield and brightness inconsistency disrupts 60–120 gsm notebook production runs, requiring real-time grammage adjustments and waste buffers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stationery Market |
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $169.94 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pens, Pencils, Notebooks, Markers Application: School, Office, Art, Craft Material: Paper, Plastic, Metal, Wood End User: Students, Professionals, Artists, Hobbyists |
| Companies Covered | Beifa Group, Faber-Castell AG, KOKUYO Co., Ltd, Guangbo Group Stock Co. Ltd., Staples Inc., Shanghai M&G Stationery, Newell Brands Inc., Lexi Pens, Deli Group Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stationery Market Evolving Landscape
Material convergence and regulatory stringency are compressing traditional supply chain configurations while opening premium positioning for certified sustainable alternatives.
Plant-based resin formulations are unifying pen barrel production across petroleum-dependent and bio-source feedstocks. European and North American premium brands are adopting castor oil-derived polyamides at scale. This substitution is unifying cost structures against crude oil volatility while satisfying retailer sustainability scorecards.
REACH solvent restrictions in marker and highlighter formulations are forcing pigment vehicle reformulation toward water-based and alcohol-reduced systems. German and French manufacturers face 2025 implementation deadlines for volatile organic compound thresholds. Art supply segments are responding with reformulated professional-grade lines that preserve lightfastness while meeting emission limits.
Direct school procurement contracts are displacing distributor-mediated purchasing in high-volume developing markets. Chinese provincial education bureaus and Indian state textbook corporations now negotiate annual supply agreements with manufacturers. This concentration is most visible in Maharashtra and Guangdong, where consolidated tenders cover notebook, pen, and examination material requirements for millions of enrolled students.
Stationery Market Segmentation
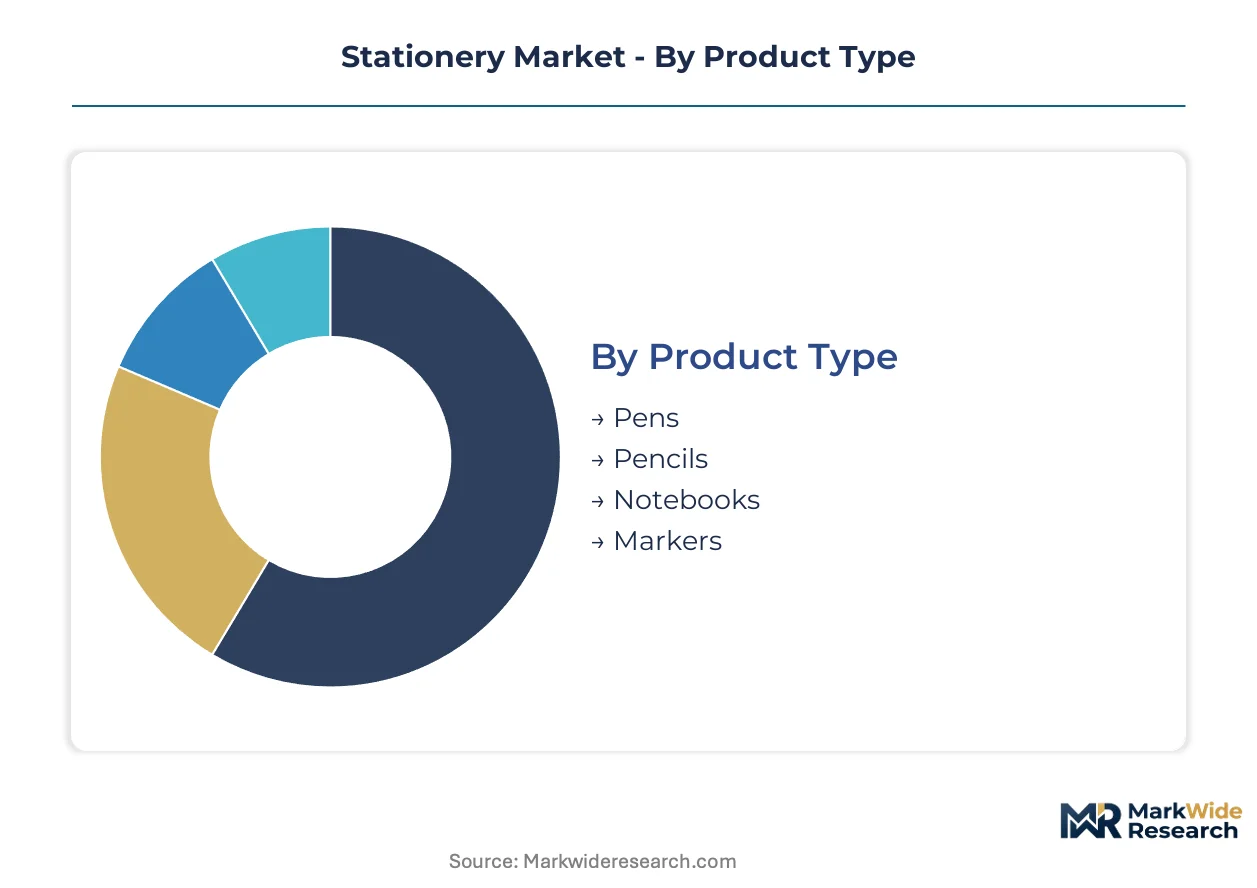
Stationery manufacturers configure production lines around grammage tolerances, nib specifications, and binding methods that vary sharply across end-use scenarios. Segmentation discipline determines which material formats absorb capital investment and which face margin compression from regulatory compliance costs.
Product Type:
Capital intensity peaks in segments requiring precision molding equipment and formulation laboratories for ink or pigment systems.
- Pens:Ballpoint, rollerball, and fountain variants demand injection molding lines for barrel production and cleanroom filling stations for ink formulation. Demand concentrates in Indian government school tenders under Sarva Shiksha Abhiyan procurement cycles, where volume specifications reward automated assembly scale.
- Markers:Alcohol-based and water-based pigment systems require solvent handling infrastructure and nib fiber compression presses. Art supply channels in Germany and France drive premium tier demand as REACH volatile organic compound deadlines approach.
- Pencils:Graphite grading and cedar slat gluing utilize woodworking and lacquering equipment with moderate tooling costs.
- Notebooks:Spiral binding and perfect binding lines represent lower capital barriers but face working capital intensity from paper inventory cycles.
Most installed capacity flows through Pens. Expansion is steepest in Markers.
Application:
Volume scale separates institutional procurement from fragmented retail channels.
- School:Examination materials and daily-use supplies operate under centralized tender systems in Maharashtra and Guangdong provinces. Chinese provincial education bureaus negotiate direct manufacturer contracts covering millions of enrolled students.
- Office:Corporate procurement through managed print services and facility management contracts favors standardized SKUs with predictable replenishment cycles.
- Art:Professional pigment load specifications and lightfastness ratings command price multiples over student grades.
- Craft:Seasonal demand patterns and hobbyist channel fragmentation compress margin stability.
School procurement anchors volume planning. Art applications deliver the steepest margin expansion trajectory.
Material:
Certification requirements and feedstock volatility differentiate input cost structures.
- Paper:60–120 gsm wood-free and recycled stocks require chain-of-custody documentation under Forest Stewardship Council and Programme for the Endorsement of Forest Certification standards. EU Ecodesign criteria redirect procurement toward certified recycled stock.
- Plastic:Pen barrels and marker casings face REACH phthalate restrictions and emerging extended producer responsibility take-back schemes in France and Germany.
- Metal:Technical pens and premium gift instruments utilize brass and aluminum machining with higher tooling amortization.
- Wood:Pencil slat production depends on cedar and basswood supplies from captive forestry operations.
Plastic formats dominate unit volume. Paper faces the steepest compliance cost escalation.
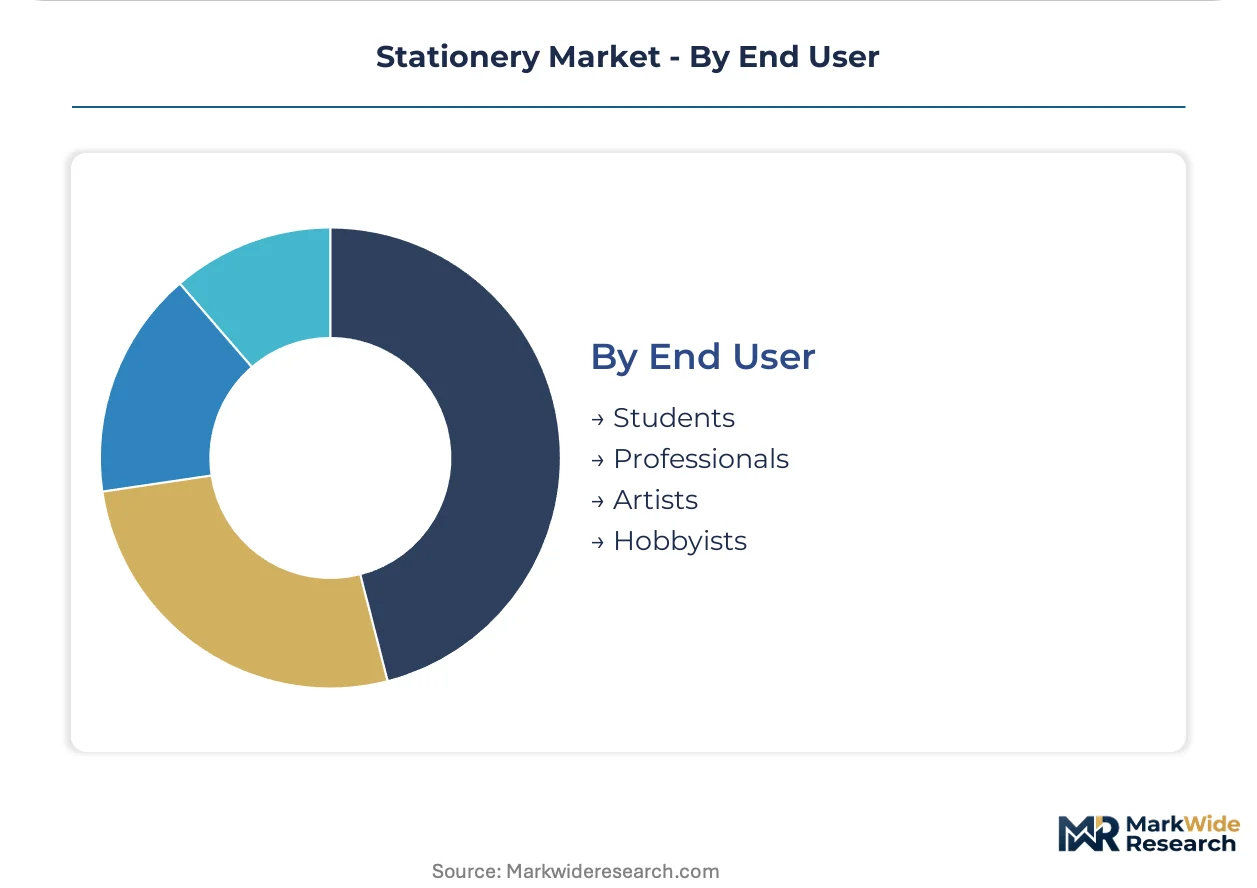
End User:
Purchase frequency and price sensitivity stratify across demographic and professional boundaries.
- Students:Soluble heavy metal limits under China GB standards and volume purchasing through education department tenders shape product specifications and testing protocols.
- Professionals:Corporate identity customization and ergonomic grip preferences support premium positioning in developed markets.
- Artists:Pigment concentration, nib durability, and lightfastness ratings determine switching costs between professional-grade suppliers.
- Hobbyists:Price elasticity and seasonal purchase patterns concentrate demand in discount retail and e-commerce channels.
Students generate the highest absolute unit demand. Artists sustain the most pronounced premium tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ningbo anchors global stationery manufacturing through its dense concentration of pen and pencil fabricators serving export markets. Regional demand patterns diverge sharply between mature economies with premium art supply consumption and developing markets anchored by institutional procurement volumes.
China
Provincial education bureaus in Guangdong negotiate direct manufacturer contracts covering millions of enrolled students annually. GB standards mandate soluble heavy metal limits in student-use colored pencils, shaping export compliance costs for factories serving multiple jurisdictions. Shanghai M&G Stationery dominates domestic distribution through these school procurement channels.
India
Sarva Shiksha Abhiyan and state-level education department tenders create predictable volume anchors for notebook and writing instrument suppliers. Government school enrollment drives mass-market purchasing concentrated in Maharashtra and Tamil Nadu. Deli Group and regional competitors position for these consolidated tenders.
Germany
REACH restrictions on phthalate plasticizers in pen grips and volatile organic compound thresholds in markers force reformulation toward bio-based alternatives. Faber-Castell AG leverages captive forestry operations in Brazil to secure certified wood supplies for pencil production. Manufacturing clusters in Bavaria and Baden-Württemberg specialize in premium art supply segments.
United States
FDA regulates ink formulations for incidental skin contact under cosmetic safety guidelines, creating compliance barriers for imported writing instruments. Staples Inc. and Newell Brands anchor corporate procurement through managed print services and facility management contracts. Distribution concentrates in the Northeast Corridor and Texas logistics hubs.
Brazil
Captive forestry operations supply certified cedar and basswood for pencil slat production serving export markets. ANVISA oversees product safety compliance for imported stationery goods. Manufacturing concentrates in São Paulo state, where integrated pulp-to-paper producers compete on chain-of-custody certification.
Stationery Market Competitive Landscape
Global majors compete with regional champions across procurement channel access and raw material integration. The vendor base stratifies between integrated forest products companies, school-contract specialists, and premium art supply houses. Three archetypes dominate: captive forestry operators controlling upstream fiber costs, direct-procurement contractors winning education tenders, and specialty pigment formulators serving professional artists. Competitive moves concentrate on backward integration into resin compounding and pulp supply, plus geographic expansion through distributor acquisitions in high-enrollment markets.
Among German-anchored manufacturers with forestry integration, Faber-Castell AG exemplifies the captive-resource archetype. Chinese direct-procurement specialists include Shanghai M&G Stationery and Deli Group Co. Ltd., both positioned within the education-tender tier. These three represent distinct strategic positions without overlapping core competencies.
| Leading Market Players |
|---|
| Beifa Group |
| Faber-Castell AG |
| KOKUYO Co., Ltd |
| Guangbo Group Stock Co. Ltd. |
| Staples Inc. |
| Shanghai M&G Stationery |
| Newell Brands Inc. |
| Lexi Pens |
| Deli Group Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Indian government school procurement through Sarva Shiksha Abhiyan and state education department tenders anchors volume pricing for notebooks and writing instruments, compressing margins for suppliers dependent on spot-market paper pulp while rewarding integrated manufacturers with captive fiber supply.
Pricing Analysis
Input-cost pass-through from virgin pulp volatility shapes contract negotiations for notebook producers, with Brazilian and Indonesian harvest cycles driving quarterly cost adjustments. Three-tier pricing structure across premium, standard, and economy levels separates certified recycled stock from virgin fiber and private-label alternatives. Price differentiation hinges on Forest Stewardship Council certification tier and volume scale in tender awards. Pricing pressure stems from EU Ecodesign procurement mandates favoring recycled content, eroding premiums for virgin-dependent suppliers. Students in government school systems exhibit highest price sensitivity, while professional art supply buyers tolerate significant premiums for pigment load and lightfastness specifications.
Supply Chain Analysis
Container freight rates from Ningbo to European and North American distribution hubs directly determine landed cost competitiveness for pen and pencil exporters. Manufacturing concentrates in China, India, and Germany, with Ningbo anchoring global pen production and Bavaria specializing in premium art supplies. Raw material flows draw from Brazilian cedar forestry for pencil slats, Indonesian hardwood pulp for notebook paper, and castor oil-derived polyamides for bio-based pen barrels. Supply chain risk centers on single-source vulnerability for Forest Stewardship Council-certified fiber streams. Distribution runs through direct school procurement contracts in developing markets and managed print service integrators in corporate channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stationery manufacturing presents a geographic-arbitrage opportunity between EU REACH compliance costs and Indian government tender volumes, with regulatory divergence creating cost baselines that favor integrated Asian producers serving European premium segments.
For Market Incumbents: Acquire captive forestry operations or long-term fiber supply agreements to secure Forest Stewardship Council certification coverage against virgin pulp price volatility. Consolidate procurement channel control through direct contracts with Chinese provincial education bureaus and Indian state textbook corporations, defending position against digital stylus substitution in secondary education by embedding refill and consumable lock-in within tender specifications. For New Entrants and Emerging Players: E-commerce direct-to-consumer channels offer lowest barrier entry for premium art supply positioning, bypassing distributor margin stacking in fragmented hobbyist retail. Target professional artist segments in Germany and France with REACH-compliant reformulated marker lines, leveraging white-space from volatile organic compound deadline pressures. White-space exists in modular pen designs qualifying for French and German extended producer responsibility take-back schemes. For Investors and Strategic Acquirers: Integrated forest products companies are the most active acquirer in this space, seeking downstream brand assets to monetize captive pulp supply. Long-term viability favors targets with dual certification coverage and established education tender relationships. Acquisition focus should center on mid-cap specialists with backward integration into resin compounding or pulp supply. Watch for inflection in EU extended producer responsibility program expansion beyond pilot markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Fiber Supply | Secures Forest Stewardship Council coverage against EU Ecodesign procurement mandates. |
| Direct School Procurement Contract Expansion | Locks volume anchors with Maharashtra and Guangdong education bureaus. |
| Bio-based Resin Formulation Scale-Up | Replaces petroleum-dependent pen barrels with castor oil-derived polyamides for REACH compliance. |
| Extended Producer Responsibility Design Certification | Qualifies modular pen systems for French and German take-back scheme channel access. |
| Professional Art Supply Premium Tier Launch | Captures pigment load and lightfastness multiples in German and French reformulation windows. |
Research Methodology
Multiple input streams — primary interviews with procurement officers at Indian state education departments and Chinese provincial bureaus, technical discussions with formulation chemists at marker manufacturers, and channel interviews with German art supply distributors — were reconciled against secondary validation from customs trade data, Forest Stewardship Council certification registries, and REACH regulatory filings. Bottom-up volume modeling across product type, application, material, and end-user segments was triangulated with top-down market sizing from trade flow analysis.
Data-stream reconciliation employed analytical frameworks spanning the projection horizon across pens, markers, pencils, and notebooks by school, office, art, and craft applications. Segmentation modeling incorporated paper grammage tiers, plastic resin types, and certification status as industry-specific dimensions. CAGRs were derived from enrollment-driven demand curves, regulatory implementation timelines, and substitution elasticity estimates for digital writing instruments.
The model assumes a particular technology adoption path; alternative pathways for stylus and tablet penetration in secondary education would alter the outlook. Forecasts reflect assumptions on hybrid learning stabilization rates, EU Ecodesign enforcement intensity, and extended producer responsibility program geographic expansion. A model refresh is warranted upon material change in Indian government education budget allocation or REACH volatile organic compound threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Diaries & Planners Market
Office Supplies
Flash Cards and USB Flash Drives Market
Office Supplies
Cutter Staplers Market
Office Supplies
Malaysia Stationery Market
Office Supplies
Copiers Market
Office Supplies
GCC School Stationery Supplies Market
Office Supplies
Student Stationery Market
Office Supplies
Marker Pens Market
Office Supplies
Stationery Products Market
Office Supplies
Latin America School Stationery Supplies Market
Office Supplies
School Stationery Supplies Market
Office Supplies
Office Supplies Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
Writing and Marking Instruments Market
Office Supplies
Global Stationery and Supplies Market
Office Supplies
Greetings Cards Market