
 Pet Water Fountain Market | 2026-2036
Pet Water Fountain Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Water Fountain Market Outlook
Food-grade stainless steel is broadening the addressable market for premium pet water fountains by displacing lower-grade plastics linked to feline acne and bacterial film accumulation. PETKIT leverages vertical integration across pump motor and filtration subsystems to sustain margin control against commodity competitors. Pioneer Pet anchors its position through ceramic artisan manufacturing partnerships in Southeast Asia, while PetSafe competes via veterinary channel exclusivity and in-clinic placement programs.
A pet water fountain is an electromechanical or gravity-fed hydration device engineered to circulate, filter, and oxygenate drinking water for companion animals, typically incorporating activated carbon or ion-exchange resin cartridges with flow rates between 50 and 150 liters per hour. Electric fountains dominate value capture due to pump-driven circulation and smart sensor integration, though gravity fountains retain volume leadership in price-sensitive emerging markets. Stainless steel material grade is accelerating fastest among urban pet owners concerned with dermatological safety and dishwasher durability, while plastic variants still occupy the mass-market tier through big-box retail placement.
The FDA Center for Veterinary Medicine oversees material safety claims for pet consumable devices in the United States, while the EU REACH framework restricts phthalate and heavy metal content in plastics sold across European member states. California Proposition 65 labeling requirements have forced reformulation of fountain reservoirs and tubing assemblies, raising compliance costs for import-dependent brands. Stakeholders must monitor evolving state-level chemical disclosure laws and the trajectory of smart-home interoperability standards before committing to connected fountain platform investments.
Market Dynamics
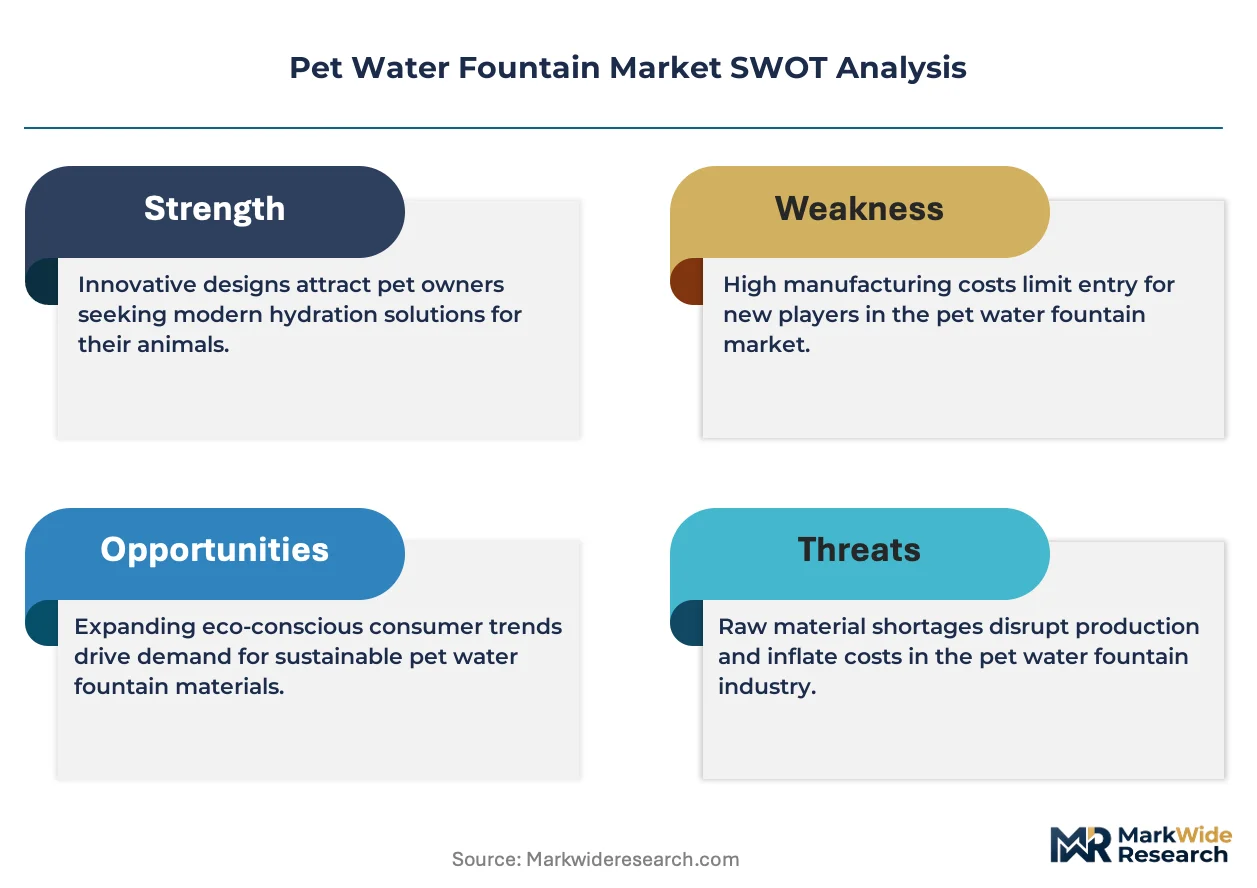
Material safety mandates from FDA and EU REACH regulators are accelerating a wholesale substrate transition from petroleum-based plastics to food-grade stainless steel and ceramic reservoirs, compressing margins for import-dependent brands while rewarding vertically integrated manufacturers with captive metallurgy capabilities.
Growth Catalysts
- REACH phthalate restrictions:The EU framework bans endocrine-disrupting plasticizers in pet consumable devices, forcing reformulation and opening share for stainless steel alternatives that bypass compliance complexity entirely.
- Multi-pet household hydration monitoring:Owners with three or more companion animals prioritize fountain capacity and filtration redundancy, driving demand for high-flow pump systems and multi-reservoir configurations.
- Subscription filter replacement models:Recurring revenue streams from activated carbon and ion-exchange cartridge auto-ship programs lock in customer lifetime value and reduce price sensitivity at initial purchase.
Market Restraints
- Pump motor supply concentration:Brushless DC submersible motor production clusters in Guangdong province, creating single-source vulnerability for brands without dual-qualified vendors.
- California Proposition 65 labeling costs:Chemical disclosure requirements for reservoir polymers and tubing assemblies add per-SKU compliance overhead that disproportionately burdens small import brands.
- Gravity fountain substitution in price-sensitive segments:Passive hydration systems without electromechanical components capture volume leadership in emerging markets where electricity reliability and disposable income constrain electric fountain penetration.
Strategic Opportunities
- Smart-home interoperability standards:Matter protocol certification for connected fountains enables voice control and automated refill alerts, opening premium positioning among tech-forward urban owners.
- Veterinary clinic channel placement:In-clinic endorsement and retail partnerships with companion animal hospitals build credibility and reduce customer acquisition costs for clinical-grade hydration monitoring.
- BPA-free material mandates in North American states:Consumer safety regulators in California, New York, and Washington are advancing labeling and disclosure rules that favor stainless steel and ceramic substrates.
Industry Challenges
- Filtration cartridge standardization gaps:Proprietary filter geometries lock consumers into single-brand replacement ecosystems, creating inventory complexity for multi-brand retailers and resistance from price-sensitive buyers.
- Submersible pump failure rates:Mineral scaling and biofilm accumulation in hard water regions accelerate motor degradation, driving warranty claims and eroding net promoter scores for brands without predictive maintenance alerts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Water Fountain Market |
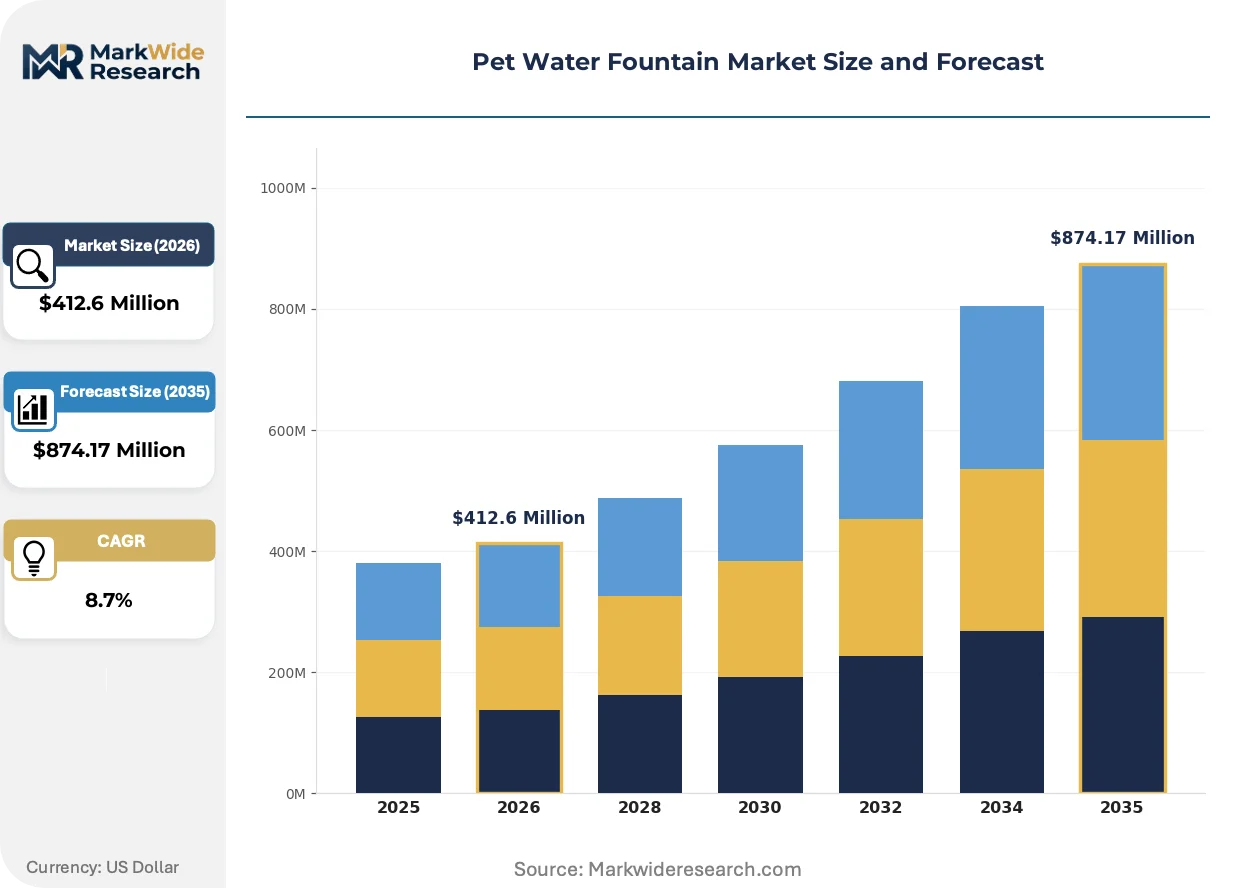
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Fountains, Gravity Fountains, Filtered Fountains, Non-Electric Fountains Material: Stainless Steel, Plastic, Ceramic, Glass End User: Pet Owners, Veterinarians, Pet Shops, Animal Shelters Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Home Improvement Stores |
| Companies Covered | Veken, Catit, PETKIT, Pioneer Pet, Petlibro, PetSafe, isYoung, Catgorie, Petmate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Water Fountain Market Strategic Shifts
Active oxygenation and sensor-integrated hydration systems are compressing the replacement cycle for legacy gravity-fed bowls while creating new data monetization pathways through companion animal health platforms.
UV-C LED sterilization modules are electrifying premium fountain architectures by eliminating bacterial biofilm without chemical additives. Urban cat owners in water-stressed municipalities adopt these systems fastest, perceiving tangible health differentiation. The technology is electrifying category margins by justifying 40-60% price premiums over carbon-filtration-only alternatives.
EU REACH Annex XVII restrictions on heavy metal content in plastics sold across member states are forcing reservoir and tubing reformulation. Import-dependent brands face 12-18 month requalification timelines for new polymer grades. Stainless steel fountain SKUs are capturing displaced demand as manufacturers bypass plastic compliance entirely.
Subscription-based filter auto-replenishment is displacing episodic retail purchasing among premium segment buyers. Direct-to-consumer channels capture recurring revenue previously lost to big-box retailers. This pattern concentrates in United States metropolitan markets where Amazon Subscribe & Save and Chewy Autoship have normalized consumable replenishment expectations.
Pet Water Fountain Market Segmentation
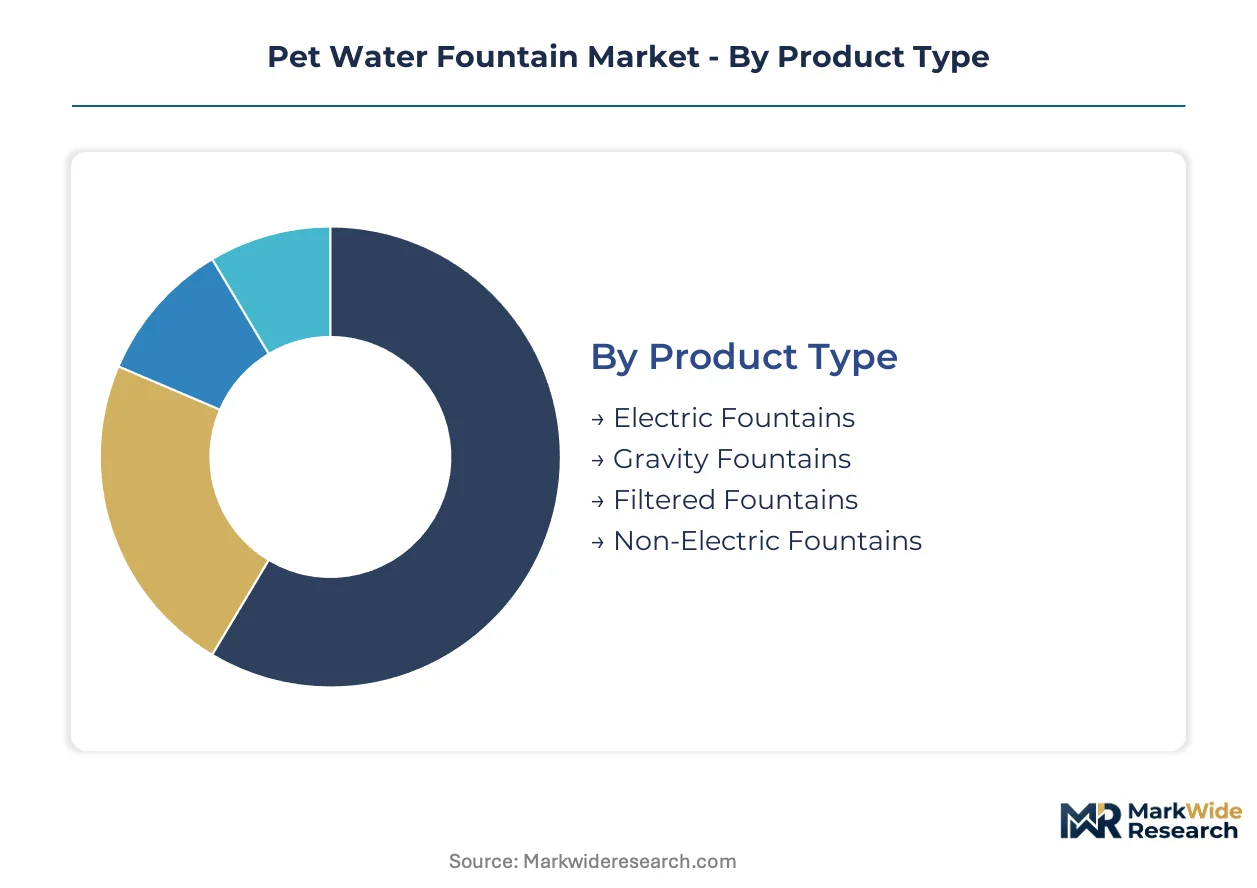
Upgrade cycles in the pet water fountain market accelerate when owners replace gravity-fed bowls with electromechanical systems or switch from plastic to stainless steel substrates. Segmentation reveals distinct margin profiles across pump-driven and passive hydration technologies, with material safety mandates reshaping purchasing priorities.
Product Type:
Replacement dynamics favor electromechanical systems over passive alternatives as multi-pet households prioritize filtration redundancy and capacity scaling.
- Electric Fountains:Pump-driven circulation systems with activated carbon or ion-exchange resin cartridges operate at flow rates between 50 and 150 liters per hour. Demand concentrates in United States metropolitan markets where subscription filter replacement models and smart-home integration justify premium positioning.
- Gravity Fountains:Passive hydration devices without electromechanical components rely on reservoir weight differential to maintain water levels. Volume leadership persists in emerging markets where electricity reliability constraints and lower disposable income favor non-powered alternatives.
- Filtered Fountains:Systems incorporating replaceable cartridges for chemical and particulate removal.
- Non-Electric Fountains:Simple reservoir designs without active filtration or circulation mechanisms.
Volume placements concentrate in Gravity Fountains; the faster expansion belongs to Electric Fountains.
Material:
Cost tiers separate food-grade metallurgy from commodity plastics as regulatory pressure elevates compliance burdens on petroleum-based substrates.
- Stainless Steel:Food-grade 304 or 316 alloy reservoirs eliminate feline acne triggers and bacterial film accumulation while enabling dishwasher cleaning. Urban cat owners in water-stressed United States municipalities adopt fastest, perceiving dermatological safety differentiation.
- Plastic:Polypropylene and ABS reservoirs dominate mass-market tier through big-box retail placement despite REACH phthalate restrictions and California Proposition 65 labeling requirements compressing margins.
- Ceramic:Artisan-manufactured reservoirs from Southeast Asian production partnerships anchor premium positioning.
- Glass:Borosilicate reservoir variants targeting chemical-averse consumer segments.
Plastic retains volume leadership; stainless steel is climbing the fastest as BPA-free mandates proliferate across North American states.
End User:
Application context determines performance specifications, with clinical settings demanding precision filtration that exceeds residential requirements.
- Pet Owners:Individual consumers purchasing for companion animal hydration in residential settings, prioritizing capacity scaling for multi-pet households and smart-sensor integration for travel convenience.
- Veterinarians:Clinical-grade hydration monitoring for post-surgical recovery and chronic condition management drives demand for UV-C sterilization and precise flow control.
- Pet Shops:Commercial display fountains for in-store animal housing and retail demonstration.
- Animal Shelters:High-capacity, durable systems for institutional multi-animal environments.
Pet Owners dominate unit placements; Veterinarians deliver the steepest margin expansion through clinical endorsement value.
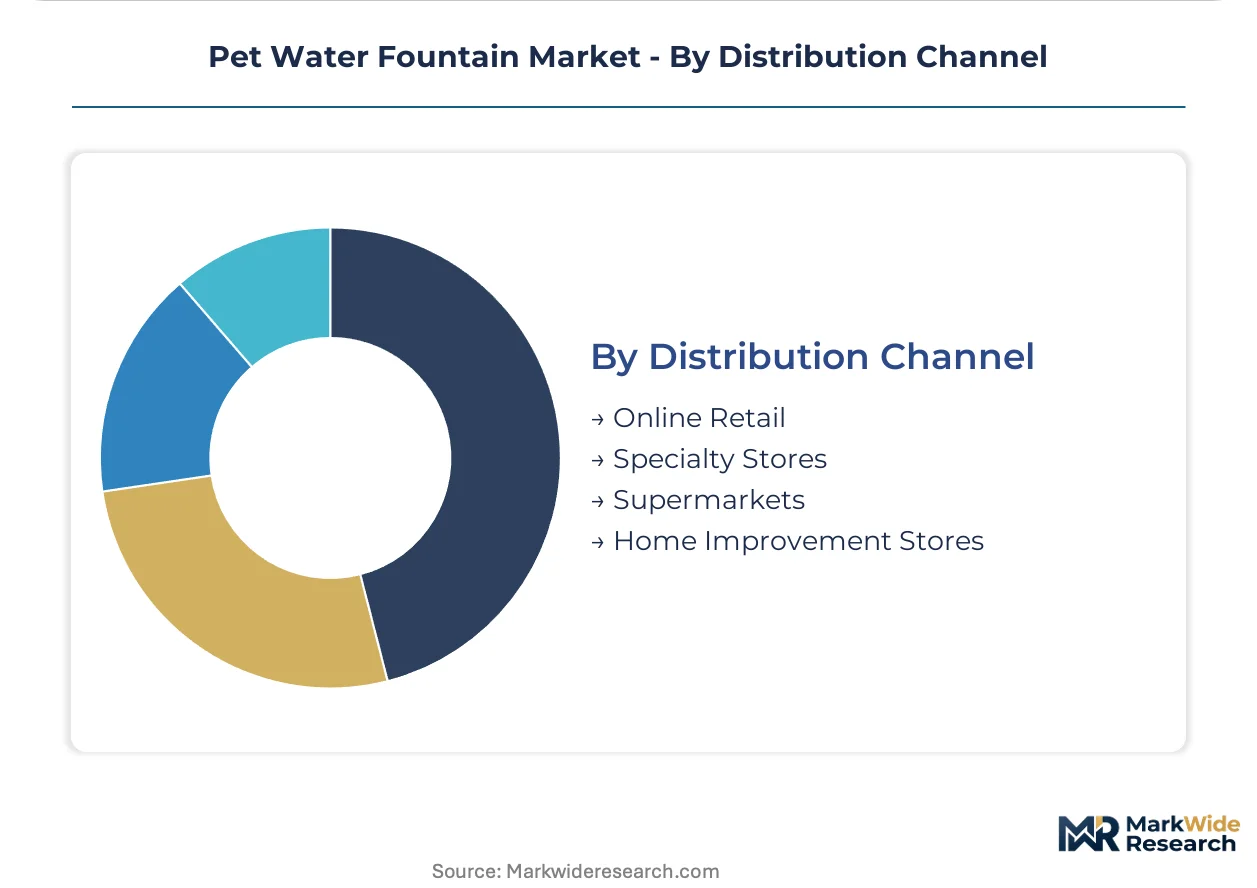
Distribution Channel:
Customer acquisition economics diverge sharply between recurring-revenue direct channels and episodic retail purchasing.
- Online Retail:Amazon Subscribe & Save and Chewy Autoship platforms capture recurring filter replenishment revenue previously lost to physical retail, concentrating in United States metropolitan markets with normalized consumable subscription expectations.
- Specialty Stores:Independent pet retailers and veterinary clinic partnerships build credibility through in-person consultation and clinical endorsement.
- Supermarkets:Mass-market placement for gravity-fed and entry-level electric fountain SKUs.
- Home Improvement Stores:Big-box channels targeting DIY-minded pet owners with installation accessories.
Supermarkets move the highest unit volumes; Online Retail is gaining share fastest through subscription lock-in mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for pet water fountains concentrates in the United States, where premium pet wellness spending and subscription-based filter replacement models drive recurring revenue streams. Multi-pet households across North American and European urban centers prioritize hydration monitoring technologies, accelerating substrate transitions from plastics to food-grade stainless steel. Regulatory pressure from consumer safety agencies in multiple jurisdictions is reshaping manufacturing footprints and compliance investments.
United States
Metropolitan pet owners in Los Angeles, New York, and Chicago drive premium segment demand through Chewy Autoship and Amazon Subscribe & Save normalization. The FDA Center for Veterinary Medicine oversees material safety claims for pet consumable devices, compelling reservoir reformulation. California Proposition 65 labeling requirements have forced chemical disclosure overhauls for fountain polymers and tubing assemblies, raising compliance costs for import-dependent brands operating through West Coast distribution hubs.
Germany
Urban cat owners in Berlin, Munich, and Hamburg adopt stainless steel fountains fastest within Europe, perceiving dermatological safety differentiation over plastic alternatives. The EU REACH framework restricts phthalate and heavy metal content in plastics, with Annex XVII forcing 12-18 month requalification timelines for new polymer grades. Manufacturing partnerships in Bavaria and Baden-Württemberg anchor ceramic artisan production for premium reservoir sourcing.
China
Brushless DC submersible motor production clusters in Guangdong province supply pump assemblies for electric fountain manufacturers worldwide. The country's national consumer product safety regulator enforces GB standards for electrical appliance safety in pet devices. Shenzhen and Dongguan industrial zones concentrate vertically integrated manufacturers with captive metallurgy capabilities, bypassing plastic compliance complexity entirely through stainless steel substrate dominance.
Japan
Tech-forward pet owners in Tokyo, Osaka, and Nagoya prioritize smart-home interoperability and UV-C LED sterilization modules for bacterial biofilm elimination. METI oversees electrical appliance safety certifications, while PMDA guidelines influence clinical-grade hydration monitoring device standards. Kanto region distributors specialize in premium ceramic fountain imports from Southeast Asian artisan partnerships.
United Kingdom
Multi-pet households in Greater London and the Southeast drive demand for high-capacity pump systems with filtration redundancy. The UK's national consumer protection framework enforces CE marking requirements for electrical pet devices post-Brexit transition. Midlands-based logistics hubs handle EU-originated stainless steel reservoir imports, navigating customs complexity for REACH-compliant substrate sourcing.
Pet Water Fountain Market Competitive Environment
Backward integration into pump motor and filtration subsystems dominates the current landscape as manufacturers defend margin positions against commodity competitors. The vendor base stratifies across three tiers: vertically integrated specialists with captive metallurgy capabilities, brand marketers dependent on Guangdong contract manufacturing, and ceramic artisan networks anchored in Southeast Asian production partnerships. Competitive intensity concentrates on substrate certification battles and subscription filter lock-in mechanics rather than hardware differentiation alone.
Within the vertically integrated tier, PETKIT exemplifies upstream control over electromechanical components. Among brand marketers with veterinary channel focus, PetSafe occupies a position tied to in-clinic placement programs. Pioneer Pet represents the ceramic artisan archetype through Southeast Asian manufacturing partnerships. These three anchors illustrate how competitive positioning diverges across metallurgy, clinical endorsement, and material craft vectors.
| Leading Market Players |
|---|
| Veken |
| Catit |
| PETKIT |
| Pioneer Pet |
| Petlibro |
| PetSafe |
| isYoung |
| Catgorie |
| Petmate |
| Others |
Value Chain & Pricing Dynamics
Multi-pet households concentrated in United States metropolitan markets anchor demand for subscription-linked fountain systems, locking pricing power into recurring filter replenishment models rather than transactional hardware margins. This buyer concentration enables premium tier extraction through Chewy Autoship and Amazon Subscribe & Save normalization, while import-dependent brands absorb California Proposition 65 compliance overhead that vertically integrated manufacturers bypass.
Pricing Analysis
Volume placements concentrate in mass-market plastic gravity fountains through big-box retail, while margin capture concentrates in stainless steel electric systems with subscription filter lock-in. Price differentiation rests on material certification grade—FDA-compliant food-grade 304 alloy commands 40-60% premiums over commodity polypropylene—and smart-sensor integration for UV-C sterilization modules. Pricing pressure intensifies in plastic tiers as EU REACH phthalate restrictions force 12-18 month polymer requalification timelines. Price-sensitive buyers cluster in emerging markets favoring non-powered gravity alternatives, while least-sensitive segments pay premium-mid-economy pricing differentiation for clinical-grade veterinary channel placement.
Supply Chain Analysis
Brushless DC submersible motor supply rests on Guangdong province production clusters, with food-grade stainless steel metallurgy drawing from Chinese and German captive foundries. Activated carbon and ion-exchange resin filtration media sources from United States specialty chemical producers and Japanese activated carbon specialists. Single-source vulnerability concentrates in Guangdong pump motor manufacturing, where dual-qualified vendor scarcity creates disruption exposure. Distribution runs through West Coast United States logistics hubs for import-dependent brands, while vertically integrated manufacturers ship direct from Shenzhen and Dongguan industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pump motor manufacturing capacity constraints in Guangdong province prop pricing power for brands with captive electromechanical production, constraining margin expansion for import-dependent competitors.
For Market Incumbents: Deepen backward integration into filtration cartridge geometries to defend against proprietary lock-in resistance from multi-brand retailers. Anchor capacity expansion in Bavaria and Baden-Württemberg ceramic artisan partnerships to bypass REACH plastic compliance entirely. Threat substitution from gravity fountain alternatives in price-sensitive emerging markets demands channel control through veterinary clinic exclusivity programs. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for filter auto-replenishment revenue capture previously lost to big-box retail. Target stainless steel fountain white space in German urban cat owner segments perceiving dermatological safety differentiation. Clinical-grade UV-C sterilization modules for post-surgical veterinary recovery represent underexploited application expansion with endorsement leverage. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated manufacturers with captive metallurgy capabilities in Guangdong and ceramic production partnerships in Southeast Asia. Long-term viability over a multi-year horizon rests on subscription filter replacement model normalization and smart-home interoperability certification. Watch FDA material safety claim enforcement trajectory as inflection indicator for substrate transition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Motors | Captive Guangdong electromechanical production defends margin against commodity competitors. |
| Subscription Filter Auto-Replenishment | Chewy Autoship and Amazon Subscribe & Save lock customer lifetime value in United States metros. |
| UV-C LED Sterilization Certification | FDA Center for Veterinary Medicine claims enable 40-60% premium over carbon-filtration alternatives. |
| Ceramic Artisan Manufacturing Partnerships | Southeast Asian production anchors premium positioning against stainless steel commoditization. |
| Matter Protocol Smart-Home Integration | Voice control and automated refill alerts open tech-forward urban owner premium positioning. |
Study Parameters
Document review covered FDA Center for Veterinary Medicine filings, EU REACH Annex XVII restriction updates, and California Proposition 65 chemical disclosure databases, complemented by interviews with pet product brand managers, veterinary clinic procurement leads, Guangdong pump motor manufacturing executives, and specialty retailer category buyers. Secondary validation drew from customs trade records for stainless steel reservoir imports, Amazon Subscribe & Save subscription velocity data, and Chewy Autoship replenishment pattern disclosures. Bottom-up unit economics triangulated against top-down category spending estimates.
Output models projected volume and value trajectories across the analysis window through segmentation by pump technology, material substrate, end-use application, and distribution channel. CAGRs derived from historical replacement cycle analysis, multi-pet household formation rates, and regulatory compliance cost pass-through elasticity. Industry-specific forecast inputs included brushless DC motor failure rate distributions and filter cartridge replacement frequency by water hardness region.
The model holds under stable REACH enforcement and FDA material claim oversight; deviation in California Proposition 65 expansion to additional polymer classes or Guangdong supply disruption would shift substrate transition timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Scratchers and Trees Market
Pet Care Products
Dog Crate Furniture Market
Pet Care Products
Asia-Pacific Pet Treats Market
Pet Care Products
Robotic Pets Market
Pet Care Products
Freeze Dried Dog Food Market
Pet Care Products
Small Dog Harness Market
Pet Care Products
Gcc Pet Food Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Europe Pet Smart Tracker Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
Pet Hair Care Market
Pet Care Products
Indestructible Dog Toys Market
Pet Care Products
United States Pet Market
Pet Care Products
Dog Bed Covers Market
Pet Care Products
Dog Brush Market
Pet Care Products
Dog Sunglasses Market