
 Student Stationery Market | 2026-2036
Student Stationery Market Size, Share, and Industry Trends Forecast 2026-2036
Student Stationery Market Insights
Digital note-taking platforms is fragmenting traditional notebook demand across secondary and higher education channels. Faber-Castell leverages its graphite and colored pencil heritage to sustain premium positioning in art-oriented student segments. Pilot Corporation anchors refillable gel pen systems that reduce per-unit waste while locking in recurring consumable sales. Shanghai M&G Stationery dominates domestic shelf space through deep distributor relationships and aggressive private-label positioning in China's retail channel.
Student stationery encompasses writing instruments, paper goods, and organizational tools manufactured from wood pulp, petroleum-derived polymers, or mineral pigments, with specifications governing lead hardness grades, paper GSM weights, and ink viscosity measured in centipoise. The category serves educational preparation, creative expression, and examination compliance across institutional and individual purchase contexts. Pens and pencils retain the largest revenue share within product type segmentation, though notebooks command higher per-transaction values in back-to-school purchasing windows. Online delivery models capture expanding share as educational institutions consolidate procurement through digital platforms, while plastic material formulations face substitution pressure from fiber-based alternatives in European regulatory environments.
EPA guidelines on volatile organic compound emissions influence ink and adhesive formulations for US-manufactured products, while REACH substance restrictions in Europe constrain phthalate plasticizer use in eraser and pen grip compounds. China's GB standards for student用品 safety specify heavy metal limits in colored coatings and migrate testing protocols for saliva-contact items. Stakeholders must monitor evolving chemical disclosure requirements across multiple jurisdictions while calibrating regional product portfolios to diverging compliance thresholds.
Market Dynamics
Digital note-taking platforms are compressing traditional paper-based consumption patterns while REACH substance restrictions force reformulation of plastic components across European supply chains.
Growth Catalysts
- Government education schemes:India's Sarva Shiksha Abhiyan and similar programs in Indonesia expand addressable student populations through subsidized enrollment and free textbook distribution.
- REACH compliance:European chemical disclosure mandates accelerate fiber-based material substitution, opening new supplier categories for eraser and grip manufacturers.
- Refillable systems:Pilot Corporation's gel pen architecture demonstrates how consumable-lock designs convert one-time buyers into recurring revenue streams.
Market Restraints
- Petroleum-derived polymer volatility:Polypropylene and ABS resin prices fluctuate with crude oil benchmarks, squeezing margin predictability for pen barrel and ruler manufacturers.
- Graphite supply concentration:Synthetic graphite production clusters in China's Heilongjiang province, creating single-source vulnerability for pencil lead suppliers.
- Digital substitution:Tablet-based examination systems in South Korean and Singaporean schools reduce per-student paper consumption during assessment windows.
Strategic Opportunities
- Rural India penetration:Kirana store networks in Bihar and Uttar Pradesh remain underserved by organized stationery distribution, offering first-mover shelf space advantages.
- EU Green Deal alignment:Bio-based plasticizer certifications under ECHA's developing framework position early adopters for preferential procurement in German and French institutional tenders.
- EdTech platform integration:Bundling physical notebooks with licensed digital content access codes creates hybrid subscription models for secondary education publishers.
Industry Challenges
- Heavy metal testing protocols:China's GB 21027 saliva-contact migration standards require specialized laboratory partnerships that smaller coating suppliers struggle to access.
- Multi-jurisdiction compliance staffing:Simultaneous EPA VOC tracking, REACH SVHC monitoring, and BIS certification management strain regulatory affairs teams at mid-size manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Student Stationery Market |
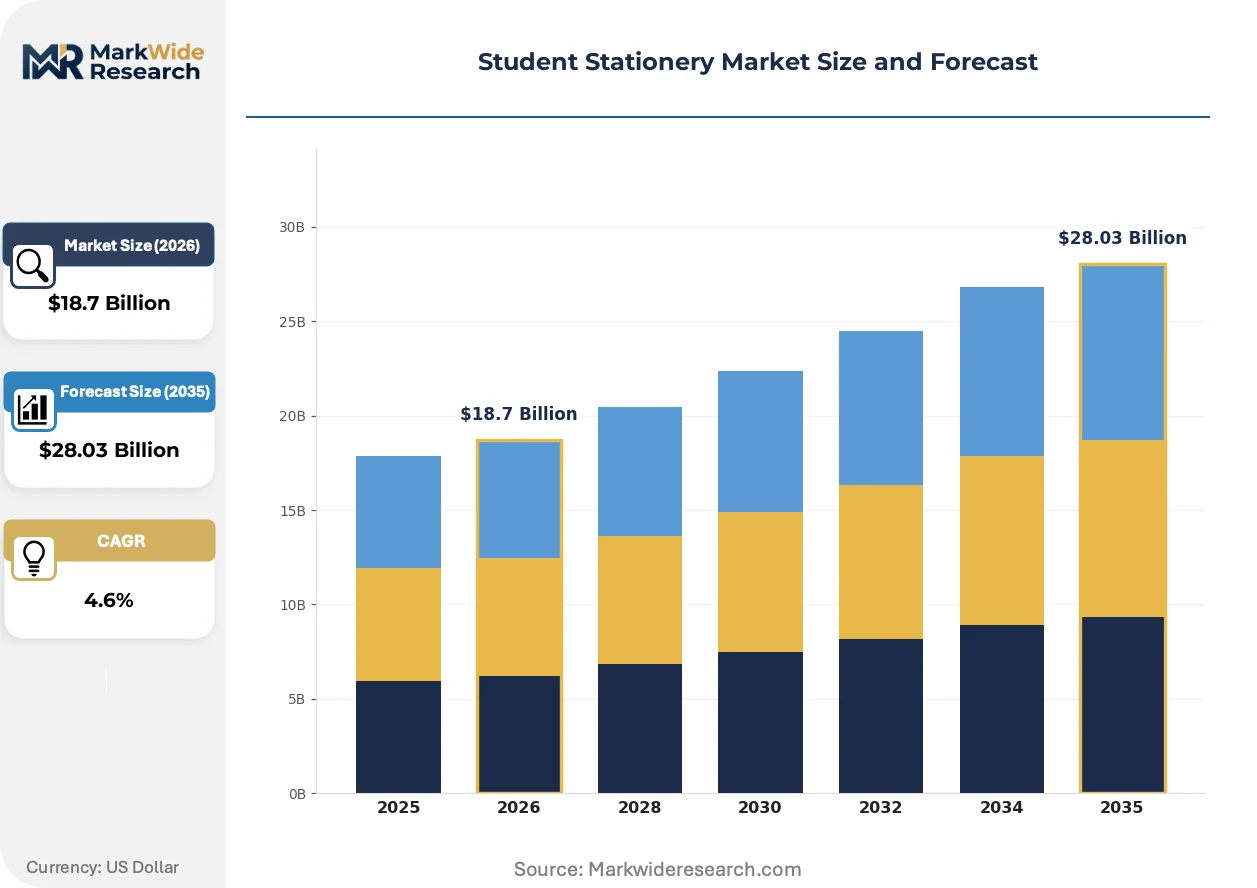
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pens, Pencils, Notebooks, Erasers Material: Paper, Plastic, Wood, Metal Delivery Model: Retail, Online, Wholesalers, Distributors Customer Type: Students, Schools, Colleges, Educational Institutions |
| Companies Covered | Faber-Castell, Pilot Corporation, Societe BIC, Kokuyo Camlin, 3M, STAEDTLER SE, Maped, Shanghai M&G Stationery, Pentel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Student Stationery Market Trends and Innovations
Material science advances and procurement digitization are restructuring how writing instruments and paper goods move from factory to student desk across institutional and retail channels.
Cloud-based note synchronization is virtualizing the functional role of bound notebooks in lecture capture. University students in North American and Nordic markets now treat paper as a supplementary sketch layer rather than primary record-keeping medium. This behavioral pivot compresses premium notebook transaction values while expanding demand for low-cost, single-subject formats.
ECHA's expanding candidate list of substances of very high concern is forcing reformulation of PVC-based erasers and TPR pen grips. Manufacturers serving German and French markets now prioritize TPE alternatives despite 15-20% raw material cost premiums. The regulatory pressure cascades through Asian export supply chains as EU-bound production lines require separate material handling protocols.
Consolidated digital procurement platforms are displacing traditional distributor relationships in school district purchasing. India's DIKSHA infrastructure and similar state-level e-procurement systems in Brazil enable direct manufacturer-to-institution contracts. This channel shift rewards suppliers with ERP integration capabilities and transparent lot-traceability documentation.
Student Stationery Market Segmentation
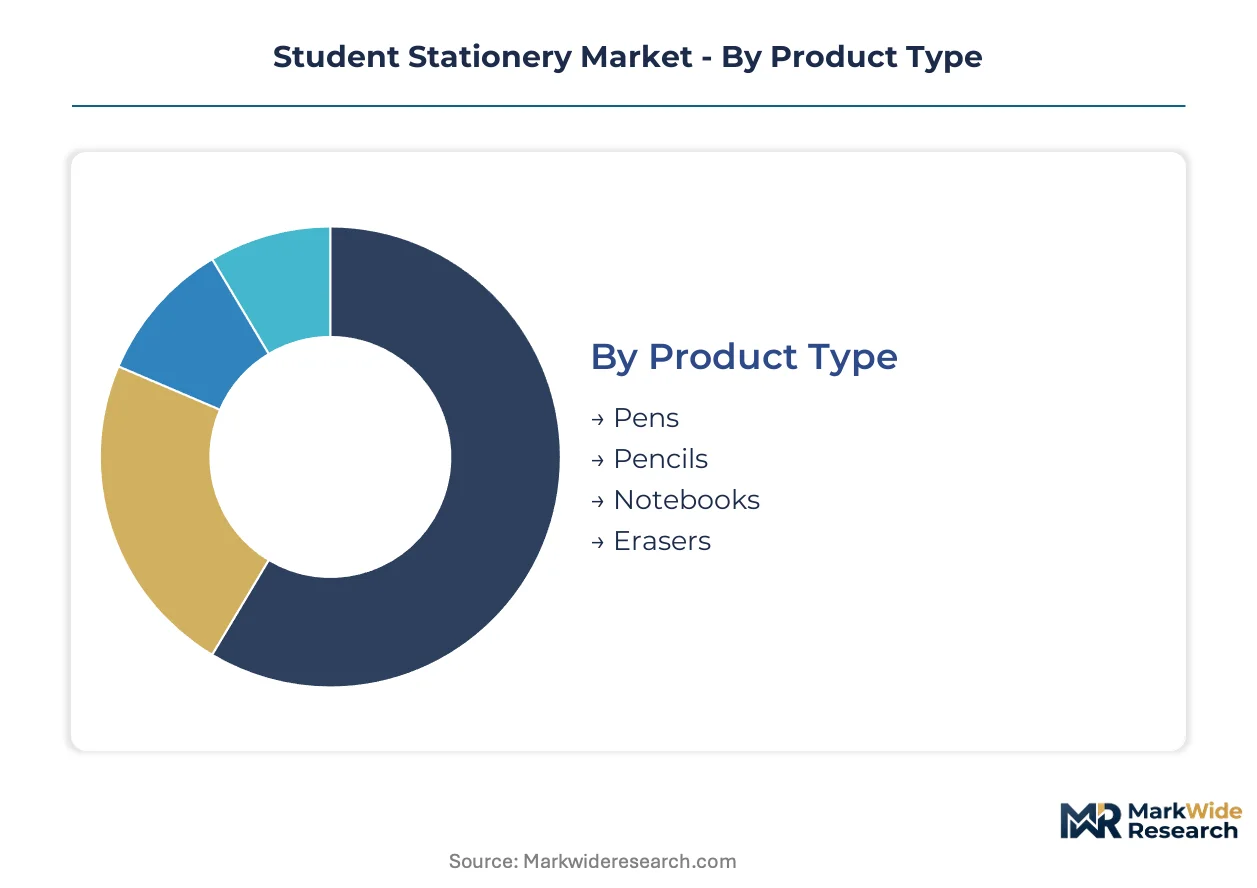
Segmentation in student stationery reveals how procurement authority, material compliance costs, and channel economics fragment addressable demand across institutional and individual buyer pools. Understanding these fault lines enables suppliers to calibrate SKU density, pricing architecture, and regulatory documentation investments.
Product Type:
Mature writing instruments dominate revenue concentration while emerging organizational formats reshape back-to-school purchasing patterns.
- Pens:Gel and ballpoint formulations specify ink viscosity in centipoise and barrel composition in ABS or polypropylene. Indian government school procurement through DIKSHA platforms concentrates volume demand for refillable systems in Bihar and Uttar Pradesh distribution networks.
- Pencils:Graphite cores grade from 9H to 9B hardness scales with cedar or basswood casings. REACH compliance in Europe forces synthetic graphite suppliers to document Heilongjiang province sourcing for EU-bound production lines.
- Notebooks:GSM weights range from 60 to 120 for ruling durability.
- Erasers:PVC and TPR compounds face phthalate substitution pressure under ECHA restrictions.
Pens handle the majority of throughput; notebooks are expanding most quickly on share as hybrid digital-physical formats gain institutional adoption.
Material:
Cost tier stratification separates premium fiber-based alternatives from commodity petroleum-derived formulations facing regulatory headwinds.
- Paper:Wood pulp sourcing from certified forestry operations governs premium positioning. European Green Deal procurement preferences in Germany and France now require FSC chain-of-custody documentation for institutional tenders.
- Plastic:Polypropylene and ABS resin prices track crude oil benchmarks with margin volatility. China's GB 21027 standards impose heavy metal migration testing for saliva-contact items that smaller coating suppliers struggle to certify.
- Wood:Cedar and basswood pencil casings specify grain density for sharpening consistency.
- Metal:Aluminum and brass components appear in premium mechanical pencil mechanisms.
Paper commands the highest volume position; plastic alternatives are climbing the fastest as bio-based certifications reshape EU sourcing requirements.
Delivery Model:
Customer type fragmentation splits procurement between centralized institutional buyers and dispersed individual transactions with diverging documentation needs.
- Retail:Kirana store networks in rural India and organized chains in urban China compete for shelf space. Shanghai M&G Stationery leverages deep distributor relationships to dominate domestic shelf allocation.
- Online:Direct-to-institution platforms displace traditional distributor margins. India's DIKSHA infrastructure and Brazil's state-level e-procurement systems enable manufacturer-to-school contracts with ERP integration requirements.
- Wholesalers:Volume aggregation serves smaller retailers with limited direct factory access.
- Distributors:Regional logistics networks manage last-mile delivery to educational institutions.
Retail channels process the highest transaction volume; online platforms are gaining share fastest as institutional procurement digitizes.
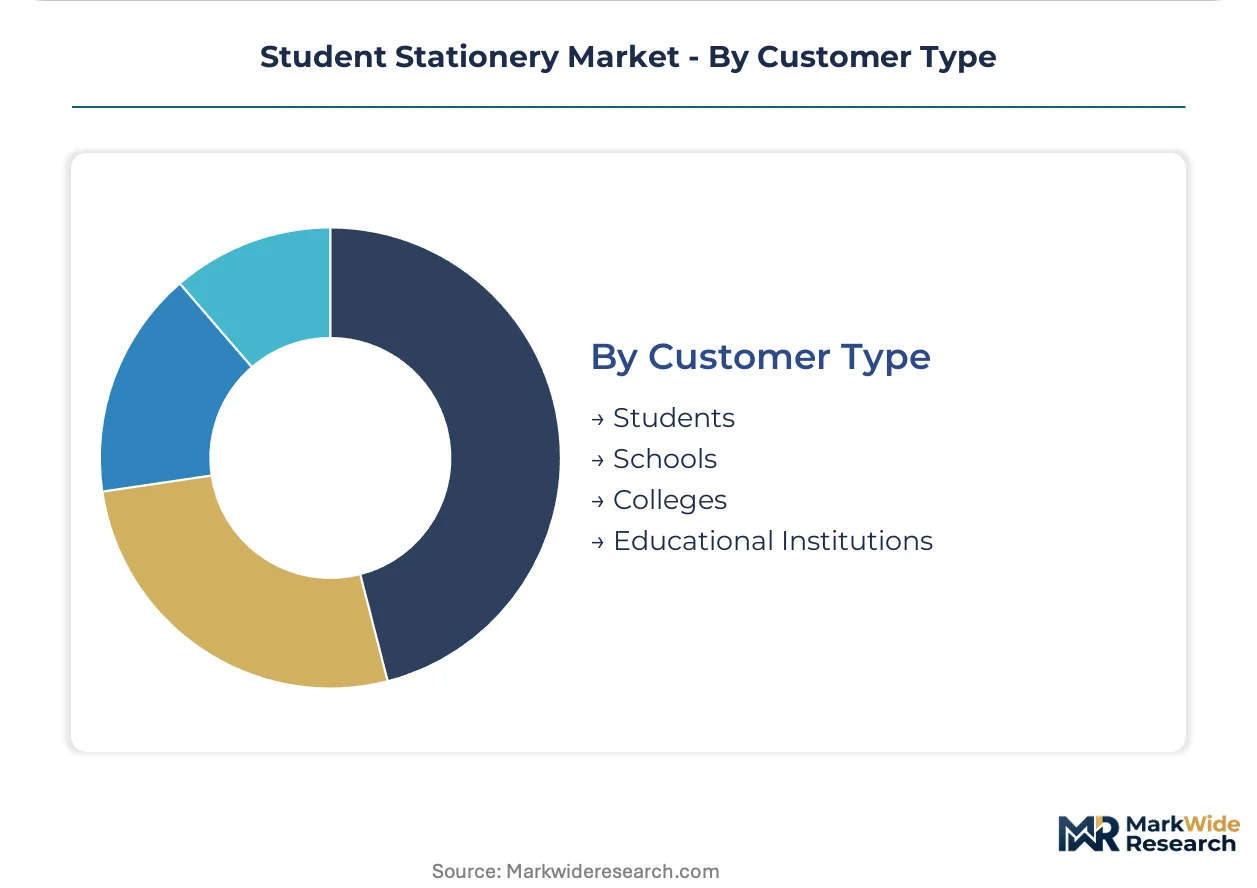
Customer Type:
Application concentration varies between individual purchasing authority and consolidated institutional budgets with diverging compliance documentation thresholds.
- Students:Individual purchasing decisions concentrate in back-to-school windows with price sensitivity. North American university students now treat paper notebooks as supplementary sketch layers rather than primary record-keeping media.
- Schools:K-12 enrollment expansion across Indonesia and India drives volume demand through government subsidy programs. Sarva Shiksha Abhiyan distribution expands addressable populations with free textbook and bundled stationery provision.
- Colleges:Higher education procurement consolidates through digital platforms with transparent lot-traceability requirements.
- Educational Institutions:Broad category captures vocational and supplementary education providers with fragmented purchasing patterns.
Schools represent the dominant volume segment; colleges are expanding most quickly as examination compliance drives specialized format demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports finished stationery to European Union institutional buyers while India's domestic manufacturing scales to serve government education programs. Trade corridors link Heilongjiang province graphite suppliers to pencil manufacturers in Germany and France.
China
Shanghai M&G Stationery leverages deep distributor relationships to dominate domestic retail shelf space. GB 21027 standards impose heavy metal migration testing for saliva-contact items that smaller coating suppliers struggle to certify. The Yangtze River Delta cluster concentrates pen barrel and mechanical pencil mechanism production for export-bound manufacturing lines.
India
Sarva Shiksha Abhiyan distribution expands addressable student populations through subsidized enrollment and free textbook provision. BIS certification requirements govern safety specifications for school-procured items. Kirana store networks in Bihar and Uttar Pradesh remain underserved by organized stationery distribution, offering first-mover shelf space advantages.
Germany
EU Green Deal procurement preferences now require FSC chain-of-custody documentation for institutional tenders. ECHA's expanding candidate list of substances of very high concern forces reformulation of PVC-based erasers and TPR pen grips. The Baden-Württemberg region hosts specialized coating suppliers adapting to REACH-compliant material handling protocols.
United States
EPA guidelines on volatile organic compound emissions influence ink and adhesive formulations for domestically manufactured products. North American university students now treat paper notebooks as supplementary sketch layers rather than primary record-keeping media. The Southeast corridor concentrates distribution warehousing serving consolidated school district digital procurement platforms.
Indonesia
Government education schemes expand addressable student populations through subsidized enrollment programs. The country's national standards body governs safety specifications for imported school supplies. Java-based manufacturing clusters assemble writing instruments for domestic distribution and regional export to ASEAN education markets.
Student Stationery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base spans vertically integrated manufacturers, regional distributors with logistics networks, and niche specialists in art-oriented formats. Three archetypes dominate: heritage brands with graphite and pigment expertise, scale-driven mass-market suppliers, and refillable-system innovators capturing recurring consumable revenue. Consolidation pressures intensify through direct-to-institution platform adoption and private-label positioning in emerging market retail.
Within the heritage-brand tier, Faber-Castell and STAEDTLER SE exemplify European manufacturers leveraging century-old graphite and colored pencil expertise to sustain premium positioning. Pilot Corporation occupies a position as a Japanese refillable-system specialist converting one-time buyers into recurring revenue streams through consumable-lock gel pen architectures. Shanghai M&G Stationery anchors the scale-driven archetype among China-based entities, representing how deep distributor relationships and aggressive private-label positioning capture domestic retail channel control.
| Leading Market Players |
|---|
| Faber-Castell |
| Pilot Corporation |
| Societe BIC |
| Kokuyo Camlin |
| 3M |
| STAEDTLER SE |
| Maped |
| Shanghai M&G Stationery |
| Pentel |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor's container cost dynamics amplify both supply concentration effects and downstream price stratification across gel pen and notebook categories. Polypropylene resin price indexation in supplier contracts passes crude oil volatility directly to pen barrel manufacturers, while REACH compliance premiums for EU-bound shipments create parallel pricing tiers that distributors must reconcile.
Pricing Analysis
Cost-plus contracts with polypropylene indexation dominate procurement between Chinese barrel manufacturers and Southeast Asian resin suppliers. Pricing stratifies across premium, standard, and economy tiers based on REACH certification status and FSC chain-of-custody documentation. Cost compression in standard-tier notebooks intensifies because Indian government procurement through DIKSHA platforms prioritizes unit economics over material certifications. School districts exhibit highest price sensitivity, while German institutional buyers absorb compliance premiums for bio-based plasticizer formulations.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements between Heilongjiang graphite producers and European pencil manufacturers. Manufacturing concentrates in China, India, and Indonesia, with raw material dependencies spanning synthetic graphite cores, FSC-certified wood pulp, and petroleum-derived polymers. Single-source vulnerability in Heilongjiang graphite supply threatens pencil lead continuity. Distribution runs through kirana store networks in rural India and consolidated e-procurement platforms for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern this market as India's DIKSHA infrastructure and Brazil's state-level e-procurement systems displace traditional distributor relationships. Interoperability between physical SKU systems and institutional ERP platforms determines supplier viability.
For Market Incumbents: Pre-empt channel displacement by securing API integration capabilities with DIKSHA and similar procurement platforms before second-tier competitors achieve technical compliance. Pilot Corporation's consumable-lock gel pen architecture demonstrates how recurring revenue models defend against private-label erosion. Backward integration into Heilongjiang graphite sourcing mitigates single-supplier concentration risk. For New Entrants and Emerging Players: Kirana store networks in Bihar and Uttar Pradesh offer shelf space penetration before organized distributors achieve rural coverage. Art-oriented student segments in secondary education channels show lowest incumbent lock-in and highest willingness to trial new brands. Partner with regional logistics aggregators to bypass established distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors refillable-system specialists with consumable-lock architectures over commodity pen manufacturers facing digital substitution. Long-term viability hinges on hybrid digital-physical bundling capabilities and institutional procurement platform integration. Monitor ECHA bio-based plasticizer certification adoption rates as inflection indicator for EU market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ERP Platform Integration | Direct DIKSHA connectivity enables manufacturer-to-school contracts bypassing distributor margins. |
| Bio-based Plasticizer Certification | ECHA framework alignment secures preferential positioning in German and French institutional tenders. |
| Heilongjiang Graphite Sourcing | Captive synthetic graphite supply insulates against single-source concentration vulnerability. |
| Hybrid Notebook-Digital Bundling | Licensed content access codes create recurring subscription models for secondary education publishers. |
| Rural India Distribution Buildout | First-mover kirana store relationships in Bihar and Uttar Pradesh capture underserved volume demand. |
Research Methodology
The analysis maps writing instruments, paper goods, and organizational tools sub-sectors, each validated through procurement officers at Indian state education departments, regulatory affairs leads at EU-bound manufacturers, distributor relationship managers at Shanghai M&G Stationery, and category buyers at organized retail chains. Secondary sources include BIS certification databases, ECHA SVHC candidate list updates, DIKSHA procurement disclosure records, and customs trade data for graphite and resin imports. Bottom-up SKU-level volume aggregation and top-down macro enrollment trend triangulation reconcile segment outputs.
Assumptions held fixed include current REACH substance restriction scope, prevailing crude oil price bands for resin indexation, and documented K-12 enrollment expansion rates across India and Indonesia. The projection horizon spans product type, material composition, delivery model, and customer type dimensions with regional regulatory cluster overlays. CAGRs derive from enrollment elasticity models calibrated against historical stationery consumption per student, with sensitivity testing for digital substitution rates and bio-based material cost premiums.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-native entrants or accelerated ECHA restriction expansion would shift outcomes. Macroeconomic volatility in petroleum feedstocks, unanticipated REACH substance additions, or technological deviation in examination digitization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Stationery Market
Office Supplies
Mechanical Pencil Leads Market
Office Supplies
Global Stationery and Supplies Market
Office Supplies
Marker Pens Market
Office Supplies
Europe School Stationery Supplies Market
Office Supplies
Custom Binders Market
Office Supplies
Perforated File Market
Office Supplies
Global Office Stationery Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
Copiers Market
Office Supplies
Pencil Sharpeners Market
Office Supplies
Office Supplies Market
Office Supplies
School Stationery Supplies Market
Office Supplies
Writing Instruments Market
Office Supplies
Stationery Products Market
Office Supplies
Malaysia Stationery Market