
 Printer Ink Cartridge Market | 2026-2036
Printer Ink Cartridge Market Size, Share, and Industry Trends Forecast 2026-2036
Printer Ink Cartridge Market Intelligence
The adoption of pigment-based cartridges for enhanced print longevity is redrawing the competitive landscape. HP Inc. leverages its vast distribution network to command a significant position in the home and small office segments. Epson Corporation specializes in its Piezoelectric Inkjet technology, offering precise droplet control. Canon Inc. competes across consumer and commercial printing with a broad portfolio, while Ninestar Corporation focuses on the compatible and remanufactured cartridge market.
A printer ink cartridge is a replaceable container holding ink, which is ejected onto paper during the printing process. Formulations typically consist of dye or pigment colorants suspended in a solvent, engineered for specific printer head technologies like thermal or piezoelectric inkjet. While inkjet cartridges command the home printing application, laser toner cartridges are prevalent in corporate offices. Demand from the commercial printing and industrial labeling sectors is driving innovation in pigment-based cartridges.
Regulations such as the European Union's RoHS directive restrict hazardous substances in electronic components, including cartridge chips. In the United States, EPA guidelines influence the management of spent cartridges, while ISO 14001 certification signals a commitment to environmental management systems. Navigating these divergent regional standards for e-waste and chemical composition remains a critical task for manufacturers seeking market access.
Market Dynamics
The market's central dynamic revolves around the conflict between the original equipment manufacturer (OEM) business model, which relies on high-margin, proprietary consumables, and the growing regulatory and consumer pressure for a circular economy promoting cartridge reuse and remanufacturing.
Growth Catalysts
- Industrial Labeling Demand:The need for durable, high-adhesion inks in manufacturing and logistics for product traceability and compliance with GHS labeling standards supports growth in specialized pigment-based cartridges.
- E-commerce Packaging:Expansion in e-commerce necessitates high-volume, on-demand printing for shipping labels, invoices, and customized branding on packages, driving consistent cartridge consumption in fulfillment centers.
- Anti-Counterfeit Formulations:The development of security inks with features like UV fluorescence or taggants provides a high-value application in protecting pharmaceuticals, luxury goods, and official documents from forgery.
Market Restraints
- Proprietary Chip Technology:OEMs embed microchips on cartridges that communicate with the printer, often blocking or creating friction for the use of third-party compatible or refilled alternatives, limiting consumer choice.
- Paperless Workflow Adoption:The corporate shift towards digital documentation, cloud storage, and electronic signatures is structurally reducing overall office printing volumes, thereby contracting the core market for ink cartridges.
- Input Cost Volatility:Prices for key ink components, including specialized pigments and solvents derived from petrochemical feedstocks, are subject to fluctuations in global commodity markets, impacting manufacturing costs.
Strategic Opportunities
- Ink Subscription Services:Offering ink-as-a-service models provides a recurring revenue stream, enhances customer retention, and uses smart printer technology to automate the replenishment process for home and small office users.
- Bio-based Ink Development:Formulating inks with renewable, biodegradable materials, such as soy or vegetable oils, addresses demand for sustainable products and aligns with corporate environmental, social, and governance (ESG) mandates.
- Binder Jetting for 3D Printing:Adapting inkjet head technology to deposit liquid binding agents in binder jetting 3D printing systems opens an adjacent industrial market in manufacturing, prototyping, and creating complex sand cores.
Industry Challenges
- Reverse Logistics for Circularity:Establishing efficient, cost-effective national programs for collecting, sorting, and processing spent cartridges to meet circular economy goals under frameworks like the EU's WEEE Directive presents a significant operational hurdle.
- Intellectual Property Litigation:Persistent and costly legal battles between OEMs and aftermarket suppliers over patents related to cartridge design and chip functionality create market uncertainty and divert resources from innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printer Ink Cartridge Market |
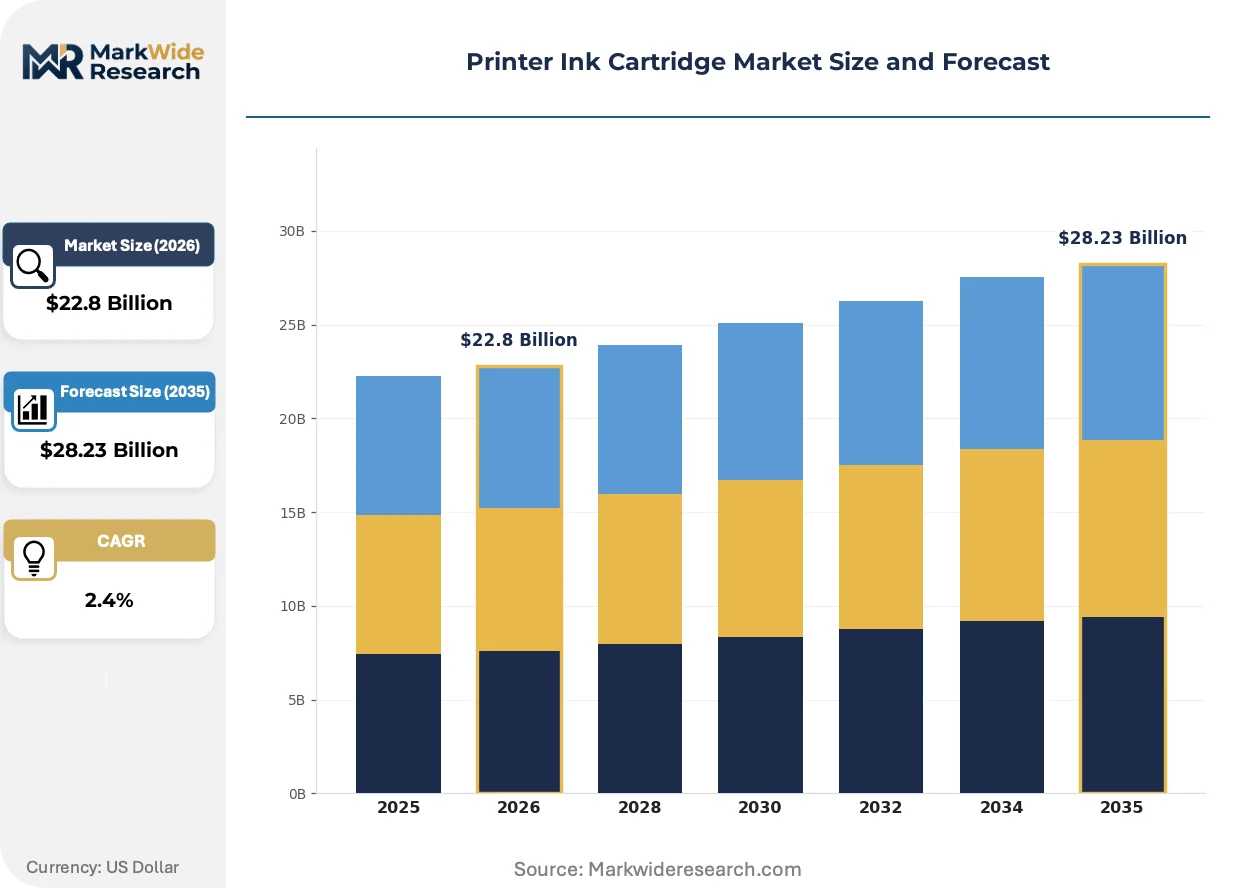
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $28.23 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
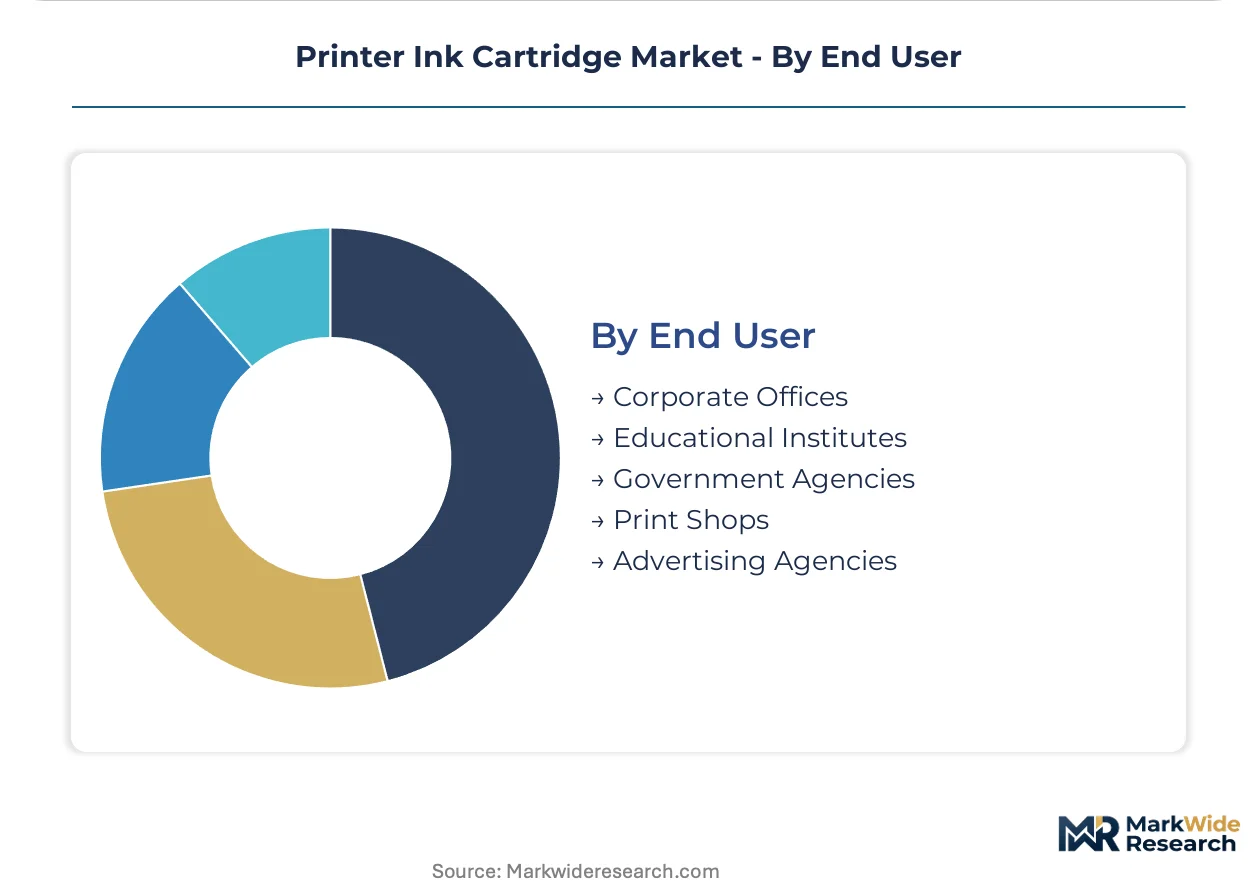
| Segmentation | Product Type: Inkjet Cartridges, Laser Toner Cartridges, Dye-Based Cartridges, Pigment-Based Cartridges, Solid Ink Cartridges Technology: Thermal Inkjet, Piezoelectric Inkjet, Electrophotography, Solid Ink Technology, Continuous Ink Supply System Application: Home Printing, Small Office Printing, Commercial Printing, Industrial Labeling, Photo Printing End User: Corporate Offices, Educational Institutes, Government Agencies, Print Shops, Advertising Agencies |
| Companies Covered | Brother Industries, Lexmark International, HP Inc., PrintRite, Ninestar Corporation, Canon Inc., Ricoh Company Ltd., Konica Minolta, Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printer Ink Cartridge Market Strategic Shifts & Innovations
Material science advancements and evolving environmental regulations are fundamentally altering the value proposition of printer ink. The focus is shifting from pure print performance to a lifecycle-aware model that incorporates sustainability, security, and service-based consumption into the product's core design.
Encapsulated pigment ink technology suspends colorant particles within a polymer resin, protecting them from environmental factors. Commercial printing and professional photography segments are adopting these inks for their superior archival properties and resistance to smudging and fading. This formulation is decomposing the traditional trade-off between the vibrant colors of dye-based inks and the durability of conventional pigments.
Implementation of the European Union's Corporate Sustainability Reporting Directive (CSRD) is forcing large companies to provide transparent data on their environmental impact. This includes waste generated from consumables like ink cartridges, influencing corporate procurement policies. Consequently, business-to-business sales are increasingly favoring manufacturers that offer verifiable cartridge recycling programs and products designed for the circular economy.
Corporate purchasing behavior is pivoting from transactional acquisitions of printers and supplies to all-inclusive managed print services (MPS) contracts. This shift consolidates purchasing decisions with MPS providers, who manage entire printer fleets and automate consumable replenishment. The trend is most visible in large North American and European enterprises seeking to optimize printing costs and reduce administrative overhead.
Printer Ink Cartridge Market Segmentation

The printer ink cartridge market segmentation reveals diverse product offerings and specialized applications crucial for understanding market dynamics. This analysis highlights how different cartridge types, technologies, applications, and end-users shape demand patterns. Market players must align product development with specific segment needs for sustained growth.
Product Type:
The distribution channel for printer ink cartridges often dictates the predominant product types available to consumers and businesses.
- Inkjet Cartridges:These containers hold liquid ink, typically dye or pigment-based, ejected through microscopic nozzles onto paper. Demand concentrates in the home and small office segments due to their versatility and lower initial printer cost.
- Laser Toner Cartridges:These cartridges contain fine dry powder toner, fused onto paper using heat and pressure. Corporate offices and high-volume print environments primarily utilize laser toner for its speed and cost-efficiency per page.
- Dye-Based Cartridges:These inks use colorants dissolved in a liquid, offering vibrant colors and smooth gradients for general printing.
- Pigment-Based Cartridges:These inks use solid color particles suspended in a liquid, providing superior fade resistance and water durability.
- Solid Ink Cartridges:These cartridges use wax-based ink sticks that melt and transfer to an imaging drum before printing.
Inkjet Cartridges dominates installed base. Pigment-Based Cartridges is where expansion concentrates.
Technology:
Printer technology dictates the ink formulation and cartridge design, directly impacting print quality and operational efficiency across various applications.
- Thermal Inkjet:This technology uses heat to create a bubble, forcing ink droplets through nozzles onto the paper. It remains prevalent in consumer and small office printers due to its cost-effectiveness and broad availability.
- Piezoelectric Inkjet:This technology employs piezoelectric crystals that vibrate to eject precise ink droplets without heat. Commercial printing and specialized industrial applications value its fine droplet control and compatibility with a wider range of inks.
- Electrophotography:This process forms images using electrostatic charges, primarily associated with laser printers and toner cartridges.
- Solid Ink Technology:This method melts solid ink sticks, which are then transferred to paper via an imaging drum, offering vibrant colors.
- Continuous Ink Supply System:This system uses large external ink tanks that refill internal reservoirs, reducing cartridge waste and operational costs for high-volume users.
Innovation in this segment focuses on enhanced droplet control and material compatibility to meet industrial demand.
Application:
The specific application drives demand for particular ink characteristics, influencing cartridge formulation and printer system design.
- Commercial Printing:This segment encompasses professional print shops, marketing agencies, and publishers producing brochures, magazines, and marketing materials. Demand here requires high-speed, consistent quality, and specialized color fidelity.
- Industrial Labeling:This application involves printing durable labels for product packaging, logistics, and compliance with GHS standards. Specialized pigment-based inks with high adhesion and resistance to harsh environments are essential for this sector.
- Home Printing:This application covers personal document printing, school assignments, and occasional photo prints by individual consumers.
- Small Office Printing:This segment includes businesses requiring routine document and basic marketing material printing with moderate volumes.
- Photo Printing:This application focuses on producing high-resolution, color-accurate photographic prints, often requiring specialized dye or pigment inks.
Growth in this segment is primarily driven by the increasing need for specialized, durable output.
End User:
Customer type significantly influences procurement patterns and the desired features in printing consumables, from volume capacity to environmental compliance.
- Corporate Offices:These entities require reliable, high-volume printing solutions for internal documents, reports, and presentations. Managed print services contracts are increasingly common, consolidating procurement.
- Print Shops:These businesses specialize in large-scale, professional printing services for external clients, demanding high-capacity, color-accurate, and cost-effective cartridge solutions. Their operations depend on consistent ink supply and color calibration.
- Educational Institutes:These organizations require printing for administrative tasks, student materials, and classroom activities, often balancing budget constraints with volume needs.
- Government Agencies:These bodies demand secure, reliable printing solutions for official documents, often with specific regulatory compliance requirements.
- Advertising Agencies:These firms require high-quality, color-accurate printing for proofs, presentations, and client mock-ups, prioritizing visual fidelity.
Procurement patterns within this segment are shifting towards managed services to optimize operational costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The printer ink cartridge market exhibits varying demand elasticity across different regions. Buyers in home and small office segments often prioritize cost-effectiveness, while industrial and commercial clients demand specialized formulations with high performance and reliability.
China
Industrial labeling and e-commerce packaging drive significant demand for specialized pigment-based inks in China. The country's GB standards influence material composition and environmental compliance for cartridges. Manufacturing and logistics hubs in the Pearl River Delta require high-volume, durable printing solutions.
Germany
Commercial printing and anti-counterfeit applications fuel demand for high-quality ink cartridges in Germany. The EU's RoHS directive impacts material composition, and the CSRD mandates transparent environmental reporting for companies. The Stuttgart region, a center for automotive and machinery, utilizes specialized industrial inks for component marking.
United States
The United States sees consistent demand from home users and corporate offices, with a growing shift towards managed print services. EPA guidelines influence the proper disposal and recycling of spent cartridges. Technology clusters like Silicon Valley require secure document printing and specialized inks for prototyping applications.
Japan
Japan's market emphasizes precision industrial applications and advanced piezoelectric inkjet technologies. METI initiatives support sustainable manufacturing practices and resource efficiency across industries. The Tokyo metropolitan area, home to major printer OEMs, drives significant research and development in new ink formulations.
India
E-commerce expansion and educational institutes contribute to the rising demand for ink cartridges in India. BIS standards ensure product quality and safety for printing consumables distributed nationwide. Bengaluru, a prominent tech and e-commerce hub, generates substantial demand for packaging and logistics labeling solutions.
Printer Ink Cartridge Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the printer ink cartridge market. The competitive structure is tiered, with original equipment manufacturers (OEMs) dominating proprietary technology, while aftermarket suppliers focus on cost-effective alternatives. Strategic archetypes include integrated printer manufacturers, specialized ink formulators, and remanufacturers. Intellectual property litigation and strategic partnerships remain dominant competitive moves across the industry.
Specialists in different market segments include HP Inc., which represents an integrated OEM model with a vast distribution network. Ninestar Corporation anchors the compatible and remanufactured cartridge market, offering cost-competitive solutions. Epson Corporation exemplifies an OEM specializing in piezoelectric inkjet technology, catering to precision printing applications.
| Leading Market Players |
|---|
| Brother Industries |
| Lexmark International |
| HP Inc. |
| PrintRite |
| Ninestar Corporation |
| Canon Inc. |
| Ricoh Company Ltd. |
| Konica Minolta |
| Epson Corporation |
| Others |
Cost & Logistics Intelligence
High-volume manufacturing capacity in Asia shapes both supply concentration and impacts price floors for standard ink cartridges. This dynamic creates a cost advantage for original equipment manufacturers and aftermarket suppliers with established production footprints.
Pricing Analysis
The European Union's RoHS directive dictates the pricing tier structure for cartridge components, influencing material costs and compliance investments. A subscription-based pricing model increasingly dominates the home and small office segments, offering predictable costs. Price differentiation stems from proprietary chip technology and specialized pigment-based ink formulations. Cost compression in the aftermarket segment is intensifying due to competition from refilled alternatives. Home users exhibit the most price sensitivity, while industrial labeling clients prioritize performance and reliability.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume standard cartridges, balancing cost efficiency with demand fluctuations. The supply chain for printer ink cartridges concentrates in China, Japan, and Germany. Raw material dependencies include specialized pigments, solvents derived from petrochemical feedstocks, and electronic microchips. Input cost volatility, particularly for petrochemicals, presents a structural risk across the supply chain. Downstream distribution runs through vast OEM networks and specialized aftermarket channels, increasingly integrating managed print services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The printer ink cartridge market presents a service-attach opportunity, with ink subscription services expanding faster than hardware sales. This shift enables recurring revenue streams and enhances customer retention for manufacturers.
For Market Incumbents:Compound existing distribution networks by integrating advanced managed print services for corporate clients. Invest in proprietary chip technology to maintain a competitive edge against aftermarket alternatives. Develop next-generation pigment-based inks with enhanced durability for industrial applications. Proactively address regulatory shifts towards circular economy models, such as the EU's WEEE Directive, to mitigate future compliance threats.
For New Entrants and Emerging Players:A certification fast-track for bio-based ink formulations offers a distinct market entry point, appealing to environmentally conscious consumers. Target specialized industrial applications like binder jetting for 3D printing, which requires specific material compatibility. The remanufactured cartridge segment in emerging markets, such as India, remains penetrable through cost-competitive, quality-certified offerings. A direct-to-consumer online subscription model provides an agile go-to-market angle.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized ink formulators and circular economy solution providers within this market. Long-term viability hinges on intellectual property protection and sustainable product lifecycles over the next decade. Acquisition targets should include companies with strong patent portfolios in piezoelectric inkjet technology or advanced material science. The adoption rate of bio-based inks across commercial printing serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Ink Subscription Services | Enhances customer retention and secures predictable recurring revenue streams for OEMs. |
| Invest in Bio-based Ink R&D | Addresses environmental mandates and appeals to corporate sustainability procurement policies. |
| Deepen Circular Economy Programs | Meets regulatory requirements like the EU's CSRD and improves brand perception. |
| Develop Specialized Industrial Inks | Captures high-value demand from industrial labeling and advanced manufacturing applications. |
| Secure IP for Cartridge Chips | Protects proprietary technology and limits competition from compatible aftermarket suppliers. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings within this analysis. The study gathered insights from OEM executives, aftermarket suppliers, industrial printing managers, and e-commerce fulfillment managers. Secondary validation involved reviewing EU RoHS directives, EPA guidelines, corporate sustainability reports, and industry association publications. A rigorous process of bottom-up and top-down triangulation ensured data consistency.
Sensitivity analysis informs the forecast framework, modeling market dynamics across the analysis window. The quantitative model segments the market by product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived through a comprehensive assessment of historical trends and projected market drivers. Industrial labeling growth rates and e-commerce expansion projections serve as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside significant shifts in digital transformation adoption or new regulatory mandates would require recalibration. Forecasts reflect assumptions regarding technological evolution and market acceptance of new printing solutions. Revision becomes warranted when global raw material pricing fluctuations cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Business Card Holder Market
Office Supplies
Global Office Stationery Market
Office Supplies
Greetings Cards Market
Office Supplies
Latin America School Stationery Supplies Market
Office Supplies
Global Office Peripherals and Products Market
Office Supplies
Malaysia Stationery Market
Office Supplies
Thumb Hole Book Page Holder Market
Office Supplies
Cutter Staplers Market
Office Supplies
Global Stationery and Supplies Market
Office Supplies
Copiers Market
Office Supplies
Stamp Pad Market
Office Supplies
Mechanical Pencil Leads Market
Office Supplies
Dictionary Pen Market
Office Supplies
Office Supplies Market
Office Supplies
Pencil Sharpeners Market
Office Supplies
Marker Pens Market