
 Europe School Stationery Supplies Market | 2026-2036
Europe School Stationery Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Europe School Stationery Supplies Market Intelligence
Educational institutions is bifurcating away from individual parent purchases across Europe. KAUT-BULLINGER & CO GmbH & Co.KG leverages direct institutional contracts to sustain volume throughput. Pelikan Vertriebsgesellschaft mbH & Co. KG anchors its position through specialized ink and writing instrument formulations for school-certified product lines. Lyreco SAS competes aggressively on catalog breadth and next-day delivery promises to municipal procurement offices.
Europe school stationery supplies encompass writing instruments, paper-based goods, filing systems, and ancillary classroom materials manufactured to EN 71 safety specifications and ISO 14001 environmental protocols, serving compulsory education from early childhood through upper secondary levels. Notebooks and pens constitute the mature volume core, while binders capture disproportionate margin contribution from institutional buyers seeking durability guarantees. Online retail channels represent the fastest-growing distribution vector, though specialty stores retain defensive positioning in premium and luxury price tiers where tactile evaluation drives selection.
REACH chemical safety standards and the EU Green Deal's recycled content mandates reshape product composition requirements, while CE marking under the Toy Safety Directive governs items marketed to early learners. France's DGCCRF and Germany's Federal Institute for Risk Assessment conduct parallel market surveillance, creating dual compliance exposure for cross-border suppliers. Stakeholders must monitor pending revisions to the EU Packaging and Packaging Waste Regulation, as extended producer responsibility obligations will recalibrate cost structures for plastic-intensive product categories.
Market Dynamics
Institutional procurement consolidation across Germany, France, and the United Kingdom is compressing supplier margins while amplifying volume concentration among contract-winning manufacturers. Ministries of Education in these three countries are mandating centralized purchasing frameworks that privilege durability certifications and recycled content thresholds over brand loyalty.
Growth Catalysts
- EU Green Deal recycled content mandates:The bloc's packaging waste directives are compelling manufacturers to reformulate plastic components toward biodegradable alternatives, creating first-mover advantages for certified suppliers.
- Germany's federal per-pupil allocation premiums:Bundesländer education budgets maintain Europe's highest stationery spend per student, anchoring volume demand for premium-grade filing systems and writing instruments.
- ISO 14001 environmental protocol adoption:Municipal procurement offices are embedding these certification requirements into tender specifications, filtering out uncertified competitors from institutional contracts.
Market Restraints
- Pulp input cost volatility:Nordic paper mill capacity constraints and energy price fluctuations are destabilizing notebook and binder margin structures for manufacturers without long-term fiber supply agreements.
- REACH chemical compliance friction:The European Chemicals Agency's expanding restricted substance lists are forcing reformulation cycles for ink solvents and plasticizers, extending product development timelines.
- Digital substitution pressure:Tablet-based learning platforms and cloud-based student assignment systems are compressing core paper product demand in upper secondary segments across Danish and Dutch school systems.
Strategic Opportunities
- Poland's underpenetrated institutional channel:Polish municipal education procurement remains fragmented among parent purchases, presenting white-space potential for direct-contract specialists with next-day logistics capabilities.
- CE marking under Toy Safety Directive convergence:Early childhood product lines face harmonized safety standards across EU member states, enabling scale economies for compliant manufacturers serving nursery and primary segments.
- Online catalog + municipal procurement portal integration:France's Chorus Pro and Germany's Vergabemarktplatz platforms are opening API-accessible channels that bypass traditional distributor markups.
Industry Challenges
- EN 71 safety testing timeline compression:Laboratory certification backlogs for new product launches are extending time-to-revenue by two to three quarters for seasonal back-to-school introductions.
- Biodegradable plastic process engineering gaps:European compounders lack sufficient technical talent in starch-based polymer formulation, constraining manufacturers' ability to meet EU Green Deal content targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe School Stationery Supplies Market |
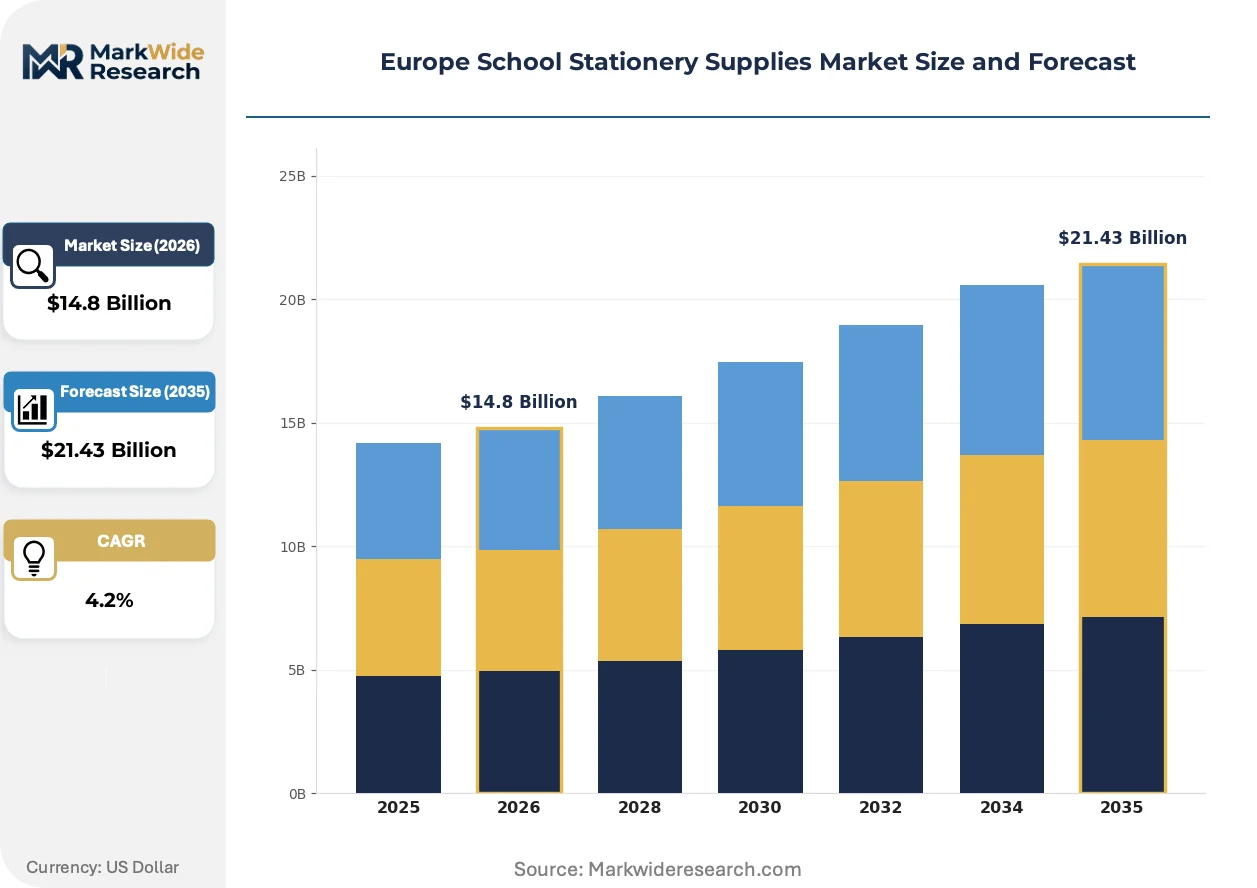
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pens, Pencils, Notebooks, Binders Customer Type: Students, Schools, Parents, Educational Institutions Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | KAUT-BULLINGER & CO GmbH & Co.KG, WH Smith High Street Limited, Lyreco SAS, Ardent Business Group Ltd, El Corte Inglés S.A., ADVEO FRANCE SAS, Ryman Ltd, Pelikan Vertriebsgesellschaft mbH & Co. KG, Herlitz, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe School Stationery Supplies Market Strategic Shifts & Innovations
Formulation chemistry and distribution logistics are converging to redefine product specifications and fulfillment expectations across European school supply channels. Manufacturers are racing to align material science advances with procurement platform digitization.
Plant-derived bioplastics derived from corn starch and sugarcane bagasse are replacing petroleum-based polypropylene in ruler, protractor, and storage box applications. German and Austrian institutional buyers are specifying these materials in framework agreements with 2027 compliance deadlines. The technology is miniaturizing production equipment footprints, enabling regional compounders to serve local school districts without centralized mega-facilities.
REACH chemical safety standards are expanding restricted substance lists to cover endocrine-disrupting phthalates in erasers and soft-grip pen barrels. Manufacturers must reformulate or face market exclusion from France's DGCCRF surveillance actions. Early childhood stationery segments face the steepest compliance costs due to stricter migration limits for mouthing-age products.
Municipal procurement offices are consolidating supplier relationships through multi-year framework agreements that bundle writing instruments, paper goods, and classroom furniture. Specialty distributors are losing share to integrated catalog operators with direct manufacturer relationships. This concentration is most visible in the United Kingdom's academy trust purchasing consortia, where single-source contracts now cover 60-plus school sites.
Europe School Stationery Supplies Market Segmentation
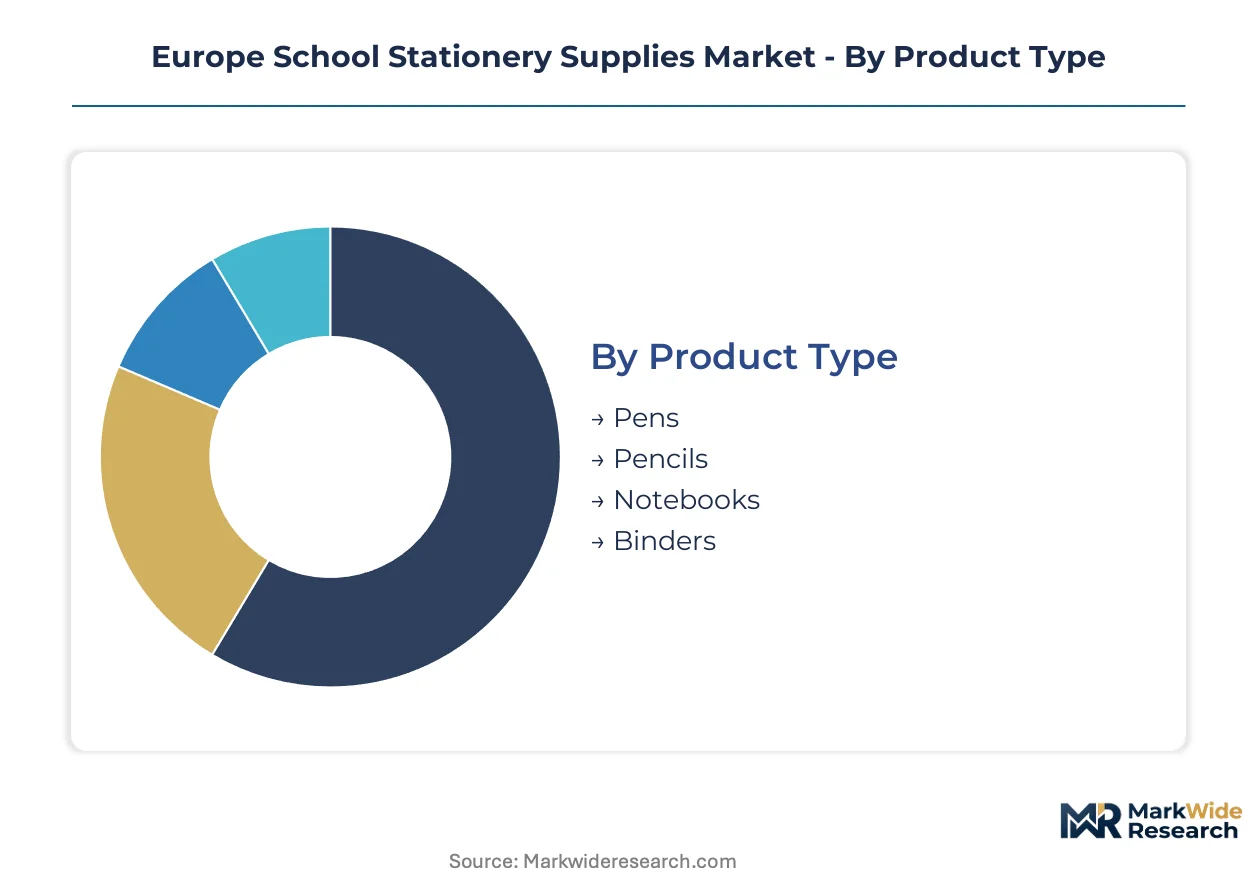
European school stationery procurement operates through four intersecting dimensions that determine compliance burden, margin structure, and channel access. Product specifications face divergent safety protocols across age cohorts, while institutional buyers impose certification requirements that reshape competitive positioning within each segment cluster.
Product Type:
REACH chemical safety standards and the EU Green Deal's recycled content mandates create tiered compliance exposure across product categories, with mouthing-age items facing the strictest migration limits.
- Notebooks:Paper-based products bound with wire or glue, subject to Nordic pulp supply constraints and EN 71 safety testing for early childhood lines. German Bundesländer education budgets anchor Europe's highest per-pupil allocations for premium-grade filing systems and paper goods, though energy price volatility destabilizes margin structures for manufacturers lacking long-term fiber agreements.
- Pens:Writing instruments incorporating ink reservoirs, nibs, and soft-grip barrels where ECHA's expanding restricted substance lists now target endocrine-disrupting phthalates. France's DGCCRF surveillance actions enforce reformulation timelines for ink solvents and plasticizers, extending product development cycles for seasonal back-to-school introductions.
- Pencils:Graphite-core instruments with wood or synthetic casings, governed by CE marking under the Toy Safety Directive for early learner segments.
- Binders:Filing systems capturing disproportionate margin contribution from institutional buyers seeking durability guarantees and ISO 14001 environmental certifications.
Notebooks handle the majority of throughput; pens are expanding most quickly on share as institutional buyers consolidate writing instrument contracts.
Customer Type:
Procurement consolidation across municipal education frameworks is compressing supplier margins while amplifying volume concentration among contract-winning manufacturers.
- Schools:Primary and secondary institutions operating under centralized purchasing frameworks mandated by Ministries of Education in Germany, France, and the United Kingdom. These buyers privilege durability certifications and recycled content thresholds over brand loyalty, filtering out uncertified competitors from institutional contracts.
- Educational Institutions:Nursery schools, vocational training centers, and academy trusts in the United Kingdom's purchasing consortia, where single-source contracts now cover 60-plus school sites and bundle stationery with classroom furniture.
- Students:Individual purchasers in upper secondary segments where tablet-based learning platforms and cloud-based assignment systems compress core paper product demand across Danish and Dutch school systems.
- Parents:Fragmented retail purchasers concentrated in Poland's underpenetrated institutional channel, where municipal procurement remains split among parent purchases rather than direct-contract frameworks.
Schools dominate absolute volume; educational institutions are climbing the fastest as framework agreements consolidate supplier relationships.
Distribution Channel:
Digital platform integration with municipal procurement portals is bypassing traditional distributor markups and reshaping fulfillment economics.
- Online Retail:E-commerce platforms representing the fastest-growing distribution vector, with France's Chorus Pro and Germany's Vergabemarktplatz platforms opening API-accessible channels that connect manufacturers directly to municipal procurement offices.
- Wholesale:Bulk supply relationships serving institutional buyers with next-day logistics capabilities, where integrated catalog operators with direct manufacturer relationships are displacing specialty distributors.
- Specialty Stores:Retail outlets retaining defensive positioning in premium and luxury price tiers where tactile evaluation drives selection.
- Supermarkets:Mass-market retail channels serving economy-tier parent purchases with limited certification transparency.
Wholesale channels manage the greatest institutional throughput; online retail is gaining share fastest through procurement portal integration.
Price Tier:
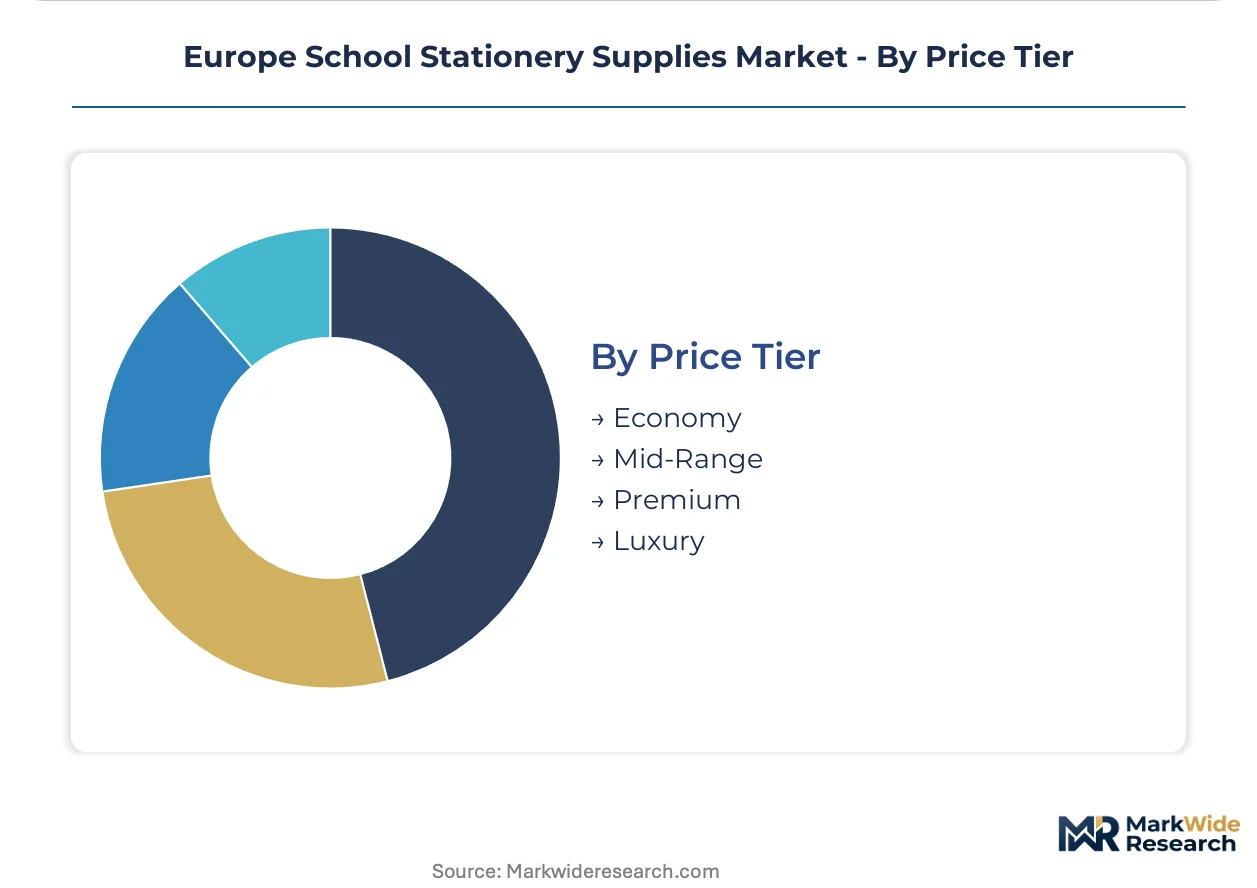
Certification grade and volume scale stratify pricing across four distinct levels that align with buyer procurement authority and product durability requirements.
- Premium:Products meeting ISO 14001 environmental protocols and EN 71 safety specifications, specified by German and Austrian institutional buyers with 2027 compliance deadlines for plant-derived bioplastics.
- Mid-Range:Certified products balancing durability guarantees with cost constraints, capturing the bulk of French and United Kingdom municipal framework agreements.
- Economy:Price-competitive lines serving parent purchases in fragmented procurement environments with minimal certification requirements.
- Luxury:High-end writing instruments and leather-bound goods distributed through specialty stores where tactile evaluation determines selection.
Mid-range products absorb the majority of institutional procurement volume; premium tier lines show the steepest expansion trajectory as EU Green Deal mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers dominate export flows to institutional buyers across Central and Eastern Europe, with Austrian compounders supplying bioplastic formulations to Nordic school systems seeking EU Green Deal compliance.
Germany
Bundesländer education budgets sustain Europe's highest per-pupil stationery allocations, anchoring volume demand for premium filing systems and writing instruments. The Federal Institute for Risk Assessment conducts parallel market surveillance with France's DGCCRF, creating dual compliance exposure for cross-border suppliers. Bavaria's industrial corridor hosts specialized ink formulators serving school-certified product lines with 2027 bioplastic deadlines.
France
Centralized purchasing frameworks through Chorus Pro privilege durability certifications and recycled content thresholds over brand loyalty. DGCCRF surveillance actions enforce REACH chemical compliance timelines for ink solvents and plasticizers in erasers and soft-grip pen barrels. The Île-de-France region concentrates municipal procurement offices integrating API-accessible channels that bypass traditional distributor markups.
United Kingdom
Academy trust purchasing consortia now consolidate single-source contracts covering 60-plus school sites, bundling stationery with classroom furniture. CE marking under the Toy Safety Directive governs early childhood items marketed across England and Scotland. The Midlands corridor hosts integrated catalog operators displacing specialty distributors through direct manufacturer relationships.
Poland
Municipal education procurement remains fragmented among parent purchases rather than direct-contract frameworks, presenting white-space potential for logistics-capable specialists. The country's national consumer protection regulator enforces EN 71 safety specifications for early learner segments. Warsaw's distribution hubs serve underpenetrated institutional channels where next-day delivery capabilities remain scarce.
Netherlands
Tablet-based learning platforms and cloud-based assignment systems compress core paper product demand in upper secondary segments. The Dutch national chemicals authority implements ECHA restricted substance lists for endocrine-disrupting phthalates in school supplies. Rotterdam's logistics cluster supports cross-border wholesale operations serving Belgian and German institutional buyers.
Europe School Stationery Supplies Market Key Industry Players
Listed leaders compete with private specialists across procurement platform integration, with family-owned German manufacturers retaining institutional contract dominance through multi-generation supplier relationships. The vendor base stratifies into three tiers: integrated catalog operators with direct logistics networks, specialized formulators holding ISO 14001 environmental certifications, and regional distributors serving fragmented parent-purchase markets. Consolidation accelerates through framework agreement bundling and API-accessible municipal portal integration.
Within the institutional-contract tier, KAUT-BULLINGER & CO GmbH & Co.KG and Pelikan Vertriebsgesellschaft mbH & Co. KG exemplify German family-owned structures leveraging direct Bundesländer relationships, while Lyreco SAS occupies a position among integrated catalog operators competing on next-day delivery promises to municipal procurement offices.
| Leading Market Players |
|---|
| KAUT-BULLINGER & CO GmbH & Co.KG |
| WH Smith High Street Limited |
| Lyreco SAS |
| Ardent Business Group Ltd |
| El Corte Inglés S.A. |
| ADVEO FRANCE SAS |
| Ryman Ltd |
| Pelikan Vertriebsgesellschaft mbH & Co. KG |
| Herlitz |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles for Nordic pulp feedstock concentrate pricing power among German manufacturers with long-term fiber agreements, compressing margins for spot-market buyers. This lead-time asymmetry shapes how institutional procurement offices negotiate framework terms across Bundesländer education budgets.
Pricing Analysis
Bioplastic formulation premiums over petroleum-based polypropylene establish a three-tier pricing structure across premium, standard, and economy levels. Certification grade under ISO 14001 and EN 71 safety tiers drives price differentiation, with municipal buyers in Germany and Austria specifying plant-derived materials for 2027 compliance deadlines. Cost compression in economy-tier notebooks and pens is intensifying because Nordic paper mill capacity constraints and energy price volatility destabilize margin structures. Parent purchasers in Poland's fragmented retail channel exhibit the highest price sensitivity, while German institutional buyers with federal per-pupil allocations show the least.
Supply Chain Analysis
Germany and Austria anchor bioplastic compounder networks serving school-certified product lines, while Nordic paper mills supply fiber for notebook and binder production. Starch-based polymer formulations and graphite-core pencil casings draw from agricultural feedstock and synthetic material streams respectively. Single-source vulnerability concentrates in Nordic pulp suppliers, where mill capacity constraints create chokepoints for paper-based goods. Distribution runs through integrated catalog operators with direct manufacturer relationships, displacing specialty distributors in municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital substitution through tablet-based learning platforms and cloud-based assignment systems threatens core paper product demand, forcing incumbents to defend material relevance against screen-based alternatives.
For Market Incumbents: Secure multi-year fiber supply agreements with Nordic mills to insulate margin structures from pulp input cost volatility. Deepen backward integration into starch-based polymer formulation to meet EU Green Deal recycled content mandates before 2027 compliance deadlines, locking out uncertified competitors from German institutional tenders.
For New Entrants and Emerging Players: Next-day logistics capabilities in Poland's underpenetrated institutional channel represent the most penetrable white-space opportunity, where municipal procurement remains fragmented among parent purchases. Target direct-contract relationships with Warsaw education procurement offices, leveraging API-accessible portal integration to bypass traditional distributor markups.
For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned German manufacturers with dormant ISO 14001 certifications and established Bundesländer relationships. Five-to-ten year viability hinges on bioplastic transition execution rather than legacy petroleum-based product lines. Watch for ECHA expansion of restricted substance lists as the inflection signal for reformulation cost spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioplastic Formulation Transition | EU Green Deal mandates compel starch-based polymer investment to retain German institutional contracts. |
| Direct Procurement Portal Integration | API connectivity with France's Chorus Pro and Germany's Vergabemarktplatz bypasses distributor markups. |
| Long-term Fiber Supply Agreements | Nordic mill partnerships insulate notebook margins from energy price volatility and capacity constraints. |
| ISO 14001 Certification Investment | Municipal tender specifications filter out uncertified competitors from framework agreements. |
| Poland Distribution Network Buildout | Next-day logistics capabilities capture white-space in fragmented municipal procurement environments. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with procurement officers at German Bundesländer education ministries, French municipal purchasing consortia, and UK academy trust operators, alongside secondary validation through EU customs trade data, REACH regulatory filings, and ISO certification registries. Bottom-up volume estimates from institutional contract disclosures triangulated against top-down education budget allocations across member states.
Across the projection horizon, the analytical framework modeled demand through four segmentation dimensions: product type, customer archetype, distribution channel, and price tier, with bioplastic compliance deadlines and digital substitution rates as industry-specific forecast inputs. CAGRs derived from historical procurement spend patterns and mandated allocation adjustments.
Underlying assumptions cover stable EU Green Deal implementation timelines and Nordic pulp supply continuity, with deviation risk concentrated in ECHA regulatory expansion and energy price volatility. Recalibration cycles align with material shifts in institutional procurement consolidation and bioplastic process engineering advances.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Global Stationery and Supplies Market
Office Supplies
Acrylic Marker Pen Market
Office Supplies
Dictionary Pen Market
Office Supplies
Marker Pens Market
Office Supplies
Pencil Sharpeners Market
Office Supplies
Global Office Peripherals and Products Market
Office Supplies
Custom Binders Market
Office Supplies
Printer Ink Cartridge Market
Office Supplies
Copiers Market
Office Supplies
Writing Instruments Market
Office Supplies
Malaysia Stationery Market
Office Supplies
Letter Opener Market
Office Supplies
Greetings Cards Market
Office Supplies
Student Stationery Market
Office Supplies
Cutter Staplers Market
Office Supplies
School Stationery Supplies Market