
 Copiers Market | 2026-2036
Copiers Market Size, Share, and Industry Trends Forecast 2026-2036
Copiers Market Analysis
Asset-light leasing and managed print services is rewriting competitive entry barriers across the copier landscape. Canon Inc. leverages its captive finance arm to bundle hardware with per-page service contracts, locking in multi-year revenue streams. Xerox Corporation anchors its position through extensive channel control over direct sales fleets serving large enterprises. Kyocera Document Solutions Inc. differentiates via long-life ceramic drum technology that reduces total cost of ownership for high-volume government users.
Copiers are electromechanical devices that reproduce text and images onto paper through xerographic, inkjet, or laser processes, typically operating at speeds from 20 to 100 pages per minute with resolutions exceeding 600 dots per inch. Their primary commercial purpose centers on decentralized document production, archival duplication, and administrative workflow support in organizations where digital-only distribution remains impractical. Multifunction devices integrating printing, scanning, and cloud connectivity now command the dominant share of new unit shipments as organizations consolidate hardware footprints. Laser technology sustains margin pools in enterprise segments where duty cycles exceed 10,000 pages monthly, while inkjet systems compete aggressively for small business placements through lower acquisition costs.
The United States Environmental Protection Agency governs energy consumption through ENERGY STAR specifications that disqualify inefficient models from federal procurement lists. Japan's Ministry of Economy, Trade and Industry enforces Top Runner standards that progressively tighten standby power limits, compelling manufacturers to redesign power management circuits. The European Union's Ecodesign Directive and RoHS restrictions on hazardous substances collectively shape material selection and recyclability requirements for equipment sold across member states. Stakeholders must monitor whether emerging right-to-repair regulations in multiple jurisdictions will disrupt existing service revenue models tied to proprietary consumables and technician-dependent maintenance protocols.
Market Dynamics
Energy efficiency mandates under the EU Ecodesign Directive and comparable frameworks in Japan and the United States are accelerating hardware refresh cycles across the copier landscape. Public-sector procurement rules in Germany now favor multifunction devices with integrated document management capabilities, concentrating demand among vendors capable of bundling hardware with per-page service contracts.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby power limits are compelling organizations to replace aging equipment, creating replacement demand across member states.
- Hybrid learning models:Educational institutions require decentralized document production for blended classroom environments, sustaining placement volumes.
- Ceramic drum technology:Extended component lifespans reduce total cost of ownership for high-volume government users, accelerating adoption in public sector.
Market Restraints
- Toner supply concentration:Proprietary consumables lock buyers into single-vendor ecosystems, limiting price competition and switching flexibility.
- Semiconductor input volatility:Controller chip shortages disrupt production schedules and extend lead times for enterprise-grade systems.
- Cloud document substitution:Digital distribution platforms reduce physical duplication requirements in administrative workflows.
Strategic Opportunities
- Right-to-repair regulations:Emerging legislation across multiple jurisdictions threatens proprietary service revenue models, opening independent maintenance channels.
- India educational infrastructure:Underpenetrated public school systems present volume opportunities for entry-level multifunction devices.
- AI-powered document analytics:Convergence of optical character recognition with automated workflow classification creates premium pricing tiers.
Industry Challenges
- Field service technician scarcity:Specialized electromechanical repair skills are aging out of the workforce faster than training programs replenish supply.
- Legacy system integration:Enterprise content management platforms require complex API configurations to connect with existing document archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copiers Market |
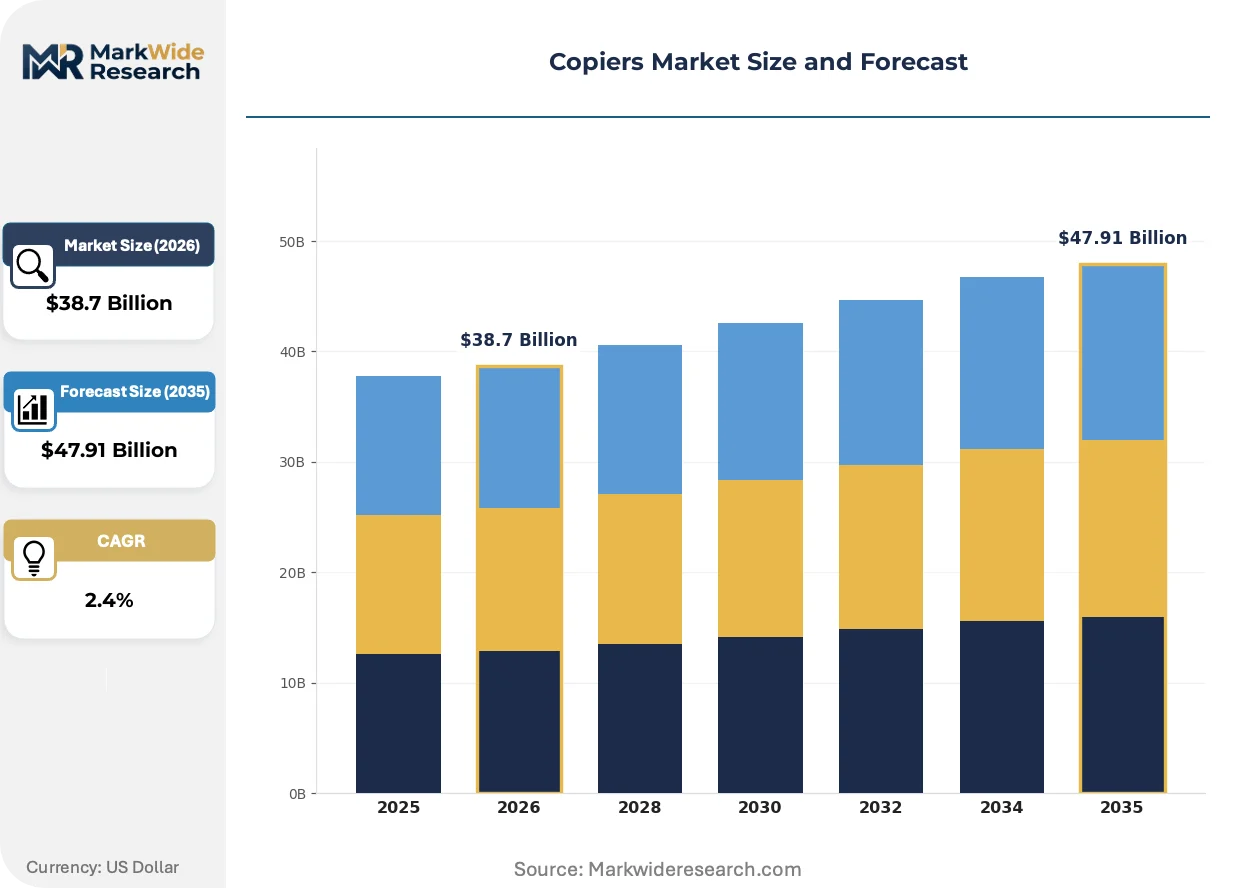
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $47.91 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser, Inkjet, Digital, Multifunction End User: Small Businesses, Large Enterprises, Educational Institutions, Government Agencies Technology: Color Printing, High-Speed Printing, Wireless Connectivity, Cloud Integration Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Canon Inc., HP Inc., Xerox Corporation, Ricoh, Brother Industries, Ltd., Konica Minolta, Inc., Kyocera Document Solutions Inc., Sharp Corporation, Lexmark International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copiers Market Emerging Trajectories
Cloud-native document workflows are compressing the traditional copier value proposition from hardware ownership toward subscription-based output management. Vendors now embed edge computing capabilities directly into multifunction devices to enable real-time collaboration without centralized server dependency.
AI-powered predictive maintenance algorithms are digitizing service delivery models across enterprise fleets. Manufacturers embed vibration sensors and page-count analytics directly into drum assemblies to forecast component failure before operational interruption occurs. Large financial services buyers in the United States now mandate predictive uptime guarantees as standard procurement terms, compressing competitive differentiation around mean-time-between-failures metrics.
Japan's Ministry of Economy, Trade and Industry enforces progressively tightening Top Runner standby power standards that disqualify inefficient models from public procurement lists. Domestic manufacturers redesign power management circuits to meet sub-watt idle consumption thresholds. Enterprise segments with 24-hour operational requirements face the steepest compliance costs, driving consolidation toward vendors with captive semiconductor fabrication capabilities.
Educational institutions are consolidating vendor relationships through centralized purchasing cooperatives that unbundle hardware acquisition from consumables supply. K-12 districts in Texas and California now negotiate multi-year enterprise agreements covering thousands of sites under single contract structures. This concentration shifts negotiating leverage toward buyers capable of guaranteeing minimum page volumes across extended replacement cycles.
Copiers Market Segmentation
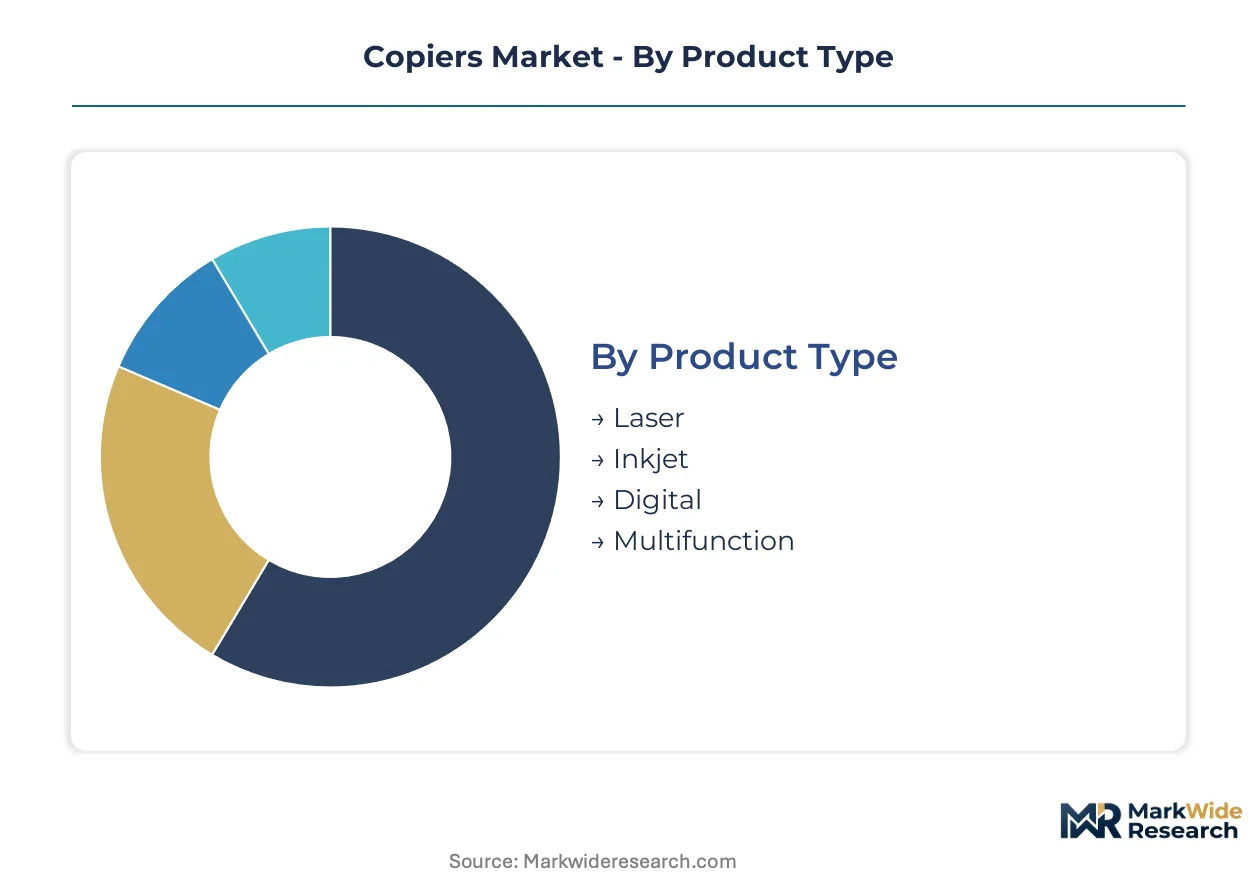
Copiers serve divergent operational profiles across document volumes, duty cycles, and integration requirements. Segmentation reveals where hardware margins concentrate versus where service revenue and consumables lock-in dominate commercial outcomes.
Product Type:
Cost tier differentiation separates acquisition-heavy placements from lifetime-value-optimized contracts across organizational budgets.
- Laser:Electrophotographic imaging through toner fusion delivers speeds exceeding 40 pages per minute with sub-cent per-page economics. Demand concentrates in United States financial services and legal sectors where archival-quality output and high duty cycles justify premium hardware investment.
- Multifunction:Integrated scanning, printing, and document routing consolidate hardware footprints while embedding vendors into workflow infrastructure. German public-sector procurement now mandates these configurations, bundling hardware with per-page service agreements that extend replacement cycles.
- Inkjet:Piezoelectric or thermal droplet deposition suits intermittent use patterns with lower acquisition costs.
- Digital:Standalone duplication without network connectivity serves legacy archival requirements in regulated industries.
Laser commands the established base. The steepest expansion runs through Multifunction.
End User:
Customer type determines contract structure, with volume guarantees and managed print services penetration varying sharply across organizational scale.
- Large Enterprises:Centralized procurement teams negotiate fleet-wide agreements with predictive uptime SLAs and automated supply replenishment. United States insurance and banking verticals now require AI-powered predictive maintenance as standard terms, compressing vendor selection around mean-time-between-failures performance.
- Educational Institutions:Hybrid learning models sustain decentralized document production for blended classroom environments. Texas and California K-12 districts consolidate thousands of sites under centralized purchasing cooperatives that unbundle hardware from consumables supply.
- Government Agencies:Compliance-driven refresh cycles dominate procurement, with EU Ecodesign Directive mandates accelerating equipment turnover.
- Small Businesses:Price-sensitive acquisition patterns favor lower-duty-cycle devices with minimal service attachment.
Large Enterprises command the established base. Educational Institutions show the steepest expansion trajectory.
Technology:
Application-specific capabilities determine pricing power, with workflow integration features commanding premium positioning over baseline output functions.
- Cloud Integration:Native connectivity to enterprise content management platforms enables serverless document workflows and real-time collaboration. Japan's METI Top Runner standards for standby power consumption drive hardware redesigns that favor edge-computing architectures with reduced centralized infrastructure dependency.
- High-Speed Printing:Continuous-feed mechanisms and enhanced fuser assemblies support production environments exceeding 100 pages per minute. Government print facilities in Germany and Japan specify these systems for centralized document factories serving multiple administrative units.
- Color Printing:Four-drum or single-pass architectures add consumables complexity but capture marketing and creative services demand.
- Wireless Connectivity:Enterprise-grade security protocols enable mobile device printing without network infrastructure overhaul.
High-Speed Printing commands the established base. Cloud Integration is gaining share fastest.
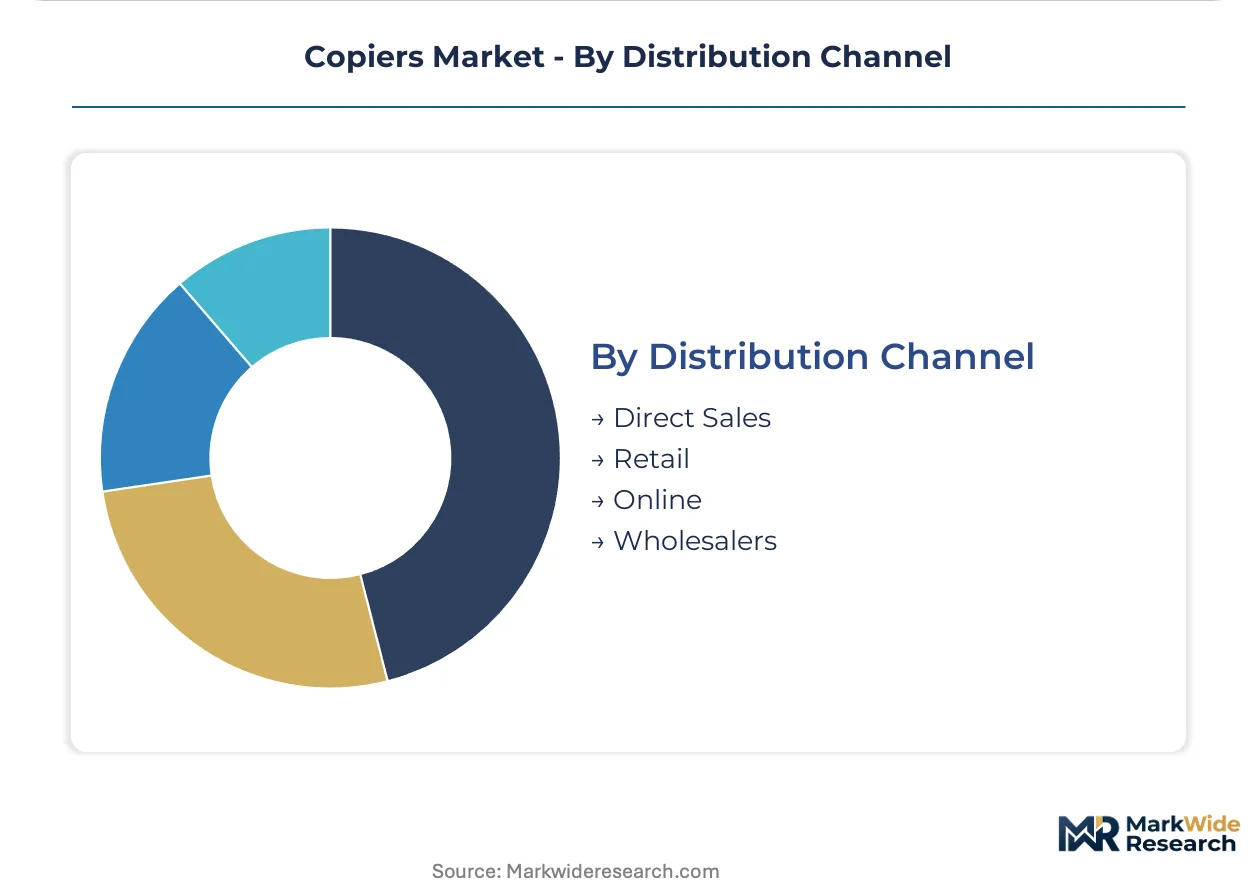
Distribution Channel:
Supply concentration shapes margin capture, with direct relationships enabling service bundling that indirect channels cannot replicate.
- Direct Sales:Manufacturer-controlled field organizations serve enterprise accounts with customized fleet configurations and captive finance arrangements. Canon's integration of hardware with per-page service contracts through its finance arm exemplifies how direct channels lock in multi-year revenue streams.
- Online:Self-service procurement with automated configuration tools expands reach to mid-market segments previously served only through dealer networks. United States small business buyers increasingly initiate research through digital channels before negotiating service terms.
- Retail:Big-box and office supply chains handle transactional volume for entry-level devices with minimal service attachment.
- Wholesalers:Inventory aggregation supports dealer and VAR ecosystems with logistics efficiency.
Direct Sales commands the established base. Online channels show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Ecodesign Directive mandates on standby power consumption are accelerating hardware refresh cycles across member states. Japan's METI Top Runner standards progressively tighten energy efficiency thresholds. Educational infrastructure investments in India and hybrid learning persistence in North America sustain placement volumes.
United States
Financial services and insurance verticals mandate predictive uptime SLAs with automated supply replenishment. The EPA's ENERGY STAR specifications disqualify inefficient models from federal procurement lists. Enterprise buyers in New York and Chicago now require AI-powered document analytics as standard contract terms.
Germany
Public-sector procurement rules favor multifunction devices with integrated document management capabilities. The EU Ecodesign Directive and RoHS restrictions shape material selection and recyclability requirements. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate demand for high-speed production systems serving administrative document factories.
Japan
METI enforces progressively tightening Top Runner standby power standards that disqualify inefficient equipment from public procurement. Domestic manufacturers redesign power management circuits to meet sub-watt idle consumption thresholds. Tokyo and Osaka enterprise segments with 24-hour operational requirements drive consolidation toward vendors with captive semiconductor fabrication.
India
Underpenetrated public school systems present volume opportunities for entry-level multifunction devices. The Bureau of Indian Standards and central government educational infrastructure programs accelerate hardware placement in state-run institutions. Maharashtra and Karnataka educational districts consolidate procurement through centralized purchasing cooperatives covering thousands of sites.
China
Domestic manufacturing scale supports cost-competitive production for export markets and local enterprise segments. MIIT energy efficiency standards and dual carbon goals shape product development priorities. Yangtze River Delta industrial zones concentrate assembly operations for laser and inkjet systems serving Asia-Pacific distribution channels.
Copiers Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent go-to-market architectures. Direct sales organizations serving enterprise accounts lock in multi-year revenue through per-page service contracts bundled with captive finance. The market structure consolidates around three strategic archetypes: integrated hardware-service vendors, component technology specialists, and scale-driven manufacturing platforms. Competitive moves center on backward integration into semiconductor fabrication and geographic expansion through dealer network acquisition.
Among Japan-based integrated vendors, Canon Inc., Ricoh, and Kyocera Document Solutions Inc. exemplify the hardware-service bundling archetype. Canon's captive finance arm enables multi-year contract structures. Ricoh occupies a position in managed print services penetration. Kyocera represents long-life component technology differentiation. These three anchors demonstrate how domestic energy efficiency mandates reshape competitive positioning through power management circuit redesign requirements.
| Leading Market Players |
|---|
| Canon Inc. |
| HP Inc. |
| Xerox Corporation |
| Ricoh |
| Brother Industries, Ltd. |
| Konica Minolta, Inc. |
| Kyocera Document Solutions Inc. |
| Sharp Corporation |
| Lexmark International, Inc. |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta manufacturing clusters feed the bulk of laser and inkjet assembly capacity for Asia-Pacific distribution, concentrating component purchasing power among domestic Chinese producers and compressing margins for foreign OEMs competing on hardware acquisition costs. This geographic concentration of final assembly and controller chip packaging creates asymmetric pricing power where local vendors capture value through captive semiconductor fabrication while import-dependent competitors absorb tariff and logistics premiums.
Pricing Analysis
Certification level (ENERGY STAR/Top Runner/Ecodesign-compliant) creates the primary spread between premium and standard hardware tiers. Three-tier pricing structure across premium, standard, and economy levels dominates contract negotiations, with per-page service bundling commanding higher lifetime value than transactional hardware sales. Pricing pressure stems from semiconductor input volatility extending lead times for enterprise-grade systems. Small businesses exhibit highest price sensitivity, favoring lower-duty-cycle inkjet devices with minimal service attachment, while large enterprises prioritize predictive uptime guarantees over acquisition cost.
Supply Chain Analysis
Upstream feedstock for ceramic drum substrates and toner polymers draws from Japan, Germany, and South Korea, with specialized fuser assembly components resting on Taiwanese semiconductor foundries. Controller chip shortages and proprietary consumables lock-in represent persistent single-source vulnerabilities. Distribution runs through direct sales organizations for enterprise accounts, dealer networks for mid-market penetration, and online self-service channels expanding fastest among United States small business buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized electromechanical repair capabilities are aging out of the workforce faster than vocational programs replenish supply, creating a structural bottleneck around field service delivery that rewards vendors with captive technician training pipelines.
For Market Incumbents: Build switching-cost moats through predictive maintenance algorithms embedded in drum assemblies, locking enterprise buyers into multi-year per-page contracts. Deepen backward integration into semiconductor fabrication to mitigate controller chip shortage exposure. Prioritize ceramic drum technology R&D to extend component lifespans and reduce total cost of ownership for high-volume government users threatened by cloud document substitution. For New Entrants and Emerging Players: Build out independent maintenance channels in jurisdictions where right-to-repair regulations threaten proprietary service revenue models. Target underpenetrated India educational infrastructure with entry-level multifunction devices sold through centralized purchasing cooperatives. Pursue white-label manufacturing partnerships with Yangtze River Delta assembly operators to achieve cost parity on hardware acquisition. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because managed print services penetration concentrates contract value among integrated hardware-service vendors with captive finance arms. Acquisition targets should display dense dealer network footprints in Germany or Japan where energy efficiency mandates accelerate replacement cycles. Monitor METI Top Runner standby power standard revisions as inflection indicator for compliance-driven hardware refresh demand.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Algorithm Development | AI-powered uptime guarantees now mandated by United States financial services buyers compress vendor selection around mean-time-between-failures performance. |
| Ceramic Drum Technology Scale-Up | Long-life component spans reduce total cost of ownership for EU Ecodesign Directive-driven government refresh cycles in Germany and Japan. |
| Captive Semiconductor Fabrication Investment | In-house controller chip production insulates against supply disruption for 24-hour operational enterprise segments in Tokyo and Osaka. |
| Right-to-Repair Channel Expansion | Independent maintenance networks capture service revenue at risk from emerging legislation across multiple jurisdictions. |
| Educational Cooperative Contracting | Centralized purchasing agreements with Texas and California K-12 districts unbundle hardware from consumables, shifting leverage toward volume-guarantee buyers. |
Methodological Framework
Operator-level perspectives from fleet managers at large enterprises, procurement officers in German public-sector agencies, field service technicians, educational cooperative purchasing directors, and aftermarket consumables distributors anchored the qualitative base. Primary interview insights combined with secondary validation from EPA ENERGY STAR certification databases, METI Top Runner compliance filings, EU Ecodesign Directive implementation reports, and SEC 10-K disclosures from listed manufacturers. Bottom-up unit shipment estimates triangulated against top-down hardware revenue analysis across the analysis window.
Scenario-bracketing framed demand projections under baseline, accelerated digital substitution, and extended hardware replacement cycle assumptions. Segmentation dimensions modeled include product type, end-user scale, technology integration level, and distribution channel structure. CAGRs derived from historical shipment trends, replacement cycle analysis, and regulatory mandate timing. Forecast inputs incorporated duty cycle patterns by vertical, energy efficiency compliance deadlines, and cloud document platform adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native document workflow platforms or independent repair consortiums would shift outcomes beyond modeled ranges. Cross-checking against Bureau of Indian Standards educational infrastructure placement data and United States federal procurement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Global Office Peripherals and Products Market
Office Supplies
Mechanical Pencil Leads Market
Office Supplies
Dictionary Pen Market
Office Supplies
Student Stationery Market
Office Supplies
Business Card Holder Market
Office Supplies
Acrylic Marker Pen Market
Office Supplies
Latin America School Stationery Supplies Market
Office Supplies
Erasable Ink Pen Market
Office Supplies
Writing Instruments Market
Office Supplies
Global Office Stationery Market
Office Supplies
Pencil Sharpeners Market
Office Supplies
Perforated File Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
Malaysia Stationery Market
Office Supplies
Global Stationery and Supplies Market
Office Supplies
Printer Ink Cartridge Market