
 Starches/Glucose Market | 2026-2036
Starches/Glucose Market Size, Share, and Industry Trends Forecast 2026-2036
Starches/Glucose Market Analytics
The EU Green Deal is expanding clean-label starch demand across European food manufacturing. Cargill Incorporated leverages its North American corn processing network to supply modified starches for bakery reformulations. Roquette Frères anchors European pea starch capacity as plant-based formulations gain shelf space. Ingredion Incorporated differentiates through specialty tapioca and potato starch portfolios targeting premium confectionery clients.
Starches and glucose denote carbohydrate polymers and monomeric sugars extracted from cereal grains, tubers, and legumes through wet milling, enzymatic hydrolysis, or physical modification; these ingredients function as thickeners, stabilizers, sweeteners, and fermentation feedstocks across industrial processing. Native starch retains granular structure for basic thickening applications, while modified starch variants command premium positioning in retort-stable and freeze-thaw resistant food systems. Maltodextrin serves pharmaceutical and nutritional applications where rapid solubility and low sweetness profiles matter, whereas dextrose monohydrate dominates intravenous solutions and sports nutrition formulations.
FDA food additive regulations and GRAS determinations govern starch modification protocols in the United States, while the EPA administers effluent standards for wet milling operations. EFSA evaluates novel starch derivatives under EU food improvement agent frameworks, and China's SAMR enforces GB standards for glucose syrup purity and labeling. Stakeholders must monitor evolving carbon accounting rules for agricultural supply chains as buyers embed Scope 3 emissions criteria into procurement contracts.
Market Dynamics
The EU Green Deal is compressing agricultural input carbon intensity requirements, forcing wet millers to reconfigure supply chains around Scope 3 accounting and regenerative sourcing protocols. This regulatory pressure is reshaping capital allocation toward lower-carbon starch extraction technologies.
Growth Catalysts
- EU Green Deal agricultural criteria:The EU Green Deal is tightening sustainability benchmarks for crop inputs, accelerating clean-label starch demand across European food manufacturing.
- Processed food industrialization:China's processed food sector is concentrating demand for modified starches as domestic bakery and confectionery production scales.
- Enzymatic modification:Novel enzyme platforms are enabling precision starch tailoring for freeze-thaw stable applications in frozen ready meals.
Market Restraints
- Corn price volatility:Wet milling margins remain exposed to feedstock fluctuations in the US Corn Belt, compressing returns during drought cycles.
- Pea starch supply concentration:European pea protein fractionation capacity limits native pea starch availability for plant-based dairy alternatives.
- Tapioca sourcing fragility:Southeast Asian cassava harvest variability creates intermittent shortages for premium confectionery tapioca derivatives.
Strategic Opportunities
- India food processing:India's FSSAI is harmonizing starch additive codes with Codex standards, opening formulation work for multinational food manufacturers.
- Pharmaceutical excipient grade:USP-NF compliance for pregelatinized starches is creating white space in controlled-release tablet matrices.
- Fermentation feedstock pivot:Dextrose streams are diverting toward precision fermentation for alternative proteins and bioplastics.
Industry Challenges
- Carbon accounting talent scarcity:Scope 3 measurement expertise remains concentrated among Big Four consultancies, inflating compliance costs for mid-tier millers.
- GRAS notification timelines:FDA's novel starch modification review queue is extending commercialization cycles for clean-label texturizers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starches/Glucose Market |
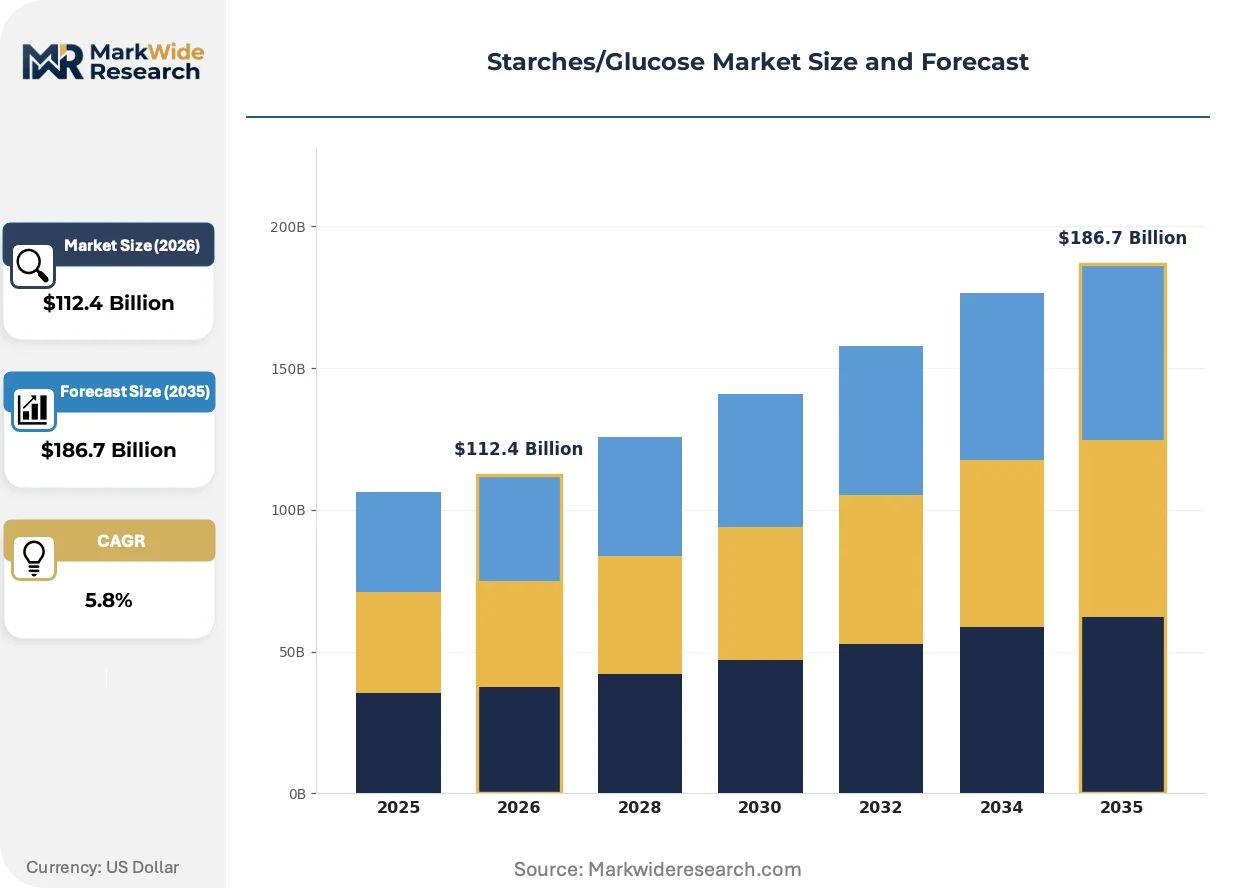
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $186.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Dextrose, Maltodextrin Application: Food & Beverage, Pharmaceutical, Animal Feed, Adhesives End User: Food Manufacturers, Bakeries, Confectioneries, Nutritional Companies Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, Grain Processing Corporation, Agrana Group, Tereos Starch & Sweeteners, Emsland Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starches/Glucose Market Evolving Landscape
Enzymatic precision processing is displacing traditional chemical modification, while regulatory carbon accounting is embedding into procurement contracts. These forces are compressing the technology gap between commodity and specialty starch tiers.
Precision enzymatic hydrolysis is decentralizing starch functionality tailoring away from centralized chemical plants. Bakery reformulators are adopting these platforms to achieve clean-label texture targets without E-number additives. This capability shift is compressing minimum efficient scale for specialty starch production.
REACH chemical registration is tightening disclosure requirements for acetylated and cross-linked starch derivatives used in EU food contact materials. Manufacturers are accelerating migration to enzymatic and physical modification methods to avoid SVHC scrutiny. The confectionery and infant nutrition segments are most affected, with several reformulations already underway.
Ingredient procurement is consolidating around vertically integrated starch suppliers capable of certifying regenerative agriculture credentials. Large food manufacturers are displacing spot-market purchasing with multi-year offtake agreements tied to carbon intensity metrics. This pattern is most visible in Northern European markets where retailer ESG scorecards drive supplier selection.
Starches/Glucose Market Segmentation
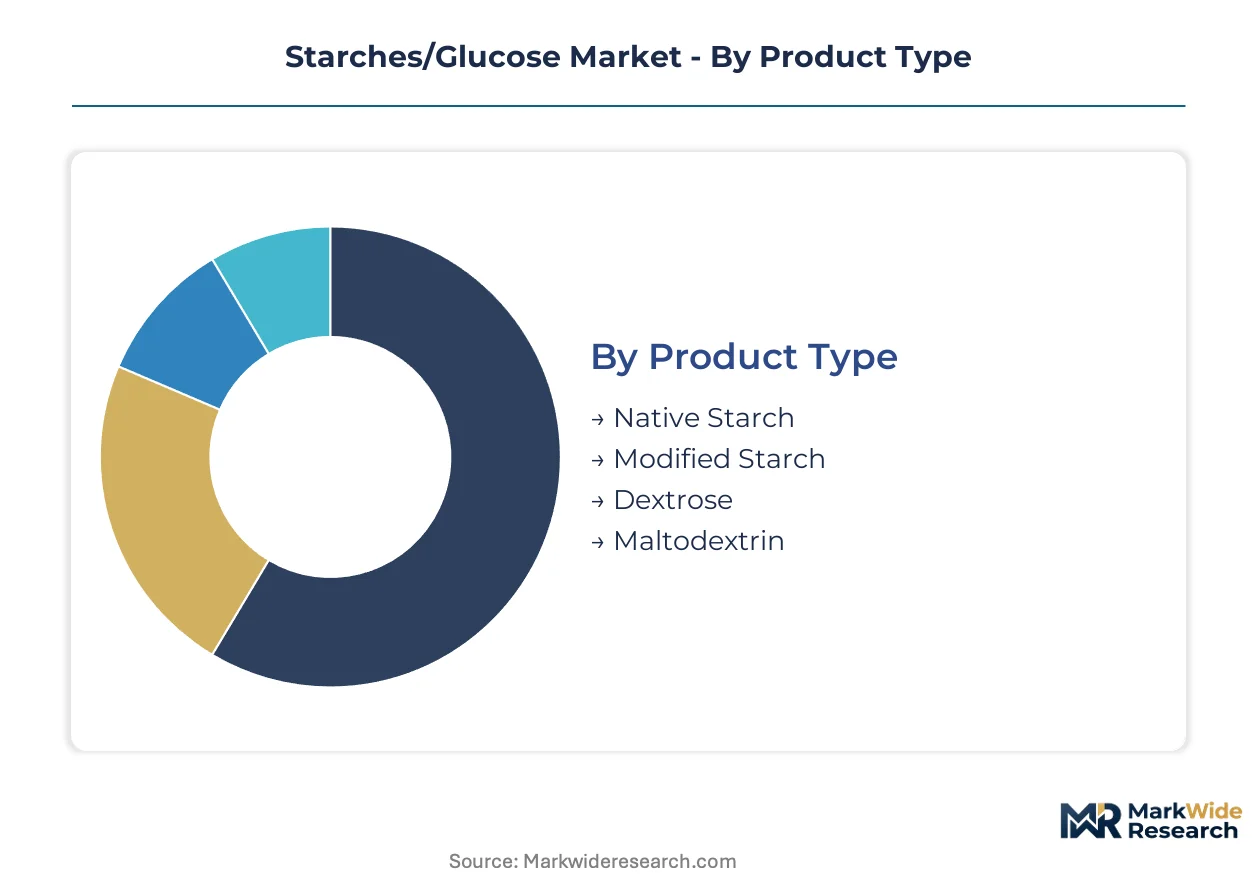
Starch and glucose suppliers configure production assets around distinct functional tiers rather than commodity grades. Segmentation discipline separates volume-driven native starch operations from precision-modified portfolios commanding formulation premiums.
Product Type:
Native starches function as standalone thickeners in basic food systems, while modified variants embed into complex multi-ingredient matrices requiring process tolerance.
- Native Starch:Granular carbohydrate polymers extracted through wet milling of corn, wheat, or potato retain crystalline structure for standard viscosification. Food manufacturers in China's industrializing bakery sector absorb volume quantities for cost-sensitive applications.
- Modified Starch:Chemical, physical, or enzymatic alteration introduces cross-linking or substitution for freeze-thaw stability and acid resistance. European clean-label reformulations under EU Green Deal procurement criteria are displacing E-number additives with enzymatically modified alternatives.
- Dextrose:Crystalline glucose monohydrate serves intravenous solutions, sports nutrition, and fermentation feedstocks.
- Maltodextrin:Low dextrose-equivalent hydrolysates provide rapid solubility with minimal sweetness for pharmaceutical excipients and infant nutrition.
Native starch leads volumes today; modified starch is gaining share fastest.
Application:
Application segmentation tracks where functional specifications diverge most sharply—food systems tolerate broader viscosity ranges than pharmaceutical grades demanding USP-NF compliance.
- Food & Beverage:Thickeners, stabilizers, and texturizers across dairy, sauces, and bakery applications. China's processed food industrialization concentrates demand for modified starches in retort-stable ready meals.
- Pharmaceutical:Pregelatinized starches and dextrose meet compendial standards for tablet binders and parenteral solutions. US FDA GRAS determinations and USP-NF monographs govern excipient qualification timelines.
- Animal Feed:Carbohydrate energy sources and pellet binders for livestock nutrition formulations.
- Adhesives:Dextrinized starches provide renewable, water-activated bonding for paper and packaging applications.
Food and beverage commands current revenue; pharmaceutical applications are expanding most quickly.
End User:
End user categories reflect formulation sophistication—industrial manufacturers integrate starches at scale while artisanal bakeries source pre-blended systems.
- Food Manufacturers:Large-scale processors of sauces, soups, and dairy alternatives requiring consistent viscosity profiles. Northern European retailers' ESG scorecards are embedding Scope 3 carbon accounting into supplier selection.
- Bakeries:Fresh and industrial bread producers utilizing native wheat starch for crumb structure and modified variants for extended shelf life.
- Confectioneries:Premium chocolate and candy makers specifying tapioca-derived starches for clarity and neutral flavor.
- Nutritional Companies:Sports nutrition and clinical formula producers demanding rapid-dissolving maltodextrin with controlled glycemic response.
Food manufacturers dominate procurement volumes; nutritional companies are climbing the fastest.
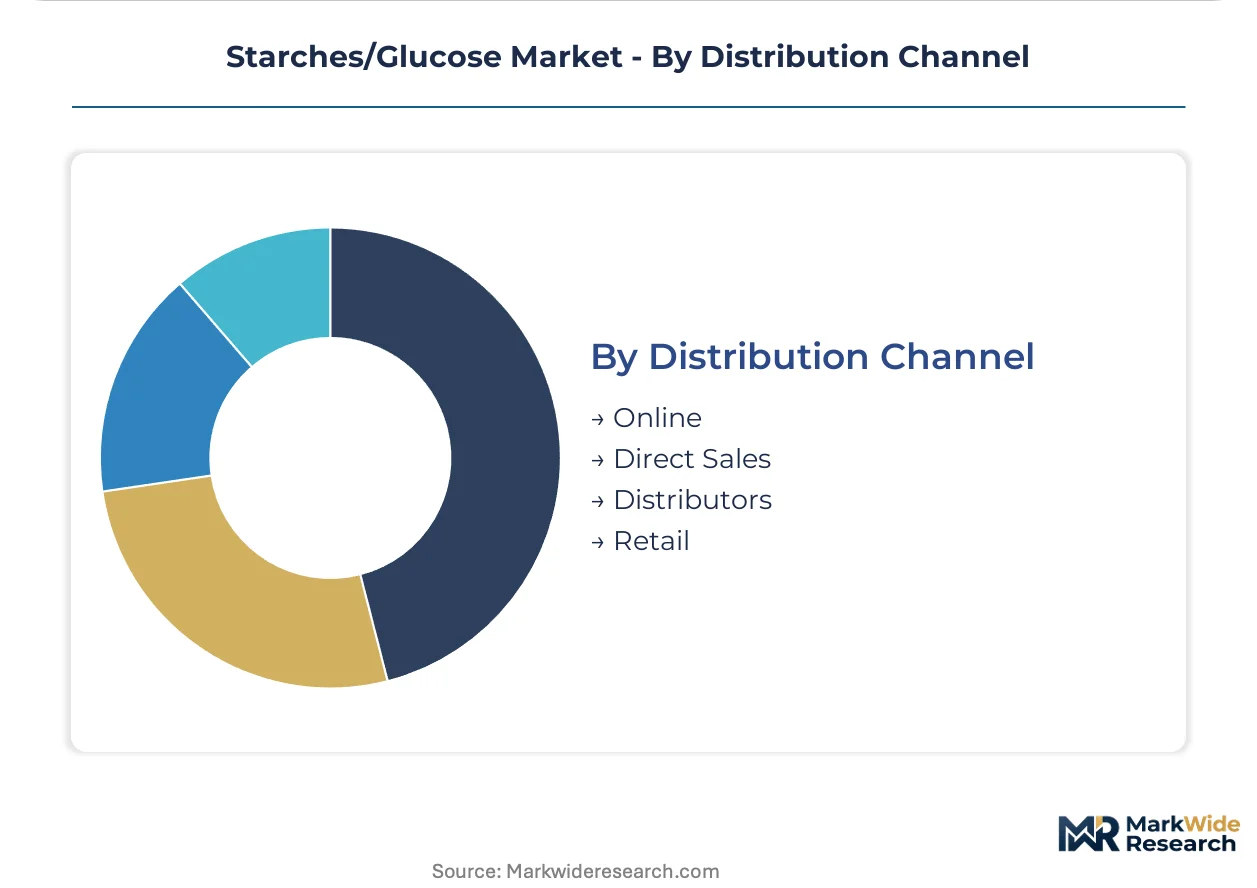
Distribution Channel:
Channel structure separates bulk commodity flows from technical service-intensive specialty sales requiring formulation support.
- Direct Sales:Long-term offtake agreements between starch millers and multinational food manufacturers. Carbon intensity metrics and regenerative agriculture certifications are displacing spot-market purchasing in EU markets.
- Distributors:Regional intermediaries serving mid-tier processors and smaller formulation houses with blended inventory.
- Online:E-procurement platforms for standardized grades and sample ordering.
- Retail:Consumer-packaged native starches for home cooking and small commercial kitchens.
Direct sales leads volume today; distributor channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The starch and glucose industry traces its modern origins to wet milling operations that scaled across the United States Corn Belt during the early twentieth century. Today, production capacity distributes across major agricultural economies where corn, wheat, and cassava processing infrastructure converges with food manufacturing demand.
United States
Iowa and Illinois wet milling complexes supply modified starches for bakery reformulations and dextrose for fermentation feedstocks. EPA effluent standards govern processing water discharge, while FDA GRAS determinations regulate novel starch modifications. The Corn Belt concentration around Cedar Rapids and Decatur anchors North American glucose syrup production.
China
Shandong and Jilin provinces concentrate cassava and corn starch capacity serving industrializing processed food sectors. SAMR enforces GB standards for glucose syrup purity and labeling compliance. The Yangtze River Delta cluster around Shanghai integrates starch derivatives into expanding confectionery and ready-meal manufacturing.
Germany
Lower Saxony and North Rhine-Westphalia host wheat and potato starch operations supplying clean-label formulations across European food manufacturing. EU Green Deal agricultural criteria compress carbon intensity requirements for crop inputs. The Hamburg-Rotterdam corridor facilitates starch trade flows between processing hubs and Nordic export markets.
India
Gujarat and Maharashtra maize processing capacity expands to serve domestic bakery and dairy alternative formulations. FSSAI harmonizes starch additive codes with Codex standards, enabling multinational formulation work. The Delhi-NCR region concentrates procurement decision-making for pan-Indian food manufacturer networks.
Brazil
São Paulo state cassava starch processors supply Latin American confectionery and paper adhesive markets. ANVISA regulates food-grade starch specifications for pharmaceutical and nutritional applications. The Campinas industrial corridor anchors South American modified starch technical service capabilities.
Starches/Glucose Market Competitive Landscape
Capital-heavy wet millers compete with asset-light specialty starch formulators across distinct value chain positions. The vendor base consolidates around integrated agricultural processors capable of certifying regenerative sourcing credentials. Three archetypes dominate: North American corn-based commodity producers, European clean-label specialists, and Asian tapioca-derived premium suppliers. Capacity expansion and enzymatic technology licensing represent the primary competitive vectors.
Among North American integrated processors, Cargill Incorporated and Archer Daniels Midland Company occupy positions exemplifying scale-driven commodity starch supply. Ingredion Incorporated represents the specialty portfolio archetype, with Tate & Lyle PLC and Roquette Frères anchoring European clean-label and plant-based formulation capabilities respectively.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Roquette Frères |
| Grain Processing Corporation |
| Agrana Group |
| Tereos Starch & Sweeteners |
| Emsland Group |
| Others |
Value Network & Pricing Analysis
Family-owned European wet milling groups anchor supply discipline through multi-generational control of Lower Saxony and North Rhine-Westphalia processing assets, enabling patient capital allocation toward enzymatic modification platforms that command formulation premiums over spot-market commodity flows.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USP-NF certified excipient grades from industrial native starches and bulk glucose syrups. Price differentiation hinges on certification tier and volume commitment scale, with pharmaceutical-grade pregelatinized starches commanding substantial premiums over food-grade modified variants. Cost compression in standard-tier native starches is intensifying because Chinese industrial processors are expanding Shandong and Jilin capacity. Food manufacturers in China's bakery sector exhibit highest price sensitivity, while pharmaceutical formulators demonstrate lowest sensitivity due to compendial compliance requirements.
Supply Chain Analysis
Ocean freight cost volatility from Southeast Asian cassava origins to European confectionery processors is reshaping sourcing strategies for premium tapioca derivatives. Supply concentrates in the United States Corn Belt, China's Shandong-J corridor, and Germany's Lower Saxony potato processing belt. Raw material dependencies center on corn, cassava, and wheat feedstocks. Single-source vulnerability runs through Southeast Asian cassava harvest variability. Distribution runs through long-term offtake agreements between integrated millers and multinational food manufacturers, displacing spot-market purchasing in EU markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal agricultural criteria function as a regulatory compounder, embedding Scope 3 carbon accounting into procurement contracts and accelerating clean-label starch demand across European food manufacturing.
For Market Incumbents: Cement regenerative agriculture certification capabilities through backward integration into Iowa and Illinois corn sourcing networks, insulating against emerging sustainability-linked procurement mandates from Northern European retailers. Prioritize enzymatic modification R&D investments to defend formulation premiums as chemical modification faces REACH SVHC scrutiny.
For New Entrants and Emerging Players: Precision fermentation feedstock supply represents a technology-first wedge, diverting dextrose streams toward alternative protein and bioplastics manufacturers seeking USP-NF compliant carbohydrate sources. Target India's FSSAI-harmonized additive codes as the most penetrable geography, leveraging technical service partnerships with Mumbai-based distribution networks.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier European pea starch fractionators constrained by protein-starch coproduction economics. Long-term viability centers on enzymatic platform licensing rather than commodity volume scale. Watch FDA GRAS notification queue length as the signal indicating commercialization cycle compression for novel clean-label texturizers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regenerative Agriculture | Secures Scope 3 compliance credentials for EU Green Deal procurement contracts. |
| Enzymatic Modification Platform Licensing | Enables precision starch tailoring without REACH chemical registration exposure. |
| Pharmaceutical Excipient Grade Certification | Opens USP-NF compliant revenue streams in controlled-release tablet matrices. |
| Long-term Fermentation Feedstock Offtake | Diverts dextrose capacity toward precision fermentation for alternative proteins. |
| India Distribution Channel Partnership | Captures FSSAI-harmonized formulation work with domestic food processors. |
Research Methodology
Coverage spans the United States Corn Belt, China Shandong-J corridor, Germany Lower Saxony, and India Gujarat-Maharashtra belt, with primary inputs from each region combining interviews with wet milling plant managers, procurement leads at multinational food manufacturers, technical R&D directors at specialty starch formulators, and distribution channel partners. Secondary validation draws from FDA GRAS filings, EFSA food improvement agent evaluations, SAMR GB standards documentation, and customs trade flow data. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Granularity-level framing applies product-grade tier, end-use application, and regional regulatory cluster dimensions at the country level across the analysis window. CAGRs derive from segment-level growth rate reconciliation against macroeconomic agricultural input indicators. Industry-specific forecast inputs include enzymatic technology adoption curves and EU Green Deal procurement timeline assumptions.
The model holds under stable regulatory enforcement intensity; deviation in FDA GRAS review timelines or EU carbon border adjustment implementation would shift commercialization cycle assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Plant Based Premix Market
Ingredients
Low Calorie Oil Market
Ingredients
Europe Feed Yeast Market
Ingredients
Global Whey Protein Ingredients Market
Ingredients
Codonopsis Extract Market
Ingredients
Xylooligosaccharide Market
Ingredients
Hops Market
Ingredients
Durian Powder Market
Ingredients
Protein Ingredients Market
Ingredients
Roasted Grain Ingredients Market
Ingredients
Fluid Lecithin Market
Ingredients
South America Fats and Oil Market
Ingredients
Sea Buckthorn Berry Extract Market
Ingredients
South America Malt Ingredient Market
Ingredients
Hydrolyzed Corn Protein Market
Ingredients
Europe Phytosterols Market