
 Soy Derivatives Market | 2026-2036
Soy Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Derivatives Market Analysis
Commodity procurement channels for soybean crushing and fractionation is tilting toward integrated origination-to-ingredient models. Cargill Incorporated leverages its river terminal network and crush capacity across the US Midwest to control origination costs. Wilmar International anchors its position through palm-soy blending operations and Southeast Asian distribution density. Bunge Limited competes via ocean freight optimization and port crush assets in Brazil and Argentina.
Soy derivatives encompass protein concentrates, isolates, flours, oils, and lecithins extracted from Glycine max through mechanical pressing, solvent extraction, or aqueous processing, serving as functional ingredients for emulsification, gelation, and nutritional fortification across formulated foods and feeds. Soy protein isolate, with minimum protein content of 90% on a dry basis, commands premium positioning in meat alternatives where texture and water-binding properties determine formulation acceptance. Soy lecithin, derived from degumming crude soy oil, occupies a mature margin pool in chocolate confectionery and pharmaceutical excipient applications. Powdered soy flour extends into bakery and extruded snack formulations where cost-efficient protein enrichment drives volume.
The US FDA governs soy protein health claims and GRAS status for food applications, while the USDA administers commodity grading and export inspection protocols that shape international market access. The EU EFSA evaluates novel soy ingredient safety for food and feed entry, with REACH compliance required for lecithin derivatives used in industrial applications. Stakeholders must monitor evolving protein content thresholds in regulatory definitions and traceability mandates that could redraw competitive boundaries between commodity crush operators and specialized fractionators.
Market Dynamics
The soy derivatives market is restructuring around sustainability mandates and protein extraction efficiency. The EU F-Gas Regulation and Green Deal are forcing crush operators to decarbonize solvent extraction processes while food manufacturers reformulate around cleaner-label soy ingredients.
Growth Catalysts
- Plant-based meat formulation:Food processors are expanding soy protein isolate procurement for texture-critical meat alternatives. Clean-label positioning drives premium-grade concentrate demand.
- EU regulatory pressure:The EU Green Deal and F-Gas Regulation mandate lower-carbon crushing operations. Compliance investments are accelerating solvent recovery system upgrades across European processing assets.
- Feed protein diversification:Chinese feed mills are expanding soy derivative procurement to reduce dependence on single-origin protein meals. Aquaculture and poultry sectors drive concentrate volume.
Market Restraints
- Input cost volatility:Soybean futures price swings compress crush margins unpredictably. Weather-driven origination shortages in Brazil and Argentina amplify cost instability.
- Supply concentration risk:River terminal and port crush infrastructure concentrates in the US Midwest and Brazilian export corridors. Logistical bottlenecks at these nodes propagate downstream.
- Protein substitution threat:Pea and fava protein isolates are gaining traction in bakery and beverage applications. Formulators are testing blends that reduce soy dependency.
Strategic Opportunities
- Underpenetrated Southeast Asian markets:Indonesia and Vietnam show nascent demand for soy lecithin in chocolate and pharmaceutical excipients. Local distribution partnerships could capture first-mover positioning.
- Precision fermentation convergence:Cell-cultured fat technologies paired with soy protein bases are enabling hybrid meat alternatives. Startups are licensing texture-modification IP from established fractionators.
- US biofuel policy tailwinds:The Inflation Reduction Act incentivizes renewable diesel feedstock production. Soy oil refiners are redirecting volume toward renewable fuel offtake agreements.
Industry Challenges
- Fractionation engineering talent scarcity:Specialized protein extraction and aqueous processing expertise concentrates at legacy crush operators. New entrants face recruitment friction for process optimization roles.
- REACH compliance timelines:Lecithin derivative manufacturers face extended ECHA registration cycles for industrial applications. Documentation delays compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Derivatives Market |
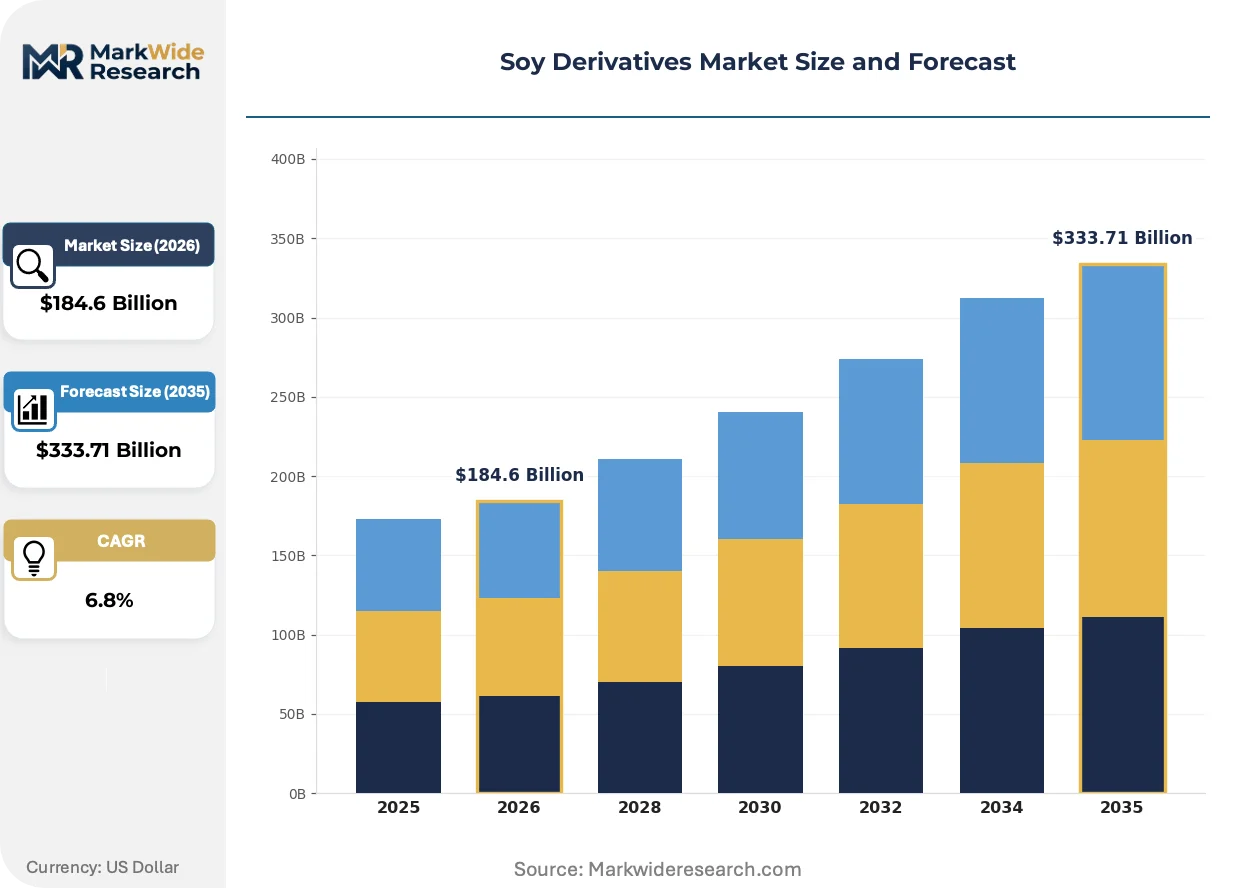
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $333.71 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Protein, Soy Flour, Soy Oil, Soy Lecithin End Use Industry: Food & Beverage, Animal Feed, Cosmetics, Pharmaceuticals Form: Powder, Liquid, Granules, Concentrate Application: Meat Alternatives, Dairy Alternatives, Sauces, Nutritional Supplements |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Bunge Limited, Louis Dreyfus Company, CHS Inc., Wilmar International, AG Processing Inc, DuPont Nutrition and Health, Ruchi Soya Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Derivatives Market Emerging Trajectories
Aqueous processing technologies are disrupting traditional solvent-based extraction. Protein fractionation methods, regulatory carbon accounting, and procurement consolidation are simultaneously reshaping competitive positioning.
Enzyme-assisted aqueous extraction is collapsing the cost differential between mechanical pressing and hexane solvent methods. European food processors are piloting these systems for organic-certified isolate production. The technology is collapsing capital requirements for mid-scale fractionation entry.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in crushing refrigeration and solvent recovery systems. Operators must retrofit cooling infrastructure or face operational restrictions. Brazilian port crush assets are most exposed due to aged equipment bases and limited retrofit capital access.
Integrated origination-to-ingredient procurement is displacing spot-market commodity buying among North American food manufacturers. Long-term offtake contracts with specified protein content and carbon intensity thresholds are replacing quarterly tenders. This pattern is most visible in plant-based meat startups securing isolate supply from Midwest crush operators.
Soy Derivatives Market Segmentation
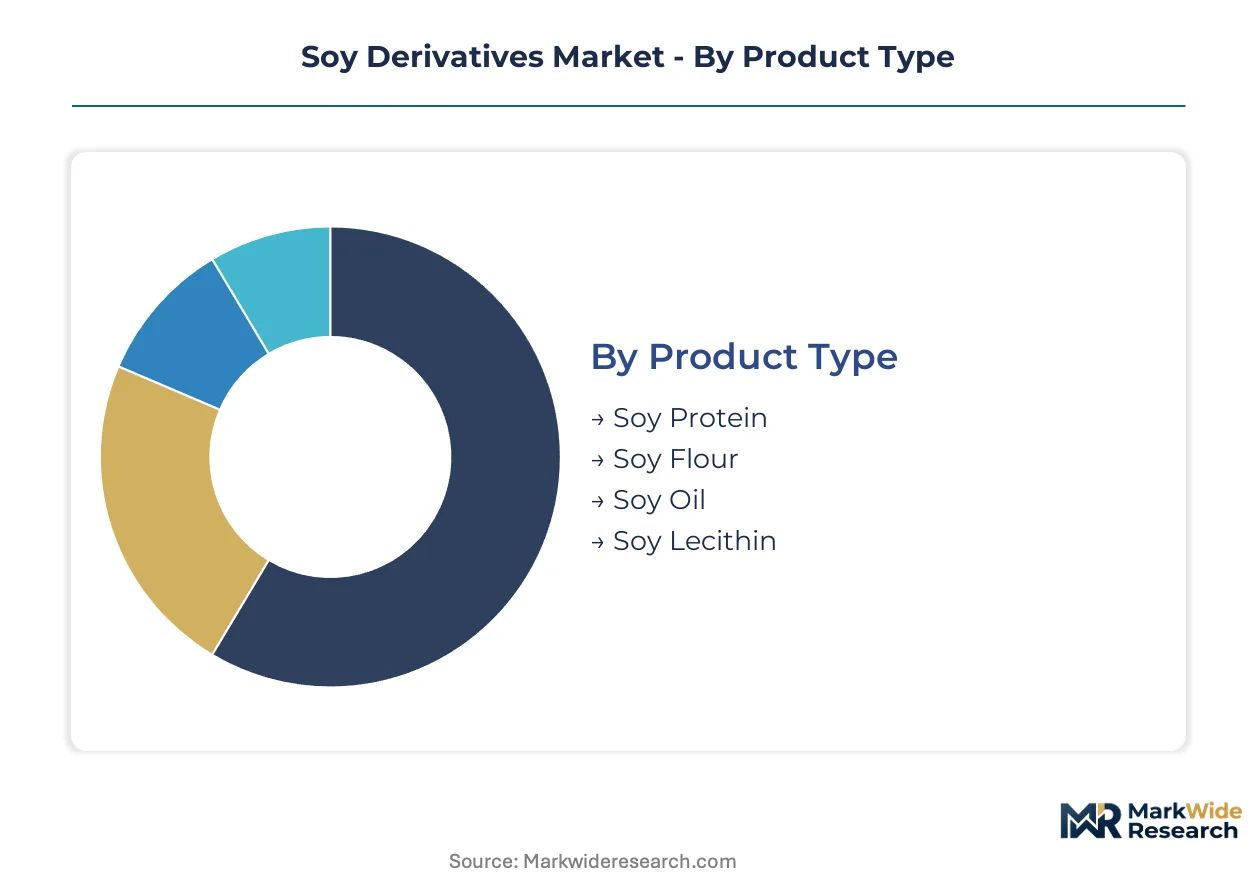
Soy derivatives fractionate into distinct value pools based on protein content, functional properties, and end-use specifications. Procurement patterns diverge sharply between commodity crush outputs and specialized isolates, requiring granular segmentation to map margin capture across the supply chain.
Product Type:
Protein extraction technologies span the use-case spectrum from commodity feed meals to pharmaceutical-grade isolates, with each tier commanding different pricing power based on purity thresholds.
- Soy Protein:Encompasses concentrates (minimum 70% protein) and isolates (minimum 90% protein) extracted via aqueous or alcohol-wash processing. Food processors in China are expanding isolate procurement for plant-based meat formulations where gelation and water-binding properties determine texture acceptance. The EU F-Gas Regulation is accelerating solvent recovery system upgrades at European fractionation assets processing organic-certified concentrates.
- Soy Oil:Refined, bleached, and deodorized grades serve food manufacturing and renewable diesel feedstock markets. US refiners are redirecting volume toward biofuel offtake agreements under Inflation Reduction Act incentives, tightening food-grade supply.
- Soy Flour:Defatted and full-fat varieties provide cost-efficient protein enrichment in bakery and extruded snack applications. Powdered flour extends into institutional baking where formulation flexibility trumps isolate performance.
- Soy Lecithin:Degummed crude oil byproduct functioning as emulsifier in chocolate confectionery and pharmaceutical excipients. Indonesian and Vietnamese chocolate processors are expanding lecithin procurement as regional confectionery manufacturing scales.
The dominant share belongs to soy oil by volume, while soy protein isolate is closing the gap fastest on value capture.
End Use Industry:
Customer concentration patterns separate commodity volume buyers from specialty ingredient specifiers, with regulatory compliance burdens varying sharply across sectors.
- Food & Beverage:Formulators leverage isolates for meat and dairy alternatives, concentrates for nutritional bars, and lecithins for emulsion stability. Clean-label positioning drives premium-grade concentrate demand in European organic-certified applications.
- Animal Feed:Aquaculture and poultry sectors in China absorb protein concentrate volume as feed mills diversify protein sourcing. Soybean meal remains the baseline commodity, though concentrate blends gain traction in precision livestock nutrition.
- Cosmetics:Lecithin derivatives function as skin-conditioning agents and emulsion stabilizers. REACH compliance timelines at ECHA compress product launch windows for industrial lecithin grades entering personal care.
- Pharmaceuticals:High-purity isolates and lecithins serve as excipients in tablet binding and lipid-based drug delivery systems. US FDA GRAS status requirements shape market access for novel soy-derived excipient formulations.
Food and beverage commands the largest value pool, with animal feed representing the steepest volume expansion trajectory.
Form:
Physical state determines handling infrastructure, shelf stability, and dissolution characteristics across manufacturing environments.
- Powder:Spray-dried isolates and flours dominate bulk handling systems in bakery and extrusion plants. Powdered formats enable precise dosing in automated formulation lines.
- Liquid:Crude and refined oils, plus fluid lecithins, require heated storage and pumping infrastructure. Brazilian port crush assets face retrofit pressure on aged liquid handling systems.
- Granules:Agglomerated lecithin and textured protein formats improve flowability in confectionery and meat alternative processing. Granule morphology reduces dusting in high-speed packaging lines.
- Concentrate:Viscous intermediate products between isolate and flour purity levels, typically 65-70% protein. Concentrates balance cost and functionality in institutional foodservice applications.
Powder forms retain the broadest installed base, while liquid formats are gaining share fastest in biofuel feedstock channels.
Application:
Functional requirements in finished goods dictate protein content thresholds, texture modification needs, and clean-label positioning strategies.
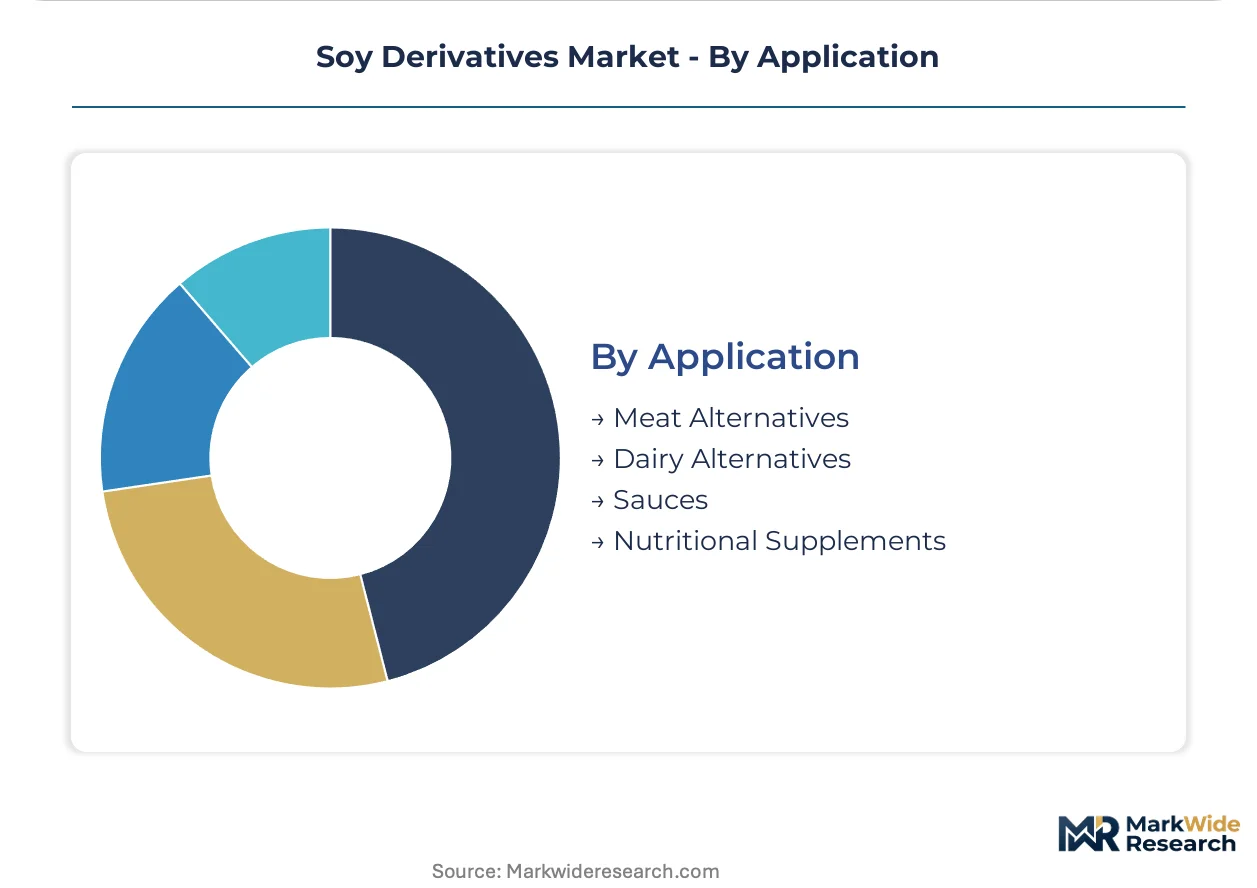
- Meat Alternatives:High-protein isolates provide fibrous texture through extrusion and shear-cell processing. Startups are licensing texture-modification IP from established fractionators to pair with cell-cultured fat technologies.
- Dairy Alternatives:Isolates and concentrates emulsify and stabilize plant-based milk and yogurt formulations. Protein content and solubility determine mouthfeel in beverage applications.
- Sauces:Lecithins and modified flours function as emulsifiers and thickeners in dressings and condiments. Cost-efficient flour grades compete with modified starches in mass-market sauce production.
- Nutritional Supplements:Isolates serve as base protein in powder and ready-to-drink formats. Sports nutrition brands specify minimum PDCAAS scores and amino acid profiles in procurement contracts.
Meat alternatives hold the premium pricing tier, with dairy alternatives expanding most quickly on volume uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese crush operators command premium pricing power against Brazilian port terminals due to integrated origination-to-ingredient procurement density. US Midwest river assets extract margin through food-grade isolate contracts. European fractionators absorb compliance costs from F-Gas Regulation retrofit mandates.
China
Feed mills in Shandong and Guangdong provinces are expanding soy protein concentrate procurement for aquaculture and poultry formulation. The Ministry of Ecology and Environment enforces dual carbon goals that tighten energy intensity standards at crushing facilities. Yangtze River Delta processors are piloting aqueous extraction systems for organic-certified isolate production.
United States
Midwest food manufacturers are locking long-term isolate offtake contracts with specified protein content and carbon intensity thresholds. The USDA administers commodity grading protocols that shape international market access for export-bound crush outputs. Illinois and Iowa river terminal networks anchor origination cost control for integrated crush-to-ingredient operators.
Brazil
Port crush assets in Santos and Paranaguá face margin compression from weather-driven origination volatility and aged liquid handling infrastructure. The national environmental regulator enforces deforestation monitoring requirements that extend traceability burdens to derivative exporters. São Paulo state processors are redirecting soy oil volume toward renewable diesel feedstock channels.
Germany
Hamburg and Bremen fractionators are accelerating solvent recovery system upgrades to meet EU F-Gas Regulation phase-down timelines. The ECHA administers REACH compliance cycles for lecithin derivatives entering industrial applications. Bavarian food processors are reformulating around cleaner-label concentrate grades for meat alternative applications.
Indonesia
Chocolate and pharmaceutical manufacturers in Java are expanding lecithin procurement as regional confectionery scales. The national food and drug regulator aligns excipient safety evaluations with ASEAN harmonization frameworks. Jakarta-Bogor industrial corridors concentrate blending operations for palm-soy derivative formulations.
Soy Derivatives Market Vendor Landscape
Integrated agricultural conglomerates and specialized fractionators split the market along origination control versus purification technology lines. The structure tilts toward consolidation at the crush origination tier while fragmenting across aqueous processing and organic-certified isolate niches. Strategic archetypes include river-terminal network operators, Southeast Asian distribution density players, and ocean freight optimizers with port crush assets. Dominant competitive moves encompass long-term offtake contracting with protein specifications and solvent recovery system retrofit partnerships.
Among North American agricultural conglomerates, Archer Daniels Midland Company exemplifies the integrated origination-to-ingredient archetype through Midwest crush capacity and river terminal density. Cargill Incorporated occupies a parallel position within this tier, leveraging origination cost control across commodity and food-grade channels. Wilmar International represents the Southeast Asian distribution density model, anchoring palm-soy blending operations and regional procurement networks.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Bunge Limited |
| Louis Dreyfus Company |
| CHS Inc. |
| Wilmar International |
| AG Processing Inc |
| DuPont Nutrition and Health |
| Ruchi Soya Industries |
| Others |
Supply Flow & Price Mechanics
Paranaguá-Santos port logistics corridors transmit Brazilian origination volatility directly into Midwest isolate premiums, concentrating pricing power with river-terminal operators while forcing food manufacturers into long-term offtake contracts with protein-grade specifications.
Pricing Analysis
The customization-premium spread between standard commodity meal and food-grade isolate with specified PDCAAS scores and carbon intensity thresholds now exceeds three-to-one. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein content certification and organic compliance status. Cost compression in standard-grade concentrate is intensifying because enzyme-assisted aqueous extraction entrants are collapsing capital barriers. Feed mills in China represent the most price-sensitive buyer segment, while plant-based meat startups securing isolate supply demonstrate the least sensitivity due to texture-critical formulation requirements.
Supply Chain Analysis
Supplier-financing facilities extended by integrated crush operators now stretch to 90-day terms for qualified food processors, tightening working capital pressure on standalone fractionators. Supply concentrates in the US Midwest, Brazil, and Argentina, with each node drawing from distinct origination basins. Hexane solvent, specialized enzyme blends, and organic-certified soybean feedstocks constitute critical input dependencies. Single-source vulnerability at Brazilian port crush assets exposed to weather-driven origination shortages represents the dominant structural risk. Distribution runs through integrated origination-to-ingredient procurement channels displacing spot-market commodity buying.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards specialized aqueous processing expertise that legacy crush operators struggle to recruit, creating persistent margin capture for fractionators with in-house protein extraction engineering capabilities.
For Market Incumbents: Insulate food-grade isolate positioning by accelerating solvent recovery system retrofits ahead of EU F-Gas Regulation phase-down deadlines. Backward integration into organic-certified soybean origination secures supply security against dual carbon goal enforcement by China's Ministry of Ecology and Environment. Channel control through long-term offtake contracts with specified carbon intensity thresholds locks out aqueous processing entrants.
For New Entrants and Emerging Players: Pursue underpenetrated lecithin demand in Indonesian and Vietnamese chocolate manufacturing corridors where regional confectionery scaling outpaces local supply. Precision fermentation convergence opportunities in hybrid meat alternatives offer the most penetrable application segment. A licensing-based go-to-market angle partnering with established fractionators for texture-modification IP reduces capital requirements.
For Investors and Strategic Acquirers: Mid-scale aqueous processing specialists with organic certification capabilities and stranded enzyme-assisted extraction assets present the optimal acquisition target archetype. Long-term viability hinges on defensible protein extraction technology positions rather than commodity crush scale. The signal to watch is REACH compliance documentation velocity at ECHA for lecithin derivative manufacturers, indicating which fractionators can sustain industrial application expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Solvent Recovery System Retrofit | EU F-Gas Regulation compliance preserves operational licenses at Hamburg and Bremen fractionation assets. |
| Organic-Certified Isolate Capacity Addition | Yangtze River Delta aqueous extraction pilots capture premium positioning in European clean-label meat alternatives. |
| Long-Term Offtake Contracting | Specified protein content and carbon intensity thresholds displace spot-market buying among North American food manufacturers. |
| Precision Fermentation IP Licensing | Texture-modification technology partnerships enable hybrid meat alternative startups to pair soy protein bases with cell-cultured fats. |
| Southeast Asian Distribution Partnership | Jakarta-Bogor industrial corridor blending operations capture nascent Indonesian and Vietnamese lecithin demand growth. |
Methodological Framework
The analysis maps soy protein isolate, concentrate, oil, flour, and lecithin value pools, each validated through procurement directors at feed mills and food processors, fractionation plant managers, and regulatory affairs specialists covering REACH and FDA compliance. Primary interviews with crush operators in Illinois, Iowa, and São Paulo state combined with secondary validation from USDA commodity grading protocols, ECHA registration databases, and customs trade data. Bottom-up volume modeling across protein content tiers triangulated against top-down market sizing from integrated agricultural conglomerate disclosures.
Assumptions held fixed include EU F-Gas Regulation phase-down timelines and Inflation Reduction Act biofuel incentive structures, while soybean futures price volatility and aqueous extraction technology diffusion rates varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, end-use industry, physical form, and application functional requirements throughout the forecast period. CAGRs derived from protein extraction efficiency improvements and procurement pattern shifts toward integrated origination-to-ingredient channels. Industry-specific inputs included renewable diesel feedstock redirection volumes and organic-certified isolate production capacity expansion trajectories.
Sensitivities concentrate around Brazilian weather patterns affecting origination, REACH compliance documentation delays at ECHA, and precision fermentation technology substitution rates. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Yeast Market
Ingredients
Chickpea Flour Market
Ingredients
Pea Starch Market
Ingredients
Cocoa Bean Extract Market
Ingredients
Global Apricot Oil Market
Ingredients
Hops Derivative Market
Ingredients
Pulses Ingredients Market
Ingredients
Palm Mid-Fraction Market
Ingredients
South America Protein Market
Ingredients
Sea Buckthorn Berry Extract Market
Ingredients
South America Lipid Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
Hydrolyzed Corn Protein Market
Ingredients
Alcohol Ingredients Market
Ingredients
APAC Savoury Ingredients Market
Ingredients
Modified Soya Flour Market