
 Avocado Powder Market | 2026-2036
Avocado Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Avocado Powder Market Analysis
The EU Green Deal is expanding compliance requirements for sustainable agricultural imports, which redirects procurement toward certified avocado powder suppliers. Olivado Group leverages its integrated supply chain from orchard to powder to meet traceability mandates. SunOpta sustains its position through diversified sourcing across multiple growing regions. Mission Produce anchors North American distribution with controlled-atmosphere storage infrastructure that extends raw material availability.
Avocado powder consists of dehydrated avocado flesh, typically containing 50-70% fat content depending on processing method, produced through freeze-drying or spray-drying to preserve nutritional integrity and extend shelf life up to 24 months. Food and Beverage applications dominate volume consumption due to smoothie formulations and clean-label ingredient substitution trends. Freeze-Dried Avocado Powder commands premium positioning in nutraceutical channels where enzymatic activity and nutrient retention justify higher price points. Spray-Dried variants occupy mainstream food manufacturing where cost efficiency and dispersibility drive selection.
FDA food safety standards govern import thresholds for microbial contamination in dried avocado products, while USDA organic certification determines eligibility for premium channel placement. The EU's REACH framework and EFSA novel food assessments create additional compliance layers for European market access. Stakeholders must monitor evolving pesticide residue limits across multiple jurisdictions and assess backward integration into controlled cultivation to secure supply consistency.
Market Dynamics
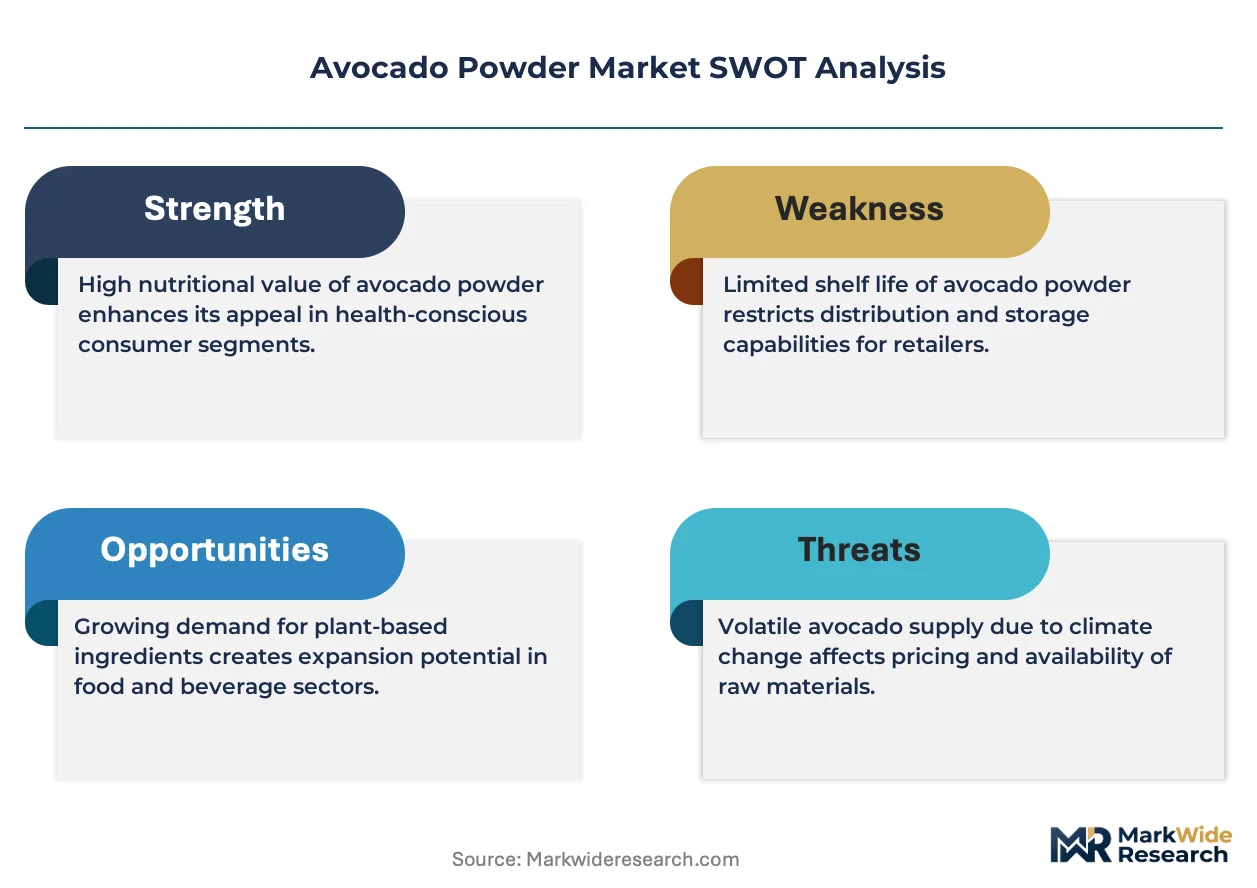
The EU Green Deal's sustainable sourcing mandates are compressing supply chains toward certified originators while freeze-drying technology premiums reshape margin allocation between processing tiers.
Growth Catalysts
- EU Green Deal compliance:Import standards under REACH and CSRD are redirecting procurement toward traceable suppliers with integrated orchard-to-powder operations.
- Smoothie formulation demand:Food and Beverage manufacturers are substituting avocado powder for fresh pulp to reduce spoilage and standardize fat content.
- Mexico:Concentrated processing infrastructure and year-round cultivar availability anchor raw material security for international buyers.
Market Restraints
- Input cost volatility:Fresh avocado prices fluctuate with water scarcity in Michoacán and Jalisco growing regions, compressing processor margins.
- Supply concentration risk:Over 70% of spray-dried powder originates from a single dominant processing cluster, creating single-point vulnerability.
- EFSA novel food assessments:European market entry requires extensive safety dossiers that delay commercialization by 18-24 months for new entrants.
Strategic Opportunities
- India:FSSAI regulatory harmonization and PLI scheme incentives for food processing create first-mover advantage for certified exporters.
- Sports nutrition applications:Protein powder co-formulations with avocado powder's lipid profile target endurance athlete segments.
- Direct-to-manufacturer channels:Bypassing traditional ingredient distributors via B2B platforms reduces margin capture by intermediaries.
Industry Challenges
- Freeze-drying technician scarcity:Specialized knowledge of lyophilization parameters for lipid-rich substrates limits capacity expansion.
- Organic certification timelines:USDA and EU organic audits require 3-year transition periods for conventional orchard conversions.
- Cross-border cold chain integrity:Maintaining enzymatic stability during intercontinental shipping demands capital-intensive controlled-atmosphere logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Avocado Powder Market |
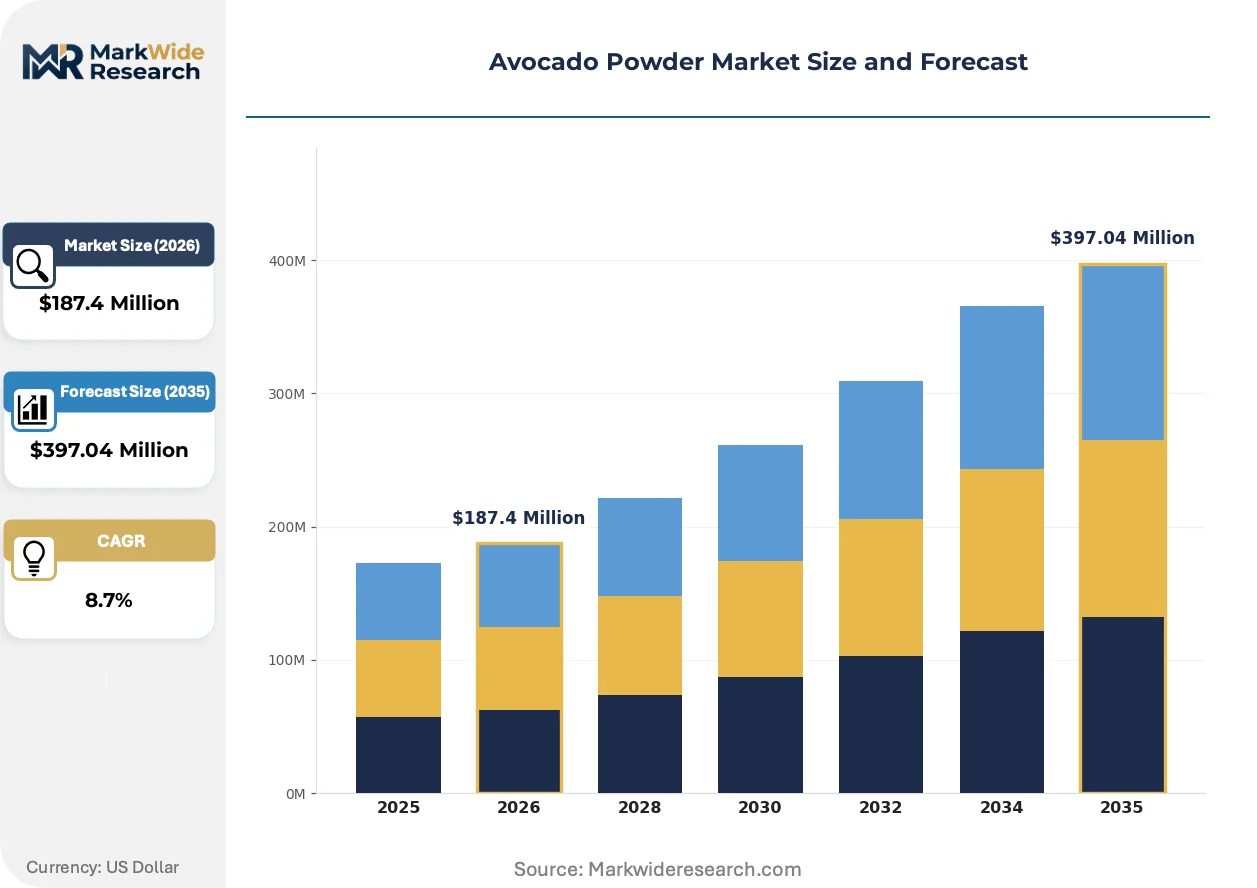
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Avocado Powder, Conventional Avocado Powder, Freeze-Dried Avocado Powder, Spray-Dried Avocado Powder Application: Food and Beverage, Nutraceuticals, Cosmetics, Animal Feed End User: Retail Consumers, Food Manufacturers, Health Stores, Restaurants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Olivado Group, SunOpta, Mission Produce, Greenjeeva, Medikonda, Calavo Growers, AVOCOOP, OVAVO LTD, Westfalia Fruit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Avocado Powder Market Emerging Trajectories
Processing technology convergence and regulatory traceability mandates are fragmenting the supplier base into tiered certification strata while end-use formulation science advances.
Hybrid freeze-spray drying systems are unifying the cost-efficiency of spray-drying with nutrient retention benchmarks previously exclusive to freeze-drying. Nutraceutical contract manufacturers in California and Germany are piloting these systems at 40% capacity premiums. This convergence is unifying two previously distinct price tiers into a single mid-premium positioning that captures both food manufacturing and supplement channels.
REACH substance restrictions on pesticide residues are tightening maximum residue limits for dried fruit derivatives across European ports. ECHA enforcement is rejecting shipments from non-compliant origins at Rotterdam and Hamburg entry points. Powder processors are responding by backward integrating into certified organic cultivation or securing exclusive offtake agreements with GlobalGAP-verified cooperatives.
Clean-label formulation mandates are compressing ingredient declaration complexity for packaged foods. CPG brands in the United States are replacing synthetic emulsifiers and artificial flavor carriers with avocado powder's natural lipid and fiber matrix. This substitution pattern is most visible in plant-based dairy alternatives and infant nutrition segments where FDA GRAS self-determination streamlines formulation approval.
Avocado Powder Market Segmentation
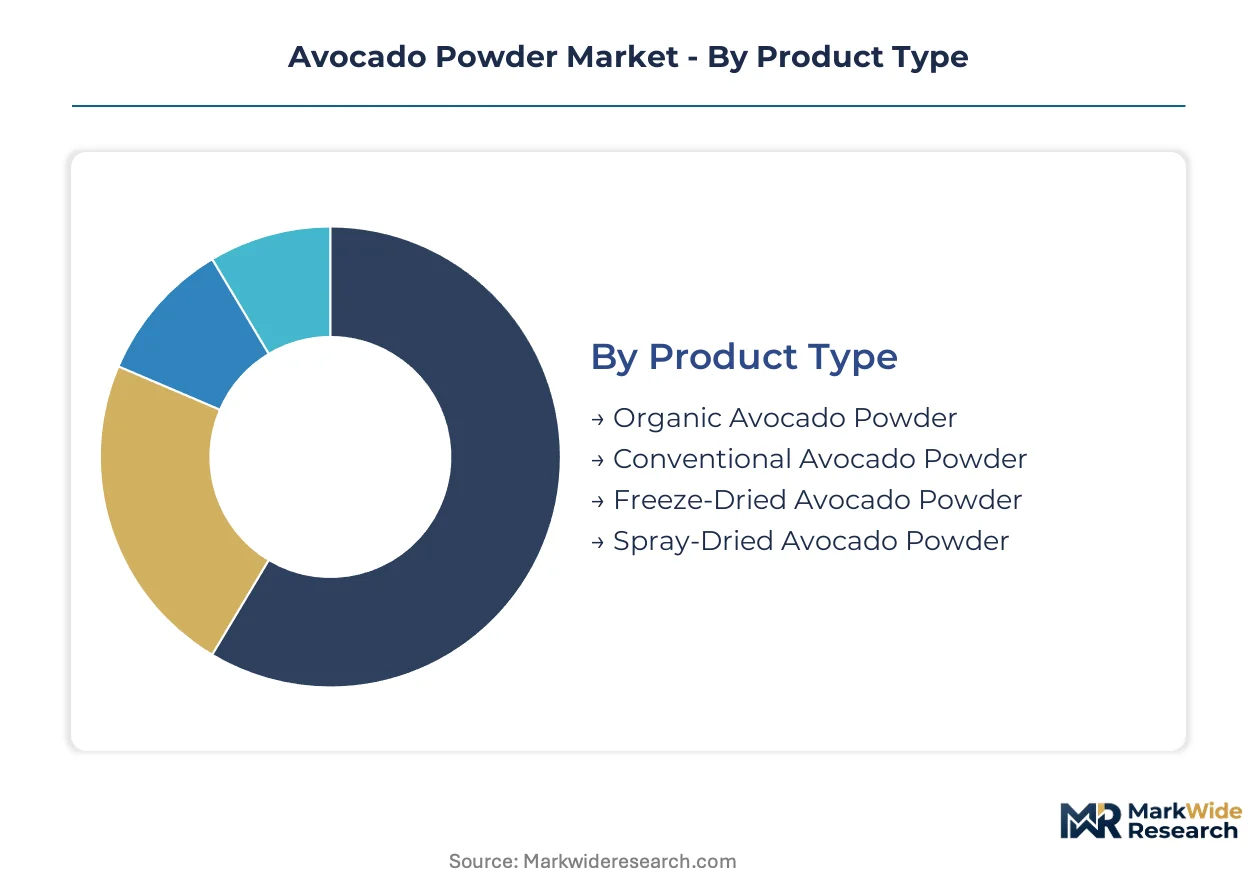
Avocado powder procurement decisions pivot on processing method, certification tier, and end-use formulation requirements. Each segmentation axis reveals distinct margin structures and compliance burdens that reshape supplier selection across food manufacturing and nutraceutical channels.
Product Type:
Buyers weigh nutrient retention against unit economics when selecting processing technology and certification grade.
- Freeze-Dried Avocado Powder:Lyophilization preserves enzymatic activity and lipid-soluble vitamins at 50-70% fat content. Nutraceutical manufacturers in Germany and California absorb 40% price premiums for batch consistency in supplement formulations.
- Spray-Dried Avocado Powder:Atomization delivers superior dispersibility and 18-month shelf stability for industrial-scale food production. Mainstream beverage manufacturers in Mexico and the United States prioritize this grade for smoothie powder blends where cost efficiency dominates selection criteria.
- Organic Avocado Powder:USDA and EU organic certification mandates 3-year orchard transition periods and residue testing. Premium CPG brands in the United States specify this grade for clean-label infant nutrition products.
- Conventional Avocado Powder:Standard cultivation without certified organic protocols serves price-sensitive food service and animal feed applications.
Volume sits with spray-dried variants; growth tilts toward freeze-dried and organic certifications.
Application:
Formulation science and regulatory pathways determine adoption velocity across end-use sectors.
- Food and Beverage:Smoothie manufacturers substitute avocado powder for fresh pulp to eliminate cold-chain spoilage and standardize fat content per serving. Clean-label dairy alternatives in the United States leverage the natural emulsification properties of avocado lipid-fiber matrices.
- Nutraceuticals:Sports nutrition brands co-formulate avocado powder with protein isolates to target endurance athletes seeking sustained lipid energy release. EFSA novel food dossiers delay European commercialization by 18-24 months for new entrants.
- Cosmetics:Topical formulations utilize avocado powder's oleic acid profile for barrier repair creams and hair conditioning treatments.
- Animal Feed:Pet food manufacturers incorporate avocado powder for omega fatty acid enrichment in premium companion animal nutrition.
Food and Beverage commands current volume; nutraceutical applications are expanding most quickly.
End User:
Procurement scale and technical specification intensity separate buyer tiers.
- Food Manufacturers:Industrial buyers negotiate annual offtake agreements with Mexican processors for 20-ton minimum orders. Specification sheets mandate particle size distribution, moisture content, and microbial load thresholds.
- Health Stores:Independent retailers stock 8-16 ounce SKUs of organic freeze-dried powder for functional food consumers. Staff training requirements concentrate on lipid profile education and storage protocol guidance.
- Restaurants:Fast-casual chains in the United States adopt avocado powder for guacamole base preparation to reduce labor and waste versus fresh fruit handling.
- Retail Consumers:Direct-to-consumer brands package single-serve sachets for home smoothie preparation through e-commerce subscription models.
Food Manufacturers dominate procurement tonnage; health stores and restaurants are gaining share fastest.
Distribution Channel:
Channel selection reflects order size, delivery velocity requirements, and technical support needs.
- Direct Sales:Bulk industrial buyers bypass distributors to negotiate price and secure lot traceability from Mexican processors. Mission Produce and Olivado Group maintain dedicated account teams for multinational CPG procurement.
- Online Retail:Amazon and specialized ingredient marketplaces serve small-batch food entrepreneurs and nutraceutical startups with 25-50 kilogram minimum orders.
- Specialty Stores:Natural products distributors like UNFI and KeHE stock organic-certified SKUs for independent retailers in the United States.
- Supermarkets:Mass retail placement remains limited due to low consumer awareness and shelf-space competition with fresh avocado displays.
Direct Sales anchors industrial volume; online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing infrastructure concentrates in Mexico while consumption fragments across regulatory jurisdictions with divergent compliance timelines. The United States anchors import volume through established cold-chain logistics. European demand accelerates under traceability mandates that favor certified originators.
United States
CPG brands in California and Texas drive formulation demand for smoothie powders and plant-based dairy alternatives. FDA GRAS self-determination streamlines novel ingredient approvals for infant nutrition applications. Los Angeles and San Diego harbor contract manufacturers specializing in lipid-rich substrate processing for nutraceutical channels.
Mexico
Michoacán and Jalisco orchards supply year-round Hass cultivar harvests to spray-drying facilities clustered around Uruapan. USDA organic certification audits and GlobalGAP verification protocols govern export eligibility to premium North American channels. Mexico City Metro anchors logistics coordination for intercontinental powder shipments.
Germany
Nutraceutical contract manufacturers in Bavaria absorb freeze-dried powder premiums for sports nutrition co-formulations targeting endurance athletes. EFSA novel food dossier requirements delay commercialization by 18-24 months for non-established suppliers. Hamburg port enforcement of REACH substance restrictions rejects non-compliant dried fruit derivative shipments.
India
FSSAI regulatory harmonization with Codex standards accelerates import clearance for certified organic avocado powder. PLI scheme incentives for food processing infrastructure attract first-mover exporters establishing Mumbai and Bangalore distribution nodes. Maharashtra's contract manufacturing sector pilots hybrid drying systems for mid-premium positioning.
Netherlands
Rotterdam serves as the primary European entry point for Latin American powder shipments undergoing ECHA residue testing. CSRD supply chain disclosure requirements redirect procurement toward orchard-integrated suppliers with verified traceability. Amsterdam-based ingredient distributors consolidate organic-certified SKUs for redistribution across German and French markets.
Avocado Powder Market Vendor Landscape
The competitive structure tilts toward orchard-integrated processors with captive supply control. Three to five dominant operators anchor volume procurement through backward integration into cultivation. Strategic archetypes separate into certified organic originators, diversified multi-region traders, and controlled-atmosphere logistics specialists. Capacity expansion and exclusive offtake agreements with GlobalGAP cooperatives constitute the dominant competitive moves reshaping supplier relationships.
Within the integrated supply chain tier, Olivado Group exemplifies orchard-to-powder traceability compliance, while SunOpta occupies a position as a diversified sourcing operator across multiple growing regions. Mission Produce anchors North American distribution infrastructure with controlled-atmosphere storage capabilities. These three entities represent distinct strategic postures: vertical cultivation control, geographic risk distribution, and logistics-intensive availability extension.
| Leading Market Players |
|---|
| Olivado Group |
| SunOpta |
| Mission Produce |
| Greenjeeva |
| Medikonda |
| Calavo Growers |
| AVOCOOP |
| OVAVO LTD |
| Westfalia Fruit |
| Others |
Supply Flow & Price Mechanics
Hybrid freeze-spray drying technology adoption in California and Maharashtra processing clusters compresses cost differentials between premium nutrient-retention grades and standard dispersibility tiers while simultaneously concentrating procurement leverage among equipment-capable operators.
Pricing Analysis
Margin tightening in spray-dried tiers reflects water scarcity-driven fresh avocado cost volatility across Michoacán and Jalisco growing regions. Three-tier pricing structure across premium freeze-dried, standard spray-dried, and economy conventional grades anchors the market, with organic certification and enzymatic activity benchmarks as primary price differentiation drivers. Cost-down pressure on mid-tier processors accelerates because CPG buyers are consolidating annual offtake agreements around 20-ton minimums. Food service distributors exhibit highest price sensitivity; nutraceutical contract manufacturers in Germany and California absorb lowest sensitivity due to formulation performance requirements.
Supply Chain Analysis
Single-source vulnerability sits with Mexican processing infrastructure, where over 70 percent of spray-dried powder originates from Uruapan-area facilities. Geographic supply concentration spans Mexico as the dominant processing hub, the United States as the primary import destination, and Germany as the European nutraceutical formulation center. Raw material dependencies draw from Hass cultivar orchards in Michoacán, natural gas inputs for dehydration energy, and specialized lyophilization equipment sourced from European manufacturers. Tariff exposure on dried fruit derivatives entering Rotterdam and Hamburg creates structural risk. Distribution runs through direct sales channels for industrial buyers, with Mission Produce and Olivado Group maintaining dedicated account teams for multinational procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in avocado powder production has become a vertical-integration race, with orchard-to-powder traceability compliance as the decisive upstream lever separating certified suppliers from commodity traders.
For Market Incumbents: Hedge against supply concentration risk by securing exclusive offtake agreements with GlobalGAP-verified cooperatives in Jalisco expansion zones while investing in hybrid drying capacity to capture mid-premium positioning. Water scarcity in Michoacán threatens raw material security; backward integration into controlled cultivation with USDA organic transition timelines defends margin position against price volatility. For New Entrants and Emerging Players: FSSAI regulatory harmonization in India opens a window for certified organic exporters to establish first-mover advantage in Mumbai and Bangalore distribution nodes before domestic processing capacity matures. Target sports nutrition co-formulation partnerships with protein powder manufacturers seeking lipid-profile differentiation; bypass traditional ingredient distributors via B2B platforms to reduce margin capture by intermediaries. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified food-ingredient conglomerates seeking orchard-integrated supply security. Long-term viability favors operators with captive cultivation, hybrid processing technology, and EU Green Deal traceability compliance. Watch EFSA novel food dossier approval velocity as the inflection indicator for European market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Cultivation | EU Green Deal traceability mandates reward orchard-controlled supply with premium channel placement. |
| Hybrid Drying System Deployment | California and Maharashtra pilot facilities capture 40% capacity premiums by unifying cost and nutrient benchmarks. |
| Exclusive GlobalGAP Cooperative Agreements | ECHA residue enforcement at Rotterdam redirects procurement toward verified originators with audit documentation. |
| Direct-to-Manufacturer B2B Platform Launch | Bypassing UNFI and KeHE distribution reduces margin capture by intermediaries in health store channels. |
| Sports Nutrition Co-Formulation Partnerships | Protein powder manufacturers in Bavaria absorb freeze-dried premiums for endurance athlete lipid energy positioning. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across powder processing plant managers, CPG procurement leads, nutraceutical contract manufacturing directors, and organic certification auditors. Bottom-up triangulation against top-down trade flow analysis validated volume estimates. Secondary sources included FDA GRAS determinations, EFSA novel food registers, USDA organic certification databases, and ECHA REACH substance restriction notices.
Reconciliation of production capacity disclosures, import clearance records, and end-use formulation demand estimates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include processing method, certification tier, application sector, and end-user procurement scale. CAGRs were derived from trend extrapolation of trade volumes and price realization data, with freeze-drying technician scarcity and organic transition timelines as industry-specific forecast inputs.
Caveats apply where EFSA novel food assessment delays, water scarcity intensification in Jalisco, or REACH residue limit tightening could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory pathway velocity and cultivation yield stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Psyllium Products Market
Ingredients
Textured Soy Flour Market
Ingredients
Liquid Feed Market
Ingredients
Middle East Feed Palatability Enhancers Market
Ingredients
Germany Gelatin Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Marine Collagen Ingredients Market
Ingredients
Corn Gluten Meal Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Mussel Oil and Powder Market
Ingredients
Plant Based Thickener Market
Ingredients
Canada Soy Protein Market
Ingredients
Bouillon Market
Ingredients
Hydroxytyrosol Market
Ingredients
North America Lipid Market
Ingredients
Global Fruits and Vegetables Ingredients Market