
 USA Yeast Extracts Market | 2026-2036
USA Yeast Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
USA Yeast Extracts Market Analytics
Asset-light toll manufacturing and third-party fermentation leasing is tilting competitive dynamics toward mid-size ingredient firms that avoid capital-intensive bioreactor ownership. Lesaffre leverages its integrated North American yeast supply chain to secure feedstock cost advantages across multiple extraction grades. DSM sustains technology leadership through proprietary autolysis process patents that yield higher free amino nitrogen content. Kerry Group competes by embedding yeast extracts within broader savory flavor systems sold to national foodservice accounts.
Yeast extracts comprise soluble cell contents released through autolysis or plasmolysis of Saccharomyces cerevisiae, typically containing 40-60% protein, 15-25% nucleic acid derivatives, and 5-10% glutamic acid by dry weight, functioning primarily as umami-intense flavor enhancers and nutrient-dense fermentation media. Autolyzed yeast dominates volume in flavor enhancer applications where hydrolyzed protein labeling carries consumer stigma, while nutritional yeast occupies the fastest-expanding position within plant-based dairy analogs and fortified food matrices. Powder form anchors industrial procurement due to extended shelf stability and standardized dosing in automated blending operations.
FDA GRAS self-affirmation pathways and USDA Organic certification requirements shape product development timelines and label claim substantiation for yeast extract suppliers serving US food manufacturers. FERC-regulated utility rates influence fermentation facility siting decisions, particularly for energy-intensive autolysis and spray-drying stages. State-level clean energy incentives in California and New York are redirecting capacity expansion toward renewable-powered production sites. Stakeholders must monitor evolving EPA effluent guidelines for fermentation-derived biomass processing as wastewater treatment costs become a decisive factor in facility economics.
Market Dynamics
Clean-label sodium reduction mandates from FDA are compressing formulation timelines and forcing food manufacturers toward yeast-derived umami systems that bypass hydrolyzed protein stigma.
Growth Catalysts
- USDA BioPreferred procurement standards:Federal purchasing mandates accelerate institutional adoption of biobased flavor modifiers across school nutrition and military ration programs.
- Plant-based meat analogs:Manufacturers of alt-protein patties and sausages expand yeast extract volumes to mask off-notes from pea and soy protein isolates.
- Midwest manufacturing corridor concentration:Proximity between Milwaukee-Chicago food processing clusters and adjacent yeast fermentation facilities reduces inbound logistics costs for savory ingredient buyers.
Market Restraints
- Molasses feedstock volatility:Sugar beet and cane supply fluctuations from climate-impacted agricultural regions transmit directly to yeast extract production economics.
- Single-source autolysis technology dependence:Proprietary enzymatic process patents held by a narrow supplier set create bottleneck risk for high-FAN (free amino nitrogen) grade availability.
- MSG substitution stigma persistence:Consumer confusion between yeast extract and monosodium glutamate labeling limits penetration in premium natural retail channels despite regulatory distinction.
Strategic Opportunities
- California clean energy incentives:State-level renewable power credits and carbon offset programs enable fermentation facility siting with net-negative operational emissions profiles.
- Precision fermentation convergence:Integration of CRISPR-edited yeast strains with traditional autolysis infrastructure promises novel peptide profiles for targeted flavor modulation.
- Direct-to-manufacturer e-procurement platforms:B2B ingredient marketplaces disintermediate traditional distributor markups for mid-size savory and snack producers.
Industry Challenges
- Fermentation biochemist talent scarcity:Specialized expertise in industrial-scale autolysis optimization and downstream processing remains concentrated among retiring cohorts at legacy production sites.
- USDA Organic certification timelines:Eighteen-to-twenty-four-month approval windows for organic yeast extract claims delay product launches and tie up working capital.
- Spray-drying energy intensity:FERC-regulated utility rate volatility directly impacts facility operating margins during peak summer demand periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Yeast Extracts Market |
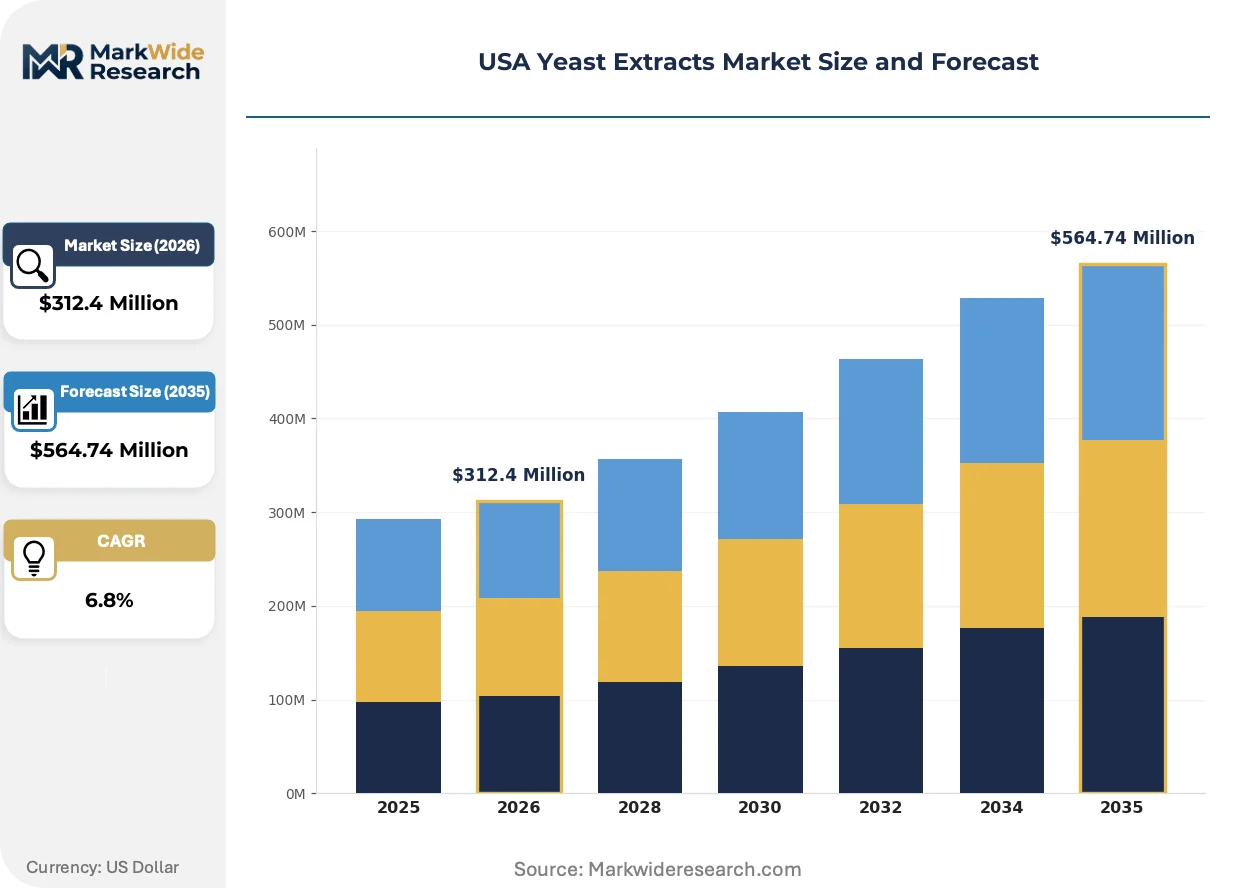
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Yeast, Active Dry Yeast, Nutritional Yeast, Autolyzed Yeast Application: Baking, Brewery, Flavor Enhancer, Animal Feed Form: Powder, Granule, Liquid, Paste End User: Food Industry, Beverage Industry, Animal Nutrition, Pharmaceuticals |
| Companies Covered | Lesaffre, DSM, Angel Yeast, Lallemand Inc., Kerry Group, Synergy Flavors, Leiber GmbH, Associated British Foods, Chr. Hansen, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Yeast Extracts Market Evolving Landscape
Bioprocess engineering advances and shifting procurement logics are compressing traditional supply relationships while opening new technical pathways for flavor differentiation.
Enzymatic autolysis control systems are hybridizing with AI-driven fermentation monitoring to enable real-time adjustment of cell lysis kinetics. Mid-size savory ingredient houses adopt these hybrid platforms to match batch-to-batch consistency previously achievable only by integrated multinationals. The technology is hybridizing quality assurance workflows with predictive maintenance protocols, reducing unplanned downtime in continuous-flow bioreactor operations.
FDA GRAS self-affirmation pathway revisions are tightening substantiation requirements for novel yeast extract peptide fractions. Food manufacturers now face extended documentation burdens when claiming reduced-sodium equivalence through umami enhancement. Savory snack producers in the Northeast corridor are responding by front-loading toxicology studies and engaging third-party GRAS panel reviews earlier in product development cycles.
Long-term toll manufacturing agreements are displacing spot-market purchasing for standardized yeast extract grades. National foodservice operators now contract directly with fermentation specialists for dedicated capacity rather than sourcing through flavor house intermediaries. This pattern concentrates most visibly in the plant-based dairy analog segment, where buyers prioritize supply security over price flexibility.
USA Yeast Extracts Market Segmentation
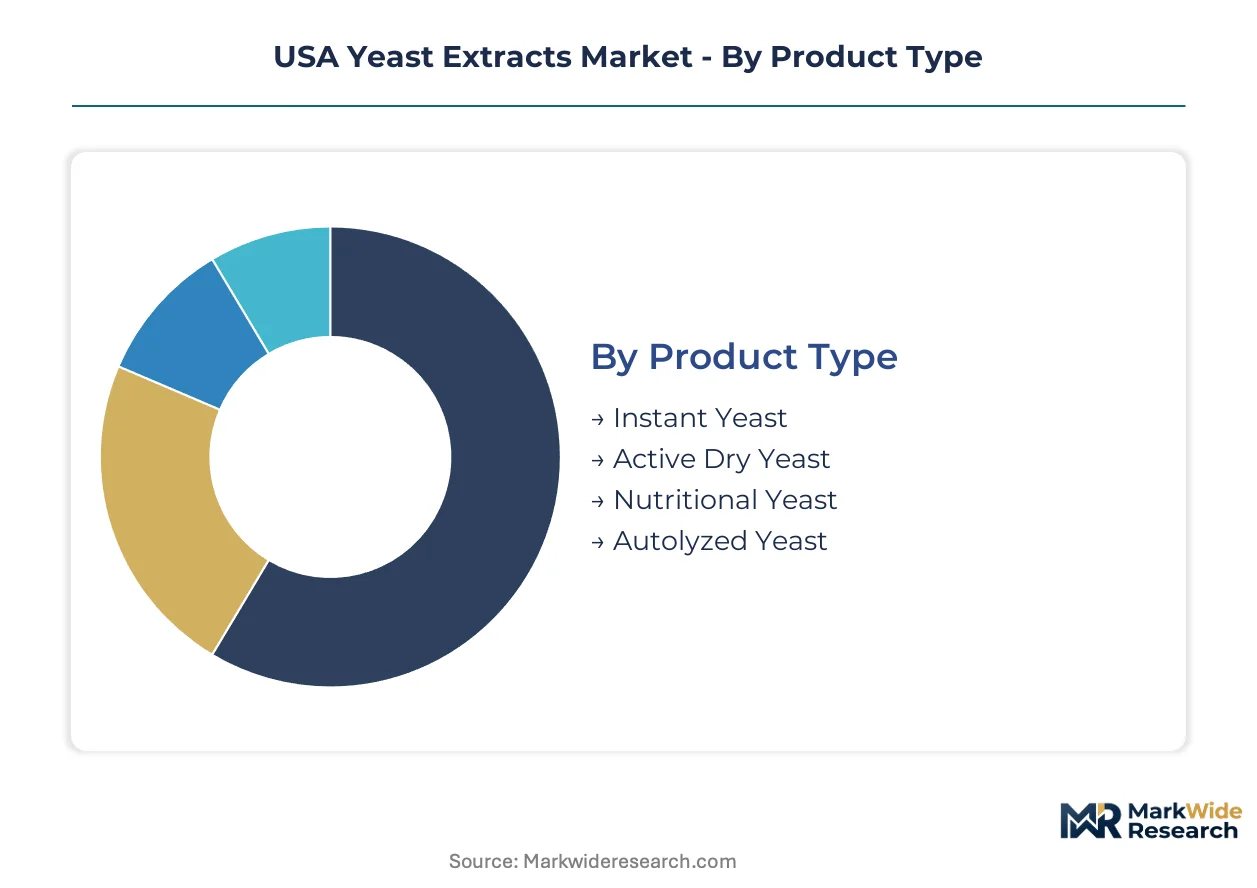
Yeast extract procurement patterns diverge sharply across product grades and application contexts, with formulation requirements dictating everything from autolysis intensity to downstream processing specifications. Understanding these segment boundaries enables suppliers to align capacity investments with the technical demands of savory snack manufacturers versus pharmaceutical fermentation buyers.
Product Type:
After-sales technical support intensity varies dramatically across yeast extract categories, with autolyzed grades requiring intensive formulation collaboration while instant yeast demands minimal post-sale intervention.
- Instant Yeast:Rapid-rehydration Saccharomyces cerevisiae cultures with standardized gassing power specifications anchor commercial baking operations where batch consistency overrides flavor complexity. Demand concentrates in Midwest industrial bakeries supplying private-label bread programs to regional grocery chains, with procurement governed by USDA organic certification timelines that extend supplier qualification cycles.
- Active Dry Yeast:Vacuum-packed dehydrated cells with extended ambient shelf stability serve craft brewery and home baking segments where cold-chain logistics prove prohibitive. Northeast distribution hubs see elevated throughput during seasonal baking surges, though molasses feedstock volatility transmits directly to pricing negotiations with malt house procurement officers.
- Nutritional Yeast:Inactivated whole-cell preparations fortified with B-complex vitamins target plant-based dairy analogs and clean-label seasoning blends. California clean energy incentives are redirecting spray-drying capacity toward renewable-powered production sites serving West Coast vegan food manufacturers.
- Autolyzed Yeast:Soluble hydrolysates with elevated free amino nitrogen content function as umami-intense flavor modifiers in reduced-sodium savory applications. FDA GRAS self-affirmation pathways shape peptide fraction documentation burdens for suppliers targeting national foodservice accounts.
By volume, autolyzed yeast leads. By growth pace, nutritional yeast is ahead.
Application:
Cost-tier differentiation separates commodity-grade yeast extracts destined for animal nutrition from premium fractions commanding formulation service premiums in savory flavor systems.
- Baking:Leavening-active cultures with precise fermentation kinetics specifications dominate high-speed commercial operations where dough throughput metrics dictate supplier selection. Midwest manufacturing corridor concentration reduces inbound logistics costs for industrial bakery procurement teams.
- Brewery:Pitching-rate-optimized strains with attenuation profiles calibrated to specific gravity targets serve craft and industrial beer production. Molasses feedstock volatility creates margin pressure for suppliers serving price-sensitive regional brewers.
- Flavor Enhancer:High-glutamate autolysates with clean-label positioning displace hydrolyzed proteins in sodium-reduced snack formulations. Plant-based meat analog manufacturers expand volumes to mask off-notes from pea and soy protein isolates.
- Animal Feed:Nutritionally dense fermentation byproducts with standardized protein content specifications support poultry and swine nutrition programs. USDA BioPreferred procurement standards accelerate institutional adoption across school nutrition and military ration programs.
Flavor enhancer applications command the highest service intensity. Animal feed generates the steepest volume throughput.
Form:
Volume-to-weight economics and automated dosing compatibility drive procurement preferences across powder, granule, liquid, and paste presentations.
- Powder:Spray-dried fine particles with standardized particle size distributions enable precise metering in high-speed blending operations. Extended shelf stability anchors industrial procurement for national savory snack producers.
- Granule:Agglomerated free-flowing particles with reduced dusting characteristics suit manual handling environments and small-batch foodservice operations. FERC-regulated utility rate volatility directly impacts facility operating margins during peak summer spray-drying demand periods.
- Liquid:Concentrated suspensions with controlled solids content bypass reconstitution steps in beverage and sauce manufacturing. Direct-to-manufacturer e-procurement platforms are disintermediating traditional distributor markups for mid-size producers.
- Paste:High-solids semi-fluid preparations with minimal processing deliver cost advantages in bulk industrial applications where solubility requirements are relaxed. Precision fermentation convergence with CRISPR-edited strains promises novel peptide profiles for targeted flavor modulation.
Powder form dominates procurement tonnage. Liquid form is climbing the fastest among beverage industry buyers.
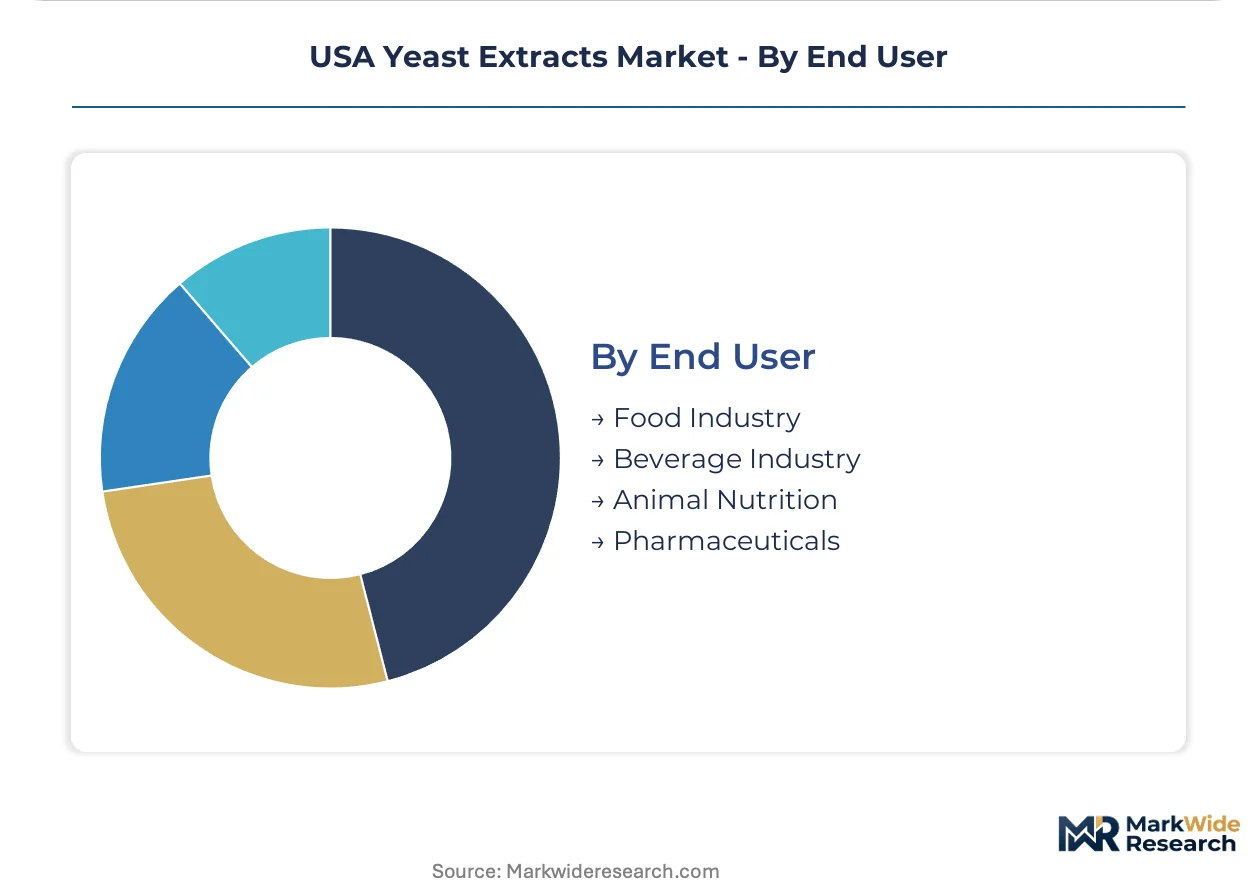
End User:
Customer-type segmentation reveals divergent technical service expectations, with pharmaceutical fermentation buyers demanding certificate-of-analysis rigor absent from commodity animal nutrition accounts.
- Food Industry:Clean-label formulation support for sodium reduction and umami enhancement drives savory snack and plant-based meat procurement. FDA labeling requirements for reduced-sodium products accelerate substitution toward yeast-derived flavor systems.
- Beverage Industry:Attenuation-consistent brewing strains and fermentation nutrients support craft and industrial beer production. State-level clean energy incentives in California and New York redirect capacity expansion toward renewable-powered production sites.
- Animal Nutrition:Protein-standardized feed ingredients with mycotoxin certification requirements serve integrated poultry and swine operations. USDA BioPreferred procurement standards govern federal purchasing mandates.
- Pharmaceuticals:GMP-compliant fermentation media with endotoxin-controlled specifications support therapeutic protein and vaccine production. EPA effluent guidelines for fermentation-derived biomass processing influence wastewater treatment cost structures.
Food industry buyers generate the highest transaction frequency. Pharmaceuticals represents the most stringent qualification barrier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA BioPreferred procurement standards and state-level clean energy incentives are redirecting fermentation capacity toward specific sub-regional clusters. The Midwest and Northeast manufacturing corridors anchor procurement concentration due to proximity between yeast production facilities and large-scale food processing operations.
Midwest Manufacturing Corridor
Industrial bakeries and savory snack producers in Illinois, Wisconsin, and Ohio drive autolyzed yeast procurement for sodium-reduced formulations. FERC-regulated utility rates influence fermentation facility siting decisions in this energy-intensive production zone. Milwaukee-Chicago clusters reduce inbound logistics costs for buyers sourcing from adjacent yeast fermentation sites.
Northeast Corridor
Clean-label foodservice operators and craft breweries in New York, Pennsylvania, and New England expand nutritional yeast volumes for plant-based dairy analogs. State-level renewable energy credits in New York redirect spray-drying capacity toward lower-carbon production profiles. Boston-Providence pharmaceutical fermentation buyers demand GMP-compliant yeast extract grades for therapeutic protein media.
California
Vegan food manufacturers and West Coast beverage innovators anchor nutritional yeast demand for fortified seasoning blends. California clean energy incentives enable fermentation facility siting with net-negative operational emissions targets. Los Angeles-San Diego clusters concentrate precision fermentation startups exploring CRISPR-edited yeast strains.
Southeast
Poultry and swine nutrition programs in Georgia, North Carolina, and Alabama standardize yeast extract procurement for animal feed formulations. USDA BioPreferred federal purchasing mandates accelerate institutional adoption across military ration and school nutrition programs. Atlanta-Charlotte distribution hubs manage outbound logistics for commodity-grade feed ingredients.
Pacific Northwest
Craft brewery density in Oregon and Washington sustains active dry yeast demand for attenuation-consistent brewing strains. EPA effluent guidelines for fermentation-derived biomass processing influence wastewater treatment cost structures in this water-scarce region. Seattle-Portland clusters concentrate small-batch savory ingredient houses seeking toll manufacturing partnerships.
USA Yeast Extracts Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Integrated multinationals with captive yeast supply chains face mid-size ingredient houses leveraging third-party fermentation leasing. Three archetypes dominate: backward-integrated biotech conglomerates, savory flavor system integrators, and toll-manufacturing specialists. Competitive moves concentrate on long-term capacity reservation agreements and precision fermentation technology licensing.
Among European-anchored biotech conglomerates, Lesaffre and DSM exemplify backward-integrated archetypes with North American yeast supply chain control. Kerry Group occupies a position within the flavor-system integrator tier, embedding yeast extracts within broader savory portfolios. Angel Yeast represents the Asia-Pacific specialist archetype competing on fermentation scale economies.
| Leading Market Players |
|---|
| Lesaffre |
| DSM |
| Angel Yeast |
| Lallemand Inc. |
| Kerry Group |
| Synergy Flavors |
| Leiber GmbH |
| Associated British Foods |
| Chr. Hansen |
| Others |
Value Network & Pricing Analysis
Milwaukee-Chicago manufacturing clusters concentrate yeast fermentation capacity within a 200-mile radius of major savory snack and industrial bakery operations, creating localized pricing power for suppliers who can guarantee just-in-time delivery without cross-country freight exposure. This geographic density allows integrated producers to command modest premiums for autolyzed grades while forcing toll-manufacturing specialists to absorb inbound molasses logistics costs.
Pricing Analysis
Certification level (USDA Organic versus conventional) creates the primary spread between commodity and premium yeast extract tiers, with organic claims commanding formulation service premiums from clean-label snack manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects FAN content gradients and spray-drying energy intensity differentials. Cost compression in standard grades is intensifying because FERC-regulated utility volatility feeds directly into spray-drying economics. Animal nutrition buyers exhibit the highest price sensitivity, while pharmaceutical fermentation accounts tolerate premium pricing for endotoxin-controlled GMP documentation.
Supply Chain Analysis
Export-control restrictions on precision fermentation technology limit CRISPR-edited strain flows between US and EU research partnerships, constraining novel peptide development pipelines. Domestic production draws from molasses feedstock anchored in Louisiana and Florida sugar processing, with supplemental cane supply from Central American trade partners. Single-source vulnerability concentrates in proprietary autolysis enzyme supply held by narrow patent holders. Distribution runs through national foodservice operators contracting directly for dedicated fermentation capacity rather than spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough driven by molasses feedstock price normalization following climate-impacted agricultural disruptions. Recovery momentum will favor suppliers with captive yeast supply chains and renewable-powered production assets.
For Market Incumbents: Harden supply security through backward integration into molasses storage and preprocessing infrastructure near Midwest fermentation corridors. Lock in long-term toll manufacturing agreements with plant-based meat analog specialists before precision fermentation startups achieve commercial scale. FDA GRAS pathway tightening represents the most immediate regulatory threat to peptide fraction documentation timelines. For New Entrants and Emerging Players: Pursue white-space opportunities in pharmaceutical-grade yeast extract media serving Boston-Providence therapeutic protein clusters, where GMP certification barriers filter out commodity suppliers. California clean energy incentives create favorable siting economics for renewable-powered nutritional yeast production targeting West Coast vegan manufacturers. Direct-to-manufacturer e-procurement platforms offer disintermediation leverage against established distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational flavor houses seeking to divest non-core yeast extract assets amid portfolio rationalization pressures. Five-to-ten-year viability hinges on precision fermentation technology licensing positions and renewable energy sourcing capabilities. Watch for EPA effluent guideline revisions as the decisive inflection signal for facility economics and stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Supply | Louisiana and Florida sugar processing proximity reduces feedstock volatility exposure for Midwest producers. |
| Renewable-Powered Spray-Drying Capacity | California and New York clean energy incentives enable net-negative emissions profiles for West Coast facilities. |
| Precision Fermentation Technology Licensing | CRISPR-edited strain access differentiates peptide fraction capabilities for targeted umami modulation. |
| Long-Term Toll Manufacturing Agreements | Dedicated capacity contracts with plant-based meat analog manufacturers displace spot-market purchasing patterns. |
| USDA Organic Certification Investment | Eighteen-to-twenty-four-month approval timelines create qualification barriers against non-certified competitors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with savory snack formulation directors, industrial bakery procurement managers, fermentation facility operations heads, and plant-based meat R&D leads. Secondary validation drew from FDA GRAS notification databases, USDA BioPreferred procurement records, FERC utility rate filings, and EPA effluent guideline dockets. Bottom-up volume estimates from individual facility capacities were triangulated against top-down market sizing from trade flow analysis.
Calibration against historical production volumes and disclosed capacity expansions anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (autolyzed, nutritional, active dry, instant), application (flavor enhancer, baking, brewery, animal feed), form (powder, liquid, granule, paste), and end user (food industry, beverage, animal nutrition, pharmaceuticals). CAGRs were derived from trend extrapolation adjusted for feedstock price normalization and regulatory implementation timelines. Molasses supply volatility and FERC rate structures served as primary forecast sensitivity inputs.
Sensitivities concentrate around EPA effluent guideline revisions, USDA Organic certification timeline extensions, and precision fermentation technology licensing access. Forecasts reflect documented assumptions regarding feedstock price normalization and clean energy incentive continuity. Material shifts in federal procurement standards or state-level renewable energy policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Tryptose Market
Ingredients
Corn Steep Liquor Market
Ingredients
Ben Oil Market
Ingredients
Specialty Yeast Market
Ingredients
Starch Market
Ingredients
Fish Gelatin Market
Ingredients
Jojoba Oil Market
Ingredients
Date Syrup Market
Ingredients
Philippines Edible Oils & Fats Market
Ingredients
Yeast Derivatives Market
Ingredients
Hops Market
Ingredients
Textured Milk Protein Market
Ingredients
Kilned Malt Market
Ingredients
Barley Malt Extract Market
Ingredients
Commercial Amino Acids Market
Ingredients
Shortening Fats Market