
 Global Arabinoxylan Fiber Market | 2026-2036
Global Arabinoxylan Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Global Arabinoxylan Fiber Market Analysis
Market Context
Asset-light contract manufacturing partnerships is reconfiguring competitive entry barriers for mid-size ingredient suppliers. Tate & Lyle leverages its corn wet-milling infrastructure to anchor North American arabinoxylan supply chains. Comet Biorefining specializes in agricultural residue conversion, positioning its wheat straw-derived fiber as a sustainable alternative to conventional cereal extracts. J. Rettenmaier & Söhne GmbH dominates European insoluble fiber markets, extending its technical milling expertise into soluble arabinoxylan grades for nutraceutical clients.
Technical Definition and Segment Structure
Arabinoxylan fiber consists of a xylose backbone substituted with arabinose side chains, typically extracted from wheat bran or corn fiber through alkaline hydrolysis or enzymatic treatment, and functions as a soluble prebiotic that selectively ferments in the colon to produce short-chain fatty acids. Powder formulations lead current volume due to bulk ingredient economics and blending flexibility in bakery and beverage applications, while capsule and tablet segments compete on dose precision for pharmaceutical and dietary supplement channels. The food industry end-use segment sustains the broadest demand base, though nutraceuticals occupies the fastest-growing margin pool as direct-to-consumer gut health brands proliferate through online distribution channels.
Regulatory Framework
EFSA novel food evaluations, FDA GRAS self-affirmation pathways, and Health Canada natural health product licensing collectively determine market access timelines and label claim permissibility for arabinoxylan fiber across major consuming jurisdictions. REACH compliance for imported cereal-derived extracts and USDA organic certification for non-GMO positioning add compliance layers that favor suppliers with established regulatory affairs capabilities. Stakeholders must monitor evolving prebiotic definition standards from Codex Alimentarius and national food agencies to anticipate reformulation requirements and competitive positioning shifts.
Market Dynamics
EFSA novel food approvals and FDA GRAS designations are compressing regulatory timelines for arabinoxylan fiber suppliers, enabling faster market entry across multiple jurisdictions while reshaping competitive positioning toward regulatory affairs capabilities.
Growth Catalysts
- Prebiotic definition harmonization:Codex Alimentarius work on prebiotic standards is clarifying label claim permissibility, reducing reformulation risk for functional food manufacturers in Germany and Japan.
- Direct-to-consumer gut health brands:Online distribution channels for nutraceuticals are expanding addressable market reach beyond traditional pharmacy and mass retail networks.
- USDA organic certification:Non-GMO positioning requirements are creating premium tier differentiation for wheat straw-derived fiber against conventional cereal extracts.
Market Restraints
- Alkaline hydrolysis input costs:Sodium hydroxide and energy-intensive extraction processes expose suppliers to commodity chemical price volatility.
- European insoluble fiber incumbent concentration:J. Rettenmaier & Söhne GmbH's technical milling dominance creates customer relationship barriers for soluble grade entrants.
- Enzymatic treatment yield limitations:Current cellulase and xylanase conversion efficiencies cap production economics at commercial scale.
Strategic Opportunities
- Indian functional food penetration:FSSAI regulatory modernization is opening prebiotic bakery and beverage applications previously constrained by ingredient approval backlogs.
- Sports nutrition powder formats:Bulk ingredient economics and blending flexibility are enabling arabinoxylan incorporation into protein and recovery formulations.
- Health Canada natural health product licensing:Streamlined approval pathways for gut-health supplements are accelerating time-to-revenue for capsule and tablet entrants.
Industry Challenges
- Regulatory affairs talent scarcity:REACH compliance and multi-jurisdictional novel food submissions require specialized expertise that mid-size suppliers struggle to recruit.
- Legacy blending equipment incompatibility:Soluble fiber hygroscopicity demands humidity-controlled handling systems that existing bakery infrastructure often lacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Arabinoxylan Fiber Market |
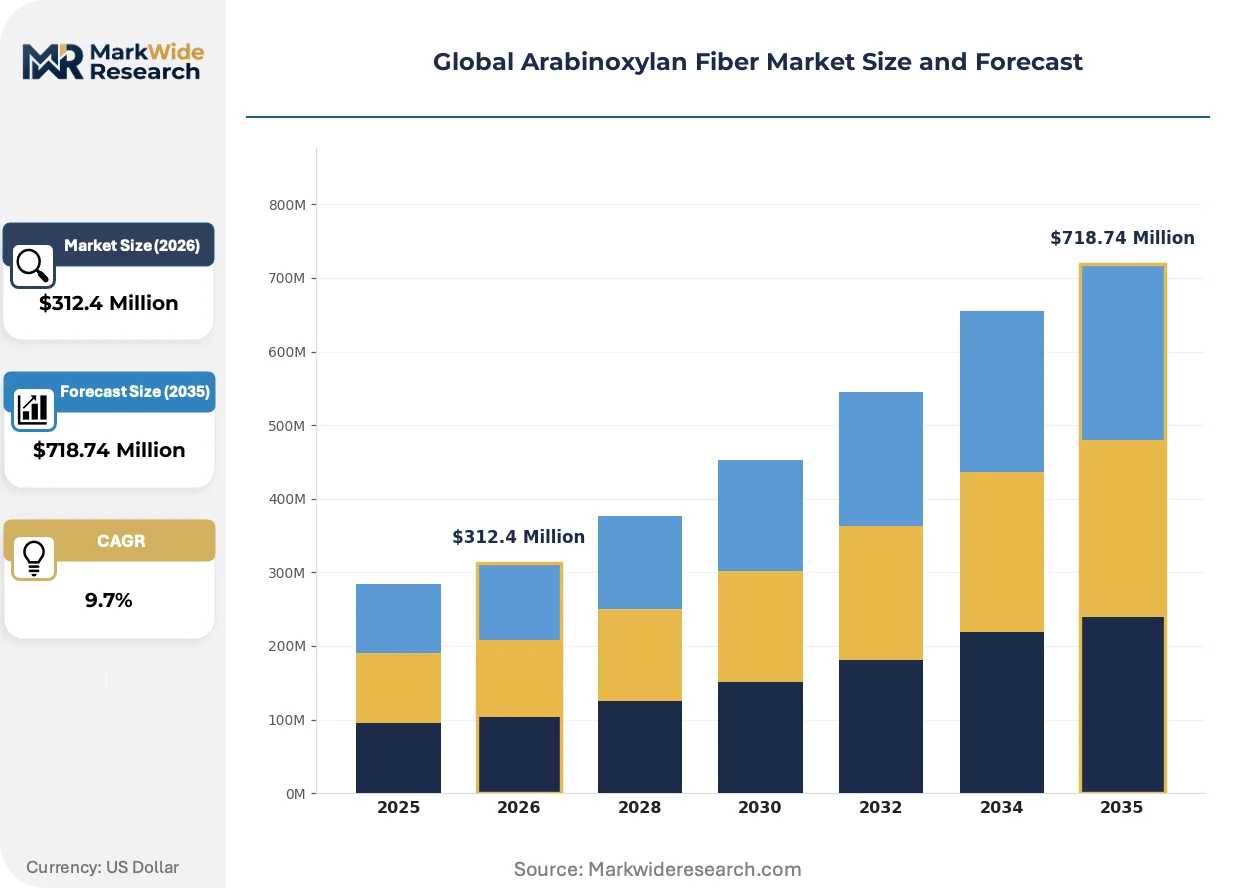
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Capsules, Tablets End User: Food Industry, Nutraceuticals, Pharmaceuticals, Animal Feed Formulation: Organic, Conventional, Dietary Supplements, Functional Foods Distribution Channel: Online, Retail Stores, Direct Sales, Health Food Stores |
| Companies Covered | Tate & Lyle, Comet Biorefining, Archer Daniels Midland (ADM), Daiwa Pharmaceutical, BioActor, Cargill, J. Rettenmaier & Söhne GmbH, Megazyme, DuPont Nutrition & Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Arabinoxylan Fiber Market Emerging Trajectories
Enzymatic extraction technologies and precision fermentation approaches are displacing traditional alkaline hydrolysis methods, altering capital intensity requirements and supplier competitive moats across the value chain.
Cell-free enzymatic bioprocessing isolates specific xylanase and arabinofuranosidase cocktails for targeted backbone cleavage, enabling pharmaceutical-grade purity without harsh chemical residues. Nutraceutical contract manufacturers in Switzerland and the Netherlands are adopting these systems to serve premium supplement brands. Conventional acid-alkaline extraction infrastructure is rendering obsolete for high-margin applications demanding clean-label positioning.
REACH registration requirements for imported cereal-derived extracts are tightening substance characterization obligations, forcing suppliers to invest in analytical capabilities for molecular weight distribution and monosaccharide ratio documentation. European ingredient distributors are consolidating supplier panels to those with established ECHA compliance histories. Wheat bran extract importers face the steepest documentation burdens, redirecting sourcing toward domestic European milling co-products.
Formulation service unbundling is separating fiber supply from application technical support, with brand owners contracting independent R&D houses for stability and sensory optimization. Direct-to-consumer gut health startups in California and New York are bypassing traditional ingredient distributor relationships entirely. This channel compression is most visible in North American nutraceuticals, where online-native brands negotiate directly with agricultural residue processors for custom arabinose substitution ratios.
Global Arabinoxylan Fiber Market Segmentation
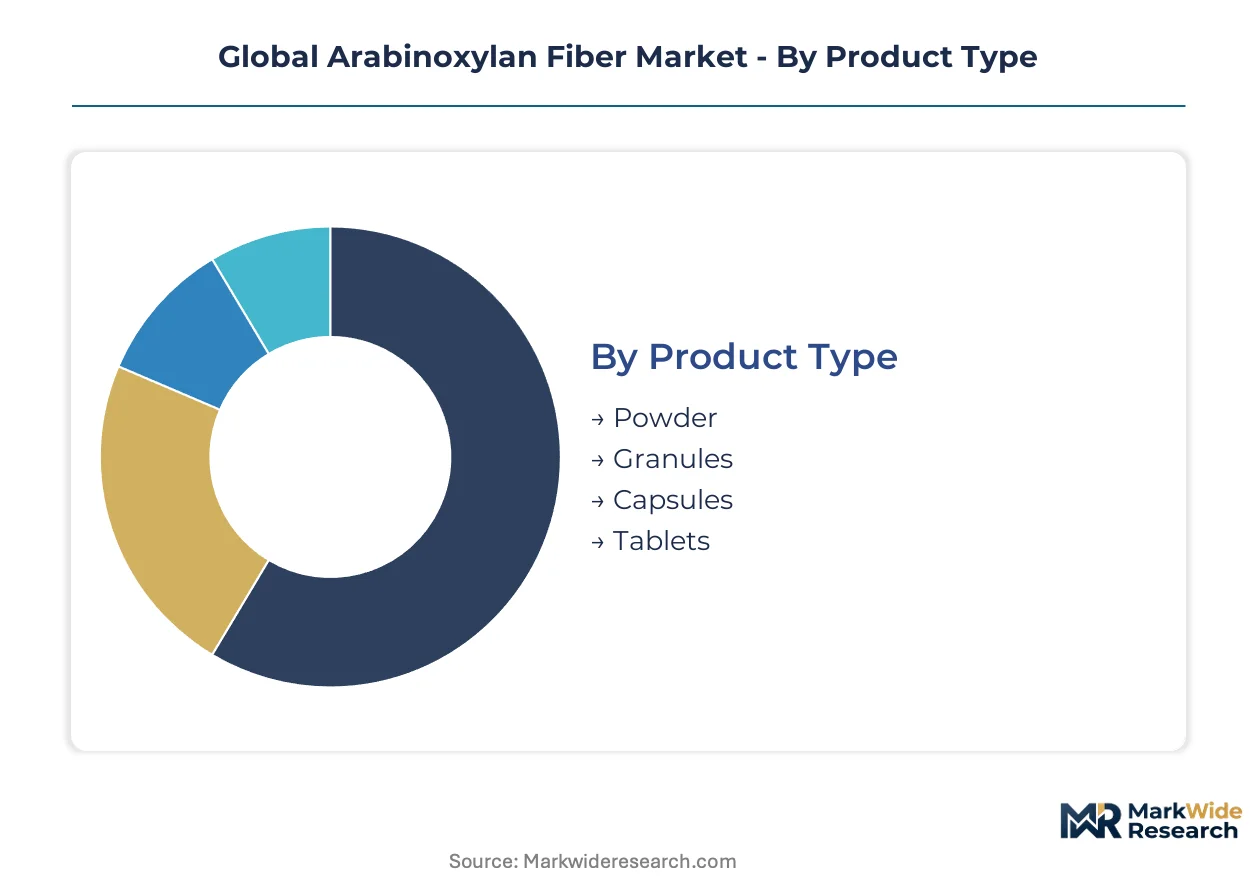
Arabinoxylan fiber suppliers face divergent margin pressures across product formats, with bulk powder commanding volume economics and precision-dose capsules capturing premium positioning in gut-health formulations. Segment selection determines capital intensity, regulatory pathway complexity, and customer concentration risk for new entrants.
Product Type:
Powder formats turn inventory fastest through bakery and beverage bulk procurement, while tablets and capsules cycle slowly through pharmaceutical qualification protocols and stability testing.
- Powder:Fine-milled arabinoxylan with customizable particle size distribution enables seamless incorporation into bread dough and beverage concentrates. German and Japanese nutraceutical manufacturers favor this format for prebiotic blend flexibility, though hygroscopicity demands humidity-controlled handling infrastructure that raises distributor capital requirements.
- Capsules:Hard-shell gelatin or HPMC encapsulation delivers precise dosing for clinical trial applications and direct-to-consumer supplement brands. Health Canada natural health product licensing timelines favor capsule entrants seeking gut-health claims, as powder stability data requirements extend approval cycles.
- Granules:Agglomerated particles improve flow properties for automated tablet presses and sachet filling operations in Swiss contract manufacturing facilities.
- Tablets:Compressed forms with disintegration profiles tailored to colonic release target pharmaceutical channel specifications requiring excipient compatibility documentation.
Powder anchors the volume base while capsules gain share at the steepest rate.
End User:
Cost tiers separate commodity animal feed applications from pharmaceutical-grade specifications demanding full supply chain traceability.
- Nutraceuticals:Direct-to-consumer gut health brands in California and New York bypass traditional distribution to source custom arabinose substitution ratios from agricultural residue processors. EFSA novel food approvals and FDA GRAS self-affirmation create dual-track regulatory positioning for premium prebiotic formulations.
- Food Industry:Bakery and beverage manufacturers integrate arabinoxylan for fiber fortification and shelf-life extension in functional bread and cereal products. USDA organic certification requirements favor wheat straw-derived fiber over conventional cereal extracts for clean-label positioning in North American retail channels.
- Pharmaceuticals:Clinical-stage developers require pharmaceutical-grade purity with documented molecular weight distribution for investigational new drug submissions.
- Animal Feed:Poultry and swine nutritionists incorporate lower-purity grades for gut microbiome modulation in antibiotic-free production systems.
Food Industry sustains the broadest demand foundation while nutraceuticals climbs the fastest toward margin leadership.
Formulation:
Application requirements dictate input sourcing, with functional foods demanding heat stability and dietary supplements prioritizing bioavailability documentation.
- Functional Foods:Heat-stable arabinoxylan variants withstand extrusion and baking temperatures above 180°C without significant viscosity degradation. Japanese functional beverage manufacturers lead incorporation into fermented dairy and plant-based milk alternatives.
- Dietary Supplements:Standalone prebiotic capsules and powder sachets target colonic fermentation kinetics with specific arabinose-to-xylose ratios documented for short-chain fatty acid yield claims.
- Organic:Non-GMO positioning with full agricultural input traceability commands 15-30% price premiums in European and North American natural product channels.
- Conventional:Standard-grade material from wheat wet-milling co-products serves cost-sensitive bakery fortification applications with less stringent certification requirements.
Conventional formulations dominate current volume while organic certification expands most quickly in premium tier positioning.
Distribution Channel:
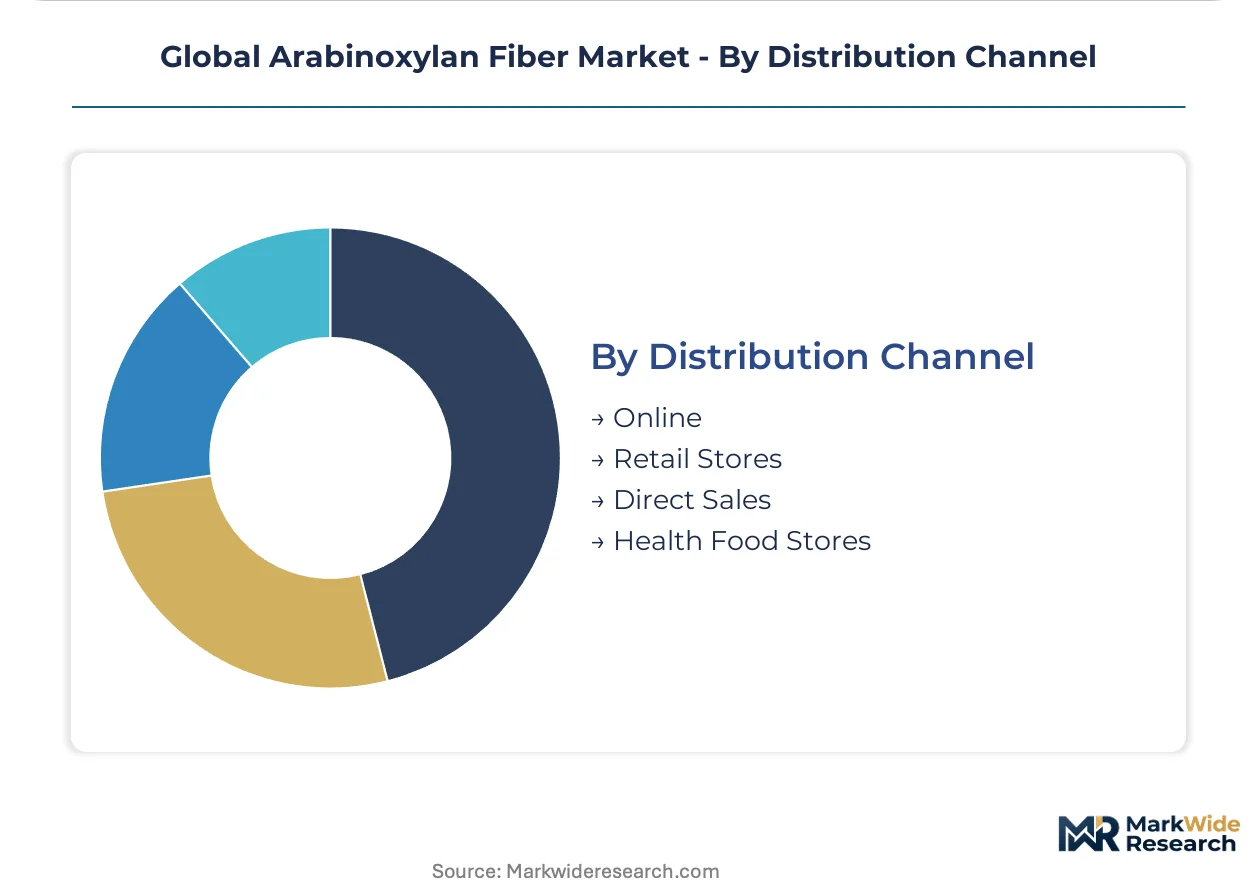
Customer type fragmentation separates price-sensitive bulk procurement from relationship-driven technical service arrangements.
- Online:Direct-to-consumer platforms enable gut-health startups to bypass ingredient distributor markups and negotiate custom specifications with Comet Biorefining and similar agricultural residue processors. California-based brands leverage this channel compression for rapid formulation iteration.
- Direct Sales:Technical field support from J. Rettenmaier & Söhne GmbH and Tate & Lyle secures long-term supply agreements with multinational bakery and pharmaceutical manufacturers requiring application development assistance.
- Health Food Stores:Independent natural product retailers in Germany and Switzerland curate premium prebiotic assortments with organic and non-GMO verification visible on packaging.
- Retail Stores:Mass-market supermarkets and pharmacy chains in Japan distribute functional food and supplement products with established FOSHU or comparable regulatory endorsements.
Direct Sales secures the largest contract value while online channels expand most rapidly through brand disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food approvals and USDA organic certification programs are accelerating ingredient access across major consuming jurisdictions. National regulators in Germany, Japan, and the United States are streamlining prebiotic label claim pathways. Industrial clusters in Switzerland, California, and the Netherlands concentrate contract manufacturing and formulation expertise.
Germany
German nutraceutical manufacturers are expanding arabinoxylan incorporation into prebiotic formulations for functional food applications. EFSA novel food evaluations provide regulatory clarity for wheat bran-derived fiber ingredients. The Baden-Württemberg region hosts specialized milling operations that supply soluble fiber grades to pharmaceutical and supplement clients.
United States
Direct-to-consumer gut health brands in California and New York are bypassing traditional distribution channels to negotiate custom specifications. FDA GRAS self-affirmation pathways enable faster market entry for corn fiber-derived ingredients. Corn wet-milling infrastructure in the Midwest anchors North American supply chain security for bulk ingredient procurement.
Japan
Japanese functional beverage manufacturers lead incorporation of arabinoxylan into fermented dairy and plant-based milk alternatives. METI guidelines on functional food labeling support FOSHU-compatible prebiotic claims. The Kanto region around Tokyo concentrates formulation R&D houses serving premium nutraceutical brands.
Switzerland
Swiss contract manufacturing facilities are adopting cell-free enzymatic bioprocessing systems for pharmaceutical-grade fiber production. Swissmedic oversight ensures quality documentation for investigational new drug submissions. The Basel-Zurich corridor hosts precision fermentation specialists serving European nutraceutical markets.
Netherlands
Dutch ingredient distributors are consolidating supplier panels to prioritize REACH-registered cereal extract importers. ECHA compliance requirements tighten substance characterization obligations for wheat bran derivatives. The Rotterdam-Antwerp port cluster facilitates import logistics for agricultural residue processors.
Global Arabinoxylan Fiber Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent margin pools. Tate & Lyle leverages corn wet-milling infrastructure to anchor North American supply chains, while J. Rettenmaier & Söhne GmbH dominates European insoluble fiber markets. Three archetypes define competitive positioning: agricultural residue processors, cereal wet-milling incumbents, and enzymatic extraction specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers seek regulatory affairs capabilities and application technical support.
Among agricultural residue processors, Comet Biorefining exemplifies the sustainable sourcing archetype through wheat straw-derived fiber positioning. Tate & Lyle and J. Rettenmaier & Söhne GmbH occupy established positions within the cereal wet-milling and technical milling tiers respectively. These three entities represent distinct strategic postures: residue-based sustainability claims, captive corn supply integration, and European milling expertise extension into soluble grades.
| Leading Market Players |
|---|
| Tate & Lyle |
| Comet Biorefining |
| Archer Daniels Midland (ADM) |
| Daiwa Pharmaceutical |
| BioActor |
| Cargill |
| J. Rettenmaier & Söhne GmbH |
| Megazyme |
| DuPont Nutrition & Biosciences |
| Others |
Supply Flow & Price Mechanics
Midwest corn wet-milling concentration anchors North American bulk supply, directing margin capture toward pharmaceutical-grade enzymatic extraction specialists in Switzerland and the Netherlands. Certification premiums for EFSA novel food status and FDA GRAS documentation create tiered pricing separation between commodity cereal extracts and clean-label agricultural residue derivatives.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and feed-grade material, with EFSA novel food status and FDA GRAS documentation commanding substantial premiums over conventional cereal extracts. Three-tier pricing structure separates organic-certified wheat straw fiber from standard wet-milling co-products from unbranded commodity grades. Pricing pressure stems from enzymatic treatment yield limitations that constrain production economics at commercial scale. Animal feed buyers exhibit highest price sensitivity, while nutraceutical contract manufacturers prioritize batch consistency and regulatory documentation over unit cost.
Supply Chain Analysis
Tariff exposure between North American corn belt suppliers and European REACH-registered importers dominates supply chain risk planning for multinational nutraceutical manufacturers. Production gravity centers on the United States, Germany, and Japan, with wheat bran extract importers facing steep ECHA documentation burdens that redirect sourcing toward domestic European milling co-products. The supply chain draws from sodium hydroxide, cellulase and xylanase enzymes, and humidity-controlled handling infrastructure. Single-source vulnerability concentrates in J. Rettenmaier & Söhne GmbH's European insoluble fiber dominance. Distribution runs through direct technical sales for multinational bakery and pharmaceutical accounts, with online channels expanding rapidly for direct-to-consumer gut health startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with EFSA novel food approval timelines and FDA GRAS documentation requirements creating switching costs that favor established suppliers with specialized regulatory affairs capabilities.
For Market Incumbents: Harden regulatory affairs capabilities through dedicated ECHA compliance teams and multi-jurisdictional novel food submission expertise, addressing the talent scarcity that constrains mid-size competitors. Expand capacity in enzymatic extraction infrastructure to capture pharmaceutical-grade margin pools as alkaline hydrolysis methods render obsolete for clean-label applications. Deepen technical field support relationships with multinational bakery manufacturers to defend against direct-to-consumer brand disintermediation. For New Entrants and Emerging Players: Build out white-space positioning in Indian functional food penetration, where FSSAI regulatory modernization is opening prebiotic bakery and beverage applications previously constrained by ingredient approval backlogs. Target sports nutrition powder formats for bulk ingredient economics and blending flexibility into protein and recovery formulations. Pursue direct online negotiation with agricultural residue processors to bypass traditional distributor markups and secure custom arabinose substitution ratios. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic extraction specialists as cell-free bioprocessing systems displace conventional acid-alkaline infrastructure. Long-term viability favors acquisition targets with established EFSA approval histories and REACH-registered supplier status, given the tightening substance characterization obligations for wheat bran derivatives. Monitor Codex Alimentarius prebiotic definition harmonization as the signal to watch for reformulation-driven demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Approval | Regulatory clarity from EFSA evaluations compresses market entry timelines for wheat bran-derived ingredients. |
| Enzymatic Extraction Scale-Up | Cell-free bioprocessing adoption by Swiss contract manufacturers enables pharmaceutical-grade purity without chemical residues. |
| Backward Integration into Agricultural Residue Supply | Wheat straw sourcing control secures sustainable positioning premiums against conventional cereal extract competitors. |
| Direct-to-Consumer Channel Development | Online distribution bypasses ingredient distributor markups for California and New York gut health startups. |
| Health Canada Natural Health Product Licensing | Streamlined approval pathways accelerate time-to-revenue for capsule and tablet entrants in gut-health supplements. |
Methodological Framework
Cross-validation between primary interviews with regulatory affairs directors, nutraceutical contract manufacturing executives, and agricultural residue procurement managers and secondary sources including EFSA novel food registers, FDA GRAS notices, and REACH registration databases anchors the qualitative findings. Bottom-up volume estimates from grade-specific production capacity and top-down demand validation from end-use consumption patterns were reconciled through iterative calibration.
Calibration against historical EFSA approval timelines and FDA GRAS self-affirmation patterns refined the projection framework across the analysis window. Segmentation dimensions modeled include product format, end-use application, formulation certification tier, and distribution channel structure. CAGRs were derived from elasticity-adjusted demand curves incorporating prebiotic label claim permissibility evolution and enzymatic treatment yield improvement trajectories.
Stress conditions across sodium hydroxide input cost volatility, REACH compliance documentation burdens, and enzymatic conversion efficiency thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization progress and extraction technology adoption curves. Material shifts in Codex Alimentarius prebiotic standards or EFSA novel food evaluation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydrolyzed Oat Protein Market
Ingredients
Low Fat Oil Market
Ingredients
Milk Mineral Concentrate Market
Ingredients
Cocoa Maker Market
Ingredients
Middle East and Africa Pea Starch Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
High Protein Flour Market
Ingredients
Native Starch Market
Ingredients
North America Fats and Oils Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Astragalus Root Extract Market
Ingredients
Global Tomato Powder Market
Ingredients
North America Potato Protein Market
Ingredients
Mulberry Leaf Extract Market
Ingredients
Microbial Food Ingredients Market
Ingredients
North America Milk Protein Market