
 Antimicrobial Coil Coating Market | 2026-2036
Antimicrobial Coil Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Coil Coating Market Outlook
Performance-based maintenance contracts is realigning how antimicrobial coil coatings are monetized, shifting value capture from upfront material sales to guaranteed hygiene outcomes over equipment life cycles. Akzo Nobel N.V. leverages its marine and protective coatings heritage to anchor technical credibility in HVAC specification channels. PPG Industries Inc. sustains R&D intensity in silver-ion release technologies that differentiate long-term antimicrobial efficacy claims. BASF SE competes through backward integration into biocide active ingredients, controlling raw material quality and regulatory compliance costs.
Antimicrobial coil coating denotes a functional surface treatment applied to aluminum or copper heat exchanger coils, incorporating biocidal agents such as silver ions, zinc pyrithione, or quaternary ammonium compounds into a polymer binder matrix at film thicknesses typically ranging from 25 to 75 microns, designed to inhibit microbial colonization and preserve thermal transfer efficiency. The polyester chemistry segment dominates current specification volumes due to its balance of UV durability, cost position, and compatibility with continuous coil coating lines, while polyurethane formulations are gaining fastest in premium HVAC applications where flexibility and chemical resistance command margin premiums. Powder coating technology occupies the largest installed application base, though UV-curable liquid systems are capturing attention for energy-cured lines seeking reduced volatile organic compound footprints.
The EPA regulates antimicrobial claims through FIFRA registration requirements that mandate efficacy data against specific microbial targets, while REACH in Europe restricts certain biocidal active substances through authorization and substitution protocols that reshape formulation portfolios for export-oriented suppliers. OSHA ventilation standards and ASHRAE indoor air quality guidelines indirectly drive specification by linking microbial control to occupant health outcomes in commercial buildings. Stakeholders must monitor evolving biocide authorization timelines and third-party certification programs to anticipate which chemistries will retain market access.
Market Dynamics
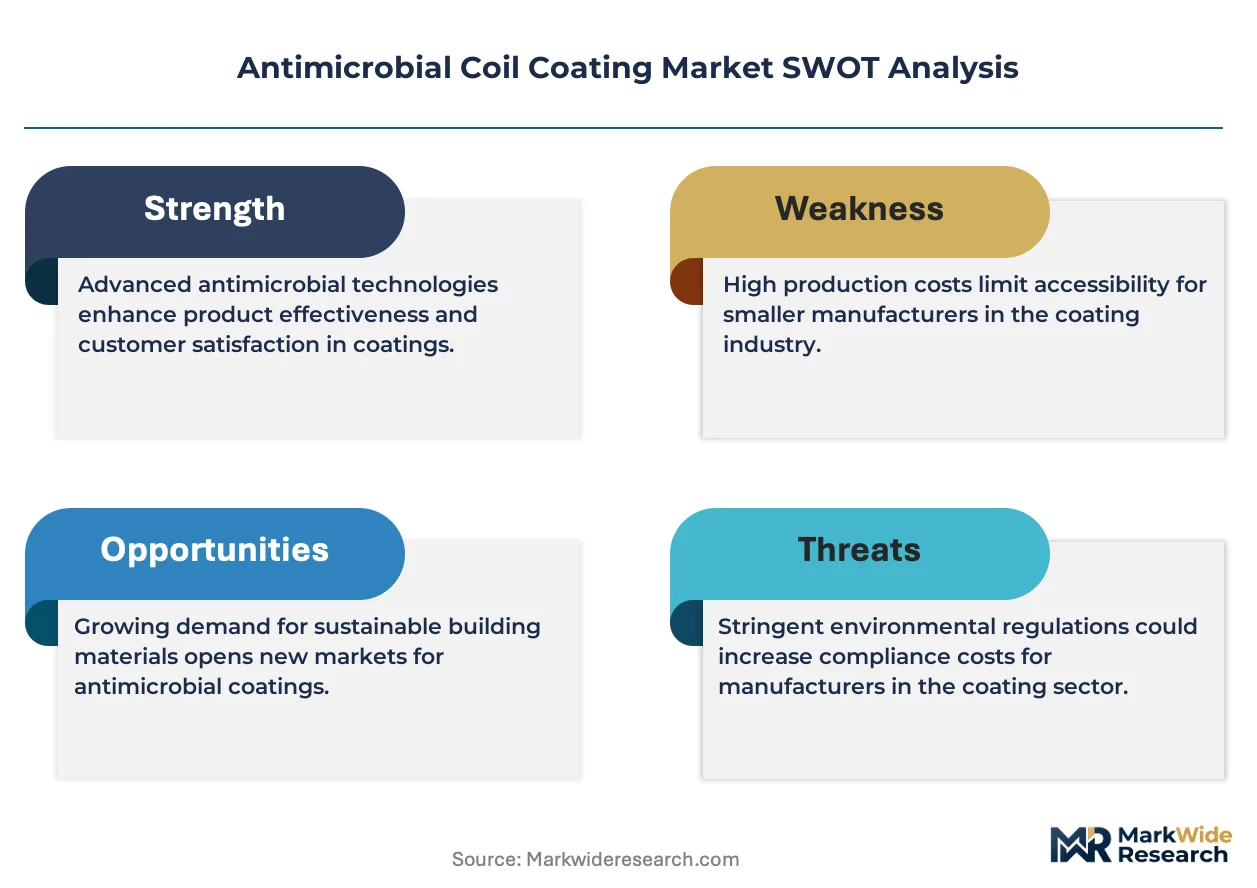
HVAC system manufacturers are expanding specification of antimicrobial-treated coils to counter biofilm-related efficiency losses, while tightening EPA registration requirements under FIFRA are forcing reformulation investments and extended efficacy testing protocols across supplier portfolios.
Growth Catalysts
- Hospital construction standards:United States healthcare facility codes now mandate indoor air quality controls that specify antimicrobial coil treatments for new HVAC installations, driving specification intensity in commercial construction channels.
- REACH authorization protocols:European biocide substitution requirements are accelerating development of next-generation active ingredients, creating competitive advantage for suppliers with advanced formulation pipelines.
- Silver-ion release technologies:Extended-duration antimicrobial efficacy claims are differentiating premium coating offerings in data center and pharmaceutical manufacturing applications where downtime costs dominate procurement criteria.
Market Restraints
- Silver price volatility:Primary active ingredient cost fluctuations compress margin stability for formulations dependent on ionic silver biocides, forcing hedging strategies or chemistry pivots.
- Biocide supplier concentration:European specialty chemical producers control key quaternary ammonium compound supply, creating geographic vulnerability for North American coating manufacturers.
- Efficacy testing duration:EPA FIFRA registration timelines extend 18-24 months for novel antimicrobial claims, delaying product commercialization and freezing formulation investments.
Strategic Opportunities
- UV-curable liquid systems:Energy-cured coating lines seeking volatile organic compound reduction present conversion opportunity for suppliers with compatible resin and photoinitiator portfolios.
- Performance-based maintenance contracts:HVAC service providers are adopting guaranteed hygiene outcome models that shift value capture from material sales to lifecycle antimicrobial performance assurance.
- Indian pharmaceutical manufacturing expansion:Domestic production capacity growth under PLI scheme incentives is creating specification demand for contamination-controlled HVAC systems in sterile processing environments.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in biocide-polymer compatibility and UV durability testing commands premium compensation, constraining R&D team scaling for mid-tier suppliers.
- Continuous coil line integration:Retrofitting existing coating operations for antimicrobial application requires capital-intensive web handling and curing system modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Coil Coating Market |
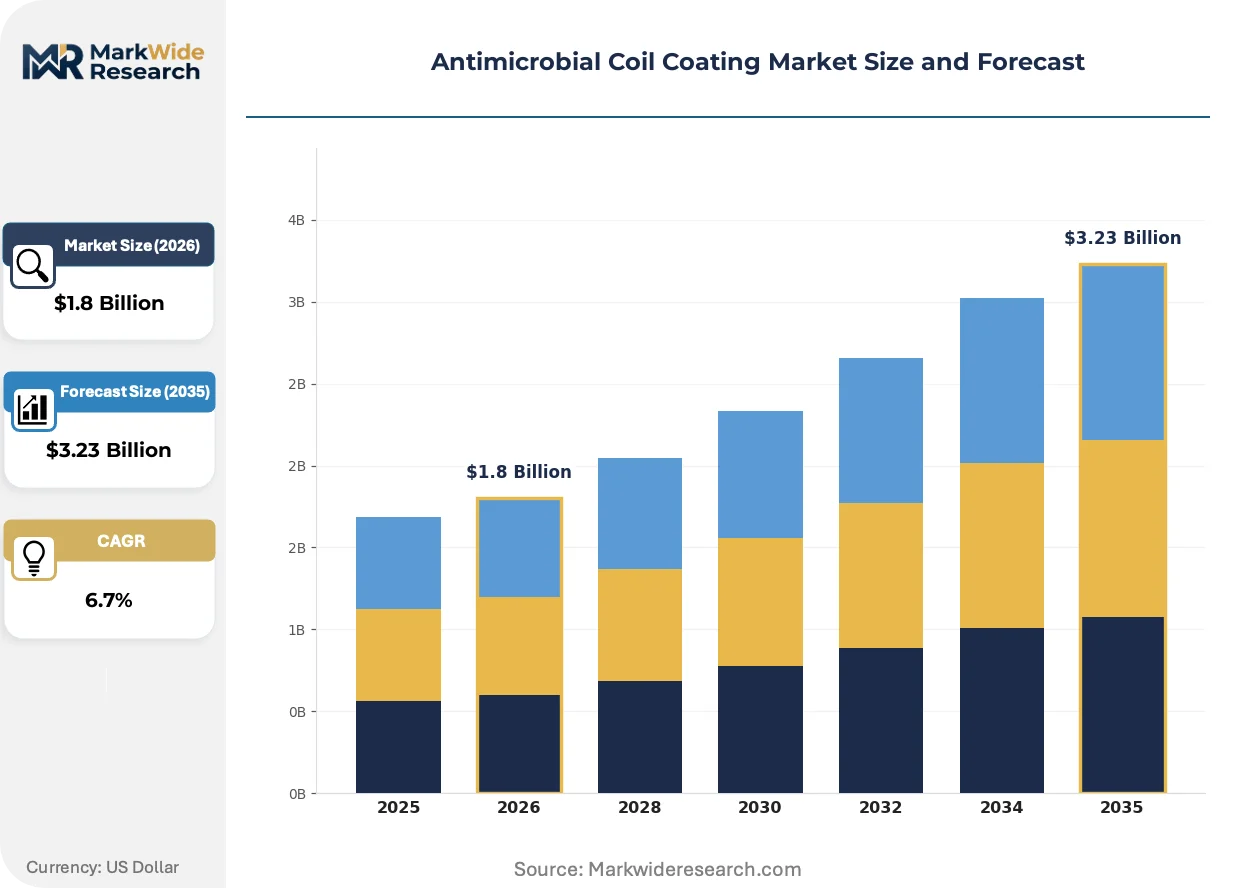
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyester, Polyurethane Application: Building & Construction, HVAC, Consumer Goods, Automotive End User: Manufacturers, Contractors, Distributors, Retailers Technology: Electrostatic Spray, Powder Coating, Liquid Coating, UV Coating |
| Companies Covered | Akzo Nobel N.V., PPG Industries Inc., BASF SE, The Sherwin-Williams Company, Axalta Coating Systems Ltd., DuPont, Nippon Paint Holdings Co., Ltd., Kansai Paint Co., Ltd., Beckers Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Coil Coating Market Strategic Shifts
Coating formulation science is converging with HVAC equipment digitalization, creating new specification criteria that prioritize verified antimicrobial performance over material cost minimization in premium segments.
UV-curable liquid coating systems are automating quality assurance through inline photoinitiator monitoring and real-time film thickness verification. Data center operators in Singapore and Northern Virginia are specifying these systems for new construction, compressing installation timelines and reducing volatile organic compound exposure during facility commissioning. The technology is automating specification decisions that previously required extended field validation periods.
EPA FIFRA registration requirements for antimicrobial claims are tightening efficacy data standards against specific microbial targets including Legionella pneumophila and Aspergillus species. Coating suppliers must now submit standardized test protocols under Good Laboratory Practice guidelines, extending pre-market investment horizons. Hospital construction specifications in California and Texas are responding by requiring third-party certification of antimicrobial performance claims prior to bid acceptance.
Facility managers are unbundling HVAC hygiene assurance from traditional maintenance contracts, creating standalone antimicrobial performance verification services. Engineering procurement departments in pharmaceutical manufacturing and food processing verticals are demanding continuous monitoring data rather than periodic inspection reports. This behavioral shift is most visible in German automotive component facilities and Japanese precision electronics manufacturing clusters where contamination control directly correlates with yield rates.
Antimicrobial Coil Coating Market Segmentation
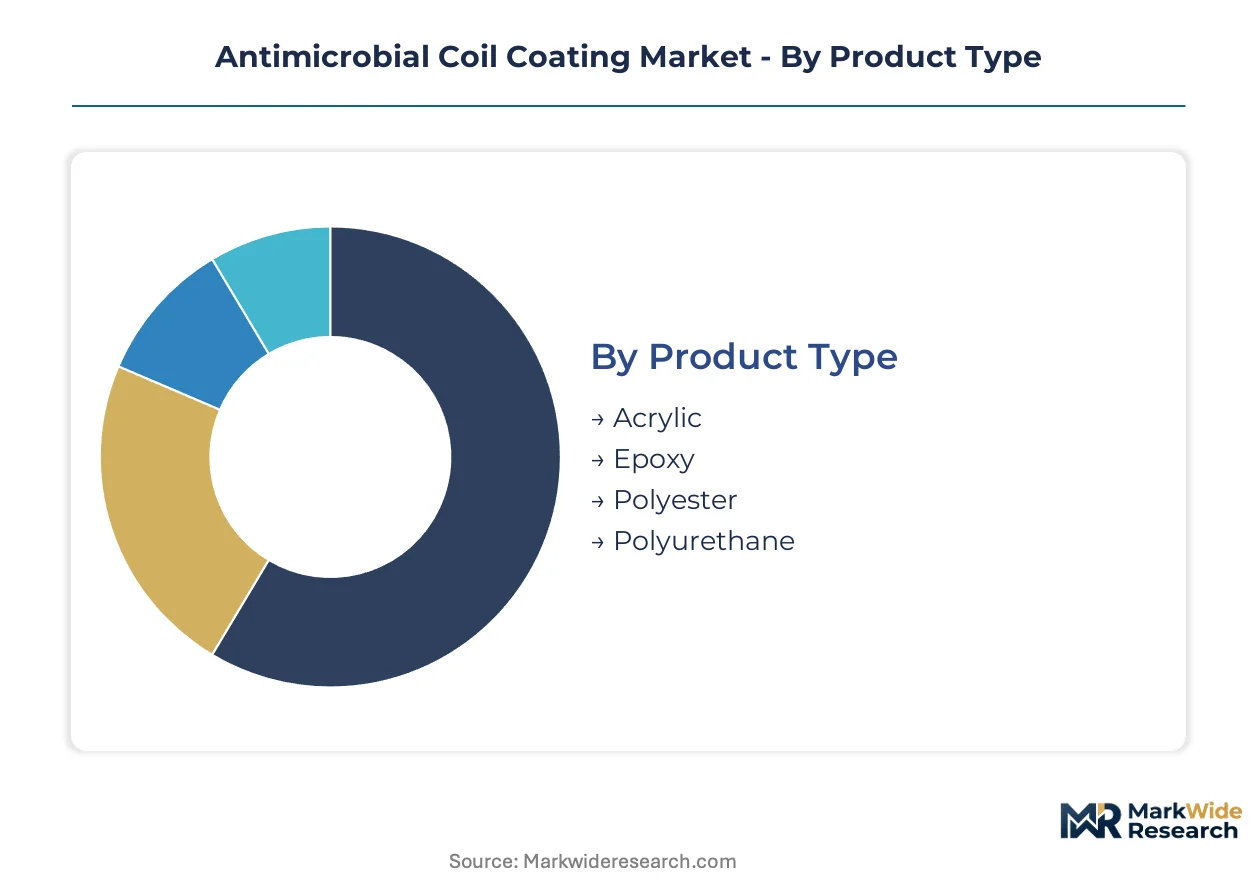
Antimicrobial coil coating procurement varies sharply by specification tier, with hospital HVAC systems demanding EPA-registered formulations while commercial buildings prioritize cost-efficient polyester alternatives. Understanding these segment boundaries clarifies where formulation investments translate to defendable margin positions versus commodity competition.
Product Type:
EPA FIFRA registration requirements apply differentially across polymer chemistries, with silver-ion-releasing polyurethanes facing extended efficacy testing timelines compared to zinc-pyrithione polyesters.
- Polyester:Dominates specification volumes through balanced UV durability and continuous coil line compatibility. Hospital construction in Texas and California specifies this chemistry for cost-controlled antimicrobial protection in large-scale HVAC retrofits.
- Polyurethane:Premium formulations command margin premiums through flexibility and chemical resistance. Data center operators in Northern Virginia and Singapore specify these coatings where thermal transfer efficiency preservation justifies higher material costs.
- Acrylic:Waterborne systems serve lower-budget commercial applications with simplified application protocols.
- Epoxy:High-crosslink density suits aggressive chemical environments in pharmaceutical manufacturing facilities.
Leading the category by volume: Polyester. Growing fastest: Polyurethane.
Application:
End-use concentration determines whether coatings must satisfy ASHRAE indoor air quality guidelines or general corrosion protection standards.
- HVAC:Heat exchanger coils in healthcare and data center infrastructure drive premium specification. Building codes in California and Texas now mandate antimicrobial treatments for new hospital installations, compressing procurement timelines for certified suppliers.
- Building & Construction:Commercial facade and structural metal applications prioritize cost efficiency over extended antimicrobial claims. German automotive component facilities and Japanese precision electronics clusters specify contamination-controlled HVAC systems that cascade demand to coil treatments.
- Consumer Goods:Appliance manufacturers specify antimicrobial coatings for refrigerator and air conditioner coils in humid climates.
- Automotive:HVAC systems in electric vehicles require lightweight coil treatments with thermal management properties.
HVAC dominates current procurement volumes. Building & Construction exhibits steepest expansion trajectory as indoor air quality mandates proliferate.
End User:
Channel structure shapes whether value capture concentrates in material sales or performance-based service contracts.
- Manufacturers:HVAC original equipment producers specify coatings at design stage, locking in multi-year supply agreements. These stakeholders prioritize EPA registration documentation and third-party certification prior to bid acceptance.
- Contractors:Installation and maintenance providers are adopting guaranteed hygiene outcome models. Facility managers in pharmaceutical manufacturing unbundle antimicrobial verification from traditional service contracts.
- Distributors:Regional stocking decisions concentrate around construction cycle timing and inventory carrying costs.
- Retailers:Consumer-facing channels serve replacement coil and DIY maintenance segments.
Manufacturers lead by specification influence. Contractors represent the fastest-climbing channel as performance-based contracts displace transactional sales.
Technology:
Capital intensity and volatile organic compound exposure differentiate application methods across regulatory jurisdictions.
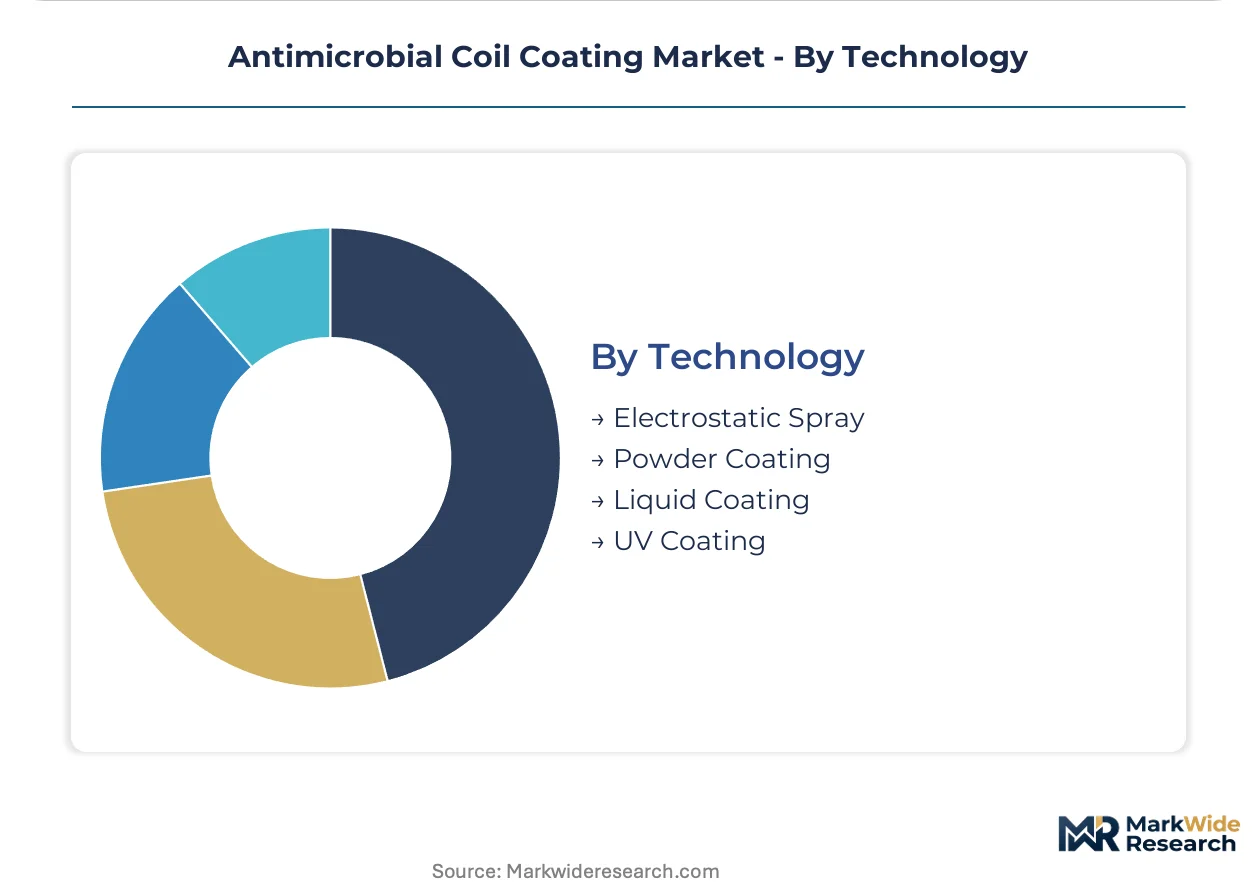
- Powder Coating:Occupies the largest installed base through continuous coil line integration. The technology requires web handling and curing system modifications that constrain retrofit economics for mid-tier suppliers.
- UV Coating:Energy-cured liquid systems automate quality assurance through inline photoinitiator monitoring. Singapore data center operators specify these for compressed installation timelines and reduced VOC exposure during commissioning.
- Liquid Coating:Conventional solventborne and waterborne systems serve legacy equipment maintenance.
- Electrostatic Spray:Precision application method for complex coil geometries in pharmaceutical cleanroom environments.
Powder coating leads by installed capacity. UV coating gains share fastest as energy-cured lines seek regulatory compliance advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coating production concentrates in industrialized economies with established chemical manufacturing bases, while consumption growth accelerates in markets tightening indoor air quality regulations. The United States and Germany anchor formulation capacity, with demand expansion shifting toward Asia-Pacific healthcare infrastructure and Middle Eastern data center construction.
United States
Hospital construction standards in California and Texas mandate antimicrobial coil treatments for new HVAC installations under ASHRAE guidelines. EPA FIFRA registration requirements tighten efficacy testing protocols, extending pre-market timelines for novel biocide formulations. Data center clusters in Northern Virginia specify premium polyurethane coatings where thermal efficiency preservation justifies higher procurement costs.
Germany
Automotive component facilities and precision electronics manufacturing clusters drive contamination-controlled HVAC specifications that cascade demand to coil treatments. REACH authorization protocols restrict certain quaternary ammonium compounds, accelerating development of next-generation active ingredients. Bavarian pharmaceutical manufacturing expansion under EU Green Deal incentives creates specification intensity for EPA-registered formulations in sterile processing environments.
China
Domestic HVAC equipment production scales to serve hospital infrastructure expansion under national healthcare modernization programs. GB standards for indoor air quality in public buildings indirectly drive antimicrobial specification through ventilation system performance mandates. Yangtze River Delta manufacturing bases integrate continuous coil coating lines to capture export demand from Southeast Asian data center construction.
India
Pharmaceutical manufacturing capacity growth under PLI scheme incentives generates specification demand for contamination-controlled HVAC systems in sterile processing. Central Drugs Standard Control Organization guidelines for cleanroom environments influence procurement criteria for antimicrobial-treated coils. Maharashtra and Gujarat industrial corridors attract coating suppliers establishing local formulation capacity to serve domestic HVAC OEMs.
Singapore
Tropical climate conditions accelerate biofilm formation on heat exchanger coils, driving preventive antimicrobial specification in commercial and healthcare facilities. Energy-cured UV coating systems gain traction among data center operators seeking compressed installation timelines and reduced volatile organic compound exposure during facility commissioning. The city-state's position as a regional headquarters for multinational HVAC manufacturers concentrates specification influence for Asia-Pacific export markets.
Antimicrobial Coil Coating Market Competitive Environment
Top-tier vendors anchor premium specification channels through EPA registration documentation and third-party certification assets, while mid-tier suppliers compete on cost-efficient polyester formulations for commercial building retrofits. The market structure reflects consolidation among integrated chemical conglomerates with captive biocide supply, alongside specialized coating formulators serving regional HVAC OEM relationships. Strategic archetypes include backward-integrated active ingredient producers, marine coatings heritage players leveraging technical credibility, and UV-curable system specialists. Dominant competitive moves encompass formulation pipeline investments addressing REACH substitution timelines, and strategic partnerships with HVAC service providers adopting performance-based maintenance contracts.
Among heritage coatings conglomerates, Akzo Nobel N.V. and PPG Industries Inc. occupy positions exemplifying technical credibility anchored in marine and protective coatings expertise. BASF SE represents the backward-integrated archetype with captive biocide active ingredient production. These three entities collectively illustrate how control over raw material quality, regulatory compliance infrastructure, and long-duration efficacy testing capabilities separates premium-tier specification access from commodity coating competition.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries Inc. |
| BASF SE |
| The Sherwin-Williams Company |
| Axalta Coating Systems Ltd. |
| DuPont |
| Nippon Paint Holdings Co., Ltd. |
| Kansai Paint Co., Ltd. |
| Beckers Group |
| Others |
Value Chain & Pricing Dynamics
Data center operators in Northern Virginia and Singapore anchor premium-tier procurement, concentrating pricing power with EPA-registered suppliers capable of documenting Legionella pneumophila efficacy under FIFRA protocols. This buyer concentration enforces three-tier pricing stratification across premium polyurethane, standard polyester, and economy-grade acrylic formulations.
Pricing Analysis
Margin tightening in silver-ion-releasing polyurethanes reflects raw material cost volatility and extended EPA registration timelines stretching 18-24 months. Pricing stratifies across premium, standard, and economy tiers based on biocide active ingredient certification grade and volume commitment scale. Cost compression accelerates in zinc-pyrithione polyesters as Asian HVAC OEMs qualify second-source suppliers. Hospital construction channels in California and Texas exhibit lowest price sensitivity, prioritizing third-party certification over procurement cost minimization.
Supply Chain Analysis
Dual-sourcing requirements from HVAC original equipment manufacturers in the United States and Germany mandate qualification of at least two biocide active ingredient suppliers per coating line. Supply concentrates in Germany for quaternary ammonium compounds, China for zinc pyrithione intermediates, and the United States for silver-ion masterbatches. Raw material dependencies span ionic silver salts, photoinitiators for UV-curable systems, and specialized polyester resins. Single-source vulnerability concentrates in European REACH-authorized biocide supply. Distribution runs through regional coating applicators with continuous coil line integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antimicrobial coil coating competition has become a vertical-integration race, with formulation houses capturing margin by internalizing biocide active ingredient production and EPA registration infrastructure.
For Market Incumbents: Extend EPA registration documentation advantages into performance-based maintenance contracts with HVAC service providers. Consolidate position by acquiring UV-curable resin specialists in Singapore and Northern Virginia data center corridors. Counter REACH substitution threats with captive pipeline investments in next-generation quaternary ammonium alternatives.
For New Entrants and Emerging Players: The price-point gap between premium polyurethane and economy polyester creates entry space for mid-tier UV-curable specialists. Target Indian pharmaceutical manufacturing clusters under PLI scheme expansion, where CDSCO cleanroom guidelines drive first-time specification demand. Lead with compressed installation timelines and VOC compliance rather than long-duration efficacy claims.
For Investors and Strategic Acquirers: The window for entry favors backward-integrated biocide producers with existing REACH authorization assets. Long-term viability hinges on control over active ingredient supply and registration infrastructure. Watch EPA FIFRA efficacy testing timeline extensions as the inflection signal for consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biocide Active Ingredients | BASF SE's captive supply of quaternary ammonium compounds insulates margin from European authorization delays. |
| EPA FIFRA Registration Investment | Extended efficacy testing against Legionella pneumophila secures hospital construction specification in California and Texas. |
| UV-Curable System Development | Singapore data center operators specify energy-cured lines for reduced commissioning timelines and VOC exposure. |
| Performance-Based Maintenance Partnerships | HVAC service providers in Germany and Japan unbundle hygiene verification from traditional service contracts. |
| Regional Formulation Capacity in India | Maharashtra and Gujarat industrial corridors attract coating suppliers serving domestic pharmaceutical HVAC demand under PLI incentives. |
Study Parameters
Regulatory filings with EPA and ECHA, customs trade data for coating raw materials, and SEC 10-K disclosures from heritage coatings conglomerates formed the secondary backbone. Primary interviews with HVAC OEM procurement directors, EPA registration consultants, coil coating line operators, and hospital facility engineering managers validated formulation trends and specification timelines. Bottom-up triangulation across polymer chemistry segments and top-down cross-checks against ASHRAE guideline adoption rates anchored volume estimates.
Bottom-up modeling built from continuous coil line capacity installations, biocide active ingredient consumption patterns, and EPA registration cohort sizes across the analysis window. Top-down verification referenced HVAC equipment production forecasts and hospital construction permit data. Segmentation dimensions included polymer chemistry tier, application technology, and end-use vertical with regulatory intensity scoring. CAGRs derived from regression against ASHRAE standard adoption curves and REACH authorization timeline impacts.
Inputs from EPA registration databases and ECHA authorization lists were available through the study window; gaps in proprietary coil coating line utilization rates introduce uncertainty bands around capacity-based estimates. Deviation in EPA FIFRA efficacy testing protocol changes or REACH substitution acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Canada Automotive OEM Coatings Market
Coatings
Germany Protective Coatings Market
Coatings
Global Performance Coating Market
Coatings
Global Smart Coating Market
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
Sol-Gel Coatings Market
Coatings
United States Industrial Wood Coatings Market
Coatings
Wire Enamels Market
Coatings
Global Antiviral Coatings Market
Coatings
Shipping Container Coatings Market
Coatings
Waterborne Wood Coatings Market
Coatings
Global Diamond Coatings Market
Coatings
High Performance Epoxy Coating Market
Coatings
BRIC Performance Coatings Market
Coatings
North America Polyimide Coating Market
Coatings
Solvent Borne Coatings Market