
 Europe Bifacial Solar Market | 2026-2036
Europe Bifacial Solar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bifacial Solar Market Insights
Module-plus-storage bundling is hardening as the dominant procurement configuration across European utility-scale tenders. LONGi Solar leverages its integrated wafer-to-module footprint to anchor pricing power in bundled contracts. Meyer Burger specializes in heterojunction cell architecture to differentiate against imported Asian supply.
Europe Bifacial Solar refers to photovoltaic modules that capture irradiance on both front and rear surfaces, typically achieving bifaciality coefficients of 70-90% through transparent backsheet or dual-glass construction with passivated emitter and rear contact (PERC) or tunnel oxide passivated contact (TOPCon) architectures; these modules serve commercial and utility operators seeking higher energy yield per installed watt. The monocrystalline segment dominates unit shipments due to superior conversion efficiency in European latitudes, while heterojunction technology leads margin pools as manufacturers command premiums for temperature coefficient advantages. Ground-mounted installations occupy the largest addressable volume, though floating solar competes for growth in markets with land-use constraints.
The EU Green Deal, CE marking under the EU AI Act's energy provisions, and the F-Gas Regulation collectively shape module certification requirements and carbon footprint disclosure thresholds for market access. ECHA REACH compliance on photovoltaic materials further constrains backsheet chemistry and encapsulant formulation choices. Stakeholders must monitor how the EU's Carbon Border Adjustment Mechanism reshapes cost structures for imported versus European-manufactured modules.
Market Dynamics
The EU Carbon Border Adjustment Mechanism is restructuring import economics for crystalline silicon modules, forcing procurement officers to recalculate landed cost models against domestic European manufacturing alternatives.
Growth Catalysts
- REPowerEU framework:The European Commission's target of 600 GW solar capacity by 2030 mandates accelerated utility-scale deployment, with member states streamlining permitting for ground-mounted bifacial arrays.
- Floating solar expansion:Reservoir-based installations in Spain and Portugal exploit water surface availability where land constraints block conventional ground-mount projects.
- Module-plus-storage bundling:Utility procurement tenders increasingly specify DC-coupled battery integration, raising effective project capacity factors and improving grid connection queue positioning.
Market Restraints
- Polysilicon supply concentration:Over 80% of metallurgical-grade silicon refining capacity sits in Xinjiang, exposing European module assemblers to forced labor documentation requirements under the EU's Corporate Sustainability Due Diligence Directive.
- Silver paste cost volatility:Metallization paste accounts for 10-15% of cell manufacturing cost, with silver price spikes compressing margins for PERC and TOPCon producers.
- Aluminum frame tariff exposure:Extruded aluminum sourcing from Chinese smelters faces anti-dumping duties, raising balance-of-system costs for dual-glass module configurations.
Strategic Opportunities
- Eastern European manufacturing:Poland and Romania offer lower labor costs and proximity to German distribution hubs, attracting module assembly investments that qualify for EU Innovation Fund support.
- Agricultural PV convergence:Agrivoltaic installations in France and Italy combine crop cultivation with elevated bifacial arrays, accessing rural development subsidies while resolving land-use conflicts.
- Green hydrogen offtake:Electrolyzer projects in the Netherlands and Denmark are signing 10-15 year power purchase agreements with solar developers, providing bankable revenue streams for merchant solar capacity.
Industry Challenges
- TOPCon process engineering scarcity:Tunnel oxide passivated contact cell fabrication requires specialized vacuum deposition expertise that European PV workforce development programs have not yet scaled.
- CE marking timeline compression:Module certification under the Construction Products Regulation now requires extended fire safety testing, extending time-to-market for new product introductions by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bifacial Solar Market |
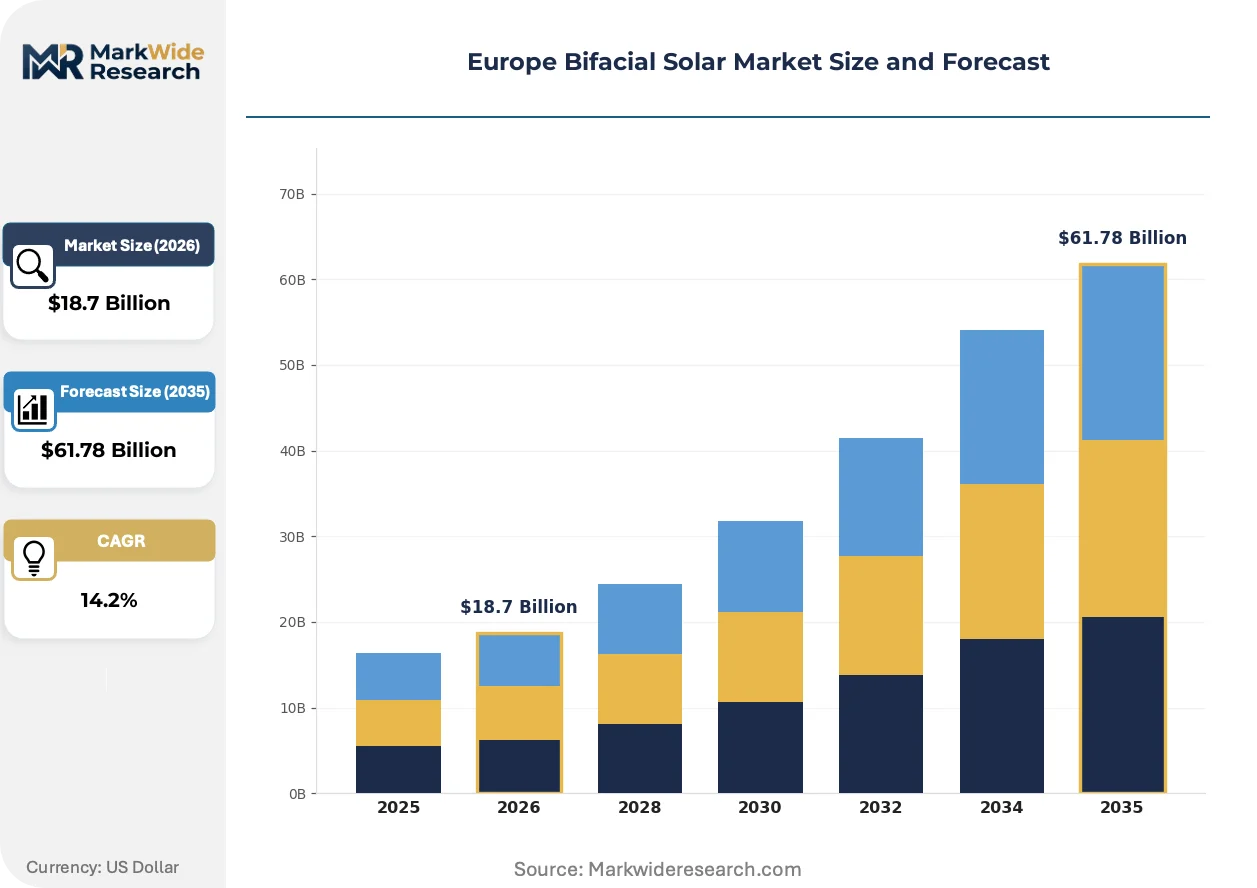
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Heterojunction End User: Residential, Commercial, Industrial, Utilities Installation Type: Ground-Mounted, Roof-Mounted, Floating, BIPV Technology: Standard Bifacial, Transparent, High-Efficiency, Others |
| Companies Covered | JinkoSolar, LONGi Solar, Trina Solar, JA Solar, Canadian Solar, Risen Energy, Meyer Burger, REC Group, Hanwha Q CELLS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bifacial Solar Market Trends and Innovations
Cell metallization and encapsulant chemistry are undergoing parallel reinvention as manufacturers chase higher bifaciality coefficients and longer field degradation warranties. These technical trajectories are compressing the performance gap between imported and European-produced modules.
Copper plating is decentralizing front-side metallization away from screen-printed silver pastes. Meyer Burger and European research institutes are piloting light-induced plating processes that cut silver consumption by 80%. Utility-scale developers in Germany are qualifying these cells for 30-year performance guarantees. The technology is decentralizing supply chain risk from precious metal commodity markets toward electroplating equipment vendors.
REACH compliance on per- and polyfluoroalkyl substances is tightening backsheet material specifications. ECHA's restriction proposal on PFAS chemicals threatens fluoropolymer-based backsheets that dominate bifacial module construction. Manufacturers are accelerating glass-glass laminate adoption or switching to polyolefin encapsulants. Spanish and Italian module assemblers face the steepest reformulation costs given their reliance on imported fluorinated films.
Merchant solar developers are unbundling engineering-procurement-construction contracts into separate component supply and installation agreements. This fragmentation allows utilities to direct-source modules while outsourcing construction to regional installers. German municipal utilities pioneered this split-contract model to retain procurement control over module efficiency specifications. The practice is spreading to Spanish independent power producers seeking to optimize project finance structures.
Europe Bifacial Solar Market Segmentation
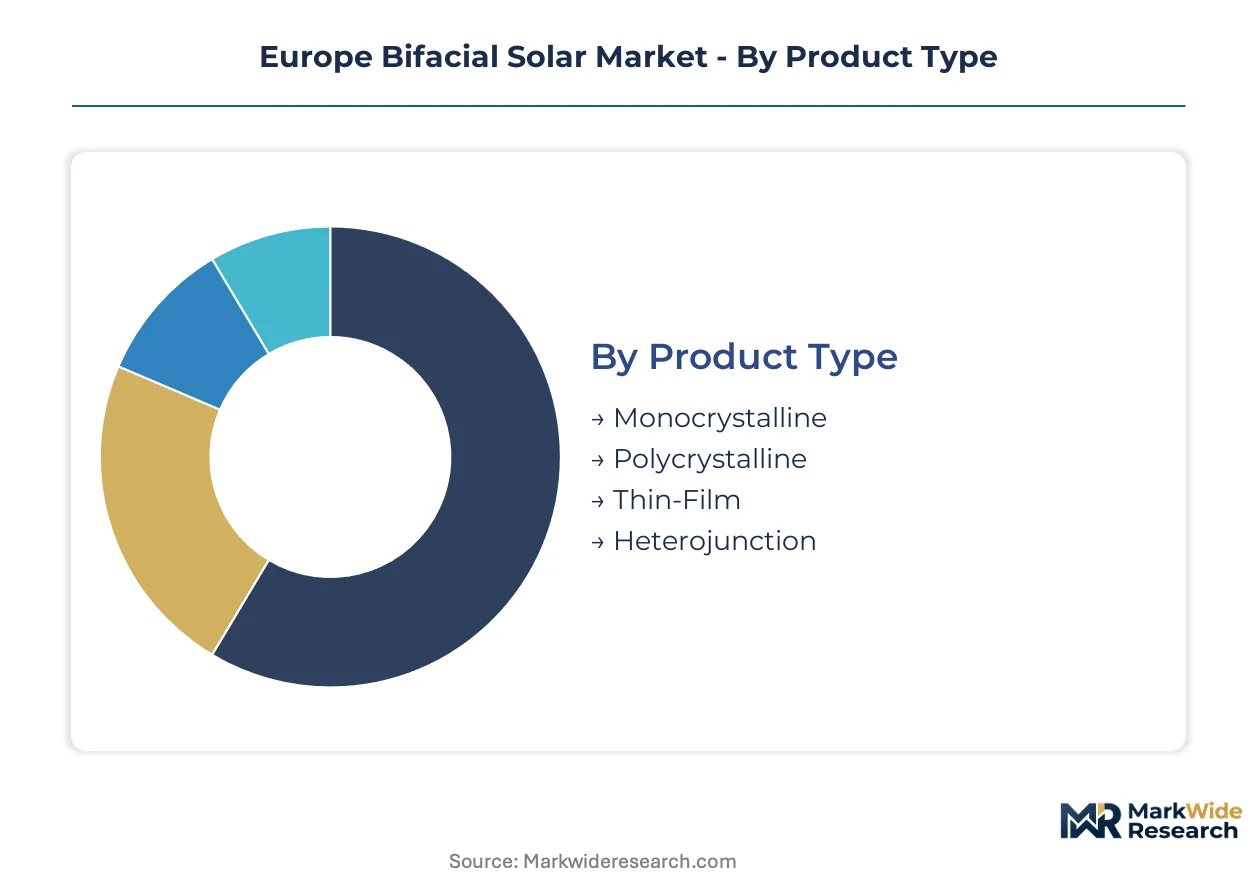
Segmentation in the Europe Bifacial Solar Market reveals how technology choices, installation constraints, and buyer economics fragment procurement patterns. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning across member states.
Product Type:
Conversion efficiency thresholds drive buyer selection, with module performance at European latitudes determining lifetime energy yield calculations.
- Monocrystalline:PERC and TOPCon cell architectures dominate utility-scale tenders due to 21-23% front-side efficiency ratings. German and Spanish developers specify monocrystalline modules for ground-mounted parks where land availability constrains total installed capacity.
- Heterojunction:Amorphous-crystalline silicon junctions deliver superior temperature coefficients and lower degradation rates. Meyer Burger's German manufacturing base supplies heterojunction cells to premium residential and commercial segments seeking 30-year performance guarantees.
- Polycrystalline:Multi-crystalline wafers retain cost advantage in price-sensitive Eastern European distributed generation projects.
- Thin-Film:Cadmium telluride and CIGS technologies occupy niche building-integrated applications where weight and flexibility outweigh efficiency metrics.
Volume sits with monocrystalline; growth tilts toward heterojunction as efficiency premiums justify manufacturing cost differentials.
End User:
Procurement scale and offtake contract structures create divergent technical specifications across customer categories.
- Utilities:Transmission-connected solar parks above 50 MW capacity specify bifacial modules with 85% bifaciality coefficients to maximize energy density. REPowerEU auction mechanisms in Italy and Portugal prioritize utility-scale deployment with streamlined permitting.
- Commercial:C&I rooftops and carport installations in France and the Netherlands favor mid-size arrays with DC-coupled storage integration. Corporate power purchase agreements provide bankable revenue streams for merchant commercial capacity.
- Industrial:Manufacturing facilities with high baseload demand self-consume solar generation to hedge against volatile wholesale electricity prices.
- Residential:Rooftop systems below 10 kW capacity concentrate in Germany's solar-heavy southern states and Italy's net-metering regions.
Installed base concentrates in utilities; commercial applications are expanding most quickly behind corporate sustainability commitments.
Installation Type:
Site constraints and land-use regulations determine mounting system selection and module construction requirements.
- Ground-Mounted:Single-axis trackers and fixed-tilt racking dominate Spanish Extremadura and Italian Puglia solar parks. Dual-glass module construction withstands mechanical loading from tracker movement and environmental exposure.
- Floating:Reservoir-based installations in Portugal's Alqueva dam and Spanish hydroelectric lakes exploit water surface availability where agricultural land protection blocks ground-mount development.
- Roof-Mounted:Commercial and industrial flat roofs in Germany's Rhine-Ruhr industrial corridor utilize lightweight framing to avoid structural reinforcement costs.
- BIPV:Building-integrated photovoltaics in French commercial construction replace conventional facade materials with photovoltaic-active surfaces.
Ground-mounted arrays command the largest addressable volume; floating solar gains share fastest where land-use conflicts intensify.
Technology:
Rear-side light harvesting architectures differentiate module performance and warranty positioning.
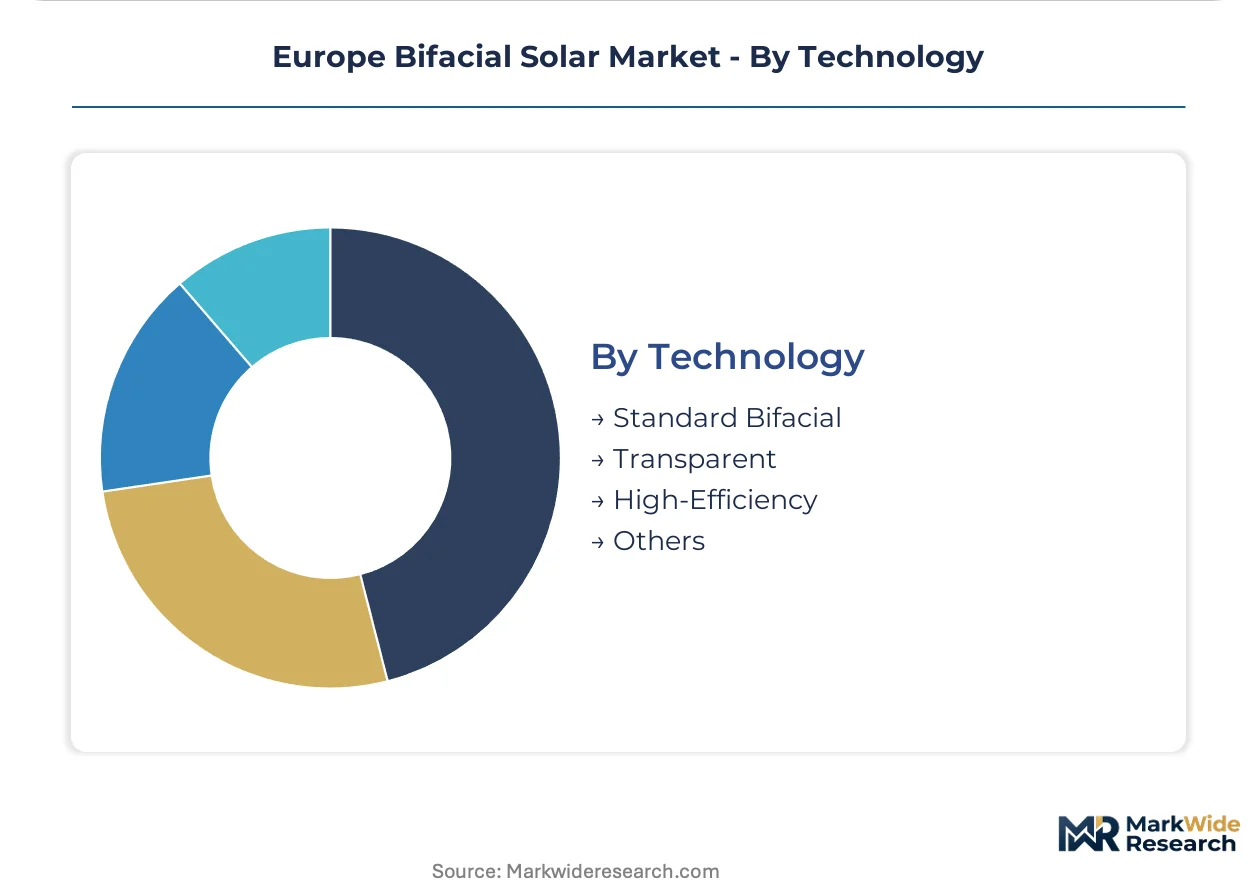
- Standard Bifacial:PERC+ and TOPCon cells with transparent backsheets achieve 70-80% bifaciality coefficients. These modules satisfy CE marking requirements under the Construction Products Regulation for mass-market deployment.
- High-Efficiency:Advanced passivation schemes and selective emitter designs push front-side efficiency above 24%. German and Dutch developers specify high-efficiency variants for space-constrained urban installations.
- Transparent:Semi-transparent glass-glass laminates serve agrivoltaic applications in France and Italy where crop photosynthesis requires partial light transmission.
- Others:Experimental architectures including back-contact and interdigitated back contact cells remain confined to pilot demonstration projects.
Standard bifacial technology anchors current deployment; high-efficiency variants show the steepest expansion trajectory as module costs decline and space constraints tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Module assembly capacity clusters in Eastern Europe while demand concentrates in Western European solar parks. This geographic split shapes logistics costs and carbon footprint calculations under the EU Carbon Border Adjustment Mechanism. Procurement officers now weight transport emissions against manufacturing origin in supplier selection.
Germany
Utility-scale tenders in Brandenburg and Saxony-Anhalt specify bifacial modules with 85% bifaciality coefficients for single-axis tracker installations. The German Renewable Energy Sources Act (EEG) guarantees feed-in tariffs for ground-mounted arrays above 20 MW capacity. Meyer Burger's Thalheim production facility supplies heterojunction cells to domestic developers seeking 30-year performance warranties.
Spain
Extremadura and Andalusia host the continent's largest pipeline of bifacial solar parks, with reservoir-based floating installations expanding at Portuguese border reservoirs. The National Integrated Energy and Climate Plan mandates 39 GW of solar capacity by 2030. Spanish developers source dual-glass modules through split-contract procurement models that separate component supply from EPC installation.
Italy
Agrivoltaic installations in Puglia and Sicily combine elevated bifacial arrays with olive and citrus cultivation, accessing rural development subsidies under the Recovery and Resilience Facility. The REPowerEU auction mechanism streamlines permitting for projects above 10 MW. Italian module assemblers face reformulation costs as ECHA REACH restrictions tighten on fluorinated backsheet materials.
Netherlands
Green hydrogen electrolyzer projects in Rotterdam and Eemshaven are signing 10-15 year power purchase agreements with solar developers, creating bankable offtake for merchant capacity. The Stimulation Scheme for Sustainable Energy Production subsidizes bifacial deployment on industrial rooftops. Dutch commercial installers favor DC-coupled battery integration to optimize grid connection queue positioning.
Poland
Lower Silesia and Greater Poland voivodeships attract module assembly investments from German distributors seeking lower labor costs and EU Innovation Fund qualification. The Polish National Energy and Climate Plan targets 20 GW of solar capacity by 2040. Domestic developers specify polycrystalline modules for price-sensitive distributed generation projects in agricultural regions.
Europe Bifacial Solar Market Competitive Landscape
The competitive structure tilts toward integrated Asian manufacturers with captive wafer capacity and European specialists in heterojunction architecture. Tier-one Chinese producers anchor pricing in utility-scale tenders through scale advantages in polysilicon refining. European fabricators defend position through technology differentiation and carbon footprint transparency. Strategic moves concentrate on backward integration into metallization materials and selective partnerships with floating solar EPC contractors.
Within the integrated manufacturing tier, LONGi Solar and Trina Solar exemplify scale-driven archetypes with upstream control over crystalline silicon supply chains. Meyer Burger occupies a specialist position representing European heterojunction cell architecture capabilities. These three anchors illustrate the bifurcation between volume-leveraged Asian supply and premium-positioned European technology differentiation.
| Leading Market Players |
|---|
| JinkoSolar |
| LONGi Solar |
| Trina Solar |
| JA Solar |
| Canadian Solar |
| Risen Energy |
| Meyer Burger |
| REC Group |
| Hanwha Q CELLS |
| Others |
Pricing and Supply Chain Analysis
Silver price volatility on the London Bullion Market Association benchmark cascades through European module assembly, stratifying procurement costs across premium heterojunction, standard PERC, and economy polycrystalline tiers.
Pricing Analysis
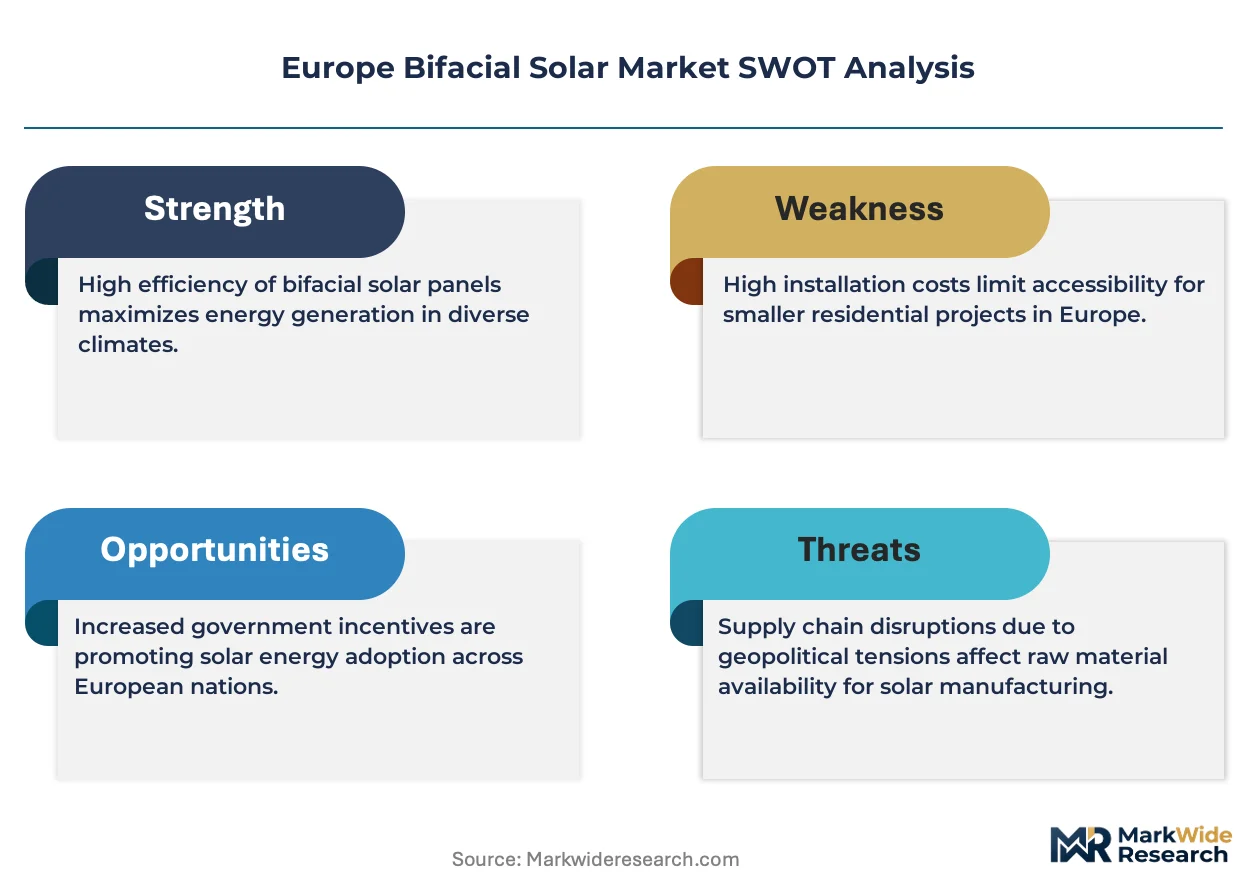
Margin tightening in standard PERC modules reflects silver paste cost spikes and aluminum frame tariff exposure from Chinese smelters. Three-tier pricing structure across premium, standard, and economy levels separates Meyer Burger's heterojunction warranties from mass-market PERC supply and Eastern European polycrystalline projects. CE marking under the Construction Products Regulation and extended fire safety testing create certification-driven price premiums. Commercial rooftop developers in the Netherlands exhibit highest price sensitivity, while German municipal utilities absorbing feed-in tariff structures show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Xinjiang-origin polysilicon refining, where over 80% of metallurgical-grade capacity concentrates. European module assemblers draw from Chinese wafer slicing, Southeast Asian cell fabrication, and domestic glass-glass lamination. Forced labor documentation requirements under the EU Corporate Sustainability Due Diligence Directive constitute the dominant supply chain risk. Distribution runs through German distribution hubs serving Western European utility-scale tenders and Polish assembly plants supplying Eastern European distributed generation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Carbon Border Adjustment Mechanism erects a cost-of-compliance moat that rewards domestic European manufacturers with transparent carbon footprint documentation against import competition.
For Market Incumbents: Anchor pricing power through backward integration into metallization materials, securing copper plating equipment partnerships to offset silver paste volatility. Expand Thalheim or comparable European manufacturing footprints to qualify for EU Innovation Fund support before CBAM phase-in accelerates. Defend against LONGi Solar's scale advantages by emphasizing carbon footprint transparency in utility tenders. For New Entrants and Emerging Players: Begin with agrivoltaic installations in France and Italy, where rural development subsidies and land-use conflict resolution create structural white space. Target floating solar EPC partnerships in Portugal and Spain, where reservoir availability outpaces established ground-mount competition. Pursue split-contract procurement models that separate module supply from installation, allowing direct utility relationships without full EPC capability. For Investors and Strategic Acquirers: The window for entry favors heterojunction cell technology specialists with proven 30-year warranty track records and European manufacturing footprints. Long-term viability hinges on REACH-compliant encapsulant chemistry reformulation capabilities ahead of PFAS restrictions. Watch for CBAM implementation enforcement as the signal to differentiate domestic from import-exposed portfolio exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallization Materials | Copper plating adoption cuts silver dependency by 80%, insulating margins from LBMA price spikes. |
| CE Marking Fire Safety Certification Acceleration | Compressed 4-6 month testing timelines reward early-submitting manufacturers with first-mover tender positioning. |
| Agrivoltaic Project Development Partnerships | French and Italian rural subsidies unlock land-constrained capacity with dual-revenue crop-plus-energy streams. |
| Green Hydrogen PPA Structuring | Rotterdam and Eemshaven electrolyzer offtake creates bankable 10-15 year revenue visibility for merchant solar. |
| PFAS-Free Encapsulant Reformulation | ECHA REACH compliance ahead of fluoropolymer bans protects Spanish and Italian assemblers from supply disruption. |
Research Methodology
Independent corroboration across utility planning officers, EPC contractors, module procurement leads, and grid operators underwrites the qualitative findings. Primary interviews with IPP project developers and floating solar specialists combined with secondary validation from EIA project databases, IEA renewable deployment reports, FERC interconnection queues, and EU auction mechanism disclosures. Bottom-up capacity installation tracking and top-down policy target reconciliation triangulate market sizing.
Rate-of-change decomposition across technology substitution curves, regulatory phase-in schedules, and supply chain cost trajectories structures the analytical framework. Segmentation dimensions span cell architecture, installation type, end-user category, and national regulatory framework across the projection horizon. CAGRs derive from modeled deployment pipelines against REPowerEU capacity targets, incorporating silver price scenarios and CBAM carbon cost assumptions.
Polysilicon supply disruption, ECHA REACH restriction acceleration, and CBAM enforcement timing are the dominant revision risks. Forecasts reflect documented assumptions on policy continuity and commodity price bands. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Switzerland Solar Energy Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Europe Solar Concentrator Market
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
Japan Solar Energy Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
Asia-Pacific Solar Tracker Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Rooftop Solar EPC Market
Solar Power Systems
Global Photovoltaic Market
Solar Power Systems
Austria Solar Energy Market
Solar Power Systems
Poland Solar Energy Market