
 Solar Panel Laminator Market | 2026-2036
Solar Panel Laminator Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Panel Laminator Market Insights
Ethylene-vinyl acetate (EVA) is pivoting toward polyolefin elastomer (POE) and co-extruded encapsulants in next-generation laminators, reshaping thermal profile requirements and chamber compatibility across equipment lines. Robert Bürkle GmbH leverages its European installed base to sustain aftermarket service revenue. Ecoprogetti anchors niche demand in pilot and R&D lines with compact vacuum platforms. Qinhuangdao Boostsolar Photovoltaic Equipment Co., Ltd. dominates cost-engineered throughput systems for tier-one Chinese module makers.
A solar panel laminator is a thermal-vacuum processing machine that bonds photovoltaic cells, encapsulant films, and glass substrates through controlled heating, vacuum degassing, and pressurized lamination cycles typically operating at 140-160°C. Its primary purpose is to eliminate voids and moisture while creating durable, weather-resistant module assemblies. Vacuum laminators occupy the highest margin tier due to precision requirements in bifacial and heterojunction cell architectures, while fully automatic technology lines capture expanding share as labor costs rise and throughput targets tighten. Roll to roll laminators serve emerging perovskite and flexible substrate research, though manual systems persist in aftermarket repair and small-batch contract manufacturing.
The EU Green Deal and F-Gas Regulation constrain fluorinated gas use in lamination processes, pushing equipment redesign toward infrared heating and closed-loop thermal systems. China's GB standards and MIIT efficiency mandates enforce domestic content ratios that favor local laminator procurement. India's PLI scheme for solar module manufacturing is stimulating import substitution for capital equipment. Stakeholders must monitor encapsulant material transitions and regional content rules to align capacity investments with shifting compliance boundaries.
Market Dynamics
The transition from EVA to POE and co-extruded encapsulants is forcing laminator manufacturers to redesign thermal chambers and vacuum profiles, creating equipment obsolescence risk for installed base owners while opening replacement cycles for advanced systems.
Growth Catalysts
- China's MIIT efficiency mandates:Domestic content requirements under GB standards accelerate procurement of locally manufactured high-throughput vacuum laminators by vertically integrated cell-to-module factories.
- Utility-scale solar farm developers:Intensifying module output targets drive automated laminator adoption to achieve cycle times below 22 minutes per batch.
- India's PLI scheme:Production-linked incentives for solar module manufacturing stimulate capital equipment import substitution and greenfield laminator installations.
Market Restraints
- Silicone and POE encapsulant cost volatility:Petrochemical feedstock price swings compress laminator OEM margins and destabilize customer project financing.
- Supply concentration in Chinese vacuum pump and heating element suppliers:Geographic single-sourcing creates lead time vulnerability and tariff exposure for European and North American equipment assemblers.
- EU F-Gas Regulation thermal limitations:Restrictions on fluorinated gas use in lamination processes constrain conventional heating system designs and extend R&D validation timelines.
Strategic Opportunities
- Perovskite tandem cell commercialization:Roll-to-roll laminator architectures for flexible substrates address emerging pilot line demand from next-generation photovoltaic research consortia.
- US Inflation Reduction Act domestic manufacturing credits:Section 45X advanced manufacturing production credits incentivize reshoring of laminator assembly and component fabrication.
- Aftermarket service unbundling:Predictive maintenance contracts and vacuum pump refurbishment programs capture recurring revenue from Europe's aging installed base.
Industry Challenges
- Thermal process engineering talent scarcity:Specialized expertise in multi-zone infrared heating control and vacuum degassing dynamics commands premium compensation and constrains OEM expansion.
- CE marking and UL certification timeline compression:Accelerated product development cycles for next-generation encapsulant compatibility create regulatory submission bottlenecks.
- Legacy PLC system integration:Retrofitting Industry 4.0 connectivity into 2015-2019 vintage laminators requires proprietary gateway development and extends commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Panel Laminator Market |
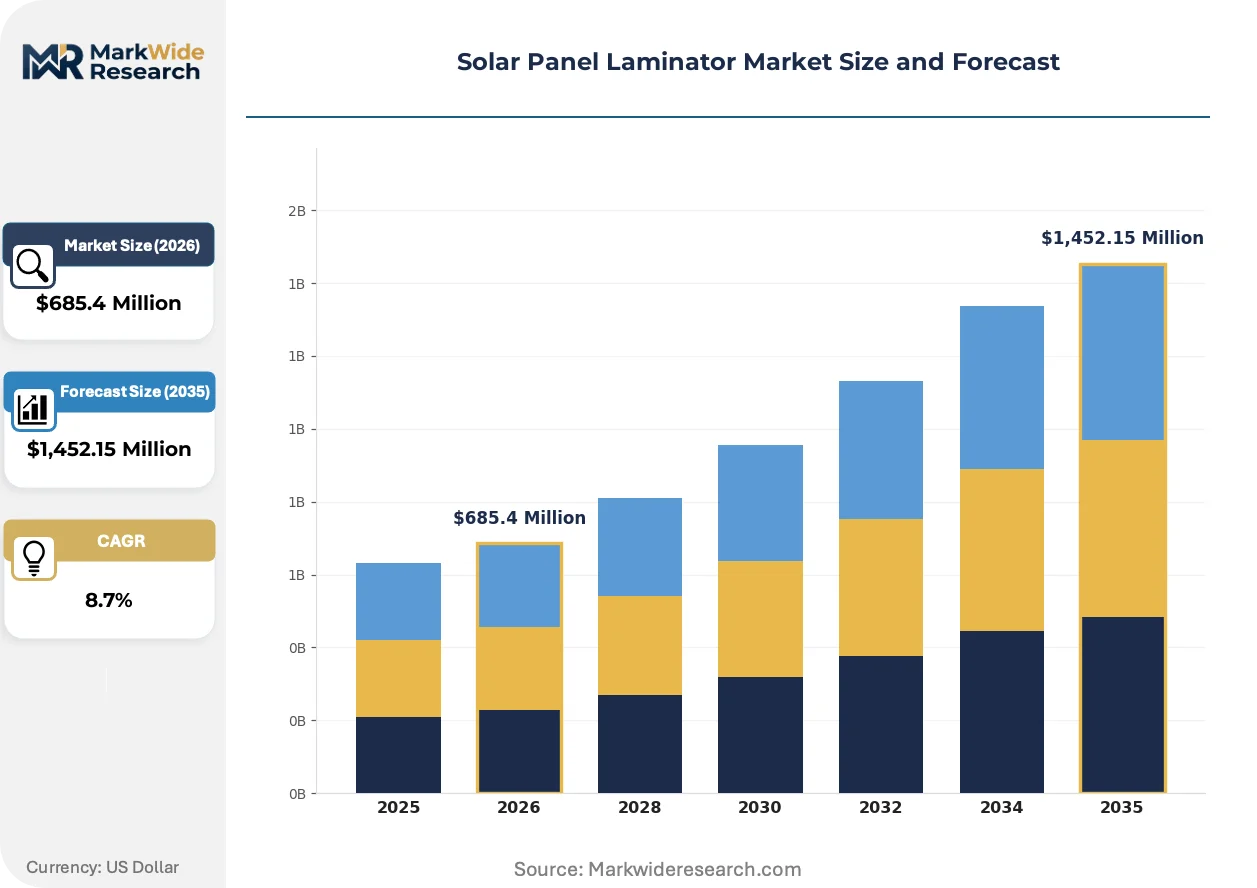
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Laminators, Roll to Roll Laminators, Manual Laminators, Automatic Laminators Technology: Semi-Automatic, Fully Automatic, Hybrid, Infrared Heating End User: Manufacturers, Research Institutions, Installers, Contractors Distribution Channel: Direct Sales, Online Retail, Distributors, Dealers |
| Companies Covered | Robert Bürkle GmbH, Ecoprogetti, Qinhuangdao Boostsolar Photovoltaic Equipment Co., Ltd., Ooitech, NPC Incorporated, Mondragon Assembly, Hebei Yiheng Solar Energy Science & Technology Co., Ltd., Shanghai Senco Technology Co., Ltd., Meier Solar Solutions GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Panel Laminator Market Trends and Innovations
Encapsulant chemistry evolution and heating technology substitution are compressing equipment replacement cycles while regional manufacturing incentives redistribute laminator demand geography.
Infrared heating systems are absorbing the thermal processing load previously handled by conventional conduction plates in next-generation laminator designs. Bifacial and heterojunction cell manufacturers in China and South Korea are specifying infrared-equipped vacuum chambers to achieve tighter temperature uniformity across 2.6-meter glass substrates. This technology transition is absorbing margin from conventional heating element suppliers while enabling faster ramp rates that compress total lamination cycle time.
The EU F-Gas Regulation is prohibiting virgin hydrofluorocarbon use in industrial thermal processes above specified threshold dates. Equipment manufacturers serving European module factories are engineering closed-loop thermal oil and electric infrared alternatives to maintain compliance without performance degradation. Vacuum laminator lines destined for Germany, Italy, and Spain now require redesigned heating subsystems that eliminate fluorinated gas dependency entirely.
Module makers are consolidating supplier relationships around full-line integration partners rather than discrete equipment vendors. Tier-one Chinese manufacturers now procure laminators as part of turnkey cell-to-module automation packages, displacing standalone equipment purchasing. This behavioral shift concentrates specification influence with systems integrators and compresses direct OEM channel access in the world's largest laminator demand market.
Solar Panel Laminator Market Segmentation
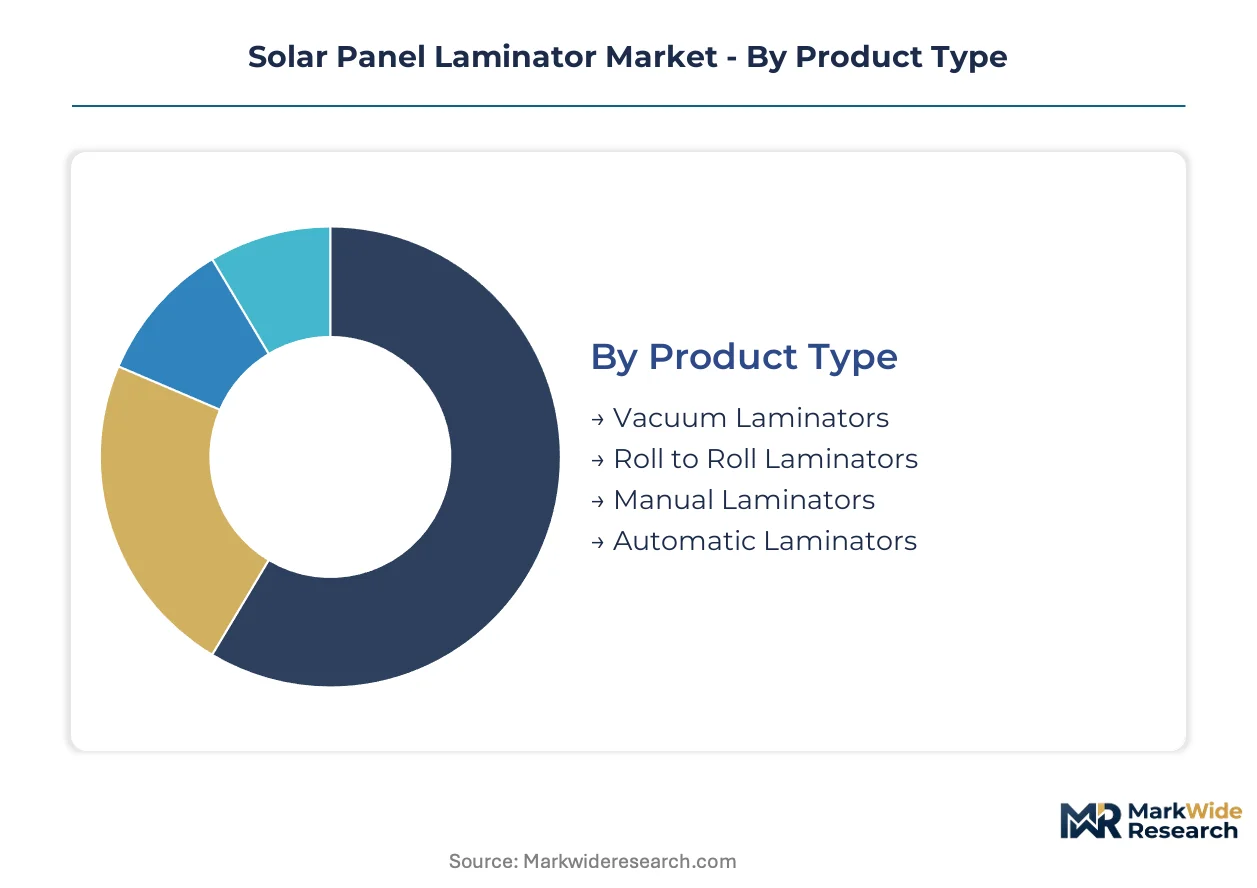
Equipment replacement cycles in solar panel laminators vary dramatically by segment, with encapsulant chemistry shifts and automation upgrades driving divergent refresh timelines across product categories. Understanding these segment-specific dynamics enables suppliers to align R&D investments with where demand is concentrating.
Product Type:
Upgrade urgency differs sharply across laminator architectures, with vacuum systems facing accelerated replacement from encapsulant transitions while manual units endure in niche applications.
- Vacuum Laminators:These thermal-vacuum systems bond cells, encapsulants, and glass through controlled heating at 140-160°C with precision degassing. Demand concentrates in China where vertically integrated cell-to-module factories require high-throughput systems for bifacial and heterojunction architectures. MIIT efficiency mandates under GB standards accelerate procurement of locally manufactured units.
- Automatic Laminators:Fully automated lines integrate loading, lamination, and unloading with cycle times below 22 minutes. Utility-scale solar farm developers in India and the US drive adoption as labor costs rise and throughput targets tighten under PLI schemes and IRA manufacturing credits.
- Roll to Roll Laminators:Continuous-feed systems serve emerging perovskite tandem cell research with flexible substrate compatibility.
- Manual Laminators:Hand-operated units persist in aftermarket repair operations and small-batch contract manufacturing where capital constraints limit automation.
Vacuum Laminators sit at the top of the volume ranking, with Automatic Laminators climbing the fastest.
Technology:
Heating system substitution is redistributing margin across technology tiers as infrared systems displace conventional thermal plates.
- Infrared Heating:Multi-zone infrared systems achieve tighter temperature uniformity across 2.6-meter glass substrates with faster ramp rates. South Korean and Chinese bifacial cell manufacturers specify these chambers to compress total lamination cycle time while absorbing margin from conventional heating element suppliers.
- Fully Automatic:End-to-end automation with PLC-controlled process management eliminates operator intervention. European module factories under EU F-Gas Regulation constraints adopt these systems to integrate closed-loop thermal oil alternatives without performance degradation.
- Semi-Automatic:Partial automation retains manual loading with automated lamination cycles.
- Hybrid:Combines conduction and infrared heating for transitional encapsulant compatibility.
Fully Automatic systems command the highest average selling prices, with Infrared Heating gaining share fastest in new installations.
End User:
Customer type determines specification complexity and service contract value, with manufacturers consolidating around full-line integration partners.
- Manufacturers:Tier-one module makers procure laminators as turnkey cell-to-module automation packages rather than standalone equipment. China's vertically integrated factories drive volume orders for high-throughput vacuum systems, displacing discrete equipment purchasing and concentrating specification influence with systems integrators.
- Research Institutions:Pilot line operators require compact vacuum platforms with flexible thermal profiles for next-generation cell architecture development. European and North American photovoltaic research consortia specify roll-to-roll configurations for perovskite tandem cell commercialization.
- Installers:Field service operations require portable or compact units for module repair and refurbishment.
- Contractors:Project-based procurement for greenfield manufacturing facilities favors leased or financed equipment.
Manufacturers absorb the dominant share of laminator shipments, with Research Institutions expanding fastest as pilot line investments accelerate.
Distribution Channel:
Channel economics reflect equipment complexity and regional manufacturing incentives, with direct relationships deepening where customization requirements intensify.
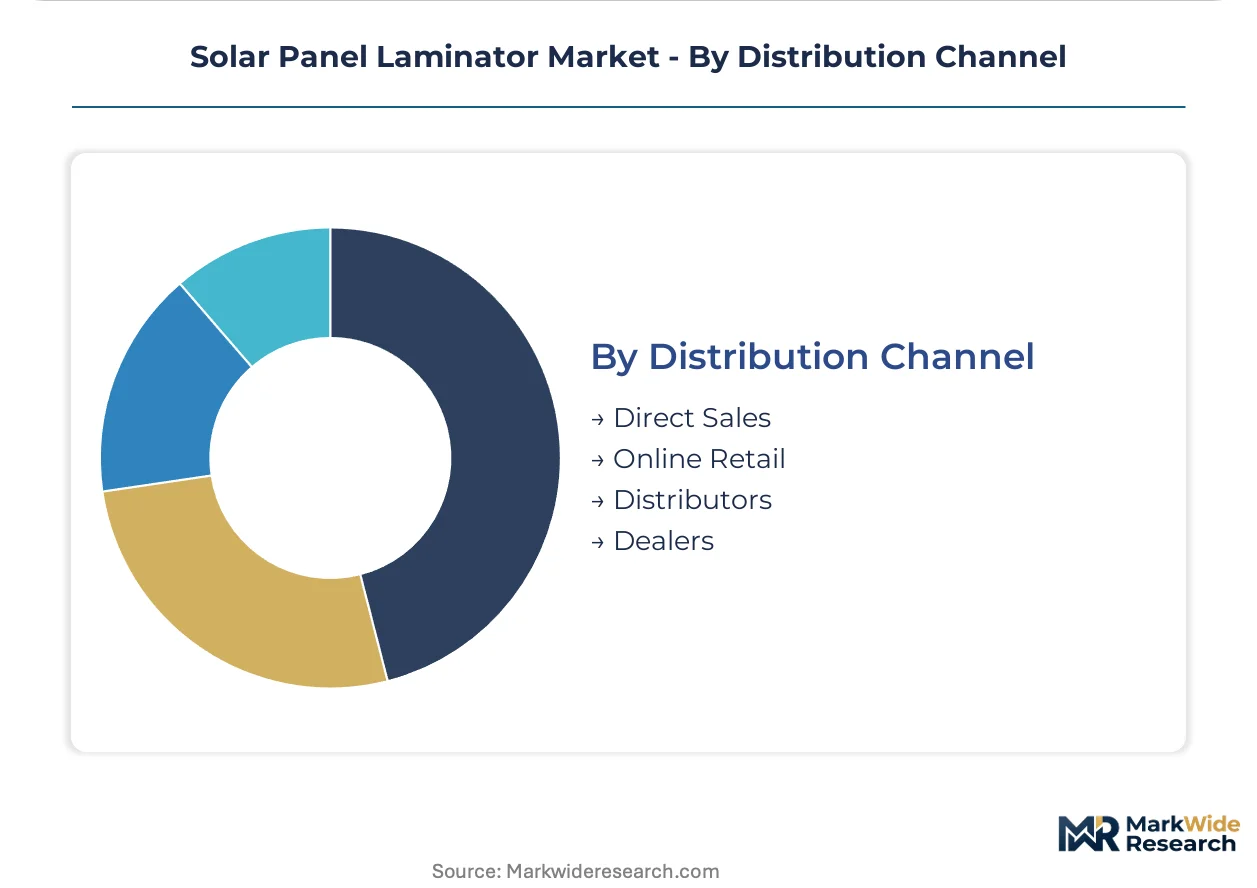
- Direct Sales:OEM field engineers configure thermal chambers and vacuum profiles for encapsulant-specific requirements. European producers like Robert Bürkle GmbH leverage direct relationships to sustain aftermarket service revenue from aging installed bases.
- Distributors:Regional inventory holders reduce lead times for standardized equipment in markets with tariff exposure. North American and Southeast Asian assemblers rely on distributors to buffer supply concentration in Chinese vacuum pump and heating element suppliers.
- Dealers:Local representation provides installation and commissioning support in fragmented markets.
- Online Retail:Digital channels serve spare parts and consumable procurement for legacy system maintenance.
Direct Sales captures the majority of new equipment value, with Distributors expanding coverage fastest in tariff-affected geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta module fabrication clusters absorb the dominant share of laminator procurement as vertically integrated cell-to-module factories expand capacity. Regional manufacturing incentives and encapsulant chemistry transitions are redistributing equipment demand across major production geographies.
China
Vertically integrated photovoltaic manufacturers in Jiangsu and Zhejiang provinces drive volume orders for high-throughput vacuum systems. MIIT efficiency mandates under GB standards enforce domestic content ratios that favor local laminator procurement. Hefei and Suzhou industrial parks concentrate pilot line investments for next-generation heterojunction cell architectures.
United States
Domestic module assembly reshoring accelerates capital equipment procurement across Southeast and Southwest manufacturing corridors. Section 45X advanced manufacturing production credits under the Inflation Reduction Act incentivize laminator assembly and component fabrication. Arizona and Texas solar industrial parks attract turnkey automation package investments from tier-one producers.
Germany
European module factories under EU F-Gas Regulation constraints adopt closed-loop thermal oil and electric infrared heating alternatives. The EU Green Deal's domestic manufacturing mandates redirect equipment sourcing toward European producers. Saxony and Bavaria host precision laminator engineering centers serving regional encapsulant compatibility requirements.
India
Production-linked incentives for solar module manufacturing stimulate capital equipment import substitution and greenfield laminator installations. BIS certification requirements and CEA grid connectivity standards shape equipment specification timelines. Gujarat and Tamil Nadu solar parks concentrate first-wave domestic laminator deployments under PLI scheme allocations.
South Korea
Bifacial cell manufacturers specify infrared-equipped vacuum chambers to achieve tighter temperature uniformity across large-format glass substrates. METI-aligned efficiency benchmarks and KOSHA industrial safety standards govern thermal system approvals. Gwangju and Incheon metropolitan areas concentrate R&D consortia pilot lines for tandem cell lamination processes.
Solar Panel Laminator Market Competitive Landscape
Capacity expansion dominates the current landscape as laminator manufacturers scale output to match module factory construction timelines. The vendor base stratifies across three tiers: European precision engineering houses, Chinese throughput specialists, and Korean automation integrators. Technology licensing agreements and strategic partnerships represent the dominant competitive moves as encapsulant chemistry transitions force collaborative R&D on thermal chamber redesign.
Within the European engineering tier, Robert Bürkle GmbH and Meier Solar Solutions GmbH exemplify precision-focused archetypes serving regional compliance requirements. Ecoprogetti occupies a position among compact vacuum platform specialists addressing pilot line demand. Qinhuangdao Boostsolar Photovoltaic Equipment Co., Ltd. represents the Chinese throughput-driven segment. These named entities anchor distinct strategic positions without exhausting the competitive field.
| Leading Market Players |
|---|
| Robert Bürkle GmbH |
| Ecoprogetti |
| Qinhuangdao Boostsolar Photovoltaic Equipment Co., Ltd. |
| Ooitech |
| NPC Incorporated |
| Mondragon Assembly |
| Hebei Yiheng Solar Energy Science & Technology Co., Ltd. |
| Shanghai Senco Technology Co., Ltd. |
| Meier Solar Solutions GmbH |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by prohibiting conventional fluorinated gas heating systems in European module factories, forcing laminator OEMs to absorb R&D costs for infrared and closed-loop thermal oil alternatives while tier-one buyers in China and India extract volume discounts from throughput-focused suppliers.
Pricing Analysis
Petrochemical feedstock volatility in silicone and POE encapsulants passes through to laminator OEM margins and end-user financing structures. Three-tier pricing structure across premium infrared-equipped vacuum chambers, standard conduction-heating automatic lines, and economy manual units differentiates by certification grade and after-sales bundling. Cost compression in standard-tier equipment is intensifying because Chinese vertically integrated factories consolidate procurement around turnkey automation packages. Small-batch contract manufacturers and research institutions exhibit highest price sensitivity, while utility-scale developers under PLI and IRA mandates prioritize throughput specifications over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from tier-one Chinese module makers, while regional distributors buffer lead time vulnerability for European and North American assemblers. Vacuum pump and heating element manufacturing concentrates in China, Germany, and South Korea. Laminator assembly draws from specialized steel framing, precision vacuum seals, and PLC control systems. Single-source vulnerability in Chinese vacuum pump suppliers creates tariff exposure and extended lead times for non-domestic equipment fabricators. Distribution runs through OEM field engineering for customized thermal chamber configuration and aftermarket service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar panel laminator market functions as a regulatory compounder where the EU Green Deal's domestic manufacturing mandates and F-Gas thermal restrictions continuously reshape equipment specifications and qualified supplier pools.
For Market Incumbents: Anchor aftermarket service revenue through predictive maintenance contracts and vacuum pump refurbishment programs targeting Europe's aging installed base. Accelerate infrared heating platform certification to preempt obsolescence risk from encapsulant chemistry transitions. Deepen backward integration into vacuum chamber fabrication to defend margin position against Chinese throughput specialists consolidating around turnkey automation packages. For New Entrants and Emerging Players: Perovskite tandem cell roll-to-roll architectures offer a technology-first wedge into pilot line demand from North American and European research consortia. Target India's PLI scheme greenfield deployments where import substitution policies create procurement preference for locally assembled equipment. Pursue equipment-as-a-service financing models to lower capital barriers for mid-tier module makers in Southeast Asia. For Investors and Strategic Acquirers: Roll-up economics work for European precision engineering houses because regional compliance requirements and F-Gas retrofit cycles fragment addressable demand across multiple specialized OEMs. Five-to-ten year viability hinges on thermal process engineering talent retention and encapsulant transition agility. Monitor MIIT efficiency mandate enforcement intensity as inflection indicator for Chinese domestic content ratio shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Infrared Heating Platform Development | EU F-Gas Regulation compliance enables continued market access for European OEMs. |
| Turnkey Automation Packaging | Tier-one Chinese manufacturers consolidate procurement around full-line integration partners. |
| Predictive Maintenance Service Contracts | Recurring revenue capture from Europe's aging vacuum laminator installed base accelerates. |
| Perovskite Roll-to-Roll Pilot Line Deployment | Research consortium demand for flexible substrate compatibility opens white-space segment. |
| India PLI Scheme Localization | Domestic assembly qualification under BIS and CEA standards redirects procurement geography. |
Research Methodology
Bottom-up module manufacturer procurement modeling reconciled against top-down laminator OEM shipment tracking forms the analytical core of this study. Primary interviews with plant engineers at vertically integrated cell-to-module factories, aftermarket service directors at European precision engineering houses, procurement leads at Indian PLI scheme beneficiaries, and thermal process R&D heads at research consortia were validated against secondary sources including MIIT GB standard filings, EU ECHA F-Gas regulatory updates, US Treasury IRA Section 45X guidance, and customs trade data on vacuum pump and heating element imports.
Historical laminator deployment trendlines across utility-scale solar farm construction, module factory capacity expansion, and pilot line research investment establish baseline growth patterns. Segmentation modeling spans equipment architecture, heating technology, automation level, end-user type, and regional manufacturing incentive framework. CAGRs were derived from equipment replacement cycle compression analysis and encapsulant chemistry transition timelines. Forecast inputs incorporate MIIT efficiency mandate enforcement trajectories and IRA domestic manufacturing credit allocation intensity.
The model holds under sustained module output requirement intensification and regional content rule enforcement; deviation in petrochemical feedstock cost trajectories or vacuum pump supply disruption would shift equipment procurement timing and geographic distribution. Forecasts reflect documented assumptions regarding encapsulant transition velocity and regulatory compliance timeline adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
United Kingdom Photovoltaic Mounting System Market
Solar Power Systems
Solar Panel Cleaning System Market
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
Concentrated Photovoltaic System Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
Chile Renewable Energy Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
US Solar Films Market
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market