
 Global EV Solar Modules Market | 2026-2036
Global EV Solar Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Global EV Solar Modules Market Analysis
Chinese photovoltaic manufacturers are expanding wafer and cell capacity dedicated to automotive-grade modules. Jinko Solar leverages vertical integration from polysilicon to module assembly for EV-specific form factors. Trina Solar anchors its position through high-efficiency PERC and bifacial architectures suited to curved vehicle surfaces. JA Solar competes on cost-optimized monocrystalline platforms that balance weight constraints with power density requirements.
EV solar modules are photovoltaic assemblies engineered for direct integration onto vehicle surfaces, typically employing lightweight substrates, flexible encapsulants, and efficiencies ranging from 18% to 24% to offset traction battery drain. These units serve primarily to extend driving range, power auxiliary systems, and reduce grid dependency for parked vehicles. Bifacial modules capture the fastest growth trajectory as automakers exploit reflected ground irradiance for incremental energy yield. PERC technology dominates current manufacturing scale due to its mature supply chain and proven automotive reliability, while thin-film approaches occupy niche applications requiring extreme curvature or weight minimization.
The EU Green Deal and Ecodesign framework shape product standards by mandating lifecycle carbon accounting and minimum efficiency thresholds for automotive-integrated photovoltaics. China's MIIT enforces GB standards for vehicle-mounted solar safety and electromagnetic compatibility, while the US NHTSA and EPA coordinate on range-testing protocols that credit auxiliary solar charging. Stakeholders must monitor how evolving certification requirements across Germany, China, and the United States interact with module design choices and factory qualification timelines.
Market Dynamics
Automotive OEMs now mandate photovoltaic integration at the platform-design stage rather than treating solar as an aftermarket accessory, compressing supplier qualification timelines and favoring cell-to-module partners with proven vehicle-surface form factor capabilities.
Growth Catalysts
- EU Green Deal efficiency mandates:The Ecodesign framework now requires lifecycle carbon accounting for automotive-integrated photovoltaics, forcing OEMs to source certified low-carbon modules and creating captive demand for compliant suppliers.
- Extended-range auxiliary power:Cabin preconditioning and battery thermal management systems draw substantial standby power; integrated solar offsets this drain and preserves traction battery capacity for propulsion.
- Germany's manufacturing scale-up:Domestic EV production capacity expansion concentrates module procurement decisions with Munich and Stuttgart engineering centers, pulling supply chain investment toward automotive-grade certification.
Market Restraints
- High-purity silicon cost volatility:Polysilicon spot price swings transmit directly to module bill-of-materials, constraining OEM willingness to commit to multi-year supply agreements at fixed pricing.
- Wafer supply concentration:Over 80 percent of semiconductor-grade silicon slicing capacity sits in China, creating single-source vulnerability for automotive qualification programs requiring traceable provenance.
- Curvature-induced cell fracture:Silicon wafer brittleness limits minimum bend radius on vehicle rooflines and hoods, forcing design compromises between aerodynamic styling and active cell area.
Strategic Opportunities
- United States IRA domestic content credits:The Inflation Reduction Act's manufacturing tax incentives reward North American module assembly, creating first-mover advantage for localized production investments.
- Vehicle-to-grid bidirectional charging:Solar-augmented EVs can arbitrage daytime generation against peak grid pricing, opening revenue streams beyond simple range extension.
- Thin-film perovskite tandem architectures:Laboratory demonstrations of flexible, ultra-lightweight cells promise integration onto curved glass and polymer body panels currently inaccessible to crystalline silicon.
Industry Challenges
- Automotive EMC certification timelines:Electromagnetic compatibility testing under China's GB standards and the EU's E-mark framework adds 12-18 months to product launch schedules, compressing window for technology refresh cycles.
- Photovoltaic-vehicle thermal co-design:Module operating temperatures degrade cell efficiency while vehicle HVAC loads compete for the same roof real estate, requiring systems engineering capabilities rare in either industry.
- End-of-life recycling infrastructure:Encapsulant and backsheet materials complicate silicon recovery; no scaled automotive-PV recycling pathway exists, creating liability exposure under extended producer responsibility frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global EV Solar Modules Market |
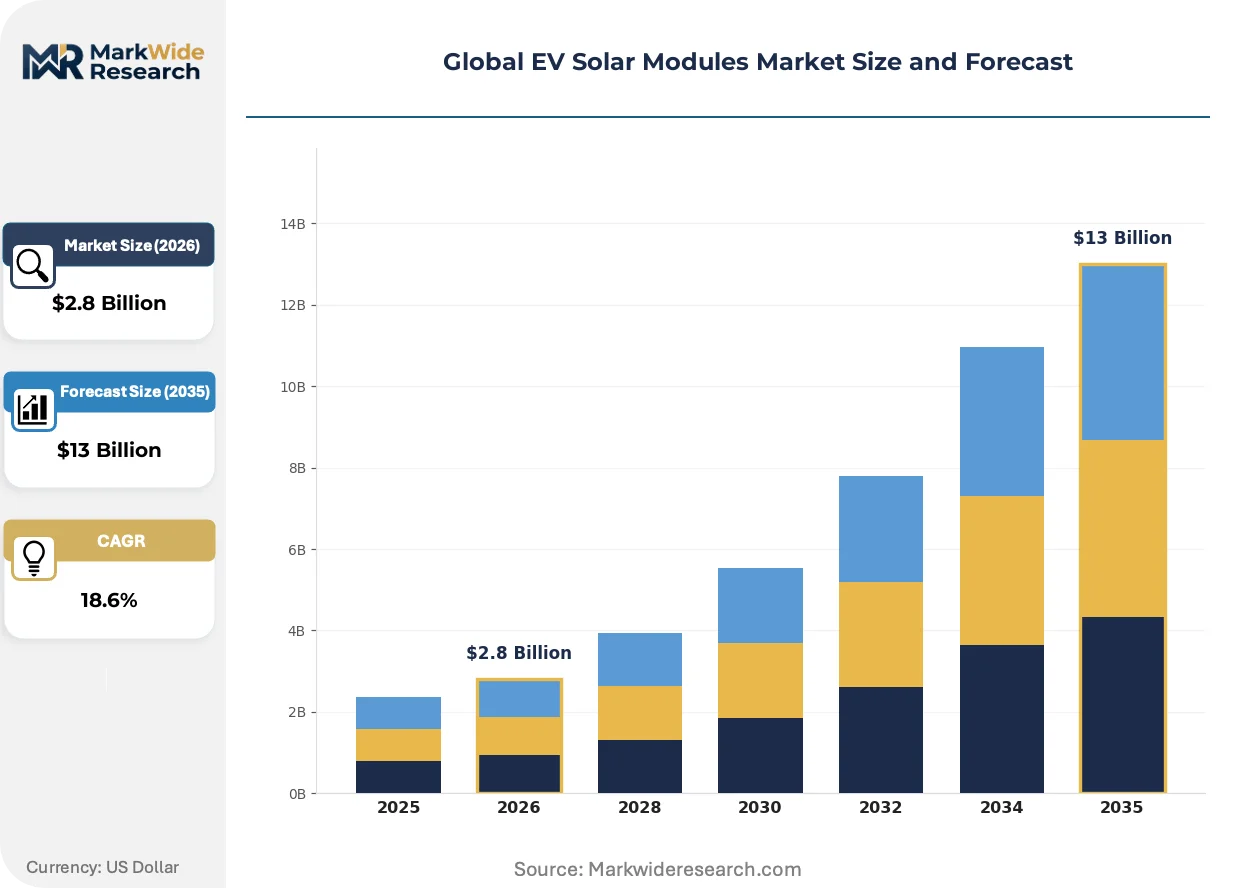
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Modules, Monocrystalline, Polycrystalline, Bifacial Modules Technology: Thin-Film, PERC, HET, Bifacial Technology Installation: Roof-Mounted, Ground-Mounted, Integrated PV, Standalone End User: OEMs, Fleet Operators, Individual Consumers, Commercial Enterprises |
| Companies Covered | Jinko Solar, Trina Solar, JA Solar, LONGi Solar, Canadian Solar, Maxeon Solar Technologies, Capsolar, Innolia, SunPower, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global EV Solar Modules Market Emerging Trajectories
Module architecture is pivoting from commodity glass-backsheet constructions toward application-specific laminates where weight, curvature tolerance, and vehicle crash safety dominate design trade-offs. This shift reconfigures supplier relationships and qualification protocols.
PERC cell technology is consolidating its position as the baseline for automotive-integrated photovoltaics. Cell efficiencies between 20 and 22 percent meet OEM range-extension targets at manufacturing scale. Tier 1 suppliers in China and Southeast Asia have retooled capacity toward bifacial PERC configurations that harvest ground-reflected irradiance. This technology is consolidating supply chain leverage with vertically integrated manufacturers possessing in-house cell and module capabilities.
The EU Ecodesign framework is tightening embodied carbon thresholds for automotive-integrated modules. Manufacturers must now document polysilicon origin, ingot energy intensity, and logistics emissions through third-party verification. German and French OEM procurement teams have inserted these requirements into supplier scorecards. Module vendors without low-carbon metallurgical-grade silicon partnerships face exclusion from platform supply agreements.
Fleet operators are unbundling solar performance guarantees from vehicle purchase contracts, demanding separate metering and verification of auxiliary system energy yield. Leasing companies and corporate sustainability officers now require irradiance-corrected kilowatt-hour reporting. This procurement evolution is most visible in California and Germany, where commercial EV deployment concentrates and ESG disclosure mandates drive granular energy accounting.
Global EV Solar Modules Market Segmentation
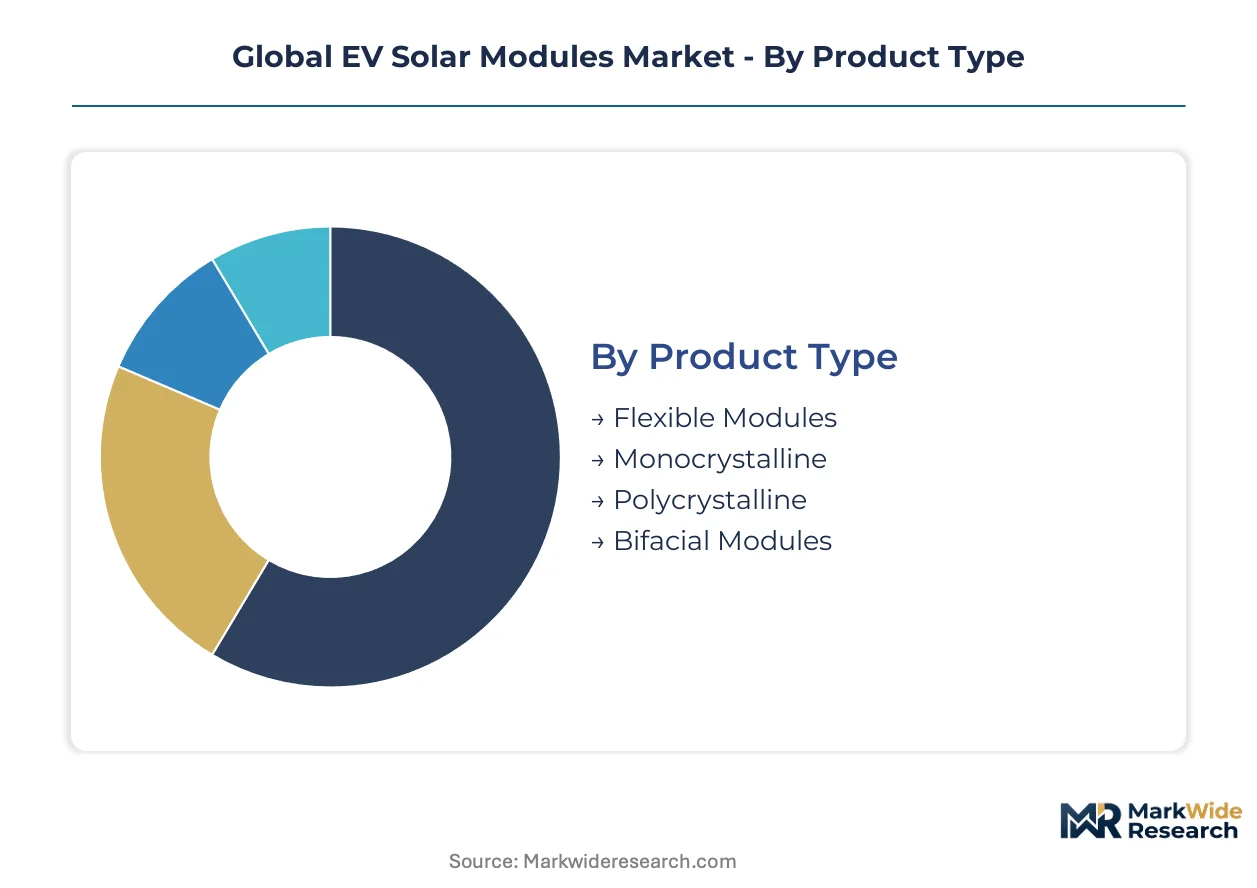
Segmentation in the EV solar modules market determines supplier qualification pathways and manufacturing investment priorities. Technology choices lock in form factor constraints that cascade through vehicle platform design cycles. Procurement teams segment by performance tier and integration depth to match module specifications against range-extension targets and aerodynamic requirements.
Product Type:
Upgrade cycles in automotive photovoltaic integration favor modules that accommodate curved body panels without sacrificing active cell area. OEM platform decisions commit suppliers to multi-year production runs.
- Bifacial Modules:Dual-sided cell architectures capture direct irradiance plus ground-reflected light, delivering 5-15% energy yield uplift on light-colored road surfaces. Demand concentrates in Germany and the United States where fleet operators prioritize range metrics in procurement scorecards; the Ecodesign framework's efficiency mandates accelerate adoption.
- Flexible Modules:Polymer substrate constructions achieve bend radii under 100mm for integration onto hoods and fenders where crystalline silicon fractures. Chinese manufacturers dominate capacity expansion for automotive-grade flexible laminates; weight savings of 40-60% versus glass-backsheet alternatives attract premium EV platforms.
- Monocrystalline:Single-crystal silicon wafers deliver 20-22% conversion efficiency in standard test conditions.
- Polycrystalline:Multi-crystal ingot approaches trade efficiency for cost position in auxiliary-power applications.
Volume placements concentrate in Monocrystalline; the faster expansion belongs to Bifacial Modules.
Technology:
Cost tier differentiation separates premium cell architectures from commodity platforms. Tier 1 suppliers concentrate capacity in high-efficiency processes while second-tier vendors serve price-sensitive auxiliary applications.
- PERC:Passivated emitter and rear contact cells dominate automotive manufacturing scale with proven reliability under thermal cycling and mechanical load. Germany's engineering centers specify PERC baselines for platform-integrated solar; mature supply chains from polysilicon to module assembly compress qualification timelines.
- Bifacial Technology:Dual-glass or transparent backsheet constructions enable rear-side photon collection without cell redesign. Ground-mounted vehicle charging installations in California and Arizona exploit high-albedo desert surfaces; the IRA's domestic content credits pull assembly investment toward North American bifacial capacity.
- Thin-Film:Cadmium telluride and CIGS depositions on flexible substrates enable extreme curvature.
- HET:Heterojunction architectures combine crystalline silicon with amorphous silicon layers for temperature coefficient advantages.
Procurement volume clusters in PERC; HET is climbing the fastest as OEMs prioritize thermal performance in sun-belt deployments.
Installation:
Application context determines structural loading, encapsulant specifications, and electrical architecture. Roof-integrated systems face pedestrian impact standards absent in ground-mounted fleet charging arrays.
- Integrated PV:Module-in-roof assemblies replace conventional glass and metal panels, eliminating aerodynamic drag from surface-mounted hardware. Stuttgart and Munich engineering centers mandate integrated photovoltaic platforms for next-generation EV architectures; crash safety certification under ECE R43 drives laminate design choices.
- Roof-Mounted:Rack-based installations on commercial vans and buses preserve existing body-in-white structures while adding 200-400W auxiliary capacity. Last-mile delivery fleets in Germany and the United States specify roof-mounted solar for cabin preconditioning; operator fuel savings calculations justify retrofit investments.
- Ground-Mounted:Stationary solar canopies shade parking while delivering charging infrastructure.
- Standalone:Portable module systems for off-grid vehicle charging in remote applications.
Platform engineering investment flows toward Integrated PV; Roof-Mounted retains the largest installed base in commercial vehicle segments.
End User:
Customer type dictates pricing architecture and performance verification requirements. Fleet procurement demands irradiance-corrected energy accounting; individual consumers prioritize warranty terms and aesthetic integration.
- OEMs:Vehicle manufacturers specify module performance at the platform-design stage, locking suppliers into 7-10 year supply agreements with stringent automotive quality protocols. China's MIIT enforces GB/T standards for electromagnetic compatibility and fire safety; European OEMs layer Ecodesign carbon accounting requirements atop baseline specifications.
- Fleet Operators:Logistics companies and corporate mobility managers unbundle solar performance guarantees from vehicle leases, demanding separate metering of auxiliary system yield. California and Germany host the most advanced fleet procurement practices; ESG disclosure mandates drive granular kilowatt-hour reporting.
- Individual Consumers:Retail purchasers respond to range-extension marketing claims and warranty coverage.
- Commercial Enterprises:Corporate vehicle pools balance capital constraints against sustainability targets.
Contract value aggregates with OEMs; Fleet Operators are gaining share fastest as electrified commercial vehicle deployment scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polysilicon refineries in Xinjiang and Inner Mongolia supply feedstock for automotive-grade wafers across three continents. This geographic concentration shapes procurement strategies for EV-integrated photovoltaics.
China
MIIT enforces GB/T standards for vehicle-mounted solar electromagnetic compatibility and fire safety. The Yangtze River Delta hosts module assembly clusters serving domestic EV platforms from BYD and NIO. Capacity expansion targets automotive-specific form factors with lightweight encapsulants.
Germany
Stuttgart and Munich engineering centers mandate integrated photovoltaic platforms for next-generation EV architectures. The EU Ecodesign framework imposes lifecycle carbon accounting on module procurement. Bavaria-based suppliers qualify under ECE R43 crash safety protocols for roof-integrated systems.
United States
The Inflation Reduction Act's domestic content credits pull assembly investment toward North American bifacial capacity. NHTSA coordinates range-testing protocols that credit auxiliary solar charging. Arizona and California fleet operators exploit high-albedo desert surfaces for ground-reflected energy yield.
Japan
METI drives automotive-photovoltaic thermal co-design standards for cabin preconditioning applications. Kansai and Nagoya manufacturing bases supply precision encapsulants for curved vehicle surfaces. Toyota and Honda platform teams specify JIS-compliant modules for hybrid auxiliary power.
South Korea
The Seoul Capital Area concentrates cell-to-module partnerships for Hyundai-Kia platform integration. MFDS-equivalent automotive safety protocols govern electromagnetic emissions testing. Busan-Ulsan port logistics support export-oriented production of lightweight laminates for European OEMs.
Global EV Solar Modules Market Vendor Landscape
Global majors compete with regional champions across certification capabilities and platform-design integration timelines. The supplier base organizes into three tiers: vertically integrated polysilicon-to-module operators, specialized automotive-grade laminators, and flexible-substrate innovators. Consolidation pressure intensifies as OEMs reduce qualified vendor lists to single-digit counts per platform. Dominant competitive moves include captive supply agreements with EV engineering centers and backward integration into metallurgical-grade silicon refining.
Among China-based vertically integrated operators, Jinko Solar, Trina Solar, and JA Solar exemplify the scale-driven archetype. These entities occupy positions spanning polysilicon production through module assembly, enabling rapid qualification for automotive form factors. Their concentration of wafer slicing and cell fabrication capacity supports the cost structures required for mass-market EV platform adoption.
| Leading Market Players |
|---|
| Jinko Solar |
| Trina Solar |
| JA Solar |
| LONGi Solar |
| Canadian Solar |
| Maxeon Solar Technologies |
| Capsolar |
| Innolia |
| SunPower |
| Others |
Supply Flow & Price Mechanics
Wafer-slicing specialists concentrated in Jiangsu province anchor module assembly economics, with labor-cost differentials between Yangtze River Delta clusters and Southeast Asian expansion sites driving 15-20% pricing-tier spreads across automotive-grade and auxiliary-power product lines.
Pricing Analysis
Warranty and performance-guarantee bundling separates premium automotive-grade modules from unbundled auxiliary-power tiers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with OEM platform contracts commanding 30-40% premiums over aftermarket retrofits. Cost compression in economy-tier flexible modules is intensifying because Chinese manufacturers are expanding polymer-substrate capacity. Fleet operators exhibit highest price sensitivity, while German OEM procurement teams prioritize Ecodesign-compliant low-carbon sourcing over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart and Munich engineering centers, while distributor networks serve aftermarket retrofit segments. Polysilicon refining concentrates in Xinjiang and Inner Mongolia, with cell fabrication anchored in Jiangsu and module assembly spreading to Vietnam and Thailand. Metallurgical-grade silicon and high-purity quartz crucibles constitute critical input dependencies. Single-source vulnerability in semiconductor-grade wafer slicing creates exposure to China's MIIT export licensing protocols. Distribution runs through Tier 1 automotive supplier consortia qualified under ECE R43 and GB/T standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive-grade polysilicon purification capacity represents the binding constraint propping module pricing, with qualified ingot supply trailing OEM platform ramp schedules by 18-24 months across all major production clusters.
For Market Incumbents: Deepen captive supply agreements with low-carbon metallurgical-grade silicon refiners to secure Ecodesign-compliant feedstock before EU carbon border adjustments tighten. Add cell-to-module capacity in Germany or the United States to capture IRA domestic content credits and compress logistics emissions for European OEM procurement teams.
For New Entrants and Emerging Players: Begin with flexible-substrate laminates for commercial van roof-mounted retrofits, where qualification timelines run shorter than integrated platform programs. California and Germany fleet operators present the most penetrable demand pool given ESG disclosure mandates and irradiance-corrected energy accounting requirements. Pursue direct contracting with last-mile delivery operators bypassing OEM qualification gates.
For Investors and Strategic Acquirers: Re-rating potential sits with automotive-qualified laminators possessing ECE R43 certification and OEM platform supply agreements given the EU Green Deal efficiency mandates. Long-term viability hinges on backward integration into polysilicon or forward integration into vehicle thermal co-design capabilities. Monitor GB/T standard revision schedules as an inflection indicator for Chinese export capacity availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive EMC Certification Investment | Accelerates product launch timelines under China's GB standards and EU E-mark frameworks. |
| Low-Carbon Polysilicon Partnership | Secures Ecodesign-compliant feedstock for German and French OEM procurement scorecards. |
| Bifacial Module Capacity Expansion | Captures IRA domestic content credits and serves Arizona fleet operators exploiting high-albedo surfaces. |
| Thin-Film Perovskite R&D Program | Enables integration onto curved polymer body panels inaccessible to crystalline silicon architectures. |
| Vehicle Thermal Co-Design Capability | Addresses module-HVAC competition for roof real estate in Stuttgart platform engineering centers. |
Methodological Framework
Document review covered SEC filings from photovoltaic manufacturers, MIIT GB standard publications, and EU Ecodesign framework implementing measures, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet sustainability officers, and polysilicon refining operations managers. Secondary sources included vehicle production databases, customs trade records for solar cell and module flows, and IEA renewable energy deployment statistics. Bottom-up module shipment estimates triangulated against top-down EV production forecasts and solar penetration assumptions.
Segment-level revenue and volume trajectories across the analysis window reflect technology-type splits, installation-method categories, and end-user archetype penetration rates. CAGRs derive from regression-based curve fitting against historical deployment patterns and policy-driven step changes in the EU, China, and United States. Key inputs include OEM platform announcement timelines, IRA credit phase-out schedules, and Ecodesign threshold tightening trajectories.
Underlying measurement precision varies by segment; integrated PV and bifacial modules carry tighter precision than thin-film niche applications given mature production data availability. Forecasts reflect assumptions regarding polysilicon price stabilization, automotive EMC certification harmonization, and fleet operator ESG disclosure enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Floating Solar System Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Solar Tracker Installation Market
Solar Power Systems
Saudi Arabia Solar Energy Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
South America Solar PV Inverters Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Canada Solar Energy Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
Bifacial Solar Module Market
Solar Power Systems
United Kingdom Distributed Solar Power Generation Market