
 Block Margarine Market | 2026-2036
Block Margarine Market Size, Share, and Industry Trends Forecast 2026-2036
Block Margarine Market Analysis
Premium fat-content specifications is rotating toward center stage as bakeries and food manufacturers reformulate recipes for cleaner labels and consistent lamination performance. Unilever leverages its global brand architecture and R&D scale to sustain formulation leadership across European and Asian markets. Bunge Limited anchors its position through backward integration into oilseed crushing and refined oil supply. Vandemoortele specializes in tailored industrial margarines for artisan and industrial bakeries, competing on technical service depth rather than commodity volume.
Block margarine is a solid, water-in-fat emulsion typically containing vegetable oils, water, salt, and emulsifiers, manufactured through scraped-surface chilling and kneading to achieve plasticity at controlled temperatures for pastry lamination and creaming applications. The product type spectrum shows organic and non-dairy variants gaining fastest traction as food manufacturers respond to plant-based and clean-label mandates, while regular block formats still occupy the largest margin pool in price-sensitive foodservice channels. End user dynamics reveal food manufacturers and bakeries driving volume, with household demand fragmenting toward smaller packaging formats that diverge from the traditional block configuration.
EU REACH and F-Gas Regulation constrain solvent and processing aid choices in European manufacturing, while FDA labeling rules in the United States shape trans-fat disclosure and nutritional claim thresholds for imported and domestic products. EFSA evaluations on refined vegetable oil contaminants further tighten quality benchmarks for suppliers accessing European retail and industrial accounts. Stakeholders must monitor evolving national dietary guidelines and carbon-border adjustments that could restructure sourcing economics for palm and shea oil feedstocks.
Market Dynamics
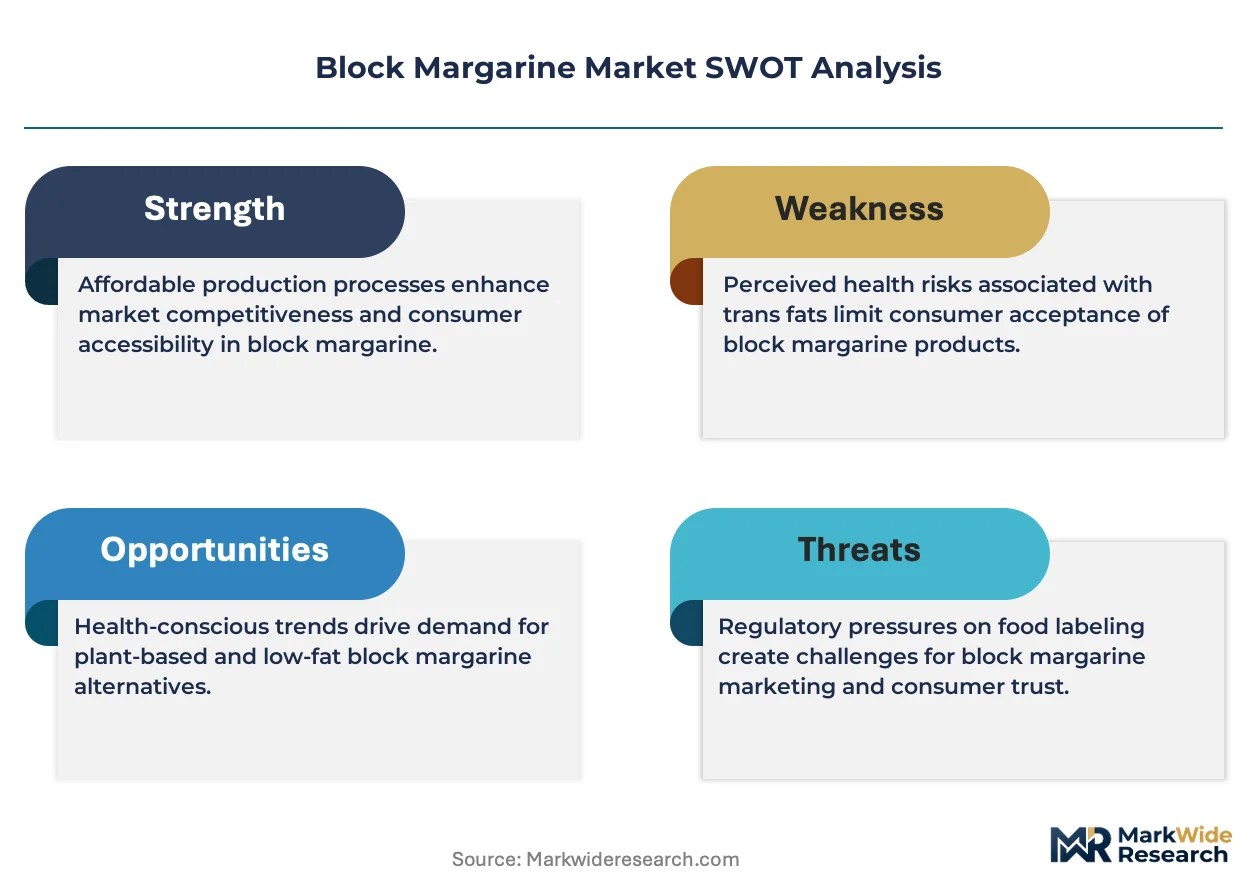
EU F-Gas Regulation and REACH compliance are compressing formulation flexibility for European manufacturers while simultaneously elevating technical barriers for new entrants seeking industrial bakery accounts.
Growth Catalysts
- Industrial Baking Cluster Expansion:Germany's concentrated artisan and commercial bakery infrastructure sustains steady offtake for high-plasticity block formats optimized for laminated dough applications.
- Plant-Based Mandates:Clean-label directives from European retail chains and food manufacturers are accelerating reformulation toward non-dairy block variants with simplified ingredient declarations.
- REACH Compliance Differentiation:Early REACH adaptation creates procurement preference among industrial buyers seeking supply security against future solvent and processing aid restrictions.
Market Restraints
- Palm Oil Price Volatility:Feedstock exposure to Malaysian and Indonesian supply disruptions compresses margin predictability for non-integrated margarine processors.
- Shea Butter Supply Concentration:West African sourcing dependencies create seasonal availability constraints for premium block formulations targeting high-lamination performance specifications.
- Hydrogenation Technology Constraints:Trans-fat reduction mandates limit traditional hardening processes, forcing capital-intensive interesterification or fractionation investments.
Strategic Opportunities
- Carbon Border Adjustment Positioning:EU CBAM implementation creates first-mover advantage for manufacturers with verified low-carbon palm and shea supply chains.
- Artisan Bakery Technical Service:Underserved small-batch bakeries in France and Italy present white space for tailored block formulations with embedded application support.
- Scraped-Surface Chilling Convergence:Integration of precision temperature control with real-time rheology monitoring enables customized plasticity profiles for specialty pastry applications.
Industry Challenges
- Emulsifier Reformulation Expertise Gap:Shortage of lipid chemists capable of optimizing water-in-fat stability under tightened additive restrictions slows product development cycles.
- Interesterification Capacity Bottlenecks:Limited European toll processing availability for enzymatic hardening extends lead times for trans-fat-free block launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Block Margarine Market |
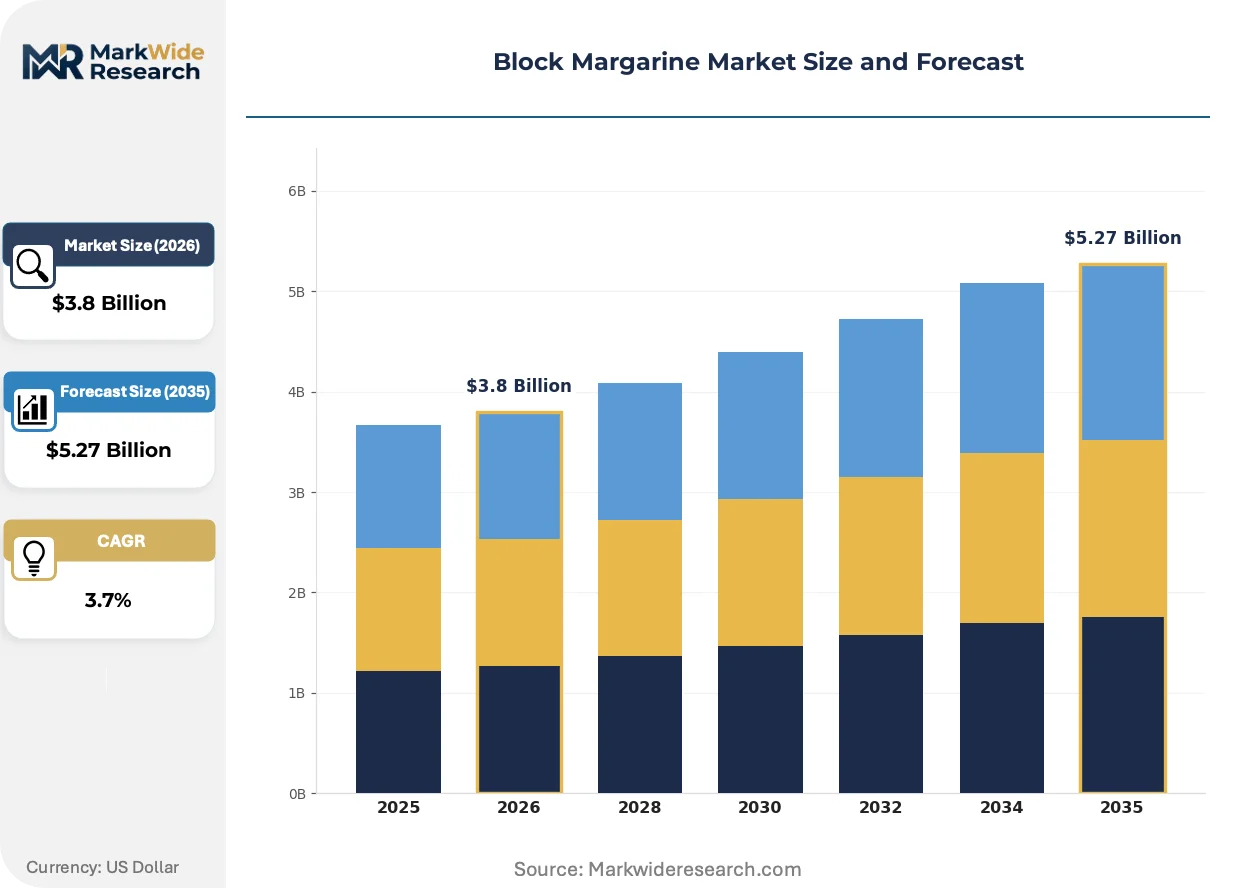
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.27 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Light, Organic, Non-Dairy End User: Households, Foodservice, Bakeries, Food Manufacturers Packaging Type: Plastic Tub, Block, Sachet, Glass Jar Fat Content: Low-Fat, Full-Fat, Reduced-Fat, Zero-Fat |
| Companies Covered | Unilever, Conagra Brands, Inc., Bunge Limited, Wilmar International Ltd., Fuji Oil Holdings Inc., Vandemoortele, Upfield, Yildiz Holding, Arla Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Block Margarine Market Emerging Trajectories
Formulation science and process control technologies are converging to redefine performance benchmarks for laminated pastry applications while regulatory pressure accelerates ingredient transparency.
Enzymatic interesterification is supplanting partial hydrogenation as the dominant structuring technology for high-melting-point block margarines. Industrial bakeries in Northern Europe are adopting these enzymatically modified fats at pace to eliminate trans-fat declarations while maintaining lamination integrity. This technology shift is compressing the addressable market for traditional hydrogenation equipment suppliers and redirecting capex toward biocatalyst production facilities.
EFSA's evolving evaluations on 3-MCPD and glycidyl ester contaminants in refined vegetable oils are tightening quality specifications for suppliers accessing European retail and industrial accounts. Margarine processors must now implement enhanced deodorization protocols or source specialty refined oils to meet downstream customer thresholds. Premium block formulations for artisan channels face the steepest compliance burden as traceability requirements extend to crushing origin documentation.
Bakery procurement departments are consolidating supplier relationships around full-service technical partnerships rather than commodity spot purchasing. Large industrial bakeries in Germany and the Netherlands are disintermediating traditional distributors to secure direct formulation support and joint development agreements. This behavioral shift is most pronounced among export-oriented frozen dough manufacturers requiring consistent fat performance across variable climatic conditions.
Block Margarine Market Segmentation
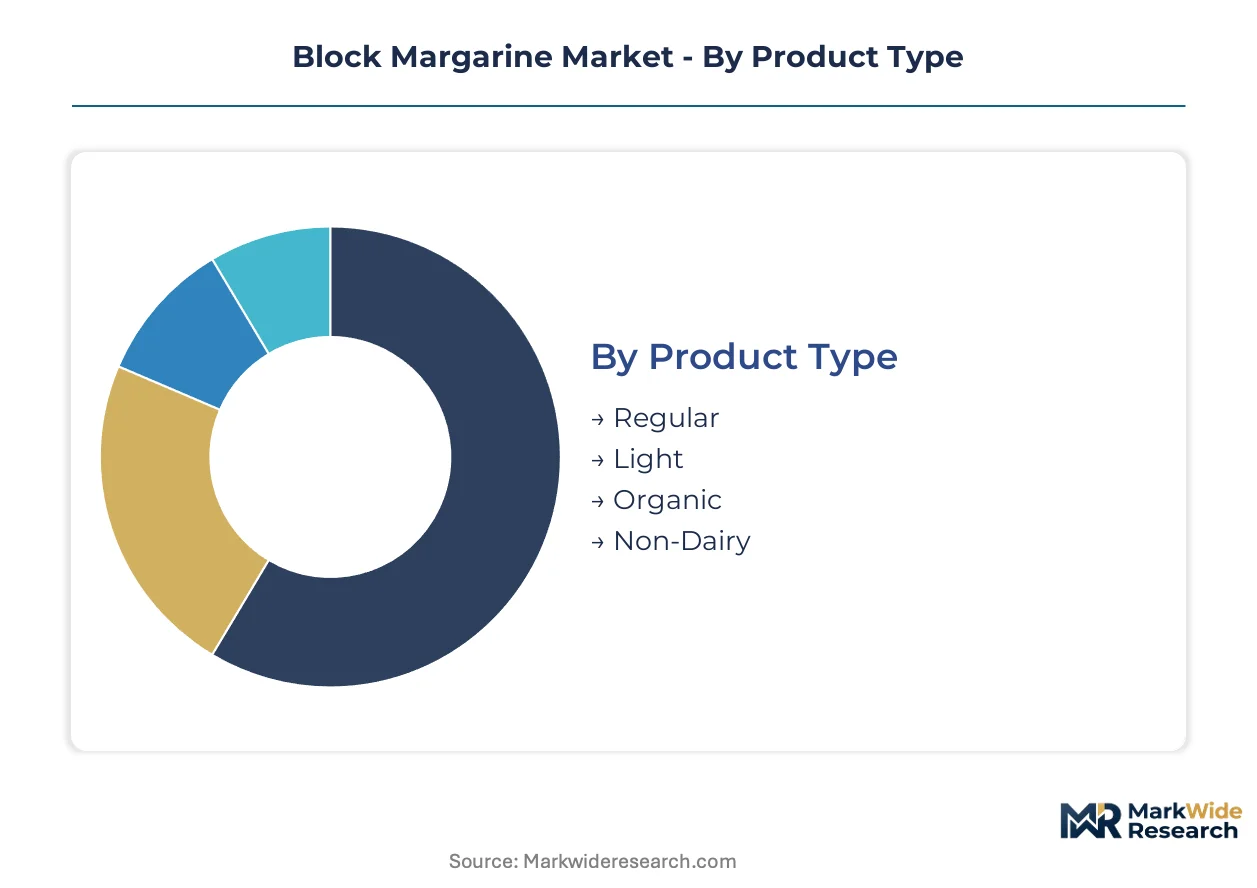
Segmentation in the block margarine market reveals distinct substitution pressures across product architectures, with plant-based alternatives and clean-label formats disrupting traditional fat-content hierarchies. Understanding these fault lines enables suppliers to calibrate formulation investments against reformulation costs and end-user switching economics.
Product Type:
Substitution pressure intensifies as dairy-free spreads and plant-based butters erode volume in conventional segments, forcing incumbents to defend shelf space through rapid clean-label repositioning.
- Regular:Standard vegetable oil-based formulations with 80% fat content dominate price-sensitive foodservice procurement in Germany and industrial baking clusters. Margins compress when palm oil feedstock costs spike, yet volume concentration in frozen dough manufacturing sustains offtake.
- Organic:Certified organic variants command procurement preference among artisan bakeries in France and premium retail channels seeking non-GMO supply chains. EFSA contaminant thresholds and origin documentation requirements elevate compliance costs, restricting supplier participation.
- Light:Reduced-fat emulsions with adjusted water-in-fat ratios serve health-positioned retail segments where nutritional claim thresholds shape formulation architecture.
- Non-Dairy:Fully plant-based blocks eliminate dairy derivatives to capture vegan-labeled bakery applications and allergen-sensitive food manufacturing.
Regular block formats anchor the volume base while Non-Dairy variants gain share at the steepest rate.
End User:
Cost tier stratification separates commodity-scale industrial buyers from premium-positioned artisan channels, with technical service depth becoming the primary differentiation lever.
- Food Manufacturers:Large-scale industrial bakeries and frozen dough producers in Germany and the Netherlands consolidate procurement around direct supplier relationships with embedded formulation support. REACH-compliant supply security and consistent plasticity across climatic variables drive vendor selection.
- Bakeries:Artisan and commercial baking operations require tailored block margarines with precise melting profiles for laminated pastry applications. Technical partnership demands concentrate in French and Italian clusters where small-batch producers seek application-specific rheology guidance.
- Foodservice:Restaurant and catering channels prioritize unit economics and storage stability over performance specifications, accepting broader plasticity tolerances.
- Households:Consumer retail demand fragments toward convenience formats, with traditional block configurations losing ground to spreadable tubs in domestic purchasing.
Food Manufacturers command the largest revenue pool while Bakeries expand most quickly through technical service premiums.
Packaging Type:
Application-specific packaging geometries align with operational workflows across industrial and artisan environments, with format choice directly influencing handling efficiency and shelf-life management.
- Block:Solid rectangular formats optimized for mechanical cutting and lamination processes remain essential for industrial pastry production. German baking clusters sustain concentrated demand for standardized block dimensions that integrate with automated production lines.
- Plastic Tub:Spreadable containers capture foodservice and household segments where scoop-and-serve convenience outweighs portion control requirements.
- Sachet:Single-serve portions address institutional catering and airline food preparation with precise dosing and reduced waste.
- Glass Jar:Premium-positioned retail formats serve gift and specialty channels where packaging aesthetics support price positioning.
Block packaging anchors the volume base while Plastic Tub formats climb the fastest through foodservice channel expansion.
Fat Content:
Margin concentration tracks formulation complexity, with full-fat and reduced-fat segments commanding distinct pricing architectures based on emulsifier sophistication and structuring technology requirements.
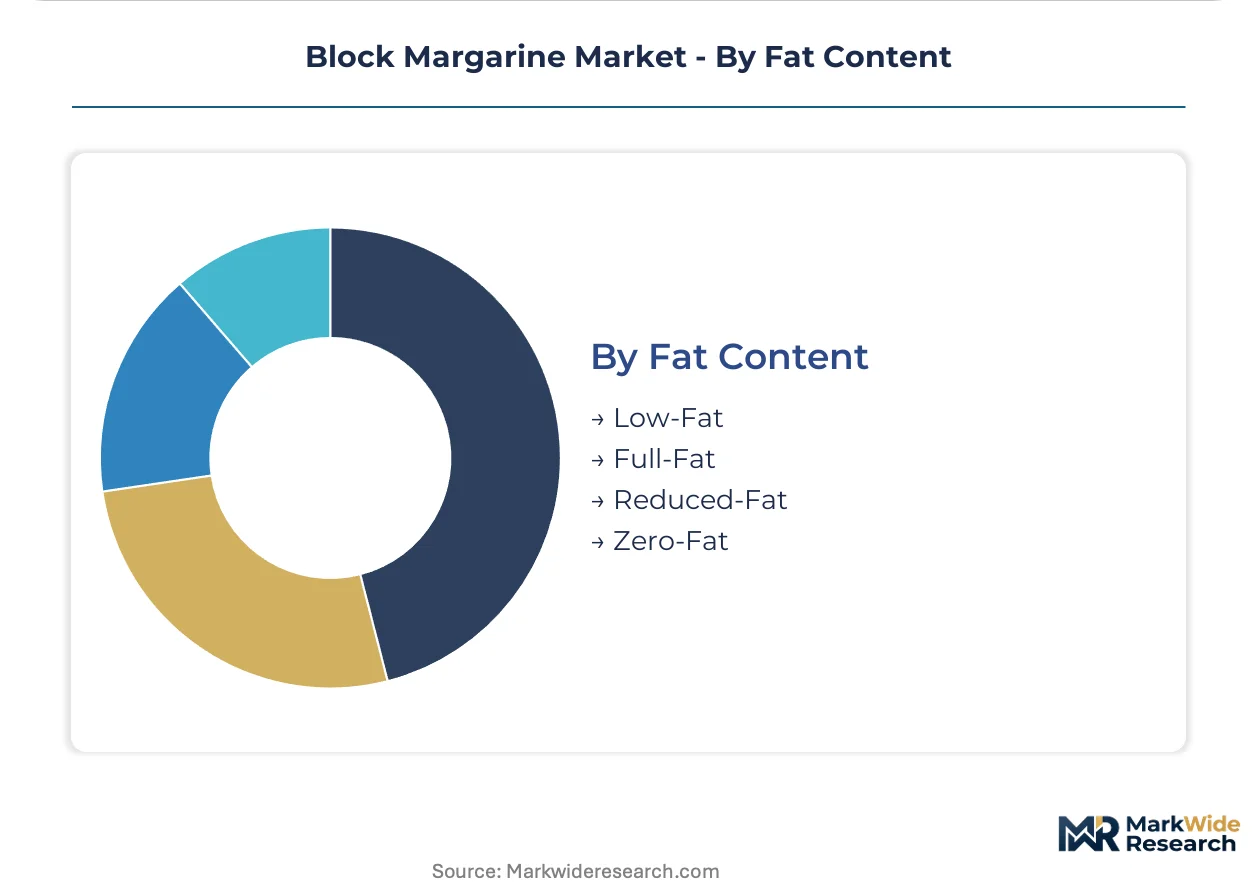
- Full-Fat:80% fat emulsions deliver optimal plasticity for laminated dough applications where butter-layer integrity determines product quality. Industrial bakeries in Northern Europe specify these formulations for croissant and puff pastry production despite trans-fat reformulation pressures.
- Reduced-Fat:60-70% fat variants with enhanced water binding serve health-claim-eligible retail products where nutritional profiling supports shelf positioning.
- Low-Fat:Sub-60% formulations address regulatory nutritional targets in institutional feeding programs with compromised functional performance.
- Zero-Fat:Fat-free spreads occupy niche positioning where complete fat elimination overrides texture and mouthfeel requirements.
Full-Fat formulations anchor the volume base while Reduced-Fat variants gain share at the steepest rate through clean-label reformulation pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German industrial bakers prioritize technical performance over feedstock cost swings, while foodservice buyers in emerging markets exhibit acute sensitivity to palm oil price fluctuations.
Germany
Industrial baking clusters in Lower Saxony and North Rhine-Westphalia sustain concentrated demand for high-plasticity block formats optimized for automated lamination lines. REACH and EU F-Gas Regulation compliance creates procurement preference for early-adapting suppliers. The Hanover-Bremen corridor anchors frozen dough export production, with manufacturers consolidating direct supplier relationships to secure formulation support.
France
Artisan bakery traditions in Île-de-France and Auvergne-Rhône-Alpes drive premium positioning for tailored block margarines with precise melting profiles. EFSA contaminant thresholds on 3-MCPD and glycidyl esters tighten quality specifications for refined oil inputs. Lyon and Paris basin operations concentrate technical service partnerships where small-batch producers seek application-specific rheology guidance.
Netherlands
Rotterdam's oilseed processing infrastructure supports backward-integrated margarine manufacturing with captive refined oil supply. EU Green Deal carbon-border provisions reshape sourcing economics for palm and shea feedstocks. The Randstad region hosts export-oriented frozen dough manufacturers requiring consistent fat performance across variable climatic conditions.
United States
FDA trans-fat disclosure rules and nutritional claim thresholds shape formulation architecture for domestic and imported products. Industrial bakeries in the Midwest prioritize unit economics in procurement decisions. Chicago-area food manufacturers balance clean-label mandates with cost containment pressures in institutional channels.
United Kingdom
Post-Brexit regulatory divergence from EU REACH frameworks creates compliance complexity for cross-border supply chains. London and Southeast England concentrate foodservice demand where storage stability outweighs performance specifications. Midlands-based industrial bakers seek supply security against potential additive restriction expansions.
Block Margarine Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the block margarine market. Integrated oilseed processors leverage captive feedstock supply to defend margin positions, while specialized margarine formulators compete on technical service depth and application expertise. The competitive landscape segments into three strategic archetypes: multinational consumer goods conglomerates with global brand architectures, agribusiness operators with crushing and refining integration, and regional specialists focused on artisan and industrial bakery technical partnerships. Dominant competitive moves include direct procurement relationship consolidation with large industrial bakeries and enzymatic interesterification capacity investments to eliminate trans-fat declarations.
Among diversified consumer goods groups, Unilever and Conagra Brands occupy positions exemplifying global brand architecture leverage. Bunge Limited and Wilmar International represent agribusiness archetypes with upstream oilseed processing integration. Vandemoortele anchors the specialist tier, competing on tailored industrial margarine formulations rather than commodity volume scale. Fuji Oil Holdings and Upfield sit within intermediate positions, balancing regional manufacturing scale with clean-label reformulation capabilities.
| Leading Market Players |
|---|
| Unilever |
| Conagra Brands, Inc. |
| Bunge Limited |
| Wilmar International Ltd. |
| Fuji Oil Holdings Inc. |
| Vandemoortele |
| Upfield |
| Yildiz Holding |
| Arla Foods |
| Others |
Supply Flow & Price Mechanics
Sixty-day inventory cycles for shea butter and specialty refined oils concentrate working capital exposure among European formulators, compressing margin flexibility when West African supply disruptions coincide with peak baking demand seasons. This lead-time structure amplifies pricing power for backward-integrated processors with captive oilseed crushing while forcing toll-dependent competitors into spot market vulnerability.
Pricing Analysis
Technical service bundling drives lifetime value more than commodity tonnage, with formulation support contracts capturing recurring revenue streams that transcend raw material volatility. Three-tier pricing structure across premium, standard, and economy levels segments buyers by application complexity and volume scale. Pricing pressure stems from palm oil feedstock volatility transmitted through Malaysian and Indonesian supply fluctuations. Food manufacturers exhibit lowest price sensitivity due to reformulation switching costs, while foodservice procurement teams prioritize unit economics above performance specifications.
Supply Chain Analysis
Just-in-time inventory preferences dominate industrial bakery procurement in Germany and the Netherlands, though artisan channels maintain strategic stockpiles of certified organic variants with extended documentation trails. Feedstock supply concentrates in Malaysia, Indonesia, and West Africa for palm and shea inputs. European enzymatic interesterification capacity constrains trans-fat-free formulation availability. Tariff exposure on refined vegetable oil imports creates margin unpredictability for non-integrated processors. Distribution runs through direct supplier relationships with large industrial bakeries, disintermediating traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Block margarine sits in early-cycle expansion as enzymatic interesterification technology penetrates industrial bakery accounts and clean-label mandates accelerate reformulation pipelines across European retail chains.
For Market Incumbents: Shield formulation leadership through captive enzymatic interesterification capacity investments that eliminate trans-fat declarations while maintaining lamination performance. Lock in direct procurement relationships with German frozen dough exporters before REACH compliance barriers harden further. Backward integration into specialty refined oil supply secures margin defense against EFSA contaminant threshold tightening. For New Entrants and Emerging Players: Technical service gaps in French and Italian artisan bakery clusters present white-space opportunities where incumbents under-serve small-batch producers with application-specific rheology guidance. Target regional artisan cooperatives with embedded formulation partnerships rather than commodity volume plays. Lead with precision temperature control integration and real-time plasticity monitoring as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because enzymatic interesterification capacity scarcity and REACH compliance expertise concentrate value capture among integrated specialists. Acquisition targets should exhibit regional manufacturing scale paired with clean-label reformulation capabilities. Watch carbon border adjustment implementation timing as inflection indicator for low-carbon supply chain premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Capacity Expansion | Eliminates trans-fat declarations while preserving lamination integrity for Northern European industrial bakeries. |
| Direct Supplier Relationship Consolidation | Captures procurement preference from German frozen dough manufacturers seeking REACH-compliant supply security. |
| Carbon Border Adjustment Positioning | Creates first-mover advantage for manufacturers with verified low-carbon palm and shea supply chains. |
| Artisan Bakery Technical Service Partnership | Addresses underserved small-batch producers in French and Italian clusters with embedded application support. |
| Specialty Refined Oil Backward Integration | Secures margin defense against EFSA 3-MCPD and glycidyl ester threshold tightening. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EFSA contaminant evaluations, EU customs trade data, and oilseed processing capacity disclosures. Primary interviews engaged lipid chemists at enzymatic interesterification facilities, procurement directors at German industrial bakeries, technical service managers at specialty margarine formulators, and regulatory affairs leads navigating REACH compliance. Secondary validation drew from ECHA substance restriction updates, Malaysian Palm Oil Board export statistics, and SEC filings from integrated agribusiness operators. Bottom-up volume modeling triangulates against top-down market sizing across product type, end user, and regional segments.
Segmentation dimensions modeled span product architecture, packaging format, fat content tier, end-user category, and regional regulatory cluster across the analysis window. CAGRs derive from trend extrapolation calibrated against historical substitution elasticities between block margarine and butter in laminated pastry applications. Industry-specific forecast inputs incorporate enzymatic interesterification capacity buildout timelines and carbon border adjustment implementation trajectories.
Underlying assumptions cover sustained palm oil feedstock availability, REACH compliance stability, and industrial bakery cluster expansion continuity, with deviation risk concentrated in West African shea supply disruptions and EFSA contaminant threshold revisions. Revision becomes warranted when carbon border adjustment enforcement crosses thresholds that restructure sourcing economics for tropical oil feedstocks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Tomato Paste Market
Processed Foods
Global Malted Milk Market
Processed Foods
Industrial Margarine Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Processed Egg Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Processed Potatoes Market
Processed Foods
Apple Butter Market
Processed Foods
Low-Calorie Margarine Market
Processed Foods
Processed Fruit Bases Market
Processed Foods
Low Fat Soups Market
Processed Foods
Egg White Cubes Market