
 Asia-Pacific Ice Cream Market | 2026-2036
Asia-Pacific Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ice Cream Market Analysis
Adult consumers seeking premium indulgence is reorganizing demand away from mass-market family packs toward single-serve artisanal formats. Inner Mongolia Yili Industrial Group leverages its dairy supply chain to dominate China's premium tier. Meiji Holdings anchors its position in Japan through R&D intensity in functional ice cream with probiotic claims. Nestlé competes across Southeast Asia through brand strength in impulse channels.
Ice cream is a frozen dairy or non-dairy emulsion typically containing milk fat, sweeteners, stabilizers, and air overrun, churned at sub-zero temperatures to achieve a semi-solid foam structure designed for sensory refreshment and nutritional delivery. Bars and cups command the deepest margin pools in Asia-Pacific, with bars leading in Japan and South Korea due to vending-machine ubiquity, while cups expand fastest in India where Gujarat Cooperative Milk Marketing Federation sustains dominance in take-home formats. Matcha flavor specialization distinguishes Japanese producers, whereas vanilla and chocolate remain volume anchors across Southeast Asian markets.
China's SAMR enforces GB standards for frozen dairy product labeling, while India's FSSAI mandates cold-chain integrity declarations that raise compliance costs for smaller processors. Japan's METI oversees energy-efficiency rules for retail freezer cabinets that shape capital expenditure patterns. Stakeholders must monitor how ASEAN harmonization of dairy import tariffs reshapes sourcing strategies for multinational operators.
Market Dynamics
Cold-chain infrastructure gaps across Southeast Asia and India's tightening FSSAI dairy compliance are forcing capital reallocation toward freezer asset ownership and third-party logistics partnerships rather than traditional distributor networks.
Growth Catalysts
- Functional probiotic claims:Japanese consumers prioritize gut-health positioning in frozen desserts, accelerating R&D investment in live-culture stability through freeze-thaw cycles.
- Convenience store penetration:China's tier-one cities now host unmanned freezer cabinets in office towers and transit hubs, collapsing the distance between impulse trigger and purchase completion.
- FSSAI cold-chain mandates:India's enforcement of temperature-integrity declarations for dairy-based products is professionalizing logistics standards and squeezing informal street-vendor channels.
Market Restraints
- Milk fat price volatility:New Zealand's Fonterra auction pricing transmits directly to formulation costs across Asia-Pacific, compressing margin buffers for mid-tier producers.
- Freezer cabinet energy standards:Japan's METI efficiency rules require capital-intensive cabinet replacement cycles that strain convenience-store operators with thin balance sheets.
- Plant-based substitution:Oat and coconut milk frozen desserts capture lactose-intolerant and vegan segments in Australia's urban centers, capping dairy-based volume ceilings.
Strategic Opportunities
- Vietnam's underpenetrated south:Ho Chi Minh City's emerging middle class lacks premium freezer-aisle depth, creating first-mover space for artisanal cup formats.
- Food-service co-manufacturing:Hotels and restaurant chains in Thailand seek private-label gelato programs, opening B2B revenue streams beyond retail.
- ASEAN tariff harmonization:Reduced dairy import duties under the ASEAN Trade in Goods Agreement enable centralized production hubs serving multiple member states.
Industry Challenges
- Refrigeration technician scarcity:India's cold-chain expansion outpaces vocational training output, extending equipment downtime and spoilage risk.
- Legacy distributor integration:Traditional wet-market channels in Indonesia resist temperature-monitoring technology adoption, creating compliance blind spots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ice Cream Market |
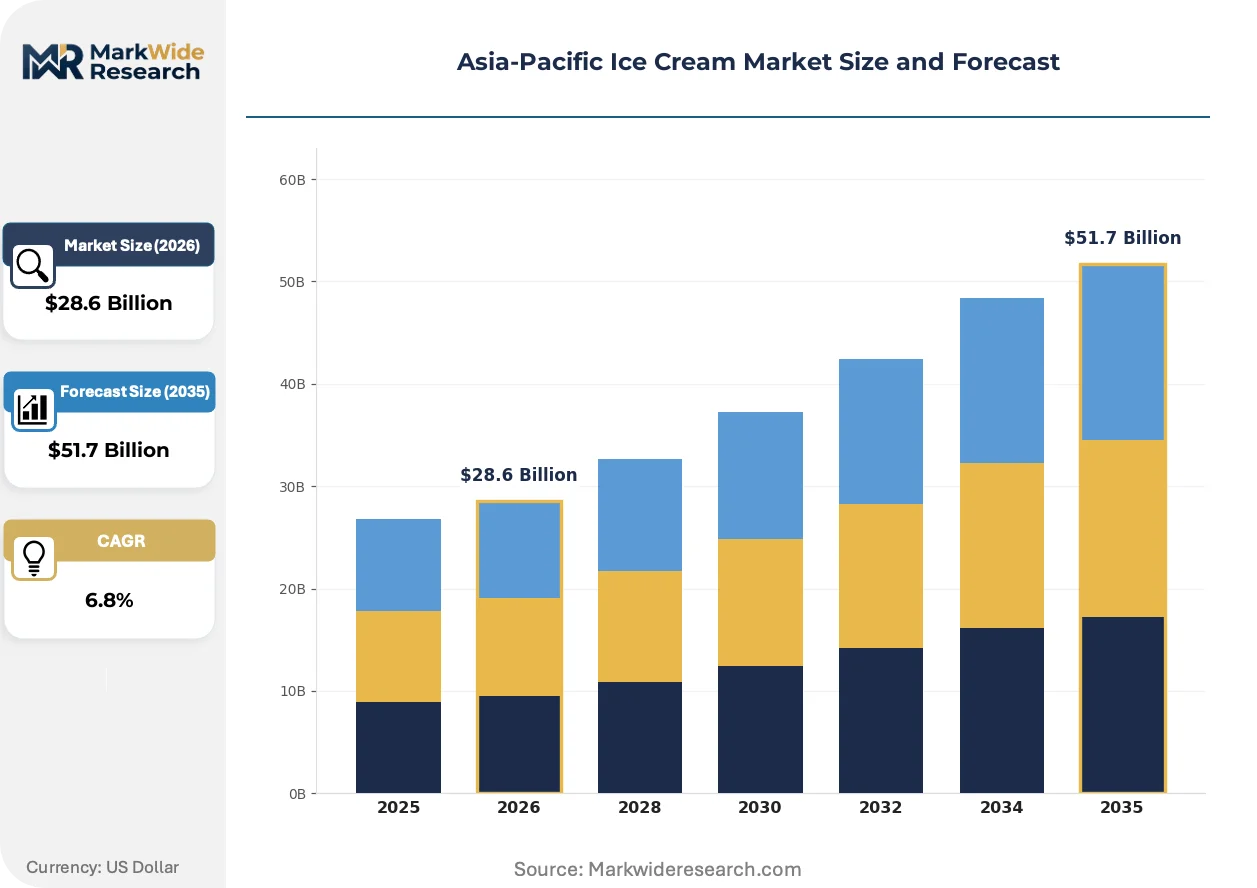
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cups, Cones, Bars, Sandwiches Flavor: Vanilla, Chocolate, Strawberry, Matcha Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service End User: Children, Teenagers, Adults, Families |
| Companies Covered | Inner Mongolia Yili Industrial Group Co., Ltd., China Mengniu Dairy Company Limited, Unilever PLC, Meiji Holdings Co., Ltd., Lotte Confectionery Co., Ltd., Nestlé S.A., Gujarat Cooperative Milk Marketing Federation Ltd, Froneri Ltd, General Mills Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ice Cream Market Emerging Trajectories
Clean-label formulation and precision fermentation are disrupting conventional dairy dependency while regulatory energy mandates reshape freezer fleet economics across the region.
Precision fermentation for dairy proteins is decomposing the traditional milk supply chain by enabling lactose-free, cholesterol-free base ingredients without cattle agriculture. Singapore's regulatory sandbox for novel foods accelerates commercial trials, while Japanese dairy cooperatives pilot hybrid products blending fermented and conventional fats to manage cost exposure.
China's SAMR enforcement of GB 28050 nutrition labeling for frozen desserts now mandates front-of-pack sugar disclosure, compressing permissible formulation ranges. Domestic producers reformulate with monk fruit and erythritol blends to maintain sweetness perception, while import-dependent brands face reformulation lag versus local competitors.
Adult consumers now treat ice cream as experiential ritual rather than family convenience, collapsing the multi-serve tub segment. Single-serve artisanal bars and cups displace bulk formats in Shanghai and Tokyo convenience channels, while dessert-focused social media content drives flavor novelty cycles that strain R&D pipelines.
Asia-Pacific Ice Cream Market Segmentation
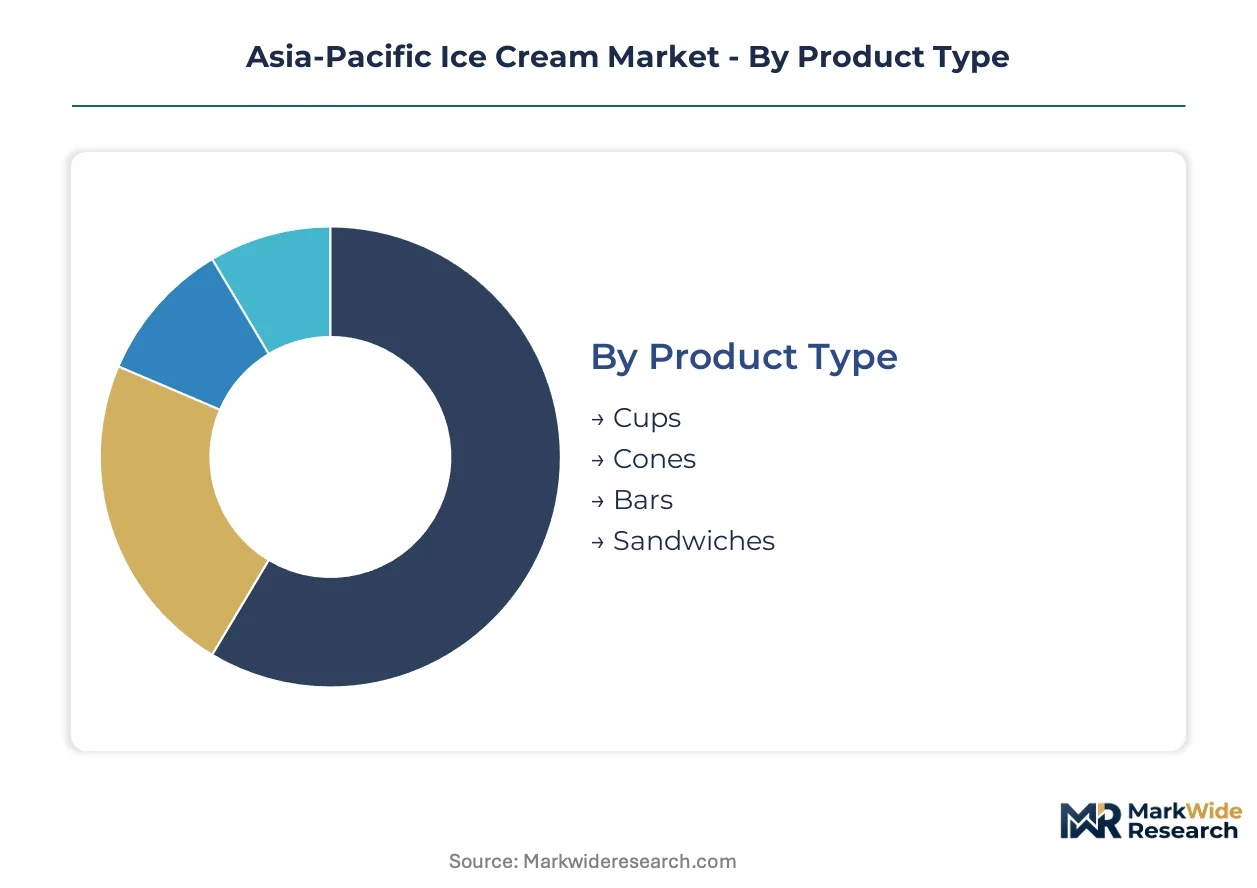
Ice cream segmentation across Asia-Pacific reflects divergent consumption rituals between impulse-driven urban convenience channels and planned household purchases. Format and flavor preferences cluster sharply by geography, with Japan's vending-machine density and India's cold-chain constraints creating fundamentally different segment economics.
Product Type:
Domestic production dominates cups and cones across India and China, while bars and sandwiches rely more heavily on imported formulations from Japan and South Korea where manufacturing precision is concentrated.
- Cups:Take-home formats with higher overrun and stabilizer content designed for freezer storage. Demand concentrates in India's tier-two cities where Gujarat Cooperative Milk Marketing Federation maintains distribution depth; FSSAI cold-chain mandates favor cup formats with longer thaw-stable windows.
- Bars:Single-serve sticks and coated formats optimized for vending-machine dispensing and impulse purchase. Tokyo and Seoul convenience channels drive volume; METI energy-efficiency rules for freezer cabinets disproportionately impact bar display economics due to high stock-keeping unit density.
- Cones:Pre-filled waffle or sugar cone formats with integrated packaging for on-premise consumption. Street-vendor channels in Indonesia and Thailand favor this segment for portability despite temperature-control challenges.
- Sandwiches:Wafer or cookie-layered formats with higher logistics complexity due to moisture sensitivity. Premium hotel and café channels in Singapore and Hong Kong absorb most regional supply.
Cups hold the largest share; momentum sits with bars.
Flavor:
Cost tier stratification is pronounced, with matcha commanding formulation premiums and vanilla anchoring volume through commodity dairy sourcing.
- Vanilla:Standardized flavor base using bourbon or Tahitian vanilla extracts blended with high-fat dairy. Southeast Asian mass-market producers in Vietnam and the Philippines optimize around this segment for cross-border production efficiency.
- Chocolate:Cocoa butter and cocoa powder formulations ranging from dairy-heavy milk chocolate to intense dark variants. Australian and New Zealand import dependence shapes procurement patterns for premium cocoa inputs.
- Strawberry:Fruit-based formulations using either freeze-dried powder or artificial flavor systems depending on price positioning. Seasonal demand spikes in South Korea align with spring marketing calendars.
- Matcha:Stone-ground green tea powder from Uji and Nishio regions in Japan defines authenticity thresholds. Domestic Japanese producers control supply chains for ceremonial-grade powder, limiting regional replication.
Vanilla holds the largest share; matcha is climbing the fastest.
Distribution Channel:
Volume concentration favors modern trade, though margin structure inverts toward food service and online retail where premium positioning is achievable.
- Supermarkets:Multi-serve tub and family-pack formats with extended shelf-facing requirements. China's tier-one city hypermarkets by Sun Art Retail Group and Yonghui Superstores dominate regional throughput.
- Convenience Stores:High-velocity impulse channels with 24-hour operation and freezer-cabinet density. Japan's Seven-Eleven and Lawson networks set the regional standard for frozen dessert merchandising.
- Online Retail:Direct-to-consumer frozen delivery requiring specialized last-mile cold packaging. Tightening FSSAI e-commerce regulations in India are professionalizing this channel's logistics standards.
- Food Service:Hotels, restaurants, and cafés sourcing gelato and artisanal formats through co-manufacturing arrangements. Thailand's hospitality recovery is expanding private-label program demand.
Supermarkets hold the largest share; online retail is gaining share fastest.
End User:
Customer type segmentation reveals the sharpest demand reorganization, with adult experiential consumption displacing family-centric purchasing.
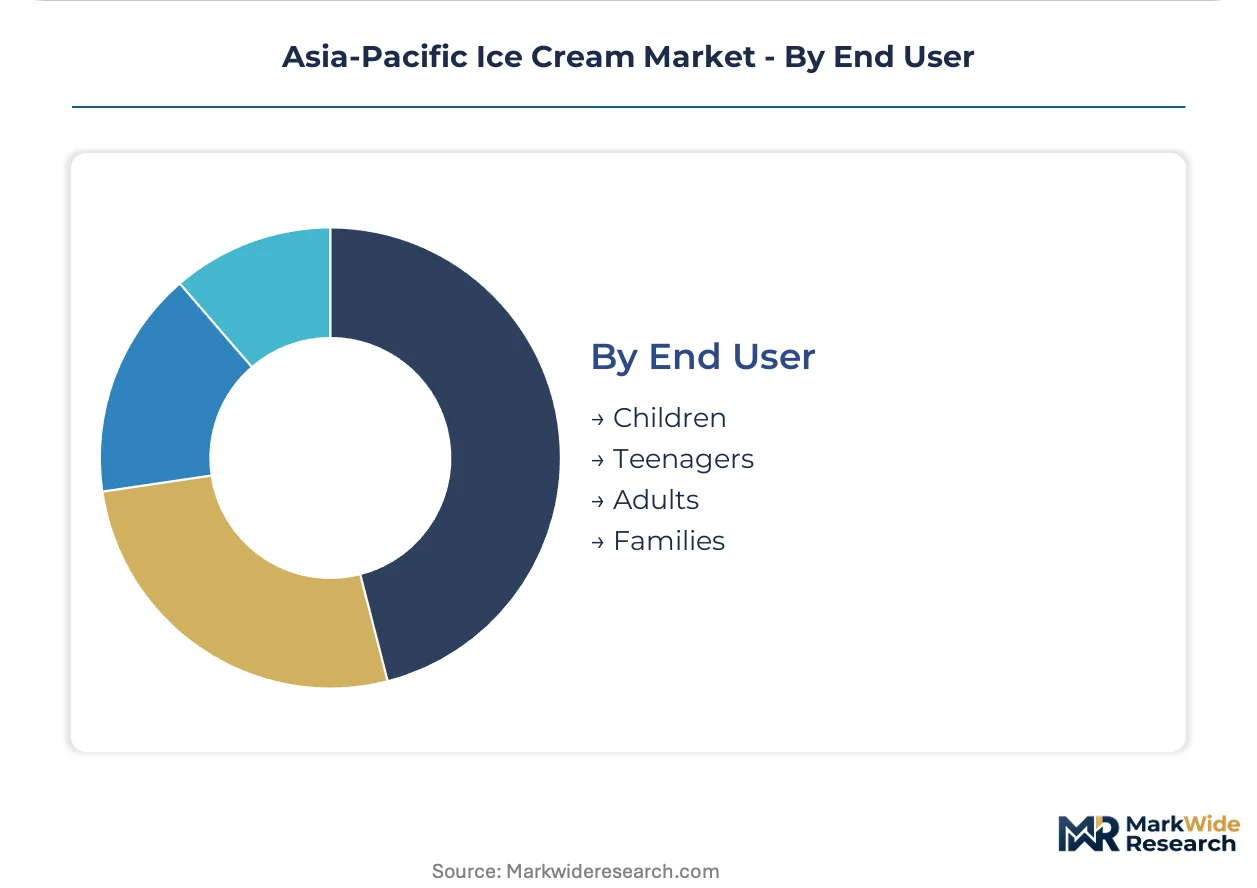
- Adults:Premium single-serve seekers treating ice cream as personal indulgence rather than shared dessert. Shanghai and Tokyo convenience channels report the steepest shift toward this segment.
- Families:Multi-serve tub purchasers prioritizing value and shareability. India's Amul and China's Yili compete intensely for household freezer space through promotional bundling.
- Teenagers:Flavor novelty-driven consumers responsive to social media marketing and limited-edition collaborations. South Korean convenience stores target this demographic with K-pop branded formats.
- Children:Sugar-conscious parents increasingly restrict this segment; reformulation toward reduced-sugar and functional claims is compressing traditional child-oriented marketing.
Families hold the largest share; adults show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium-seeking adult consumers cluster in China's tier-one cities, Japan's metropolitan corridors, and India's emerging urban centers, driving divergent format preferences and regulatory exposure across the region.
China
Unmanned freezer cabinets in Shanghai and Beijing office towers collapse impulse-to-purchase distance, while SAMR enforces GB 28050 front-of-pack sugar disclosure rules. Inner Mongolia Yili Industrial Group leverages its dairy supply chain dominance to capture premium tier growth in the Yangtze River Delta corridor.
Japan
Vending-machine ubiquity in Tokyo and Osaka drives single-serve bar volume, with METI energy-efficiency rules for retail freezer cabinets reshaping capital expenditure patterns. Meiji Holdings anchors its position through R&D intensity in functional probiotic claims that command formulation premiums in Kanto region convenience channels.
India
FSSAI cold-chain compliance mandates for dairy-based frozen desserts professionalize logistics standards and squeeze informal street-vendor channels. Gujarat Cooperative Milk Marketing Federation sustains dominance in take-home cup formats across tier-two cities where freezer infrastructure penetration lags tier-one metros.
South Korea
K-pop branded limited-edition formats target teenage consumers in Seoul convenience stores, while vending-machine density in Busan-Ulsan mirrors Japan's impulse-channel structure. Lotte Confectionery Co., Ltd. exemplifies the scale-driven archetype serving this novelty-responsive demographic.
Vietnam
Ho Chi Minh City's emerging middle class lacks premium freezer-aisle depth, creating first-mover space for artisanal cup formats. ASEAN Trade in Goods Agreement tariff harmonization enables multinational operators to serve this underpenetrated south through centralized production hubs.
Asia-Pacific Ice Cream Market Vendor Landscape
Player mix skews toward integrated dairy conglomerates with captive supply chains and multinational CPG platforms with impulse-channel brand equity. Market structure concentrates around tier-one Chinese domestic producers, Japanese functional specialists, and Southeast Asian distribution arms of global majors. Strategic archetypes include supply-chain-integrated dairy giants, R&D-intensive health-claim innovators, and brand-heavy impulse-channel operators. Dominant competitive moves encompass backward integration into dairy sourcing and convenience-store freezer cabinet asset ownership.
Among China-based dairy conglomerates, Inner Mongolia Yili Industrial Group Co., Ltd. and China Mengniu Dairy Company Limited represent the supply-chain-integrated archetype controlling upstream milk sourcing. Meiji Holdings Co., Ltd. anchors the functional innovation tier through its Japanese R&D infrastructure. Nestlé S.A. and Unilever PLC exemplify the multinational CPG archetype leveraging brand equity across Southeast Asian impulse channels.
| Leading Market Players |
|---|
| Inner Mongolia Yili Industrial Group Co., Ltd. |
| China Mengniu Dairy Company Limited |
| Unilever PLC |
| Meiji Holdings Co., Ltd. |
| Lotte Confectionery Co., Ltd. |
| Nestlé S.A. |
| Gujarat Cooperative Milk Marketing Federation Ltd |
| Froneri Ltd |
| General Mills Inc. |
| Others |
Supply Flow & Price Mechanics
Precision fermentation dairy proteins are displacing conventional milk fat across premium formulations, simultaneously shifting procurement geography toward Singapore's novel-food regulatory sandbox and compressing traditional dairy-based pricing premiums in Japan and Australia.
Pricing Analysis
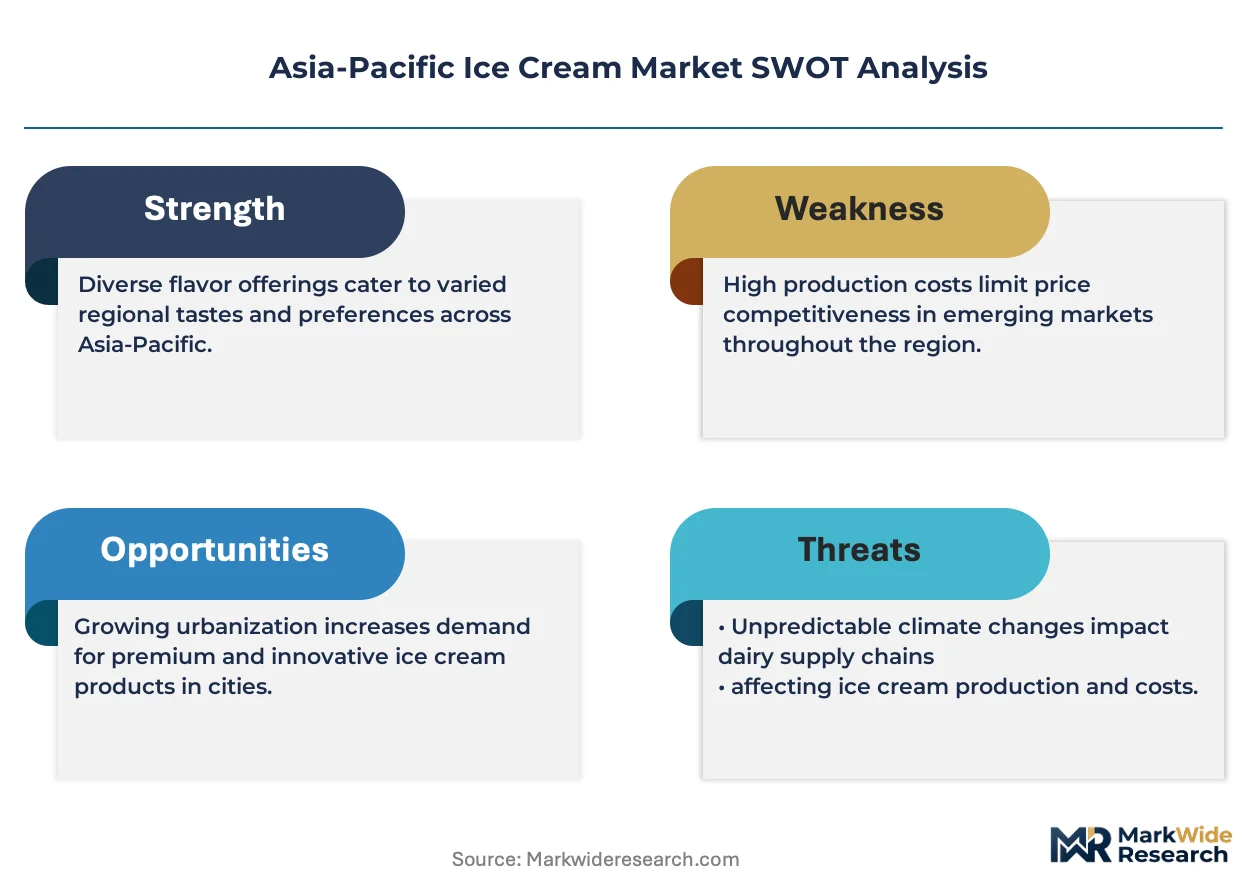
Next-generation precision-fermentation bases command formulation premiums against conventional dairy and first-generation plant alternatives across the Asia-Pacific ice cream market. Three-tier pricing structure across premium artisanal, standard impulse, and economy family-pack levels stratifies by ingredient sourcing transparency and cold-chain certification grade. Pricing pressure stems from Fonterra auction volatility transmitting directly to mid-tier producer margins. Convenience-store operators show highest price sensitivity due to METI-mandated freezer cabinet replacement cycles, while food-service channels absorb premium positioning with least resistance.
Supply Chain Analysis
New Zealand's Fonterra auction system functions as a chokepoint transmitting milk fat price shocks across Asia-Pacific formulation costs. Manufacturing concentrates in China, Japan, and South Korea for bar formats; India and Thailand dominate cup production. Raw material dependencies span New Zealand milk powder, Japanese matcha powder, and Southeast Asian coconut cream. Single-source vulnerability runs through Uji-region ceremonial-grade matcha supply. Distribution runs through captive freezer cabinet networks in convenience channels and third-party cold-chain partnerships for modern trade.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific ice cream market sits in early-cycle expansion as adult experiential consumption penetrates China's tier-one cities and Vietnam's emerging metros, with unmanned freezer infrastructure collapsing purchase friction.
For Market Incumbents: Fortify cold-chain asset ownership against FSSAI compliance escalation in India and SAMR labeling enforcement in China. Deepen backward integration into precision fermentation partnerships to hedge Fonterra price exposure. Prioritize freezer cabinet density in Shanghai and Ho Chi Minh City transit corridors to preempt challenger shelf access. For New Entrants and Emerging Players: Anchor in Vietnam's underpenetrated south where premium cup formats lack freezer-aisle competition. Target Thailand's hospitality private-label gelato programs as a B2B beachhead with lower brand equity barriers than retail. Lead with matcha-authenticity storytelling or probiotic functional claims to differentiate against integrated dairy conglomerates. For Investors and Strategic Acquirers: The market sits at a premium-format acceleration phase that favors supply-chain-integrated regional specialists over pure-brand plays. Long-term viability hinges on captive dairy sourcing and cold-chain infrastructure ownership rather than marketing spend efficiency. Monitor ASEAN tariff harmonization implementation as the signal for centralized production hub economics activation.| Strategic Initiative | Industry Significance |
|---|---|
| Freezer Cabinet Asset Ownership | METI efficiency rules and FSSAI mandates make captive cold-chain infrastructure a competitive moat in Japan and India. |
| Precision Fermentation Partnership | Singapore's regulatory sandbox accelerates dairy-protein alternative sourcing that hedges Fonterra auction volatility. |
| Functional Probiotic R&D Investment | Meiji Holdings' gut-health positioning commands premium shelf space in Kanto region convenience channels. |
| Food-Service Co-Manufacturing Program | Thailand's hospitality recovery expands private-label gelato demand beyond retail margin compression. |
| ASEAN Centralized Production Hub | Tariff harmonization under ATIGA enables single-factory supply across Vietnam, Thailand, and Philippines markets. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with dairy procurement directors, convenience-store category managers, cold-chain logistics operators, and FSSAI compliance officers; and secondary validation through customs trade records, SAMR GB standard filings, METI energy-efficiency rulemakings, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category spending estimates.
Across the projection horizon, the analytical framework segmented by product format, flavor positioning, distribution channel, and end-user demographic. CAGRs derived from trend extrapolation of convenience-store freezer penetration, adult consumption shift rates, and regulatory compliance cost absorption curves. Forecast inputs incorporated Fonterra auction price trajectories and ASEAN tariff schedule implementation timelines.
Underlying assumptions cover cold-chain infrastructure buildout pacing and precision fermentation commercialization timelines, with deviation risk concentrated in India's FSSAI enforcement intensity and China's unmanned retail adoption curves. Practitioners should keep alternative scenarios live as regulatory harmonization and novel-food approval pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
United States Processed Meat Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Processed Egg Market
Processed Foods
India Spray Dried Food Market
Processed Foods
Dairy Desserts Market
Processed Foods
High Pressure Processing (HPP) for Rice and Grain Market
Processed Foods
Low-Calorie Margarine Market
Processed Foods
Broth Market
Processed Foods
North America Ice Cream Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
Africa Soup Market
Processed Foods
Sugar-Free Ice Cream Market
Processed Foods
US Tomato Paste Market
Processed Foods
Butter Crisco Market
Processed Foods
Apple Butter Market
Processed Foods
Low Fat Pasta Market