
 Low Calorie Rice Pudding Market | 2026-2036
Low Calorie Rice Pudding Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Rice Pudding Market Analytics
Asset-light contract manufacturing is narrowing the capital barrier for new entrants in refrigerated dairy-alternative desserts. Royal leverages its European co-packing network to extend shelf presence without owning production facilities. Kozy Shack anchors its competitiveness through deep specialization in ready-to-eat pudding formats. Kraft Foods dominates mainstream retail distribution through long-standing control over supermarket refrigerated sets.
Low calorie rice pudding is a reduced-energy dairy or plant-based dessert containing cooked rice grains, typically formulated with less than 150 calories per single-serve portion through sugar substitution or fat reduction, and retailed under refrigerated conditions for immediate consumption. The product serves consumers managing caloric intake while seeking indulgent texture profiles. Vegan formulations lead growth trajectory as oat and coconut milk bases displace conventional dairy in European and North American retail. Single-serve cups command the dominant packaging share, though eco-friendly formats are gaining traction among sustainability-oriented retailers. Health food shops represent the fastest-growing distribution channel as specialty grocers expand functional dessert assortments.
FDA nutrition labeling requirements and EU F-Gas Regulation on refrigeration emissions shape formulation and cold-chain compliance costs for manufacturers operating in North America and Europe. BIS standards in India and EFSA clean-label guidance create divergent compliance thresholds for brands pursuing multi-territory distribution. Stakeholders must monitor evolving sweetener approval pathways and refrigeration energy standards to align capital allocation with regulatory trajectory.
Market Dynamics
Clean-label reformulation pressure is compressing margins while forcing rapid sweetener substitution across European and North American manufacturing footprints. Manufacturers must simultaneously satisfy EFSA guidance on additive transparency and retailer demands for front-of-pack simplicity.
Growth Catalysts
- EU F-Gas Regulation:Refrigeration equipment upgrades across Germany, France, and the United Kingdom are modernizing cold-chain infrastructure, expanding retail shelf capacity for chilled desserts.
- Wellness program enrollment:Corporate nutrition initiatives in North America are subsidizing low-calorie dessert options in workplace cafeterias, creating institutional procurement pull.
- Oat milk enzymatic processing:Advanced hydrolysis techniques are improving texture parity with dairy bases, accelerating plant-based formulation adoption.
Market Restraints
- Stevia supply concentration:Raw leaf processing capacity clusters in China, creating price volatility and qualification delays for alternative sweetener sourcing.
- Refrigerated logistics density:Last-mile cold-chain coverage gaps in secondary European cities limit distribution radius for temperature-sensitive single-serve formats.
- Clean-label shelf-life tradeoff:Natural preservative exclusion reduces product viability, constraining export timelines to distant markets.
Strategic Opportunities
- Indian urban premium retail:FSSAI-aligned clean-label positioning opens modern trade channels in Mumbai and Bangalore as refrigerated dairy dessert sections expand.
- Direct-to-subscription models:Cold-chain logistics partnerships enable recurring delivery of multi-pack assortments, bypassing traditional supermarket slotting fees.
- Biodegradable barrier coatings:Material science advances in cellulose-based cup linings align with retailer sustainability mandates in Scandinavian markets.
Industry Challenges
- Food technologist specialization:Shortage of formulation chemists skilled in protein-stabilized plant-based emulsions extends R&D cycle timelines.
- Co-packer qualification backlog:Third-party facility audits for allergen segregation protocols create 6-12 month onboarding delays for new production partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Rice Pudding Market |
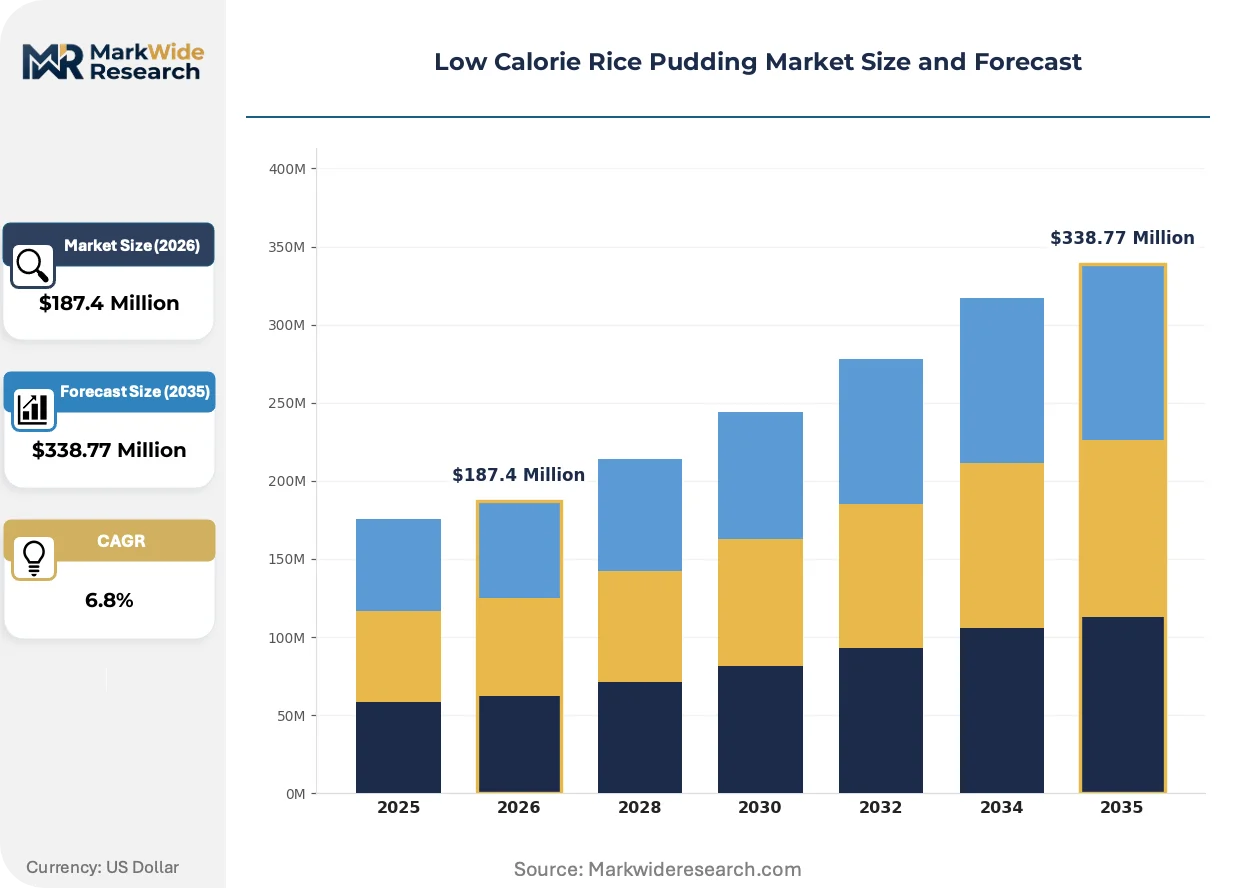
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Vegan, Gluten-Free, Organic Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Health Food Shops Customer Type: Health-Conscious Consumers, Diabetics, Weight Watchers, Fitness Enthusiasts Packaging Type: Single-Serve Cups, Multi-Pack, Bulk, Eco-Friendly |
| Companies Covered | Royal, Kozy Shack, Kraft Foods, Hunt's, Hannaford, Dr. Oetker, Kellogg's, Tesco Groceries, Mondelez International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Rice Pudding Market Evolving Landscape
Formulation science and packaging engineering are converging to resolve the historic tradeoff between caloric reduction and sensory satisfaction. These developments are compressing product development cycles while raising technical barriers for laggard manufacturers.
Fermentation-derived sweetener platforms are hybridizing protein engineering with enzymatic conversion to produce glycoside profiles matching sucrose temporal dynamics. Specialty ingredient houses in Denmark and the Netherlands are licensing these bioprocesses to dessert manufacturers seeking to eliminate lingering aftertaste complaints. The technology is compressing the competitive window for first-mover clean-label positioning in European retail.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon replacement in refrigerated transport and retail display cases. Equipment retrofit obligations are raising capital requirements for cold-chain operators while creating aftermarket service revenue pools for compliance engineering specialists. German supermarket chains are responding with centralized distribution center consolidation to optimize refrigeration asset utilization.
Single-serve assortment purchasing is fragmenting traditional category management relationships between dessert brands and supermarket buyers. Health food shops and specialty grocers are disintermediating conventional slotting fee structures through direct brand partnerships and localized merchandising. This channel rotation is most visible in London and Berlin, where curated refrigerated sets emphasize functional claims over legacy brand recognition.
Low Calorie Rice Pudding Market Segmentation
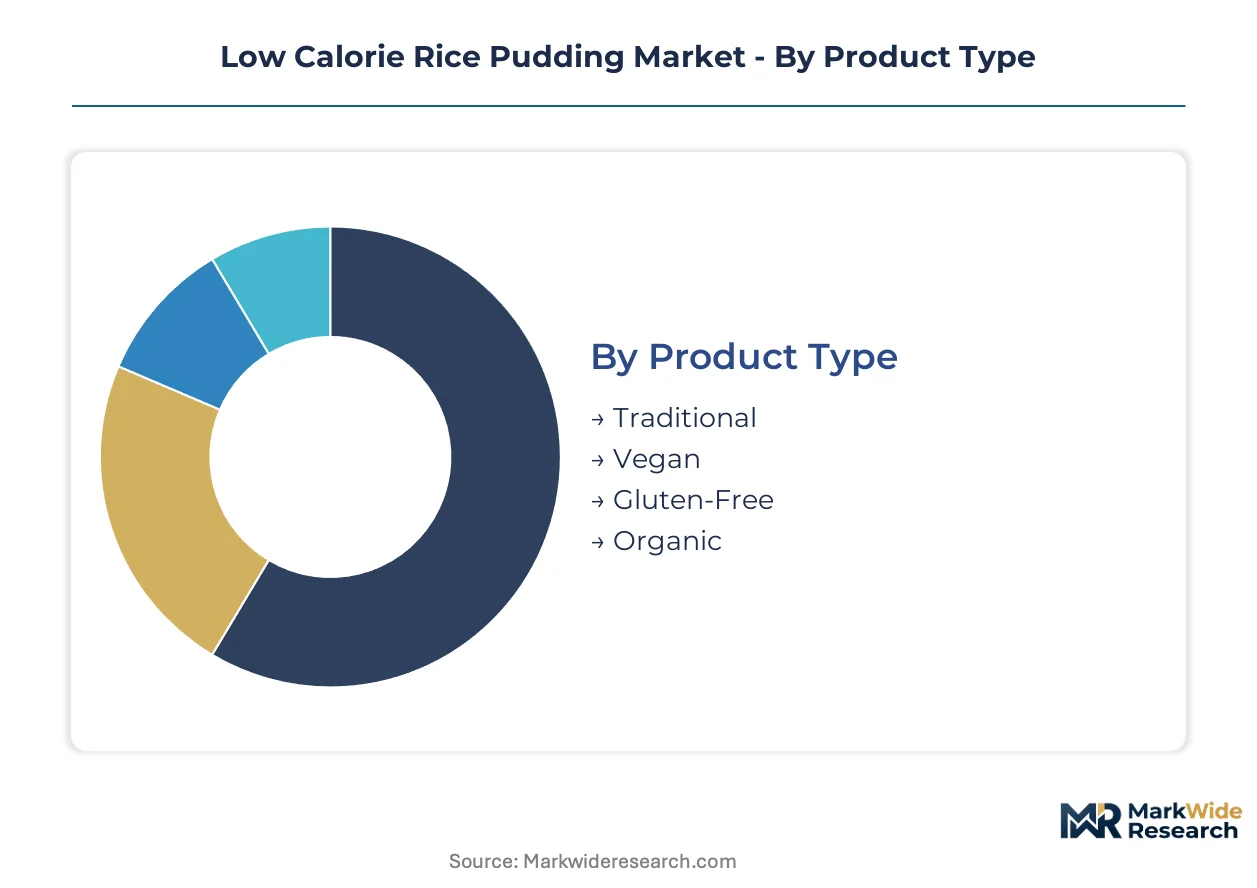
Segmentation in low calorie rice pudding reveals how formulation science, channel strategy, and consumer health objectives intersect. Manufacturers must align product architecture with distinct cold-chain requirements and regulatory thresholds across target markets.
Product Type:
Formulation chemistry determines caloric density, shelf stability, and clean-label positioning for each product tier.
- Traditional:Dairy-based formulations using skim or reduced-fat milk achieve sub-150 calorie targets through portion control and modest sugar reduction. German and French retailers favor these SKUs for their familiar mouthfeel and established manufacturing protocols.
- Vegan:Oat and coconut milk bases displace conventional dairy through enzymatic hydrolysis that replicates creamy texture without lipid load. EFSA-aligned clean-label positioning accelerates placement in Scandinavian and British health food channels.
- Gluten-Free:Rice varieties certified below 20ppm gluten threshold serve celiac and gluten-sensitive populations. Processing segregation protocols extend co-packer qualification timelines.
- Organic:Certified organic rice and sweetener inputs command shelf space in premium supermarket sets. Supply concentration in specific growing regions constrains scaling velocity.
Traditional formulations command the established base. The steepest expansion runs through Vegan.
Distribution Channel:
Channel selection dictates refrigeration infrastructure investment, margin structure, and consumer touchpoint frequency.
- Supermarkets:Refrigerated dessert aisle placement requires slotting fee commitments and centralized distribution center compliance with EU F-Gas Regulation retrofit schedules. Kraft Foods and Royal leverage long-standing buyer relationships to secure eye-level positioning.
- Online Retailers:Cold-chain logistics partnerships enable temperature-controlled last-mile delivery without retail intermediary markup. Subscription bundling of multi-pack assortments bypasses traditional shelf access barriers.
- Specialty Stores:Curated assortments emphasize functional claims and artisanal provenance over mass-market branding. London and Berlin clusters show strongest traction.
- Health Food Shops:Fastest-climbing channel as specialty grocers expand functional dessert sets with dietitian-curated positioning. Direct brand partnerships disintermediate conventional slotting structures.
Supermarket penetration anchors volume. Health Food Shops are gaining share fastest.
Customer Type:
Health objective severity shapes sweetness intensity, portion architecture, and nutritional labeling emphasis.
- Health-Conscious Consumers:Broad demographic seeking permissible indulgence without caloric penalty. Clean-label front-of-pack simplicity drives purchase decision in British and German retail.
- Diabetics:Glycemic management demands stevia or monk fruit sweetening with explicit glucose impact disclosure. FDA nutrition labeling requirements govern permissible health claims.
- Weight Watchers:Calorie-point alignment with commercial diet programs necessitates precise macronutrient transparency. Single-erve portioning matches program portion discipline.
- Fitness Enthusiasts:Post-workout recovery positioning emphasizes protein fortification and rapid glycogen replenishment. Gym-adjacent retail and direct-to-consumer subscription models concentrate demand.
Health-Conscious Consumers represent the volume core. Fitness Enthusiasts show the steepest adoption curve.
Packaging Type:
Format engineering balances convenience, sustainability mandates, and cold-chain thermal performance.
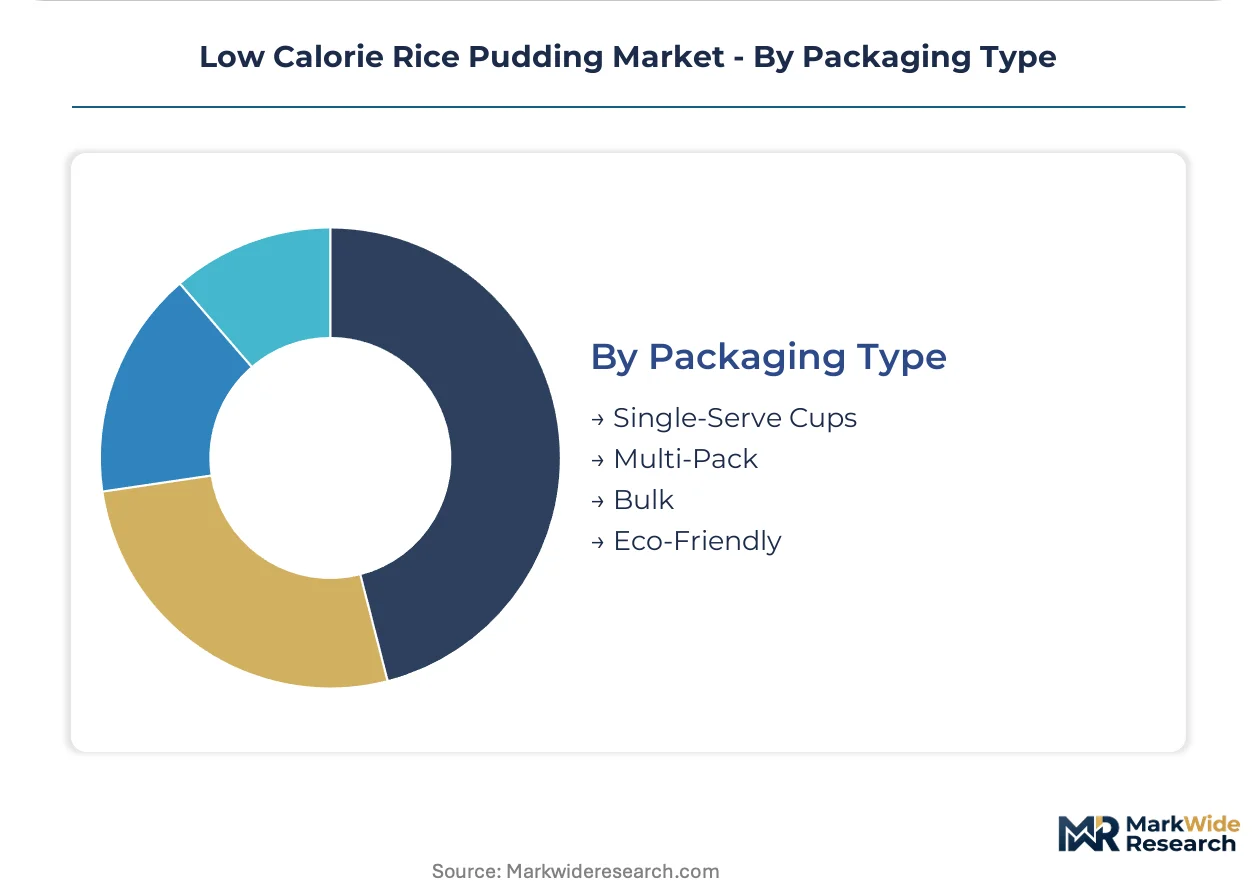
- Single-Serve Cups:Dominant format for immediate consumption and precise portion control. Conventional plastic structures face retailer pressure for barrier-coated cellulose alternatives.
- Multi-Pack:Four-to-six unit bundling reduces per-unit packaging cost and supports subscription replenishment cycles. Family purchasing concentrates in British supermarket channels.
- Bulk:Foodservice and institutional procurement formats for workplace cafeteria wellness programs. Extended shelf-life requirements challenge clean-label preservative exclusion.
- Eco-Friendly:Biodegradable barrier coatings and post-consumer recycled content align with Scandinavian retailer sustainability mandates. Material science advances compress cost premium versus conventional formats.
Single-Serve Cups dominate current volume. Eco-Friendly formats are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation retrofit mandates are expanding refrigerated retail capacity across multiple markets. Germany, the United Kingdom, France, India, and the United States concentrate distinct demand drivers and regulatory frameworks.
Germany
Corporate wellness program enrollment drives institutional procurement of portion-controlled desserts. EU F-Gas Regulation phase-down schedules accelerate supermarket refrigeration upgrades. Berlin and Munich retail clusters expand functional dessert aisles with clean-label positioning.
United Kingdom
Health food shop expansion disintermediates traditional supermarket slotting structures. EFSA clean-label guidance shapes additive transparency requirements. London specialty grocer clusters emphasize dietitian-curated refrigerated sets over legacy brand placement.
France
Familiar dairy-based mouthfeel preferences sustain traditional formulation demand. EU Green Deal sustainability mandates pressure packaging material transitions. Parisian premium supermarket channels prioritize certified organic rice inputs.
India
Urban modern trade expansion in Mumbai and Bangalore creates refrigerated dessert section growth. FSSAI standards govern clean-label positioning for premium retail entry. Maharashtra and Karnataka metropolitan clusters show strongest traction for plant-based alternatives.
United States
FDA nutrition labeling requirements govern permissible health claims on glycemic impact. Workplace cafeteria wellness initiatives subsidize low-calorie dessert procurement. Greater Boston and Pacific Northwest metro areas concentrate fitness-enthusiast subscription demand.
Low Calorie Rice Pudding Market Competitive Landscape
Channel-controlling players compete with product-specialist players across refrigerated dessert aisles. Supermarket slotting fee structures favor established retail relationships, while direct-to-consumer models bypass traditional intermediaries. Three archetypes dominate: diversified food conglomerates with refrigerated set control, pudding-format specialists with deep manufacturing expertise, and asset-light brands leveraging co-packing networks. Competitive moves center on clean-label reformulation speed and cold-chain logistics partnerships.
Within the diversified conglomerate tier, Kraft Foods and Mondelez International exemplify channel-controlling positioning through long-standing supermarket buyer relationships. Royal represents the asset-light archetype, utilizing European co-packing networks to extend shelf presence without production facility ownership. Kozy Shack occupies the specialist position, anchoring competitiveness through ready-to-eat pudding format concentration.
| Leading Market Players |
|---|
| Royal |
| Kozy Shack |
| Kraft Foods |
| Hunt's |
| Hannaford |
| Dr. Oetker |
| Kellogg's |
| Tesco Groceries |
| Mondelez International |
| Others |
Value Network & Pricing Analysis
Jiangsu Province's stevia leaf processing clusters concentrate raw material supply for alternative sweeteners, compressing margin structures for European and North American formulators seeking clean-label positioning. This geographic concentration of enzymatic hydrolysis capacity creates asymmetric pricing power that ripples through oat milk base costs and finished goods positioning in refrigerated dessert aisles.
Pricing Analysis
Certification level creates the primary spread between economy and premium tiers, with EFSA-aligned clean-label SKUs commanding shelf space premiums in German and British health food channels. Three-tier pricing structure across premium organic, standard reduced-calorie, and economy private-label levels stratifies around sweetener sourcing transparency and refrigeration compliance investment. Cost compression in the standard tier is intensifying as contract manufacturers absorb EU F-Gas Regulation retrofit obligations. Workplace cafeteria procurement programs show least price sensitivity due to wellness subsidy structures, while secondary European city distributors face acute margin pressure from last-mile cold-chain gaps.
Supply Chain Analysis
EU F-Gas Regulation phase-down schedules function as de facto export controls on refrigeration equipment and servicing capacity, constraining cold-chain expansion in emerging markets. Raw material flows draw from Chinese stevia processing, Thai coconut milk extraction, and Nordic oat enzymatic hydrolysis facilities. Single-source vulnerability clusters in Jiangsu sweetener qualification create 6-12 month onboarding delays when switching suppliers. Distribution runs through centralized German distribution centers optimized for refrigeration asset utilization, with direct-to-subscription models bypassing traditional supermarket slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low calorie rice pudding sits in early-cycle expansion as refrigerated dessert aisles in European health food shops and Indian modern trade channels widen addressable penetration. Wellness program enrollment and clean-label reformulation velocity provide structural tailwinds for specialized entrants.
For Market Incumbents: Harden refrigerated set control through exclusive co-packer capacity reservations in Poland and the Czech Republic, locking out emerging brands facing qualification backlogs. Deepen EFSA-aligned certification investment to defend premium positioning against private-label encroachment in British and Scandinavian markets. Vertical integration into oat milk enzymatic processing secures texture parity advantages as plant-based formulations displace dairy bases. For New Entrants and Emerging Players: Direct-to-subscription models in Greater Boston and Pacific Northwest metro areas represent the most penetrable entry point, bypassing Kraft Foods and Royal's supermarket slotting dominance. Indian urban premium retail in Mumbai and Bangalore offers white-space expansion as FSSAI-aligned clean-label positioning opens modern trade channels. Cold-chain logistics partnerships with compliance-engineering specialists enable recurring delivery without retail intermediary markup. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors asset-light brands with established co-packing networks and EFSA certification pathways already cleared. Long-term viability hinges on formulation science capabilities in protein-stabilized plant-based emulsions, where food technologist scarcity extends competitive moats. Acquisition targets should demonstrate direct health food shop relationships in London and Berlin clusters. Watch for stevia supply qualification delays as an inflection indicator for input cost volatility and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | EFSA-aligned additive transparency opens placement in Scandinavian health food channels. |
| Co-Packer Network Expansion | Polish and Czech facility qualification bypasses 6-12 month onboarding delays for new entrants. |
| Direct-to-Subscription Launch | Cold-chain logistics partnerships enable recurring delivery without supermarket slotting fees. |
| Biodegradable Packaging Transition | Cellulose-based barrier coatings align with EU Green Deal sustainability mandates. |
| Wellness Program Partnership | Corporate cafeteria procurement subsidies create institutional volume anchors. |
Research Methodology
Cross-validation between primary interviews with dessert category buyers, food technologists, and cold-chain logistics operators anchors the qualitative findings against secondary validation. Regulatory affairs specialists at EFSA and FDA provide compliance pathway intelligence, while co-packer facility managers detail qualification timeline constraints. Secondary sources include EU F-Gas Regulation implementation filings, EFSA clean-label guidance documents, and refrigerated retail audit data from Nielsen and Circana. Bottom-up SKU-level modeling triangulates against top-down category expenditure estimates.
Calibration against historical adoption curves in plant-based dairy alternatives and functional dessert categories refines projection parameters across the analysis window. Segmentation dimensions span formulation chemistry, distribution channel refrigeration infrastructure, customer health objective severity, and packaging thermal performance. CAGRs derive from regression analysis of clean-label penetration rates and wellness program enrollment trajectories. Oat milk enzymatic processing yield improvements and stevia supply concentration indices serve as industry-specific forecast inputs.
Practitioners should monitor EFSA sweetener approval pathway shifts and EU F-Gas Regulation phase-down acceleration for early signals of compliance cost recalibration. Forecasts reflect assumptions on clean-label shelf-life tradeoff resolution and cold-chain density expansion in secondary European cities. Material shifts in stevia leaf processing capacity concentration or enzymatic hydrolysis technology licensing terms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Chocolate Filling Market
Processed Foods
Pea Processed Ingredients Market
Processed Foods
Tomato Puree Market
Processed Foods
Asia-Pacific Food Spread Market
Processed Foods
United States Processed Meat Market
Processed Foods
Low Fat Soups Market
Processed Foods
Fast-Food Reusable Market
Processed Foods
Broth Market
Processed Foods
Processed Peanut Market
Processed Foods
Potato Soup Market
Processed Foods
Processed Cashew Market
Processed Foods
Egg White Cubes Market
Processed Foods
Spray Cheese Market
Processed Foods
US Tomato Paste Market
Processed Foods
North America Ice Cream Market
Processed Foods
Ready to Cook Market