
 Low Fat Vegetable Soups Market | 2026-2036
Low Fat Vegetable Soups Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Vegetable Soups Market Analytics
European organic vegetable processors is shifting sourcing toward regional contract farms to secure traceable low-fat bases. Campbell Soup Company leverages its North American canning infrastructure to sustain volume leadership in broth-based formats. Progresso competes through diversified chunky and pureed lines across mainstream retail channels. Amy's Kitchen specializes in organic ingredient positioning that anchors premium shelf placement in health stores.
Low fat vegetable soups are heat-processed, shelf-stable preparations containing reduced lipid content, typically achieved through minimal oil emulsification and vegetable-puree bodying agents rather than cream or butterfat enrichment. These products serve commercial and retail buyers seeking convenient, nutrient-dense meal options aligned with cardiovascular wellness protocols. Broth-based formats dominate volume due to lower production complexity and extended ambient stability, while creamy variants command margin premiums through modified starch and legume-base emulsion technologies. Organic ingredient type positioning captures the fastest-growing demand pool as clean-label certification becomes a non-negotiable filter in specialty shops and premium supermarket aisles.
The FDA governs sodium disclosure and health claim substantiation for US-manufactured soups, while the EFSA and EU Green Deal frameworks press European producers toward carbon-accountable sourcing and reduced-packaging formats. These regulatory layers elevate compliance costs for import-dependent brands but simultaneously create protected market space for domestic reformulators with certified supply chains. Stakeholders must monitor evolving front-of-pack labeling mandates and decide whether to absorb certification overhead or cede positioning to established clean-label incumbents.
Market Dynamics
Clean-label certification requirements are compressing margins for reformulators while simultaneously erecting entry barriers that protect incumbent positions in premium retail channels. The FDA's updated Nutrition Facts mandates and parallel EFSA front-of-pack labeling frameworks force simultaneous sodium reduction and transparency investments.
Growth Catalysts
- Cardiovascular wellness protocols:Hospital and corporate cafeteria procurement teams now mandate low-sodium, low-fat options in contracted meal programs, pulling shelf-stable vegetable soups into institutional foodservice.
- EU Green Deal carbon-accountability:European producers with certified regional supply chains gain preferential listing in supermarket sustainability tiers, accelerating investment in traceable contract farming.
- Retort pouch technology:Flexible packaging formats reduce shipping weight and enable microwave-ready convenience, attracting urban millennial households in Japan and Germany.
Market Restraints
- Organic vegetable input volatility:Weather-driven yield fluctuations in Mediterranean and California growing regions create margin compression for clean-label formulators locked into fixed-price retail contracts.
- Canning infrastructure concentration:North American thermal processing capacity remains controlled by a handful of legacy operators, limiting new entrant scale-up options.
- Sodium reduction technical floor:Below 480mg per serving, flavor degradation accelerates without potassium chloride or yeast extract masking systems, constraining reformulation latitude.
Strategic Opportunities
- Direct-to-subscription channels:Meal-kit platforms and health-focused subscription boxes in the United States bypass slotting fee barriers while capturing recurring revenue from wellness-seeking households.
- Regenerative agriculture certification:USDA Organic plus Soil Health Institute verification commands 15-20% shelf price premiums in specialty retail, creating protected positioning.
- Functional ingredient convergence:Prebiotic fiber fortification combined with plant-protein enrichment targets digestive health and satiety claims simultaneously, opening new benefit-positioned SKUs.
Industry Challenges
- Clean-label formulation expertise scarcity:Food scientists capable of delivering sodium reduction without artificial flavor systems command premium compensation, constraining R&D team expansion.
- Dual certification timeline compression:Simultaneous USDA Organic and Non-GMO Project verification requires 18-24 month supply chain requalification, delaying new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Vegetable Soups Market |
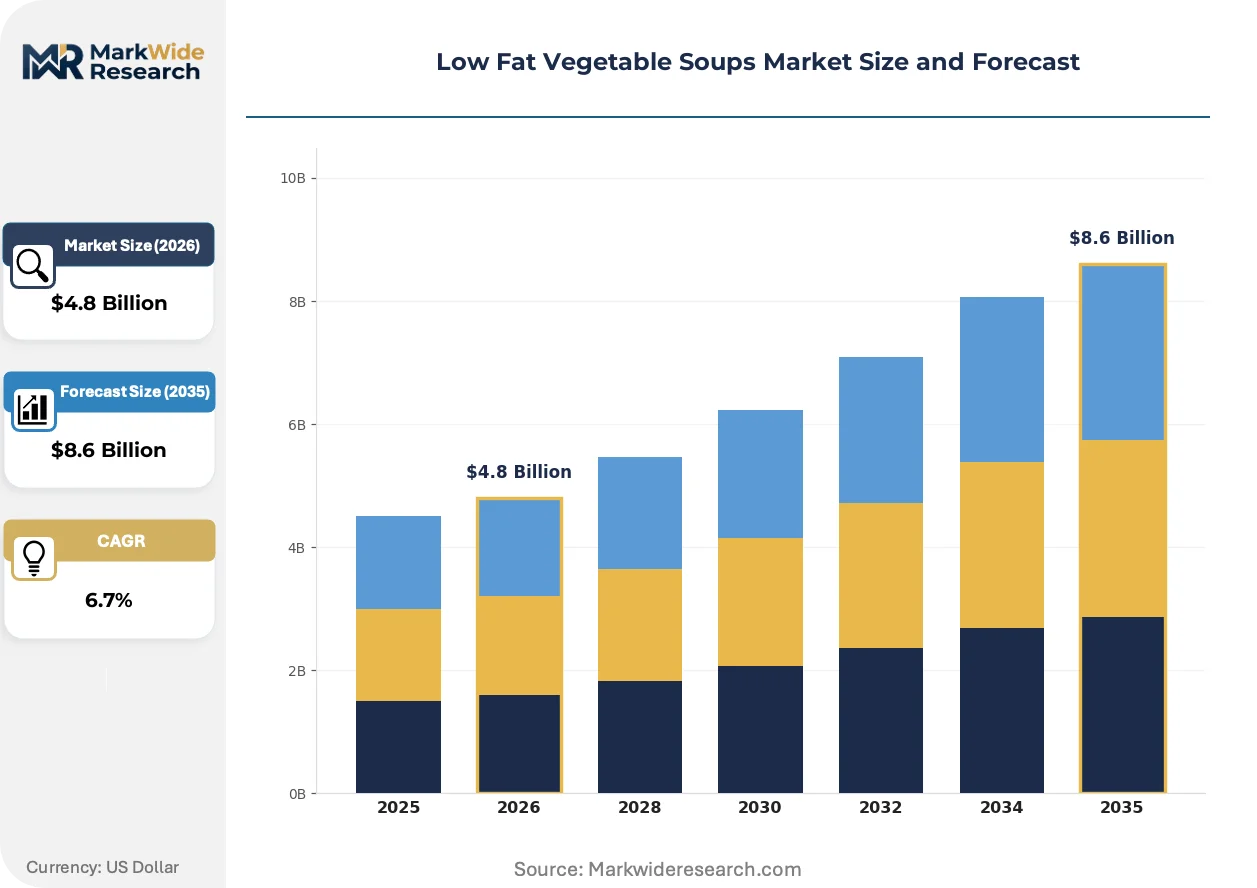
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creamy, Chunky, Broth-based, Pureed Packaging Type: Canned, Tetra Pack, Glass Jar, Pouch Ingredient Type: Organic, Non-GMO, Plant-based, Gluten-free Distribution Channel: Supermarkets, Online, Health Stores, Specialty Shops |
| Companies Covered | Campbell Soup Company, Progresso, Amy's Kitchen, General Mills, The Hain Celestial Group, Del Monte Foods, Rao's Specialty Foods, Pacific Foods, Dr. McDougall's Right Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Vegetable Soups Market Evolving Landscape
Reformulation priorities are pivoting from fat reduction alone to integrated clean-label architectures that satisfy multiple simultaneous certification requirements. This shift demands new processing partnerships and ingredient sourcing strategies.
High-pressure processing (HPP) is overtaking traditional retort sterilization for refrigerated soup lines, preserving volatile aromatic compounds and vibrant color that heat degradation destroys. Premium supermarket buyers in Germany and Japan now specify HPP for their private-label vegetable soup programs. The technology is overtaking thermal processing in the chilled premium segment, compressing shelf-life extension economics for conventional canners.
EFSA's evolving front-of-pack Nutri-Score algorithm recalibrations are penalizing sodium density more severely, forcing European reformulators to accelerate potassium-based salt replacer adoption. The framework's 2024 recalibration compresses permissible sodium thresholds for B-grade classification. Mediterranean producers with existing low-sodium legume-base formulations gain immediate competitive advantage in French and Spanish retail.
Urban millennial households are consolidating weekly grocery trips into fewer, larger basket purchases through delivery platforms, shifting soup discovery from in-aisle browsing to algorithmic recommendation. This pattern concentrates trial volume behind paid search placement and subscription bundling rather than end-cap displays. The United States and United Kingdom demonstrate the most pronounced channel migration, with direct-to-consumer brands capturing disproportionate share of new household penetration.
Low Fat Vegetable Soups Market Segmentation
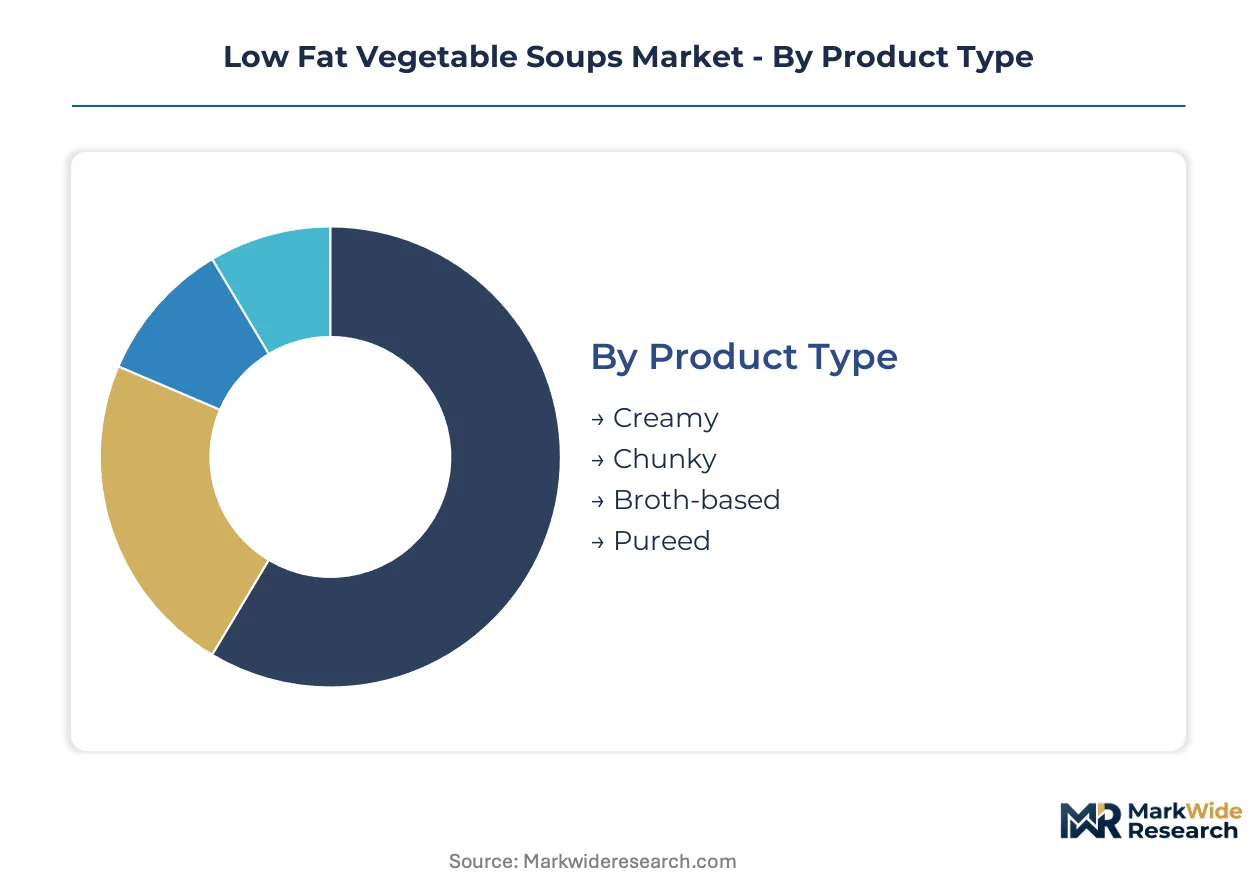
Segmentation in low fat vegetable soups reveals how formulation choices, packaging formats, and certification tiers create distinct competitive battlegrounds. Each dimension carries different margin structures and regulatory exposure that reshape where capital flows.
Product Type:
Buyers in this category separate by texture preference and preparation convenience, with institutional procurement teams favoring formats that hold stability through extended holding periods.
- Broth-based:Clear, reduced-fat preparations rely on vegetable stock foundations with minimal emulsification. Hospital and corporate cafeteria contracts in the United States pull volume through cardiovascular wellness procurement mandates.
- Creamy:Modified starch and legume-base emulsion technologies replicate mouthfeel without butterfat enrichment. German and Japanese premium retail channels command margin premiums for clean-label creamy variants.
- Chunky:Diced vegetable inclusions deliver visual authenticity and satiety cues.
- Pureed:Smooth, uniform textures serve pediatric and geriatric nutrition applications.
Volume sits with Broth-based; growth tilts toward Creamy.
Packaging Type:
Format selection tracks logistics economics and microwave-ready convenience demands among urban millennial households.
- Canned:Thermal-processed steel and aluminum containers deliver extended ambient stability with established recycling infrastructure. Campbell Soup Company's North American canning network locks in volume leadership through scale economies.
- Pouch:Flexible retort formats cut shipping weight and enable single-serve microwave preparation. Japanese convenience retail and German urban delivery platforms are accelerating pouch adoption fastest.
- Tetra Pack:Aseptic carton systems suit broth-based lines with shorter distribution cycles.
- Glass Jar:Premium positioning in specialty shops leverages visual transparency and perceived purity.
Volume concentrates in Canned; Pouch climbs the fastest on convenience premiums.
Ingredient Type:
Certification tiers create price stratification that separates mass retail from protected specialty positioning.
- Organic:USDA Organic and EU Organic certification requires traceable supply chains with 18-24 month requalification timelines. Amy's Kitchen anchors premium shelf placement in United States health stores through organic ingredient positioning.
- Non-GMO:Non-GMO Project verification runs parallel to organic in North American clean-label filtering.
- Plant-based:Vegan positioning captures flexitarian households beyond strict dietary adherents.
- Gluten-free:Celiac-safe protocols open access to medical nutrition and wellness segments.
Organic commands the steepest expansion trajectory; Plant-based broadens addressable demand fastest.
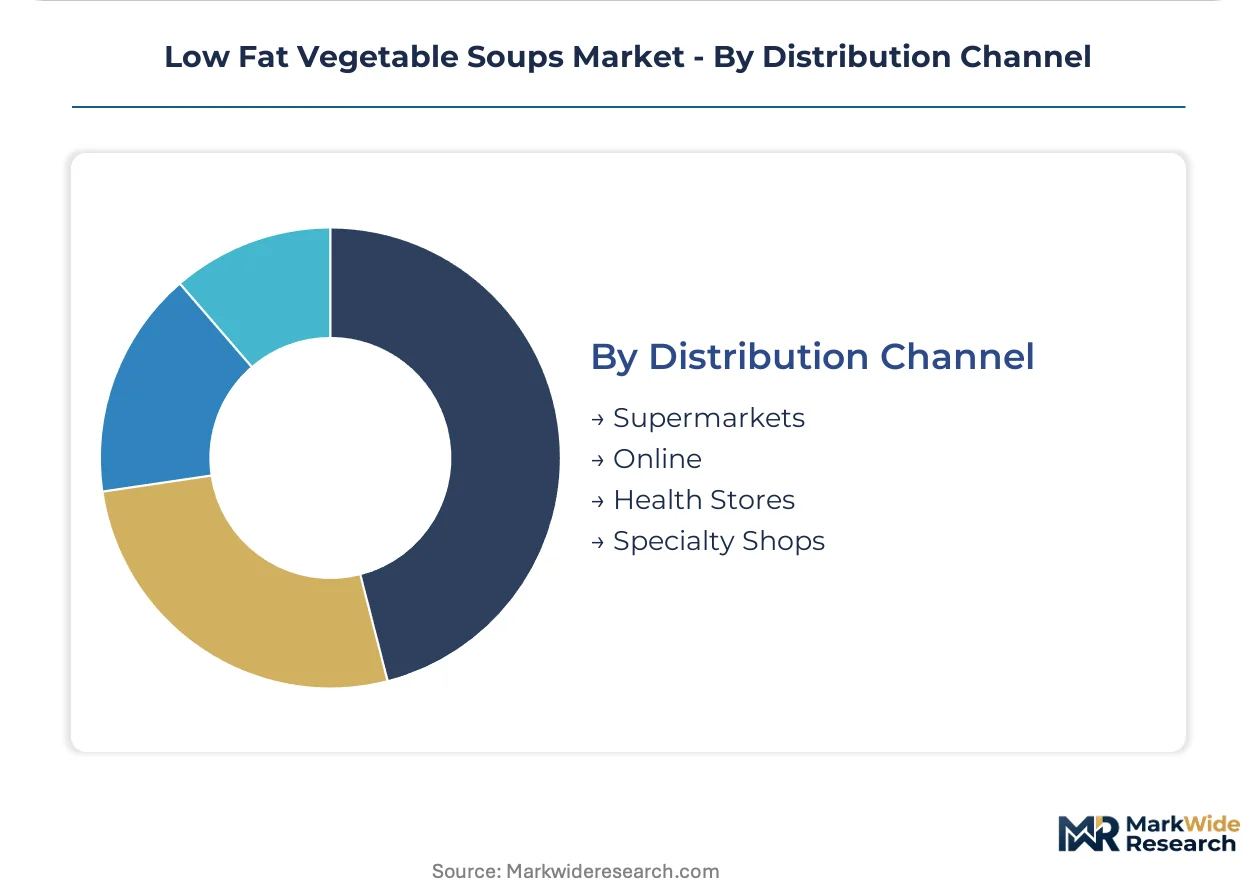
Distribution Channel:
Channel selection determines discovery mechanics and slotting fee exposure, with algorithmic recommendation displacing in-aisle browsing.
- Supermarkets:End-cap and center-store placement drives impulse trial through visual merchandising. Progresso competes across mainstream United States retail through diversified line presence.
- Online:Subscription bundling and paid search placement concentrate trial volume behind platform algorithms. Direct-to-consumer brands in the United States and United Kingdom capture disproportionate new household penetration.
- Health Stores:Clean-label curation creates protected positioning for certified organic entrants.
- Specialty Shops:Regional European organic vegetable processors secure traceable low-fat bases through contract farm networks.
Supermarkets hold volume; Online gains share fastest on subscription economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley vegetable production and Mediterranean contract farming networks anchor the geographic concentration of low-fat soup ingredient supply chains. Procurement teams in three national markets pull differentiated volume through distinct regulatory and retail channel configurations.
United States
Hospital cafeteria wellness mandates and corporate foodservice contracts drive institutional procurement of low-sodium broth-based formats. The FDA's updated Nutrition Facts label requirements force simultaneous sodium reduction and transparency investments. Chicago and New York metropolitan areas concentrate retail distribution infrastructure for shelf-stable soup brands.
Germany
Urban millennial households favor microwave-ready retort pouch formats through delivery platform consolidation. EFSA's front-of-pack Nutri-Score recalibrations penalize sodium density, accelerating potassium-based salt replacer adoption. Bavaria's organic vegetable processors secure traceable supply chains through regional contract farm networks.
Japan
Convenience retail channels and single-serve consumption patterns sustain demand for ambient-stable vegetable preparations. METI guidelines on food labeling and health claim substantiation shape formulation priorities. Tokyo and Osaka metropolitan corridors concentrate premium retail placement for clean-label soup variants.
United Kingdom
Algorithmic recommendation engines on grocery delivery platforms displace in-aisle discovery for soup trial purchases. The Food Standards Agency's evolving front-of-pack labeling frameworks align with EU Green Deal carbon-accountability pressures. London's health store clusters create protected positioning for certified organic entrants.
Low Fat Vegetable Soups Market Competitive Landscape
Global majors compete with regional champions across canning infrastructure, clean-label certification, and direct-to-consumer channel access. The vendor base separates into three tiers: legacy thermal processors with captive North American capacity, organic specialists with 18-24 month supply chain requalification timelines, and direct-to-subscription entrants bypassing supermarket slotting fees. Strategic moves concentrate on M&A for certified supply chain access and portfolio diversification into functional ingredient fortification.
Within the legacy processor tier, Campbell Soup Company and Progresso occupy positions sustained by scale advantages in broth-based format production. Amy's Kitchen anchors the organic specialist archetype through premium health store placement. These three names exemplify how certification overhead and channel access separate competitive positions in an increasingly regulated formulation environment.
| Leading Market Players |
|---|
| Campbell Soup Company |
| Progresso |
| Amy's Kitchen |
| General Mills |
| The Hain Celestial Group |
| Del Monte Foods |
| Rao's Specialty Foods |
| Pacific Foods |
| Dr. McDougall's Right Foods |
| Others |
Value Network & Pricing Analysis
Hospital and corporate cafeteria procurement teams concentrate demand for low-sodium broth-based formats, locking contract pricing structures around volume-based tiered agreements with annual renegotiation cycles. This buyer concentration forces suppliers to absorb organic vegetable input volatility while maintaining fixed-price commitments to institutional accounts.
Pricing Analysis
Service-level bundling separates premium organic positioning from economy-tier commodity contracts, with clean-label certification and regenerative agriculture verification commanding shelf price premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient certification grade and packaging format convenience. Pricing pressure stems from weather-driven yield fluctuations in Mediterranean and California growing regions compressing margins for fixed-contract suppliers. Institutional procurement teams exhibit highest price sensitivity due to mandated budget caps, while health store channels tolerate premium positioning for certified organic variants.
Supply Chain Analysis
Reverse-logistics flows for retort pouch and Tetra Pack formats remain underdeveloped, with limited recycling infrastructure for flexible packaging creating end-of-life cost externalities. Primary vegetable sourcing concentrates in the United States, Spain, and Italy, with California's Central Valley and Mediterranean contract farms anchoring low-fat base supply. Processing draws from tomato, carrot, and legume inputs with seasonal availability constraints. Single-source vulnerability in North American thermal processing capacity, controlled by legacy canning operators, limits new entrant scale-up options. Distribution runs through supermarket center-store placement, direct-to-subscription platforms, and health store specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around clean-label certification overhead that weaker players cannot sustain, with dual USDA Organic and Non-GMO Project timelines forcing 18-24 month supply chain requalification that eliminates undercapitalized reformulators.
For Market Incumbents: Anchor market position through captive supply chain investments in regional contract farming networks that secure traceable organic vegetable inputs. Acquire potassium-based salt replacer formulation capabilities to accelerate sodium reduction without flavor degradation. Defend against direct-to-subscription entrants by controlling health store shelf placement through exclusive distribution agreements with premium retail clusters. For New Entrants and Emerging Players: The mid-tier price-point gap between Amy's Kitchen premium positioning and mainstream private-label economy offers white-space opportunity for certified organic entrants with streamlined supply chains. Target algorithmic recommendation engines on grocery delivery platforms in the United States and United Kingdom where discovery mechanics favor new brands. Pursue regenerative agriculture certification as differentiation lever to command specialty retail shelf price premiums. For Investors and Strategic Acquirers: The window for entry favors organic specialists with established 18-24 month supply chain requalification timelines and existing health store distribution relationships. Long-term viability hinges on portfolio diversification into functional ingredient fortification targeting digestive health claims. Monitor EFSA Nutri-Score algorithm recalibrations and FDA sodium disclosure mandates as regulatory inflection indicators that will accelerate consolidation toward compliant formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Certification | USDA Organic plus Soil Health Institute verification commands 15-20% shelf price premiums in specialty retail channels. |
| Retort Pouch Technology Adoption | Flexible packaging reduces shipping weight and enables microwave-ready convenience for urban millennial households in Japan and Germany. |
| Potassium-Based Salt Replacer Integration | EFSA Nutri-Score recalibrations penalizing sodium density accelerate reformulation toward B-grade classification compliance. |
| Direct-to-Subscription Channel Launch | Meal-kit platforms and health-focused subscription boxes bypass supermarket slotting fee barriers while capturing recurring revenue. |
| High-Pressure Processing Investment | HPP preserves volatile aromatic compounds and vibrant color that heat degradation destroys for premium private-label programs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with food scientists, category buyers at health stores, procurement managers at hospital systems, and supply planners at organic vegetable processors. FDA sodium disclosure guidelines, EFSA front-of-pack labeling frameworks, and EU Green Deal carbon-accountability requirements provided regulatory validation. Nielsen retail audit data, organic certification databases, and import-export records supplied demand-side calibration. Bottom-up volume modeling and top-down value reconciliation triangulated market sizing across the analysis window.
Data-stream reconciliation merged shipment volumes, retail velocity metrics, and production capacity utilization into unified forecasting architecture. Segmentation dimensions modeled include product type, packaging format, ingredient certification tier, and distribution channel complexity. CAGRs were derived from regression analysis against macroeconomic indicators and consumer health expenditure patterns. Organic vegetable input cost indices and retort packaging material price trajectories informed margin compression assumptions throughout the projection horizon.
Inputs from regulatory agencies and trade associations were available through the study window; gaps in real-time organic vegetable yield data and private-label contract terms introduce uncertainty bands around volume forecasts. Practitioners should monitor FDA sodium threshold adjustments, EFSA Nutri-Score algorithm updates, and weather patterns in Mediterranean growing regions for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Ice Cream Parlor Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Processed Cashew Market
Processed Foods
Apple Butter Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
Low Fat Chicken Soup Market
Processed Foods
North America Soup Market
Processed Foods
Yogurt Dip Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Processed Peanut Market
Processed Foods
Instant Cooking Food Market
Processed Foods
United States Food Spread Market
Processed Foods
Shelf-Stable Soup Market
Processed Foods
Low Calorie Rice Pudding Market
Processed Foods
United States Processed Meat Market
Processed Foods
Noodles Market