
 Global Take Out Fried Chicken Market | 2026-2036
Global Take Out Fried Chicken Market Size, Share, and Industry Trends Forecast 2026-2036
Global Take Out Fried Chicken Market Outlook
Young professionals ordering solo meals through mobile apps is unwinding the traditional family-bucket model that long defined fried chicken purchasing. Wingstop Inc leverages its digital-first infrastructure to capture off-premise occasions, while Chick-fil-A Inc sustains exceptional throughput via drive-thru lane design and kitchen automation. GENESIS BBQ anchors its expansion in Asian metropolitan corridors with localized spice profiles that compete against American incumbents.
Take out fried chicken comprises battered and pressure-fried poultry pieces, typically held at temperatures above 140°F through insulated packaging to preserve crust integrity and food safety during transit. The primary commercial purpose centers on delivering convenience-oriented protein meals to off-premise consumers within thirty minutes of preparation. Tenders and hot wings dominate volume in North American markets where boneless formats suit commuter consumption patterns. Online delivery channels capture the fastest expansion as aggregator platforms restructure last-mile economics, though supermarkets retain margin strength in pre-fried retail formats across European cities.
The FDA governs poultry processing standards and pathogen controls in the United States, while the EU Green Deal and REACH frameworks reshape packaging material specifications across European operations. EFSA guidelines on acrylamide in fried foods are tightening oil temperature protocols and prompting equipment upgrades. Stakeholders must monitor how dual carbon goals in China and emerging state-level packaging bans in the United States will recalibrate supply chain costs and format innovation priorities.
Market Dynamics
Aggregator platforms are compressing delivery economics while EU packaging mandates force simultaneous capital redeployment toward fiber-based containers, creating a dual squeeze on operator margins.
Growth Catalysts
- Platform consolidation:Delivery aggregators in the United States are standardizing last-mile logistics, reducing per-order fulfillment costs for independent operators.
- REACH compliance:European coating innovations for oil-barrier paperboard are unlocking compliant packaging alternatives ahead of enforcement deadlines.
- Drive-thru automation:Kitchen robotics and predictive queuing systems in North American suburban corridors are lifting throughput per labor hour.
Market Restraints
- Palm oil volatility:Frying medium costs swing with Malaysian and Indonesian export policy, compressing gross margins on value-menu items.
- Equipment import dependence:Pressure-fryer manufacturing concentrates in East Asian foundries, exposing operators to shipping rate spikes and tariff uncertainty.
- Acrylamide thresholds:EFSA guidelines on Maillard reaction byproducts are forcing oil temperature reductions that extend cook cycles and reduce hourly output.
Strategic Opportunities
- Indian metropolitan corridors:Tier-1 cities show underpenetrated quick-service density relative to protein consumption growth, offering first-mover positioning.
- Ghost kitchen convergence:Dark kitchen infrastructure and cloud-based order management are collapsing real estate requirements for market entry.
- Dual carbon alignment:China's national emissions targets are accelerating subsidies for electrically heated frying equipment, favoring early equipment upgrades.
Industry Challenges
- Food safety certification velocity:HACCP-to-FSMA transition timelines in multi-unit operations are stretching compliance resources across divergent national standards.
- Legacy POS integration:Third-party platform APIs frequently conflict with incumbent kitchen display systems, requiring middleware development or full-stack replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Take Out Fried Chicken Market |
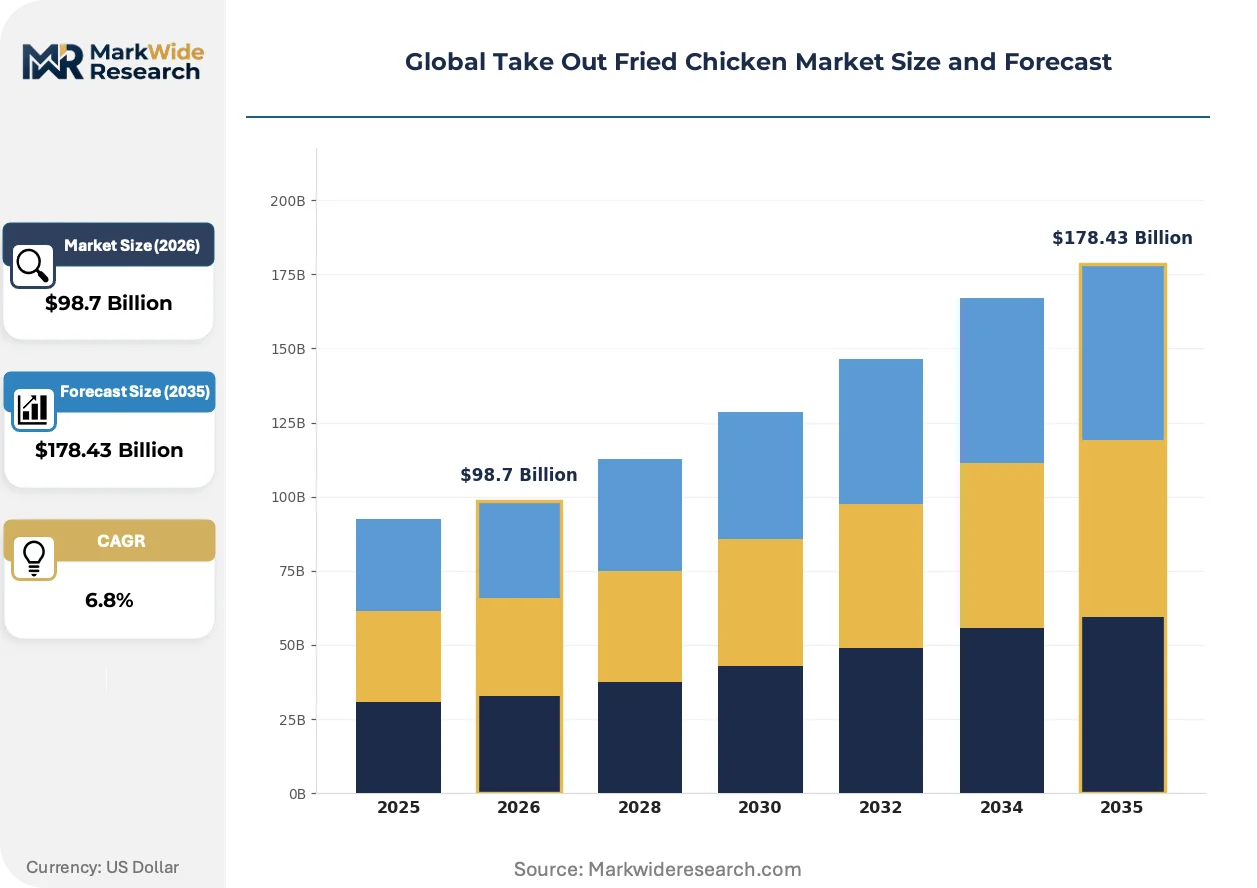
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Wings, Drumsticks, Tenders, Whole Chicken Distribution Channel: Online Delivery, Restaurants, Food Trucks, Supermarkets Customer Type: Families, Students, Professionals, Tourists Flavor Profile: Spicy, Barbecue, Honey Garlic, Original |
| Companies Covered | Wingstop Inc, Bojangles Restaurants Inc, Yum! Brands Inc, GENESIS BBQ, Charoen Pokphand Group Co. Ltd, Chick-fil-A Inc, Raising Cane's Restaurants LLC, Zaxbys SPE Franchisor LLC, Restaurant Brands International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Take Out Fried Chicken Market Strategic Shifts
Active packaging engineering and regulatory chemistry are rewriting material specifications while consumption fragmentation demands format innovation beyond traditional bucket sizing.
Pressure-activated venting films in insulated bags are supplanting conventional polystyrene clamshells for hot-hold transport. Wing-focused chains in the United States are adopting these laminates at scale. The shift is compressing packaging weight and enabling curbside-ready branding without thermal performance loss.
EU Green Deal packaging mandates are phasing out single-use plastics for ready-to-eat foods by 2030. Operators across Germany, France, and the Netherlands are trialing molded-fiber alternatives with proprietary oil-resistant coatings. The transition is most acute in urban delivery zones where municipal enforcement precedes federal deadlines.
Solo meal occasions are fragmenting traditional family-format purchasing into snack-sized and individual-portion orders. Mobile-first consumers in South Korea and Japan are substituting combo meals with à la carte tender and wing selections. This rotation is visible in Tokyo and Seoul where convenience-store fried chicken now rivals dedicated quick-service volume.
Global Take Out Fried Chicken Market Segmentation
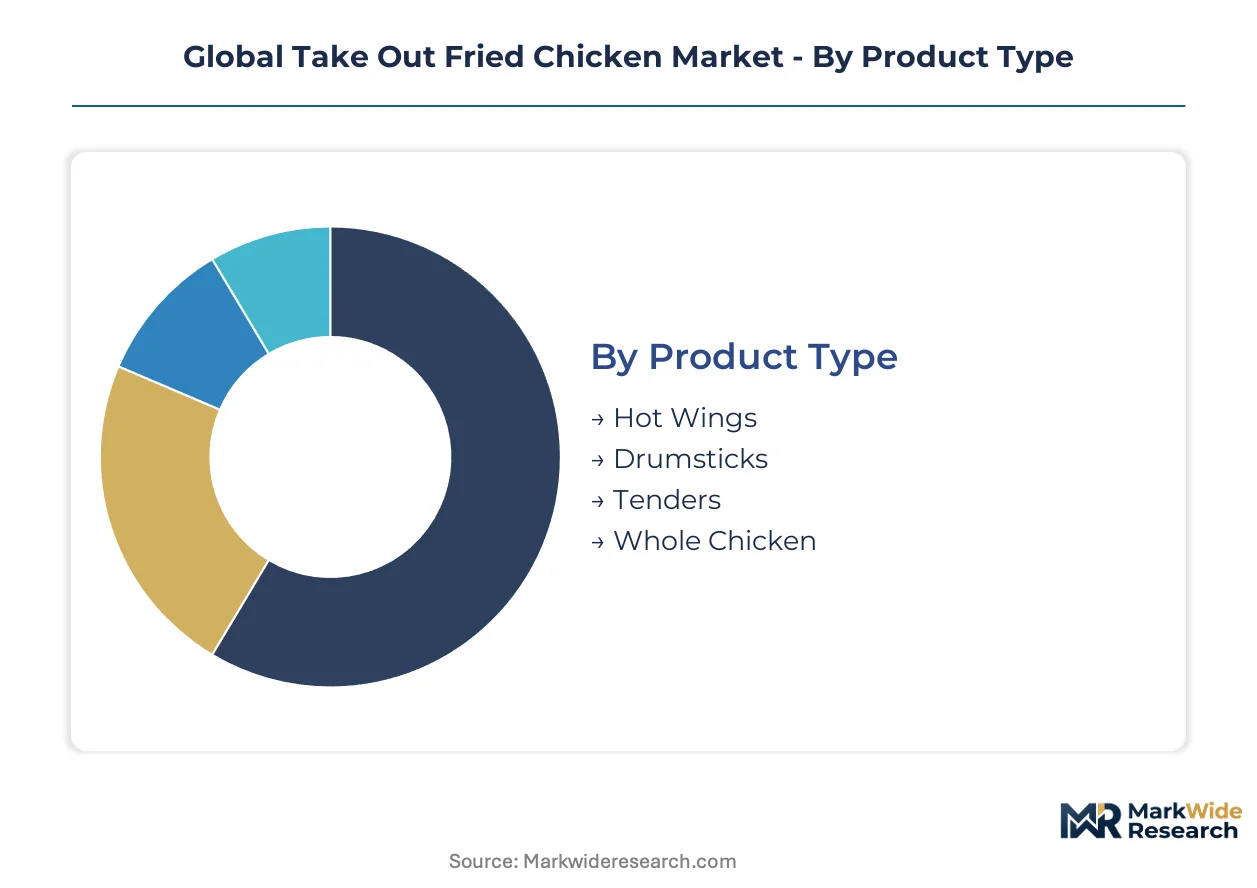
Product formats and purchasing contexts fragment the market into distinct operational requirements. Each segment demands specialized packaging, holding equipment, and channel-specific preparation workflows.
Product Type:
Channel mix varies sharply by cut geometry—boneless formats dominate mobile-aggregator flows while bone-in pieces concentrate in drive-thru and supermarket channels.
- Tenders:Strips of pectoralis minor muscle, pressure-fried in standardized 2-3 ounce portions. Demand concentrates in United States commuter corridors where one-handed consumption suits vehicle-based eating. Boneless construction reduces per-unit holding complexity for ghost kitchen operators.
- Hot Wings:Sectioned wingettes and drumettes, typically sauced post-fry to preserve crust texture. South Korean and Japanese aggregator platforms show steepest expansion for this format, driven by late-night solo ordering occasions.
- Drumsticks:Single-bone thigh cuts with higher meat-to-batter ratio. European supermarket chilled cases favor this format for home-reheating applications.
- Whole Chicken:Spatchcocked or quartered birds for family-format sharing. United States drive-thru chains retain volume leadership here, though the format is losing share to portioned alternatives.
By volume, Tenders leads. By growth pace, Hot Wings is climbing the fastest.
Distribution Channel:
Margin structures diverge by who owns the customer relationship—direct channels capture lifetime value while intermediaries trade margin for reach.
- Online Delivery:Aggregator-mediated transactions with platform fees of 15-30 percent. Ghost kitchen infrastructure in United States, United Kingdom, and South Korean metropolitan corridors is collapsing real estate requirements for this channel.
- Restaurants:Branded quick-service locations with dedicated fry lines and holding cabinets. Drive-thru automation in United States suburban markets is lifting throughput per labor hour through predictive queuing systems.
- Supermarkets:Pre-fried retail formats in chilled or hot-hold deli sections. German and French operators face EU Green Deal packaging mandates that are accelerating fiber-based container transitions.
- Food Trucks:Mobile fryer units serving event and office-park clusters. Regulatory variance across United States municipal jurisdictions creates licensing complexity for multi-city operators.
Online Delivery captures the steepest expansion trajectory. Restaurants retain the highest absolute transaction volumes.
Customer Type:
Purchasing frequency and occasion timing split cleanly across life-stage and mobility patterns.
- Professionals:Solo weekday lunch and dinner occasions, typically ordered through mobile apps. Tokyo and Seoul show highest per-capita frequency for this segment.
- Families:Weekend bucket-format purchasing for shared consumption. United States drive-thru design optimizes for multi-item order complexity and child-meal bundling.
- Students:Price-sensitive demand concentrated near university corridors. Indian Tier-1 cities show underpenetrated density relative to enrollment growth.
- Tourists:Impulse purchases at transit hubs and entertainment districts. Airport and railway station locations in Japan and United Kingdom command premium pricing.
Families generate the highest per-transaction value. Professionals show the fastest ordering frequency growth.
Flavor Profile:
Regional preference maps create localization requirements for multi-national operators.
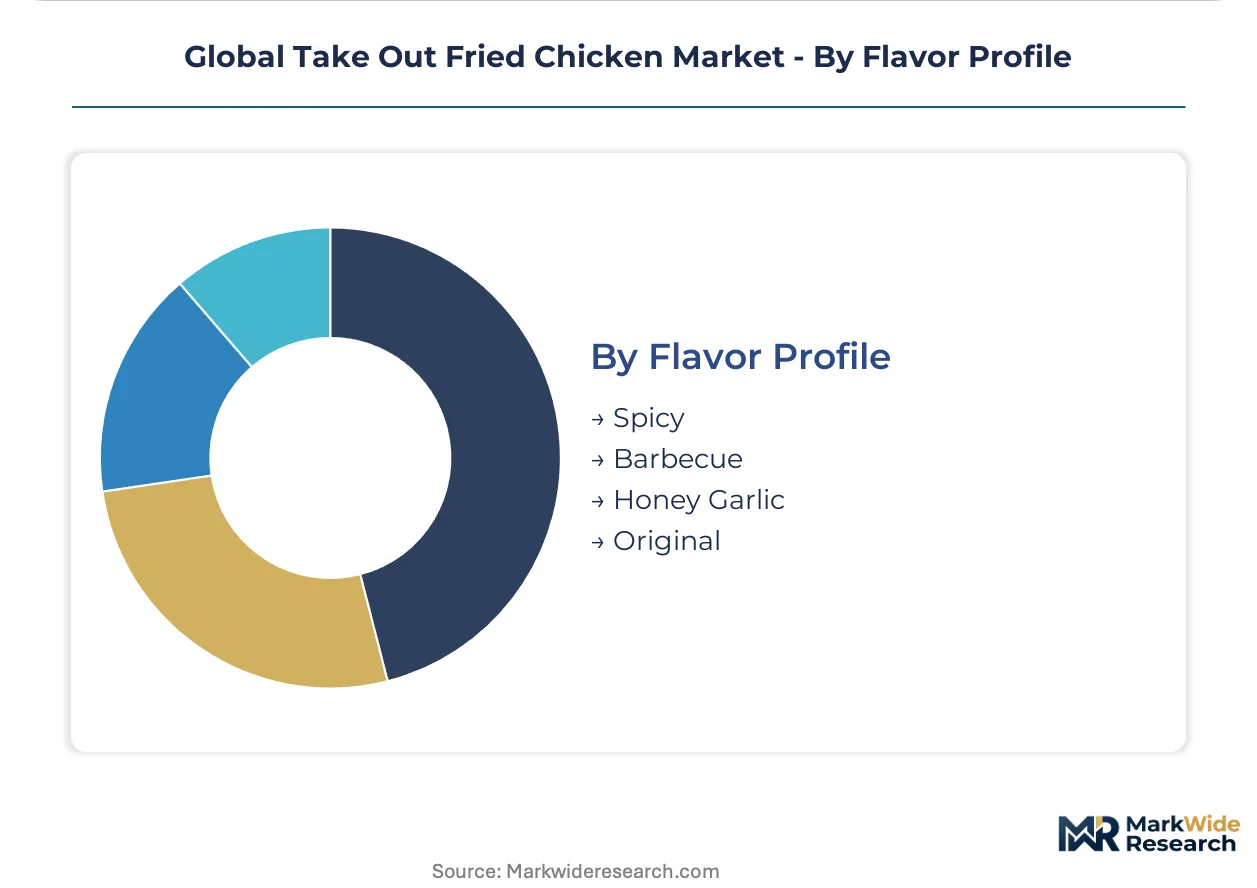
- Spicy:Capsicum-based heat levels calibrated to local tolerance thresholds. South Korean gochugaru and Sichuan mala variants command loyalty in their respective home markets.
- Original:Salt-pepper batter without post-fry saucing. United States and United Kingdom baseline preference supports manufacturing standardization.
- Barbecue:Tomato-molasses or vinegar-based coatings applied post-fry. Popular in United States southern states and German urban markets.
- Honey Garlic:Sweet-savory glaze popular in Canadian and Australian markets. Higher sugar content complicates holding temperature protocols.
Original dominates manufacturing runs. Spicy is expanding most quickly across new market entries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pressure-fryer manufacturing concentrates in East Asian foundries, yet consumption patterns diverge sharply across regulatory environments. Drive-thru infrastructure density, aggregator platform maturity, and packaging compliance timelines create distinct operational profiles in each national market.
United States
Drive-thru lane design and kitchen automation sustain exceptional throughput in suburban corridors. FDA poultry processing standards govern pathogen controls while state-level packaging bans in California and New York accelerate fiber-based container transitions. Ghost kitchen density in Atlanta and Dallas-Fort Worth collapses real estate requirements for aggregator-mediated delivery.
South Korea
Late-night solo ordering through mobile apps fragments traditional family-bucket purchasing into snack-sized occasions. MFDS guidelines on fried food safety align with national dual carbon goals that subsidize electrically heated frying equipment. Seoul's convenience-store fried chicken volume now rivals dedicated quick-service chains in Gangnam and Hongdae districts.
Germany
Supermarket chilled deli sections retain margin strength in pre-fried retail formats across Berlin and Munich. EU Green Deal packaging mandates and REACH frameworks force simultaneous transitions to molded-fiber containers with proprietary oil-resistant coatings. Municipal enforcement in Hamburg and Frankfurt precedes federal deadlines for single-use plastic phaseout.
Japan
Commuter consumption patterns favor boneless tenders suited to one-handed vehicle-based eating. METI efficiency standards and EFSA-aligned acrylamide thresholds prompt oil temperature protocol adjustments. Tokyo and Osaka convenience-store chains capture professional lunch occasions through aggregator platform integration.
India
Tier-1 cities show underpenetrated quick-service density relative to protein consumption growth among student and professional segments. FSSAI food safety certifications and state-level municipal licensing create compliance complexity for multi-city operators. Bengaluru and Hyderabad corridors offer first-mover positioning for dark kitchen infrastructure deployment.
Global Take Out Fried Chicken Market Competitive Environment
Concentration sits with vertically integrated quick-service chains that control fry-line equipment, packaging procurement, and last-mile aggregator relationships. The vendor base spans three strategic tiers: global brand licensors with franchise density advantages, regional specialists with localized flavor profiles, and equipment-dependent dark kitchen operators. Competitive moves center on drive-thru automation deployment and fiber-based packaging transitions ahead of regulatory deadlines.
Among North American quick-service incumbents, Chick-fil-A Inc and Wingstop Inc exemplify divergent archetypes—one optimizing suburban drive-thru throughput, the other capturing digital-native off-premise occasions. GENESIS BBQ anchors the Asia-Pacific expansion vector with metropolitan corridor concentration. Yum! Brands Inc sits across multiple archetypes through portfolio diversification. Restaurant Brands International represents the multi-brand holding structure common among scale-driven competitors.
| Leading Market Players |
|---|
| Wingstop Inc |
| Bojangles Restaurants Inc |
| Yum! Brands Inc |
| GENESIS BBQ |
| Charoen Pokphand Group Co. Ltd |
| Chick-fil-A Inc |
| Raising Cane's Restaurants LLC |
| Zaxbys SPE Franchisor LLC |
| Restaurant Brands International |
| Others |
Value Chain & Pricing Dynamics
Sixty-day fryer equipment lead times from East Asian foundries concentrate procurement power among large multi-unit operators, compressing margin recovery options for independents facing palm oil volatility and REACH-compliant packaging cost premiums.
Pricing Analysis
EU Green Deal packaging mandates dictate the pricing tier structure across European operations, forcing three-tier pricing structure across premium fiber-based containers, standard coated paperboard, and economy polystyrene legacy formats still permitted in non-EU markets. Price differentiation rests on oil-barrier certification grade and volume scale, with municipal enforcement timelines in Hamburg and Frankfurt accelerating premium tier adoption. Cost compression in value-menu items is intensifying because Malaysian palm oil export policy swings feed directly into frying medium economics. Quick-service chains show least price sensitivity due to backward integration into fry-line equipment, while ghost kitchen operators and food trucks absorb full spot-market volatility.
Supply Chain Analysis
Just-in-time poultry sourcing dominates quick-service operations, though strategic stockpiling of palm oil and specialized frying fats has expanded among Tier-1 chains hedging against Indonesian export restrictions. Manufacturing concentration centers on China, South Korea, and Taiwan for pressure-fryer fabrication, while poultry processing draws from United States, Brazil, and Thailand feedstock hubs. Raw material dependencies span batter mix formulations, high-oleic frying oils, and insulated packaging laminates. Single-source vulnerability in East Asian foundry capacity exposes operators to shipping rate spikes. Distribution runs through aggregator platform networks, direct franchise logistics, and supermarket deli supply chains with divergent cold-chain requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Packaging-as-a-service models and predictive maintenance subscriptions for fry-line automation are expanding faster than equipment hardware sales, creating recurring revenue layers that reshape capital deployment calculations across the value chain.
For Market Incumbents: Secure fiber-based packaging supply agreements ahead of EU Green Deal enforcement deadlines in Germany and France. Lock in multi-year palm oil offtake contracts through Indonesian and Malaysian trading houses to buffer margin compression from export policy volatility. Vertical integration into molded-fiber container manufacturing offers defensive positioning against coating technology shortages.
For New Entrants and Emerging Players: HACCP-to-FSMA certification fast-tracks open first-mover positioning in Indian Tier-1 cities where quick-service density lags protein consumption growth among student corridors. Ghost kitchen infrastructure in Bengaluru and Hyderabad collapses real estate barriers. Lead with spicy flavor localization calibrated to Sichuan mala or gochugaru heat profiles that differentiate against American incumbents.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across dark kitchen and aggregator-dependent sub-segments as cloud-based order management displaces legacy POS infrastructure. Five-to-ten-year viability favors operators controlling fry-line equipment procurement and direct customer relationships over pure-platform intermediaries. Watch for inflection when electrically heated frying equipment subsidies under China's dual carbon goals accelerate equipment replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Drive-Thru Automation Deployment | Kitchen robotics and predictive queuing systems lift throughput per labor hour in United States suburban corridors. |
| Fiber-Based Packaging Transition | EU Green Deal mandates force molded-fiber adoption with proprietary oil-resistant coatings ahead of 2030 deadlines. |
| Aggregator Platform Integration | API harmonization with third-party delivery networks captures off-premise occasions in South Korean and Japanese markets. |
| Flavor Localization Programs | Regional spice calibrations for gochugaru and Sichuan mala profiles defend share against American brand incumbents. |
| Dual Carbon Equipment Upgrades | Electrically heated frying equipment subsidies under China's national emissions targets reduce fossil fuel dependency. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with quick-service franchise operations directors, ghost kitchen facility managers, aggregator platform supply chain leads, and poultry processing plant supervisors. Secondary validation drew from FDA poultry processing standards, EU Green Deal regulatory filings, EFSA acrylamide guideline updates, and customs trade data on pressure-fryer equipment imports. Bottom-up order volume estimates from aggregator platforms were triangulated against top-down protein consumption trends across metropolitan corridors.
Across the analysis window, the forecasting framework modeled volume and value trajectories through product type segmentation by cut geometry, distribution channel stratification by customer relationship ownership, and regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation of digital ordering penetration, packaging compliance cost curves, and automation adoption rates. Industry-specific inputs included fryer equipment replacement cycles, palm oil futures price bands, and municipal enforcement timelines for single-use plastic phaseouts.
Underlying assumptions cover sustained aggregator platform consolidation, stable Malaysian and Indonesian palm oil export policy, and incremental REACH compliance cost pass-through, with deviation risk concentrated in tariff exposure on East Asian equipment imports and state-level packaging ban acceleration in California and New York. Revision becomes warranted when electrically heated frying equipment subsidy thresholds or acrylamide regulatory limits cross enforcement boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Global Dried Processed Food Market
Processed Foods
Global Potato Flake Market
Processed Foods
Low Calorie Rice Pudding Market
Processed Foods
Processed Potatoes Market
Processed Foods
Spray Cheese Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Fermented Food and Drinks Market
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
India Spray Dried Food Market
Processed Foods
Block Margarine Market
Processed Foods
Fat Free Food Market
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
Global Malted Milk Market
Processed Foods
Instant Curry Market
Processed Foods
Fruit Processing Market
Processed Foods
Fresh Pasta Market