
 China Freeze-Dried Food Market | 2026-2036
China Freeze-Dried Food Market Size, Share, and Industry Trends Forecast 2026-2036
China Freeze-Dried Food Market Outlook
E-commerce platforms is reconfiguring how freeze-dried food reaches Chinese consumers, with live-streaming commerce and community group buying now commanding substantial volume flows. Zhengzhou Donsen Foods Co. Ltd leverages its central China manufacturing base to anchor supply for domestic e-commerce fulfillment. Shenzhen Lujia Fdfood Co., Ltd. competes through specialized fruit lyophilization that targets southern China's tropical ingredient sourcing. Lixing Group dominates bulk institutional contracts through backward integration into raw material procurement networks.
Freeze-dried food refers to products dehydrated through sublimation under vacuum at temperatures typically below −40°C, preserving cellular structure and enabling rapid reconstitution with water for nutritional retention near fresh equivalents. The process serves commercial purposes spanning military logistics, emergency stockpiling, and premium consumer convenience where shelf stability and weight reduction carry operational value. Fruits and vegetables retain the largest volume share as raw material abundance in China's agricultural belts supports cost-competitive processing, while meats command premium positioning due to higher protein density requirements and complex lyophilization parameters. The military end user segment exhibits the most concentrated procurement structure with multi-year supply agreements, whereas retail consumers fragment across online retail and specialty stores channels with divergent price sensitivity profiles.
SAMR food safety standards and GB national standards for dehydrated products govern manufacturing compliance, with MEE environmental regulations on energy-intensive vacuum processes adding cost layers to facility operations. China's dual carbon goals are pressuring processors to adopt renewable-powered lyophilization or face regional production caps in high-emission zones. Stakeholders must monitor how NMPA evolving nutritional labeling requirements and provincial clean-energy mandates will reshape capital allocation between equipment upgrades and geographic relocation.
Market Dynamics
Lyophilization technology upgrades across Shandong and Fujian provinces are compressing production cycles while SAMR food safety standards and GB national standards tighten compliance thresholds for vacuum dehydration equipment.
Growth Catalysts
- Dual carbon goals:MEE environmental regulations on energy-intensive vacuum processes are forcing renewable-powered equipment adoption, creating first-mover advantages for processors with solar-integrated facilities.
- Military procurement:National food security directives are expanding multi-year freeze-dried ration contracts, locking in volume commitments that stabilize capacity utilization for qualified suppliers.
- First-tier city demand:Shanghai, Beijing, and Shenzhen outdoor recreation brands are building dedicated freeze-dried product lines, pulling premium positioning away from commodity dehydrated goods.
Market Restraints
- Input cost volatility:Vacuum pump energy consumption and refrigerant prices fluctuate with regional electricity tariffs, squeezing margin predictability for batch processors.
- Supply concentration risk:Raw material procurement networks cluster in specific agricultural belts, exposing processors to regional harvest variability and transportation bottlenecks.
- Technical limitation:Meat lyophilization requires complex protein denaturation control that extends cycle times and elevates rejection rates versus fruit and vegetable processing.
Strategic Opportunities
- Live-streaming commerce:E-commerce platforms are reconfiguring volume flows through community group buying, opening direct-to-consumer channels that bypass traditional retail markups.
- Emergency stockpiling:Provincial disaster preparedness programs represent underpenetrated institutional demand with standardized specification requirements.
- Clean-energy mandates:Regional production caps in high-emission zones are pressuring geographic relocation to renewable-rich provinces, creating facility consolidation opportunities.
Industry Challenges
- Lyophilization engineering talent:Vacuum process optimization and sublimation curve modeling require specialized skills that outpace domestic training program output.
- NMPA nutritional labeling:Evolving requirements for dehydrated product reconstitution instructions extend certification timelines and demand reformulation documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Freeze-Dried Food Market |
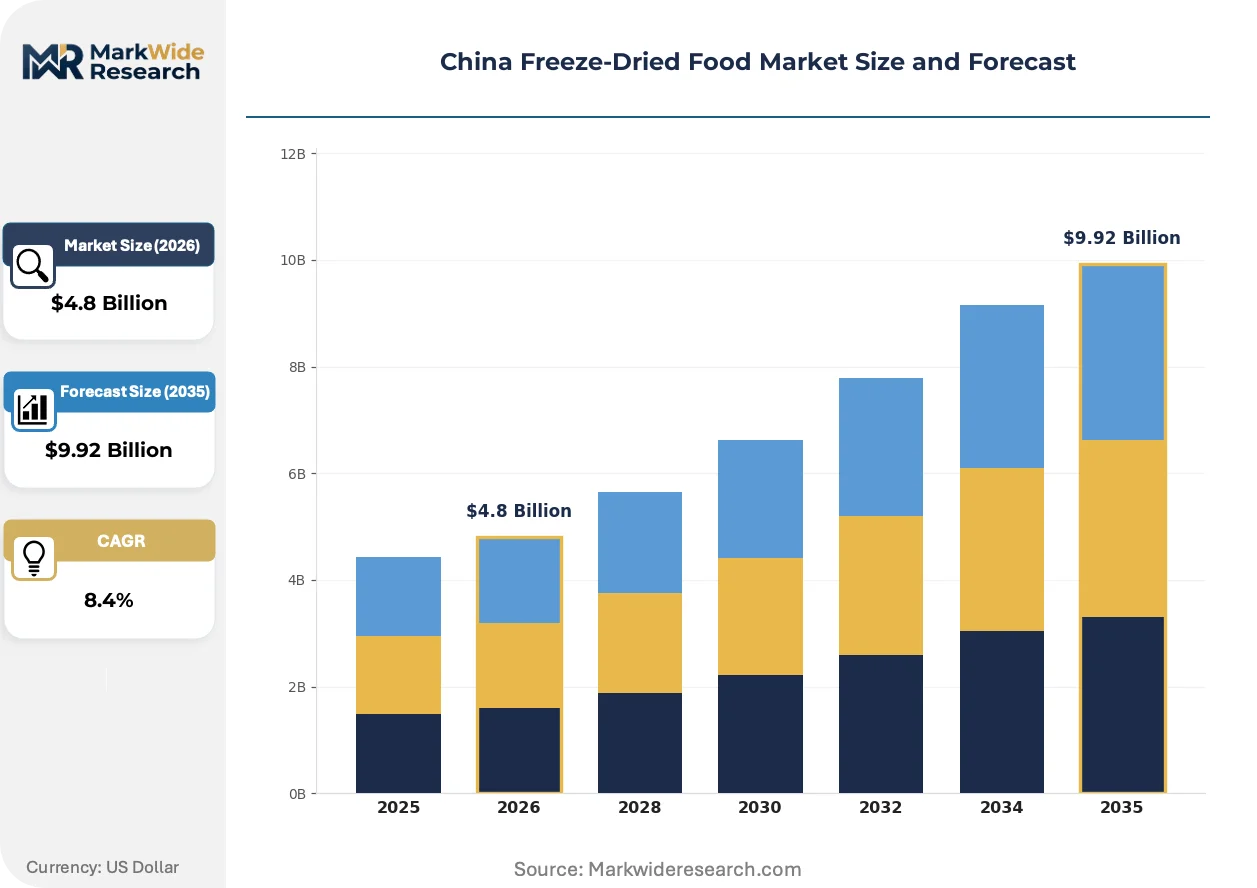
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Meats, Soups Application: Camping, Emergency Preparedness, Travel, Household Use End User: Retail Consumers, Food Service Providers, Military, Healthcare Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Zhengzhou Donsen Foods Co. Ltd, Shenzhen Lujia Fdfood Co., Ltd., Lixing Group, Chaucer Foods Ltd, China Mark Foods Co. Ltd, Tianjin Sai Yu Food Co., Ltd., Shanghai Richfield International Co. Ltd, Kerry Group PLC, Anyang General Foods Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Freeze-Dried Food Market Strategic Shifts
Automation and regulatory precision are converging to reshape how freeze-dried food moves from agricultural input to packaged output, with digital process control and clean-energy mandates driving capital allocation decisions.
Smart lyophilization systems with real-time sublimation monitoring and automated pressure modulation are digitizing quality control protocols that previously relied on operator judgment. Military suppliers and premium consumer brands are adopting these systems fastest, compressing batch-to-batch variation and reducing manual inspection labor. The technology is digitizing compliance documentation for SAMR audits, creating audit trails that accelerate certification renewals.
SAMR food safety standards for dehydrated products are tightening microbial limit specifications and traceability requirements. Processors must now implement hazard analysis critical control point systems with digital logging that interfaces with provincial regulatory databases. Small and mid-sized facilities in Shandong face the steepest adaptation costs, driving consolidation toward enterprises with dedicated quality infrastructure.
Outdoor recreation brands are unbundling after-sales education from product sales, offering rehydration technique tutorials and recipe content through proprietary apps. This shifts consumer relationships from transactional retail to subscription engagement, with first-tier city millennials responding most strongly. Shenzhen and Beijing represent the strongest adoption geography, where premium positioning justifies content investment that commodity processors cannot match.
China Freeze-Dried Food Market Segmentation
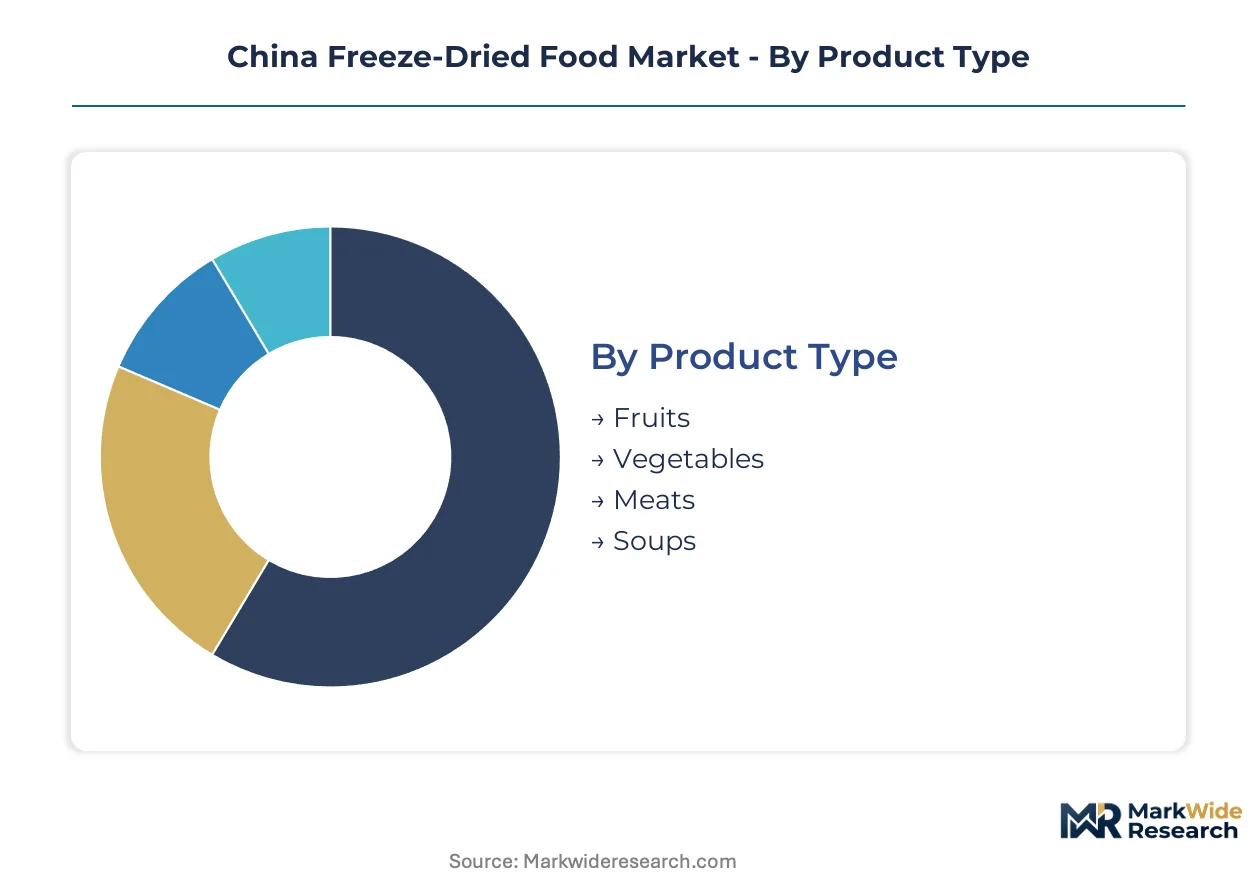
Freeze-dried food segmentation in China reflects divergent production economics and procurement rhythms. Product type determines lyophilization cycle complexity, while application and end-user categories shape inventory velocity and margin structure across the value chain.
Product Type:
Fruits turn through production fastest with standardized sublimation curves, while meats extend cycle times through protein denaturation protocols. Vegetables occupy the middle ground on throughput, and soups require multi-component blending that slows batch completion.
- Fruits:High-sugar substrates like strawberries and mangoes sublimate efficiently with minimal structural collapse. Demand concentrates in Shanghai and Beijing premium outdoor brands where lightweight trail snacks command price premiums over conventional dried alternatives.
- Vegetables:Lower sugar content extends primary drying phases but preserves rehydration texture for soup applications. Procurement networks in Shandong and Fujian agricultural belts supply cost-competitive feedstock to processors with backward integration into raw material sourcing.
- Meats:Complex myofibrillar protein stabilization requires extended freezing and controlled temperature ramping.
- Soups:Multi-ingredient formulations demand separate lyophilization of components before final blending.
Fruits anchor the volume base while meats gain share at the steepest rate.
Application:
Cost tiers separate emergency stockpiling programs with bulk procurement power from premium consumer convenience plays. Camping applications sit at the premium extreme, while household use represents the most price-sensitive mass-market entry point.
- Camping:Premium outdoor recreation brands in Shenzhen and Beijing build dedicated freeze-dried product lines with rehydration education bundled through proprietary apps. SAMR nutritional labeling compliance adds certification overhead that smaller commodity processors cannot absorb.
- Emergency Preparedness:Provincial disaster preparedness programs represent institutional demand with standardized multi-year specifications. Military procurement under national food security directives locks in volume commitments that stabilize capacity utilization.
- Travel:Lightweight convenience positioning targets high-frequency business travelers on domestic rail and air routes.
- Household Use:Community group buying channels penetrate price-sensitive urban households with basic fruit and vegetable offerings.
Emergency preparedness commands the largest contract values while camping delivers the highest per-unit margins.
End User:
Customer type determines procurement concentration, with military and healthcare exhibiting consolidated buying power against fragmented retail channels. Food service providers occupy a middle tier with regional chain consolidation driving volume aggregation.
- Retail Consumers:E-commerce platforms and live-streaming commerce fragment demand across divergent price sensitivity profiles. First-tier city millennials respond strongest to content-driven subscription engagement models.
- Food Service Providers:Regional restaurant chains and institutional caterers source bulk ingredients for reconstitution in commercial kitchens.
- Military:Multi-year ration contracts under national food security directives create the most concentrated procurement structure. Qualified suppliers face rigorous GB standards compliance for vacuum dehydration equipment.
- Healthcare:Hospital nutrition departments and eldercare facilities specify clinical-grade products with enhanced microbial limit documentation.
Military procurement anchors contract stability while healthcare expands most quickly on aging demographics.
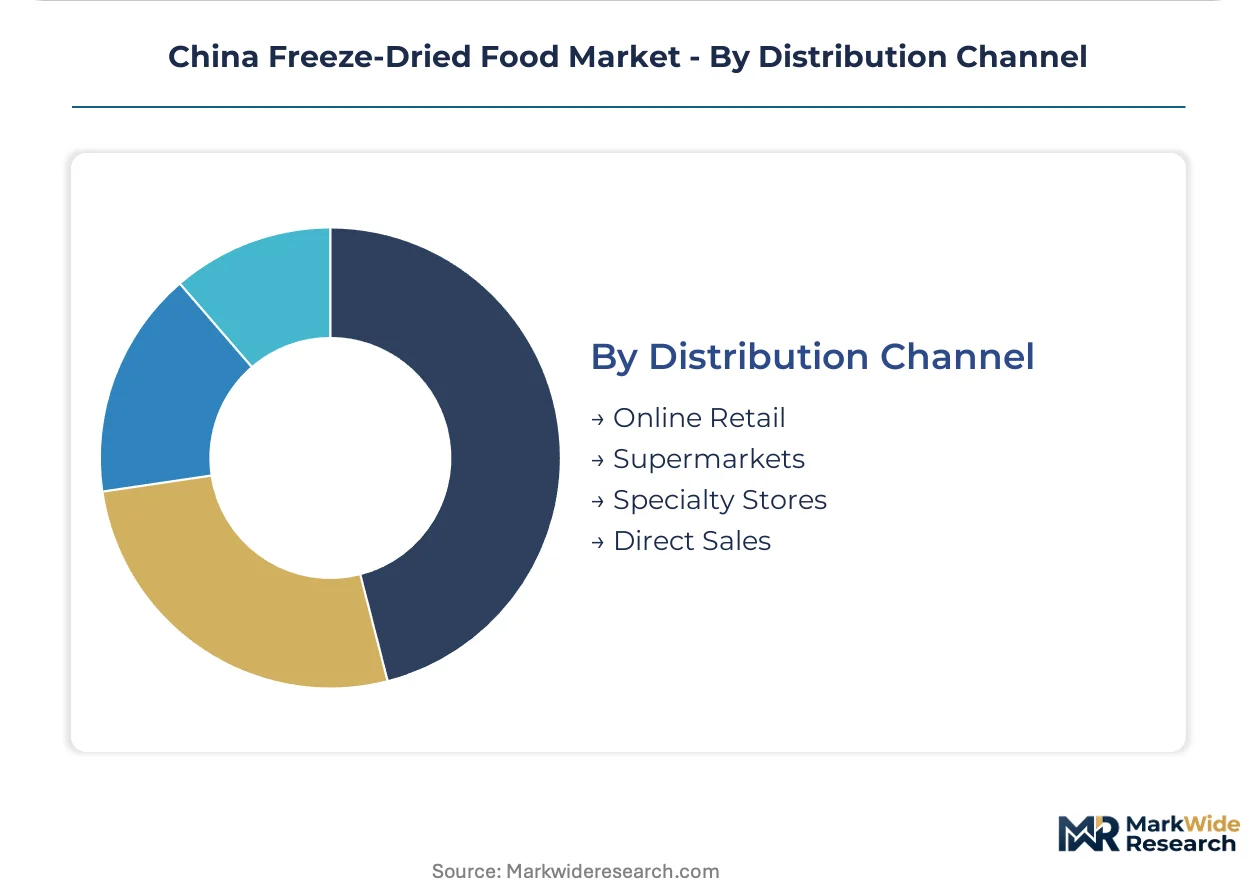
Distribution Channel:
Geographic reach and margin capture trade off across channel types, with direct sales offering highest retention against online retail's volume scale. Supermarkets and specialty stores face divergent foot traffic patterns between first-tier and lower-tier cities.
- Online Retail:Zhengzhou Donsen Foods leverages central China manufacturing to anchor domestic e-commerce fulfillment. Live-streaming commerce and community group buying now command substantial volume flows that bypass traditional retail markups.
- Supermarkets:Shelf placement in Carrefour, RT-Mart, and domestic chains requires slotting fees that favor processors with scale economies.
- Specialty Stores:Outdoor equipment retailers in Beijing and Shanghai curate premium freeze-dried assortments with trained staff rehydration guidance.
- Direct Sales:Institutional contracts with military and healthcare end users eliminate intermediary margins.
Online retail captures the broadest geographic reach while direct sales delivers the highest margin retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium outdoor brands in Shenzhen and Beijing command pricing premiums that Shandong bulk processors cannot match, creating a coastal-inland value asymmetry that shapes capital flows across provincial boundaries.
Shandong Province
Centralized lyophilization clusters in Weifang and Yantai anchor fruit and vegetable processing for domestic e-commerce fulfillment. SAMR food safety standards enforcement tightens microbial limit specifications for vacuum dehydration equipment operators. Agricultural belt backward integration into strawberry and apple procurement networks supports cost-competitive feedstock access for qualified processors.
Fujian Province
Tropical ingredient sourcing from southern coastal farms drives specialized fruit lyophilization capacity expansion in Xiamen and Quanzhou. MEE environmental regulations on energy-intensive vacuum processes pressure solar-powered equipment adoption. Technology upgrades cutting rehydration times by half attract premium outdoor recreation brand contracts from first-tier city distributors.
Guangdong Province
Pearl River Delta manufacturing bases in Shenzhen and Guangzhou build dedicated freeze-dried product lines for millennial outdoor consumers. Dual carbon goals mandate renewable-powered lyophilization adoption or face regional production caps. Live-streaming commerce platforms headquartered in Shenzhen reconfigure volume flows through community group buying channels.
Beijing Municipality
Military procurement programs under national food security directives concentrate multi-year ration contract negotiations with qualified suppliers. NMPA evolving nutritional labeling requirements extend certification timelines for dehydrated product reconstitution instructions. Specialty outdoor equipment retailers curate premium assortments with trained staff rehydration guidance for capital region consumers.
Henan Province
Zhengzhou central China manufacturing anchors supply chain positioning for domestic e-commerce fulfillment networks. Provincial disaster preparedness programs represent underpenetrated institutional demand with standardized specification requirements. Clean-energy mandates pressure geographic relocation to renewable-rich provinces, creating facility consolidation opportunities for processors with captive energy infrastructure.
China Freeze-Dried Food Market Competitive Environment
Vertically integrated agricultural processors and specialized lyophilization equipment operators split the market between bulk commodity supply and premium branded positioning. The vendor base concentrates around three strategic archetypes: backward-integrated raw material controllers, technology-specialized sublimation engineers, and e-commerce-anchored direct-to-consumer brands. Dominant competitive moves include renewable-powered facility relocation to evade MEE emission caps and proprietary app-based subscription engagement models that shift consumer relationships beyond transactional retail.
Among central China-based food processors, Zhengzhou Donsen Foods Co. Ltd exemplifies the e-commerce-anchored archetype through its geographic positioning for domestic fulfillment network access. Shenzhen Lujia Fdfood Co., Ltd. occupies a specialization-driven position reflecting its southern China tropical ingredient sourcing concentration. Lixing Group represents the institutional-contract tier with its focus on bulk supply agreements and backward integration into agricultural procurement networks.
| Leading Market Players |
|---|
| Zhengzhou Donsen Foods Co. Ltd |
| Shenzhen Lujia Fdfood Co., Ltd. |
| Lixing Group |
| Chaucer Foods Ltd |
| China Mark Foods Co. Ltd |
| Tianjin Sai Yu Food Co., Ltd. |
| Shanghai Richfield International Co. Ltd |
| Kerry Group PLC |
| Anyang General Foods Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Shandong Province's lyophilization clusters in Weifang and Yantai concentrate freeze-dried fruit and vegetable capacity, translating upstream agricultural belt proximity into pricing power for processors with backward integration into strawberry and apple procurement networks.
Pricing Analysis
Configured-to-order pricing for military ration contracts and premium outdoor brand SKUs commands spreads of 40-60% above standard e-commerce SKUs. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and rehydration performance metrics. Cost compression in the standard tier intensifies because community group buying channels aggregate price-sensitive demand. Retail consumers through live-streaming commerce exhibit highest price sensitivity, while military procurement demonstrates lowest sensitivity due to specification compliance requirements.
Supply Chain Analysis
Upstream feedstock draws from Shandong strawberry and apple belts, Fujian tropical fruit farms, and Henan central China logistics hubs. Raw material dependencies include vacuum pump refrigerants, food-grade nitrogen for inert atmosphere processing, and laminated barrier packaging films. Single-source vulnerability concentrates in lyophilization equipment spare parts from German and Japanese OEMs. Distribution runs through Zhengzhou central fulfillment nodes for e-commerce, direct institutional contracts for military and healthcare, and Shenzhen live-streaming commerce platforms for consumer reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where SAMR food safety certification and GB standards compliance create regulatory entrenchment that locks out unqualified competitors.
For Market Incumbents: Entrench position through solar-integrated lyophilization facility upgrades in renewable-rich provinces to evade MEE emission caps, and deepen backward integration into agricultural procurement networks to secure feedstock against harvest variability. Emerging e-commerce-native brands with proprietary app subscription models represent the primary substitution threat. Certification investment in NMPA nutritional labeling compliance serves as the priority defensive lever. For New Entrants and Emerging Players: Provincial disaster preparedness programs in Henan and emergency stockpiling contracts represent the most penetrable entry point, as standardized specifications reduce qualification friction versus military procurement. Live-streaming commerce direct-to-consumer channels bypass slotting fee barriers that protect supermarket incumbents. Go-to-market execution should anchor on rehydration education content bundled through WeChat mini-programs to build subscription engagement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with solar-integrated facilities and digital sublimation monitoring systems that compress batch variation. Long-term viability across the projection horizon rests on clean-energy mandate compliance and SAMR audit trail capabilities. Acquisition targets should screen for backward integration depth and renewable infrastructure. The signal to watch is provincial production cap enforcement intensity in high-emission zones as inflection indicator for facility relocation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable-Powered Facility Relocation | Solar-integrated lyophilization in Fujian and Shandong evades MEE regional production caps. |
| Backward Integration into Agricultural Procurement | Captive strawberry and apple sourcing networks in Shandong agricultural belts secure cost-competitive feedstock. |
| Proprietary App Subscription Engagement | Shenzhen and Beijing outdoor brands shift consumer relationships from transactional retail to content-driven retention. |
| SAMR Certification Infrastructure Investment | Digital HACCP logging and audit trail capabilities accelerate certification renewals and lock out smaller competitors. |
| Live-Streaming Commerce Channel Expansion | Zhengzhou central China manufacturing anchors direct-to-consumer fulfillment bypassing traditional retail markups. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SAMR regulatory filings, GB standards documentation, and provincial agricultural output statistics. Primary interviews engaged lyophilization equipment operators, military procurement officers, e-commerce platform category managers, and outdoor brand product development leads. Secondary validation incorporated MEE environmental compliance disclosures, NMPA nutritional labeling guidance, and customs trade data on vacuum dehydration equipment imports. Bottom-up capacity modeling triangulates against top-down demand aggregation across military, healthcare, and consumer segments.
Forecast inputs include lyophilization cycle time compression trajectories, renewable energy adoption curves, and live-streaming commerce penetration rates. Segmentation dimensions span product type, application, end user, and distribution channel with regional regulatory cluster differentiation. CAGRs derive from capacity utilization trends and pricing spread evolution. Industry-specific forecast inputs incorporate dual carbon goal enforcement intensity and SAMR microbial limit specification tightening schedules.
Practitioners should monitor MEE emission cap enforcement, NMPA labeling requirement finalization, and provincial disaster preparedness budget allocations for early signals of forecast revision. Forecasts reflect assumptions on technology adoption curves and regulatory implementation timelines. Cross-checking against SAMR published inspection outcome data and provincial energy consumption statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
Artisanal Ice Cream Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
Processed Beef Market
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
Apple Butter Market
Processed Foods
Dairy Desserts Market
Processed Foods
Low Moisture Food Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Spray Cheese Market
Processed Foods
Shelf-Stable Soup Market
Processed Foods
United States Food Spread Market
Processed Foods
Porridge Market
Processed Foods
Africa Soup Market
Processed Foods
Egg White Cubes Market
Processed Foods
Global Pasta Market