
 France Refined Petroleum Product Market | 2026-2036
France Refined Petroleum Product Market Size, Share, and Industry Trends Forecast 2026-2036
France Refined Petroleum Product Market Foresight
Buyer concentration across France's refined petroleum product sector is broadening as logistics companies diversify fuel procurement beyond traditional integrated suppliers while aviation operators and shipping firms expand direct contracting. TotalEnergies anchors downstream distribution through its extensive retail network and refining infrastructure at Normandy and Flanders. Esso competes on operational efficiency across its Gravenchon complex and channel partnerships with fleet operators. BP PLC differentiates through low-carbon fuel blending investments aligned with French decarbonization targets.
France refined petroleum products encompass hydrocarbon outputs from crude oil distillation and conversion processes, including diesel with maximum 10 ppm sulfur content under Euro VI standards, gasoline meeting EN 228 specifications, and kerosene-based jet fuel refined to AFQRJOS Check List parameters for turbine engine combustion. These products serve as primary energy inputs for mobility, industrial heat, and power generation across French manufacturing and transport infrastructure. Diesel retains structural dominance in heavy-road freight and agricultural machinery where battery alternatives face payload and range constraints. Jet fuel represents the fastest-growing product category as Paris Charles de Gaulle and Orly airports restore international connectivity. Liquefied petroleum gas occupies a mature niche in residential heating across rural Grand Est and Auvergne-Rhône-Alpes regions.
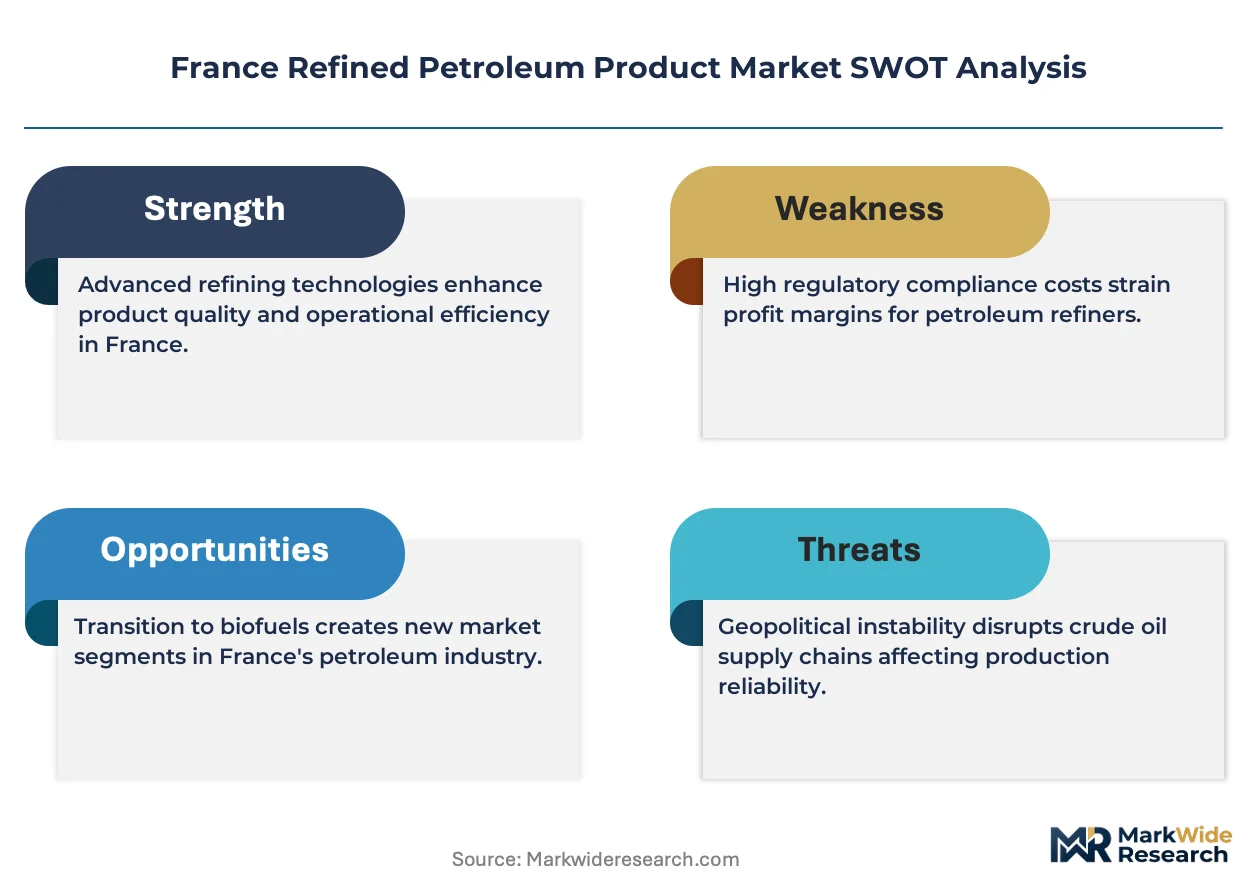
ANSM and France's national energy regulator enforce product quality standards, while EU REACH and F-Gas Regulation constrain sulfur content and fluorinated gas use in refining processes. The EU Green Deal's Fit for 55 package is forcing refiners to integrate biofuel blending mandates and carbon intensity accounting into operational planning. Stakeholders must monitor hydrogen refinery integration timelines and renewable fuel of non-biological origin certification pathways to preserve asset viability.
Market Dynamics
The France refined petroleum product sector faces structural compression from the EU Green Deal's Fit for 55 package, which mandates biofuel blending quotas and carbon intensity disclosures that refiners must integrate into operational planning or face asset stranding.
Growth Catalysts
- Aviation Recovery:Paris Charles de Gaulle and Orly airports are restoring international connectivity, expanding jet fuel offtake as flight schedules normalize post-pandemic.
- REACH Compliance Pathways:Refiners investing in renewable fuel of non-biological origin certification gain preferential access to EU ETS credits and national low-carbon fuel standard incentives.
- Freight Electrification Uncertainty:Battery range and payload constraints in heavy-road logistics preserve diesel demand along the Paris-Ile-de-France corridor through the near term.
Market Restraints
- Crude Supply Concentration:French refining depends on seaborne crude imports through Rotterdam and Mediterranean terminals, exposing margins to Baltic freight volatility and OPEC+ supply decisions.
- Hydrogen Integration Capex:Refinery electrification and green hydrogen feedstock switching require capital deployment at scale that mid-sized operators cannot access without consolidated balance sheets.
- LPG Demand Erosion:Heat pump adoption in rural Grand Est and Auvergne-Rhône-Alpes is displacing residential liquefied petroleum gas for space heating.
Strategic Opportunities
- Sustainable Aviation Fuel Mandates:ReFuelEU Aviation requirements create dedicated offtake contracts for SAF producers with blending infrastructure at French airports.
- Normandy Industrial Cluster:The Le Havre-Rouen refining complex offers carbon capture and storage integration potential for low-carbon hydrogen production serving regional chemical manufacturers.
- Digital Fuel Cards:Fleet operators are adopting real-time consumption tracking platforms that bypass traditional wholesale intermediaries and enable direct refiner-contractor relationships.
Industry Challenges
- Process Engineer Shortage:French technical universities produce insufficient catalysis and hydroprocessing specialists to staff refinery modernization programs.
- Co-Processing Certification:ANSM and EU renewable fuel verification timelines delay market entry for bio-intermediate blends, compressing returns on pilot plant investments.
- Legacy Terminal Retrofit:Existing storage and pipeline infrastructure requires hazardous material recertification to handle novel biofuel chemistries with different corrosion profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Refined Petroleum Product Market |
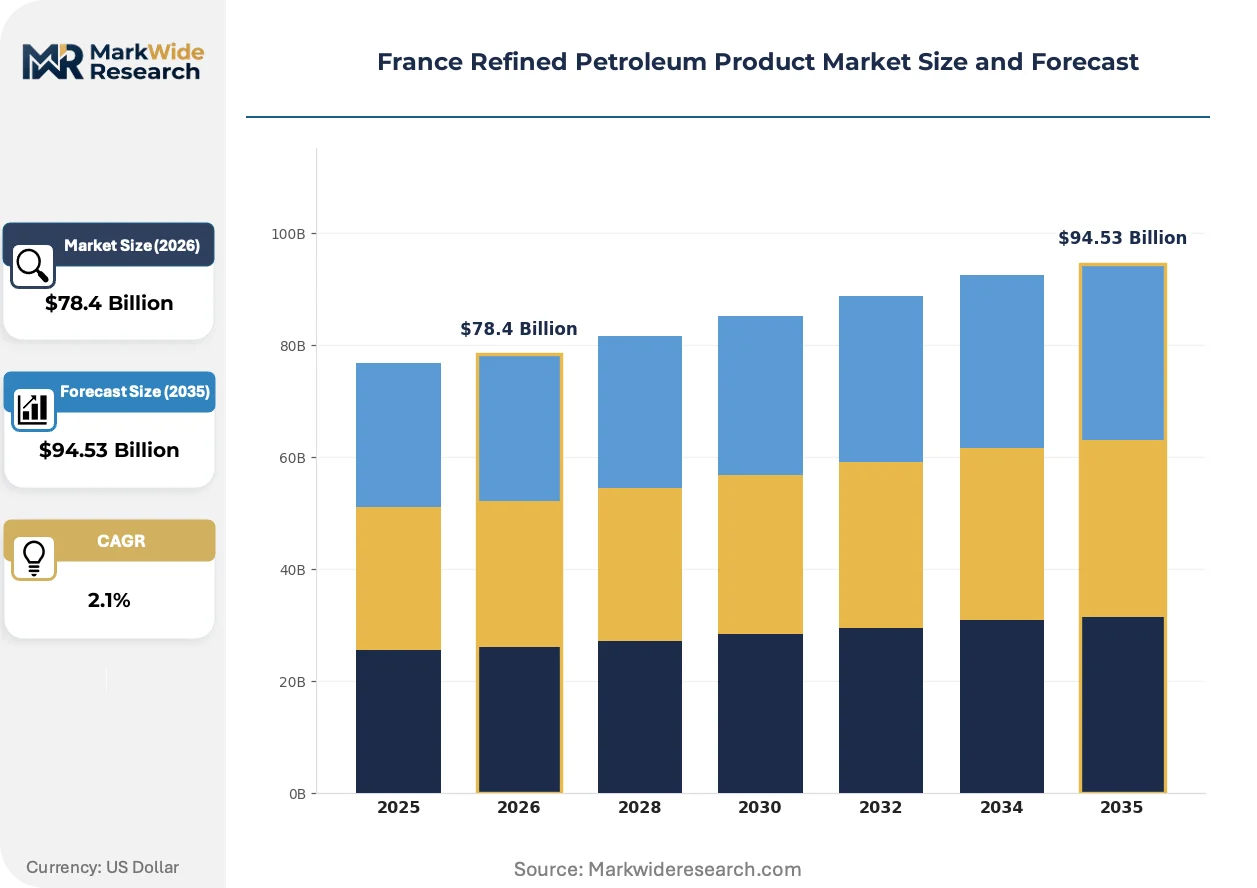
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $94.53 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel, Gasoline, Kerosene, Fuel Oil, Liquefied Petroleum Gas, Jet Fuel Application: Transportation Fuel, Industrial Fuel, Power Generation, Marine Fuel, Aviation Fuel, Residential Heating Distribution Channel: Direct Sales, Retail Fuel Stations, Industrial Supply Contracts, Wholesale Traders, Online Platforms, Bulk Supply End User: Logistics Companies, Manufacturing Plants, Aviation Operators, Shipping Firms, Construction Businesses, Residential Consumers |
| Companies Covered | TotalEnergies, Esso, ExxonMobil, BP PLC, Royal Dutch Shell, Chevron Corporation, Petroineos, Repsol SA, Ponticelli, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Refined Petroleum Product Market Shifts & Advancements
Digital instrumentation and policy-mandated carbon accounting are compressing decision cycles across France's downstream sector, forcing faster capital reallocation toward certified low-carbon product streams.
Advanced process control systems using machine learning are automating distillation unit optimization at French refineries. Operators at the Normandy complex deploy these platforms to minimize energy intensity per barrel. The technology is automating yield maximization that previously required shift-based manual adjustment, reducing variable cost spreads against Northwest European benchmarks.
The EU Green Deal's F-Gas Regulation constrains fluorinated gas use in refining refrigeration and heat pump systems. French facilities must substitute alternative working fluids or retrofit equipment, adding compliance capital burdens. Jet fuel producers face the tightest timelines as AFQRJOS Check List parameters now incorporate lifecycle carbon thresholds.
Fleet procurement teams are consolidating fuel purchasing through digital platforms that aggregate consumption across multiple depots. Large logistics operators in the Paris-Ile-de-France corridor negotiate directly with refiners, bypassing traditional wholesale distributors. This pattern concentrates volume with integrated suppliers capable of certifying carbon intensity at the batch level.
France Refined Petroleum Product Market Segmentation
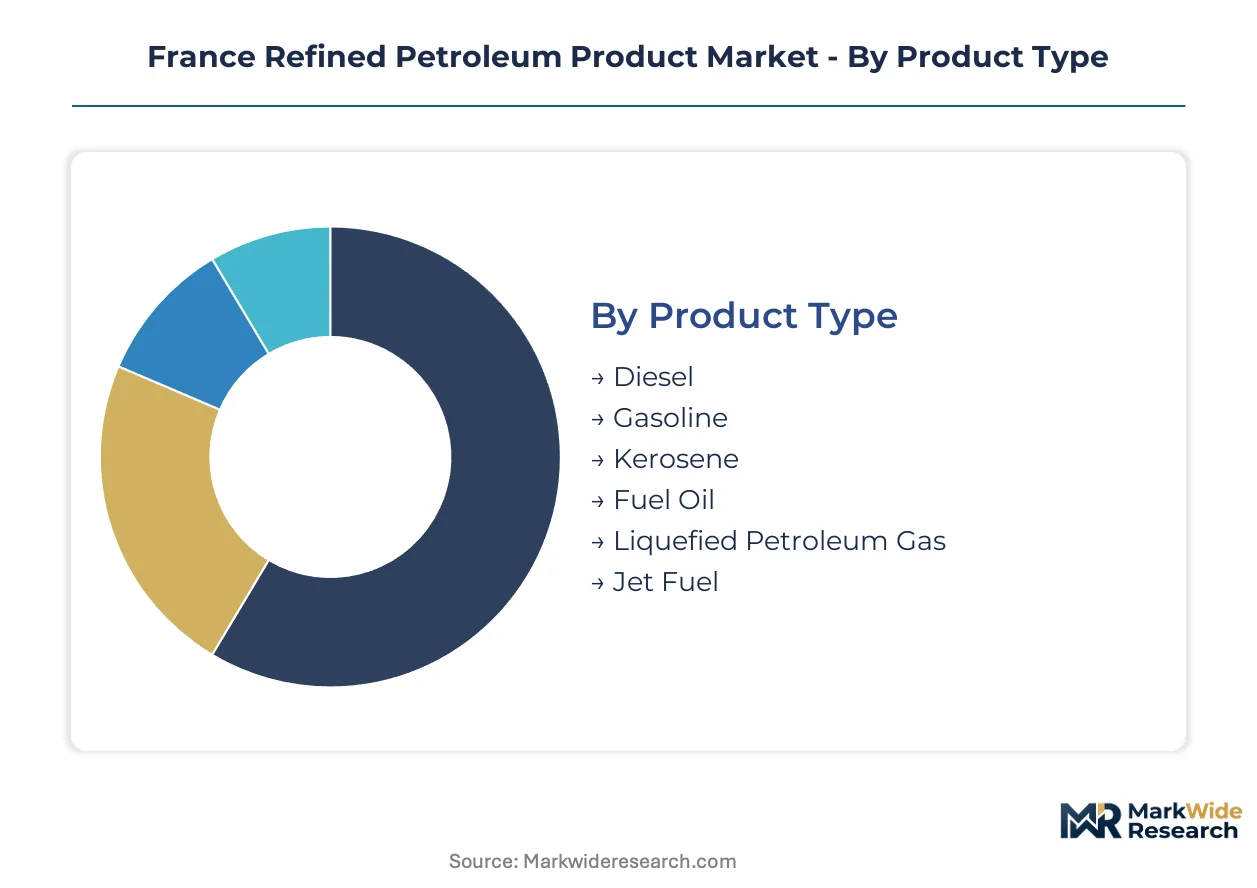
Refined petroleum product flows in France fragment across multiple demand axes that determine pricing power and margin capture. Understanding these divisions reveals where integrated refiners can defend position against wholesale disintermediation and where new entrants find vulnerability in legacy supply arrangements.
Product Type:
Supply concentration at the Le Havre-Rouen and Flanders refining complexes shapes product availability across the national market.
- Diesel:Hydrocarbon fuel meeting Euro VI standards with maximum 10 ppm sulfur content. Demand concentrates in heavy-road freight along the Paris-Ile-de-France corridor where battery range constraints preserve diesel's near-term relevance for logistics operators.
- Jet Fuel:Kerosene-based turbine fuel refined to AFQRJOS Check List parameters. Paris Charles de Gaulle and Orly airports drive offtake expansion as international flight schedules normalize post-pandemic, making this the steepest expansion trajectory among all product categories.
- Gasoline:Light distillate meeting EN 228 specifications for spark-ignition engines. Passenger vehicle demand in urban centers faces electrification pressure from the EU Green Deal's transport decarbonization timelines.
- Kerosene:Illuminating and heating-grade distillate distinct from aviation specifications. Rural Grand Est maintains residual demand for non-pipeline heating applications.
- Fuel Oil:Heavy residual product for industrial combustion and marine bunkering. Normandy chemical manufacturers and Mediterranean port operations anchor remaining offtake.
- Liquefied Petroleum Gas:Propane-butane blend for residential and light commercial heating. Heat pump adoption in Auvergne-Rhône-Alpes is compressing household demand.
Diesel absorbs the bulk of installed capacity; jet fuel is expanding most quickly.
Application:
Cost tier differentiation separates premium-certified low-carbon fuels from standard-specification products in procurement negotiations.
- Transportation Fuel:Road, rail, and pipeline-delivered products for mobility applications. Fleet operators in the Paris-Ile-de-France corridor negotiate direct contracts with refiners, bypassing traditional wholesale intermediaries.
- Aviation Fuel:Dedicated turbine fuel supply to commercial airports. ReFuelEU Aviation mandates are forcing SAF blending investments at Charles de Gaulle infrastructure.
- Industrial Fuel:Process heat and feedstock energy for manufacturing. Normandy chemical clusters demand certified low-carbon intensity products for EU ETS compliance.
- Marine Fuel:Bunker fuels for Mediterranean and Atlantic port calls. IMO sulfur regulations constrain product specifications at Marseille-Fos and Le Havre terminals.
- Power Generation:Distillate and residual fuels for grid backup and island systems. Corsica and overseas territories maintain diesel-fired capacity for reliability.
- Residential Heating:LPG and kerosene for non-gasified rural households. Heat pump subsidies through France's national low-carbon fuel standard are eroding this segment.
Transportation fuel commands the largest volume share; aviation fuel is climbing the fastest on SAF mandate compliance.
Distribution Channel:
Customer type fragmentation determines whether procurement flows through integrated refiner networks or independent intermediaries.
- Direct Sales:Refiner-to-end-user contracts with batch-level carbon certification. Large logistics operators and aviation handlers dominate this channel for transparency requirements.
- Retail Fuel Stations:Branded and independent forecourt operations. TotalEnergies' national network anchors consumer-facing diesel and gasoline availability.
- Industrial Supply Contracts:Term agreements with manufacturing and chemical processors. Normandy cluster facilities negotiate multi-year offtake with carbon intensity guarantees.
- Wholesale Traders:Independent intermediaries aggregating smaller volumes. This channel is losing share to digital platforms that enable direct refiner relationships.
- Online Platforms:Digital fuel card and procurement systems with real-time consumption tracking. Fleet operators adopt these for depot-level aggregation across the Paris-Ile-de-France logistics network.
- Bulk Supply:Pipeline, barge, and rail deliveries to storage terminals. Mediterranean and Rotterdam crude import dependencies shape this channel's cost structure.
Direct sales capture the highest margin transactions; online platforms are gaining share fastest through fleet digitization.
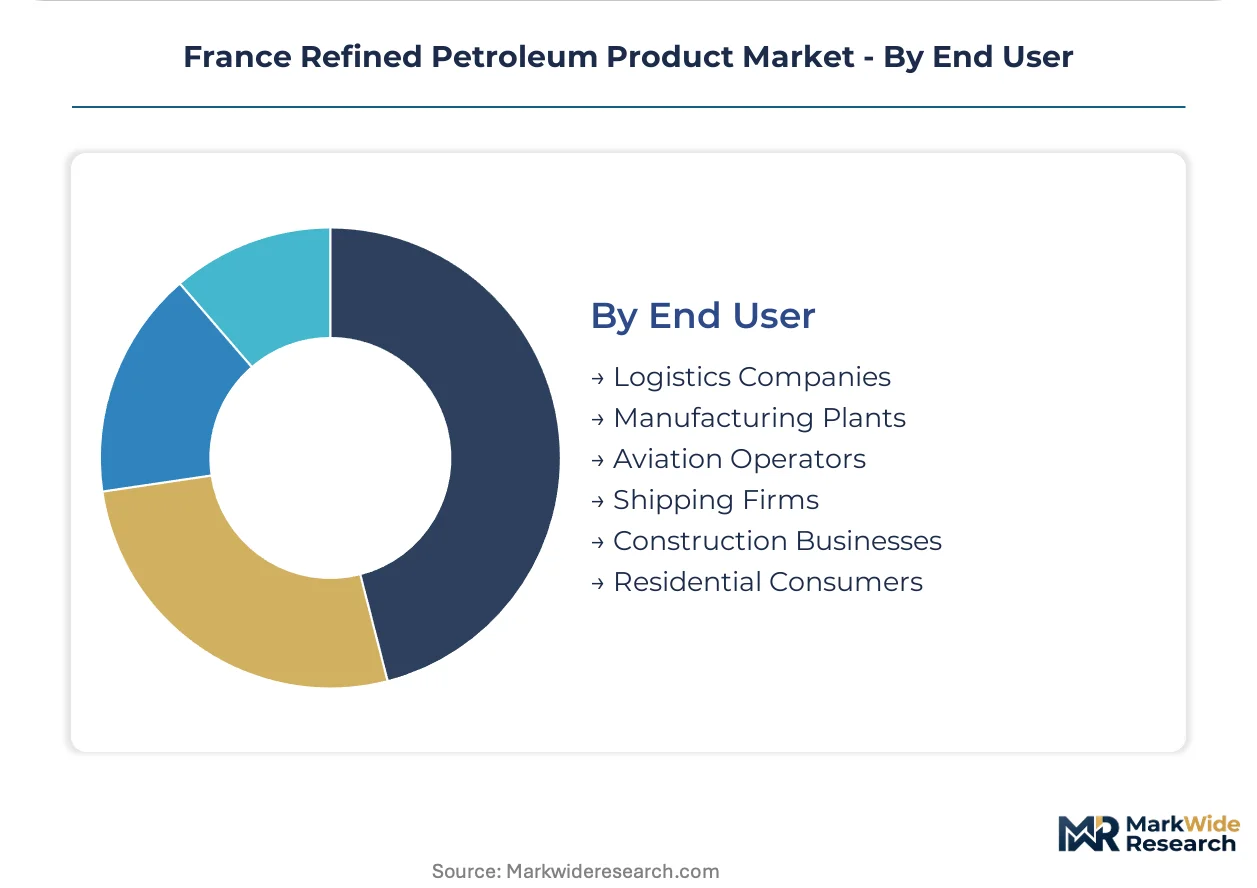
End User:
Volume concentration among large offtakers determines contract structure and pricing leverage in negotiations.
- Logistics Companies:Heavy-road freight and last-mile delivery operators. Diesel procurement for the Paris-Ile-de-France corridor remains their dominant energy spend category.
- Aviation Operators:Airlines and ground handlers at French airports. ReFuelEU compliance timelines are forcing SAF procurement commitments at Charles de Gaulle and Orly.
- Manufacturing Plants:Chemical, steel, and cement producers requiring process heat. Normandy industrial cluster participants demand low-carbon hydrogen integration pathways.
- Shipping Firms:Mediterranean and Atlantic coastal operators. Marseille-Fos bunkering infrastructure serves their fuel oil and marine diesel requirements.
- Construction Businesses:Mobile equipment and temporary power generators. Agricultural machinery demand in rural Grand Est overlaps with this user category.
- Residential Consumers:Household LPG and heating oil purchasers. Auvergne-Rhône-Alpes heat pump adoption is displacing this segment most rapidly.
Logistics companies absorb the bulk of diesel volume; aviation operators are expanding offtake most quickly on international route restoration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crude import terminals at Rotterdam and Mediterranean ports anchor France's refined petroleum supply geography, with domestic refining capacity concentrated at coastal complexes that process seaborne feedstocks into transport and industrial fuels.
Île-de-France
Paris Charles de Gaulle and Orly airports drive jet fuel offtake expansion as international flight schedules normalize post-pandemic. The EU Green Deal's Fit for 55 package mandates biofuel blending quotas that refiners must integrate into supply contracts serving this corridor. Logistics operators in the Paris-Ile-de-France freight network negotiate direct diesel procurement with integrated suppliers, bypassing wholesale intermediaries through digital fuel card platforms.
Hauts-de-France
The Le Havre-Rouen refining complex processes crude deliveries into diesel, gasoline, and industrial feedstocks for Normandy chemical manufacturers. ANSM and France's national energy regulator enforce product quality standards across this cluster. Carbon capture and storage integration projects at Le Havre terminals target low-carbon hydrogen production pathways for regional industrial decarbonization.
Provence-Alpes-Côte d'Azur
Marseille-Fos bunkering infrastructure serves Mediterranean shipping routes with marine diesel and fuel oil compliant with IMO sulfur regulations. F-Gas Regulation constraints affect refrigeration systems at regional refining units. The port complex maintains residual demand for heavy residual products among coastal chemical processors.
Auvergne-Rhône-Alpes
Rural residential heating demand for liquefied petroleum gas persists in this region despite accelerating heat pump adoption. France's national low-carbon fuel standard subsidizes electrification alternatives that displace LPG in household applications. Agricultural machinery operators in surrounding areas sustain diesel requirements for equipment where battery alternatives face payload constraints.
France Refined Petroleum Product Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue low-carbon certification and digital platform integration. The France refined petroleum product sector consolidates around integrated energy majors with coastal refining infrastructure and downstream distribution networks. Three archetypes dominate: vertically integrated majors controlling full supply chains, regional specialists with terminal and logistics assets, and digital intermediaries disintermediating wholesale relationships. Competitive dynamics center on refinery modernization capex deployment and direct contracting relationships with large fleet operators.
Within the integrated major tier, TotalEnergies and Esso anchor downstream distribution through extensive retail networks and refining infrastructure. BP PLC exemplifies the low-carbon transition archetype with investments in sustainable fuel blending aligned with French decarbonization targets. These entities represent contrasting strategic positions: scale-driven operational efficiency versus certification-led product differentiation.
| Leading Market Players |
|---|
| TotalEnergies |
| Esso |
| ExxonMobil |
| BP PLC |
| Royal Dutch Shell |
| Chevron Corporation |
| Petroineos |
| Repsol SA |
| Ponticelli |
| Others |
Supply & Pricing Matrix
Green hydrogen refinery integration timelines are compressing capital recovery periods while simultaneously concentrating procurement leverage among integrated majors with balance sheet capacity for feedstock switching. This dual pressure reshapes contract structures across French downstream markets as buyers demand certified low-carbon intensity at batch level and suppliers face stranded asset risk without conversion investment.
Pricing Analysis
Carbon intensity certification bundling separates premium-contracted volumes from spot-market transactions with unverified provenance. Three-tier pricing structure across certified low-carbon, standard-specification, and residual fuel grades reflects differentiation by EU ETS compliance tier and SAF mandate alignment. Cost compression in standard diesel runs through freight electrification uncertainty along the Paris-Ile-de-France corridor. Logistics operators with direct refiner relationships exhibit lowest price sensitivity; residential LPG purchasers facing heat pump substitution show highest elasticity.
Supply Chain Analysis
Specialized process engineering talent scarcity in French technical universities constrains refinery modernization velocity at coastal complexes. Crude feedstock draws from seaborne imports through Rotterdam and Mediterranean terminals, with finished products sourced from Le Havre-Rouen and Flanders refining infrastructure. Single-source vulnerability concentrates at Rotterdam crude import chokepoints. Distribution runs through pipeline networks, barge corridors, and rail terminals serving the Île-de-France logistics cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sustainable aviation fuel co-processing technology is displacing conventional hydroprocessing units, creating a hardware-transition window where capital deployment determines competitive position.
For Market Incumbents: Hedge against asset stranding by accelerating ReFuelEU Aviation compliance infrastructure at Charles de Gaulle and Orly terminals. Secure backward integration into bio-intermediate supply chains before ANSM certification timelines compress. Prioritize direct contracting relationships with aviation operators over wholesale channel maintenance.
For New Entrants and Emerging Players: Enter via digital fuel card platforms that aggregate fleet consumption across Paris-Ile-de-France depots, bypassing established wholesale intermediaries. Target logistics operators with real-time carbon accounting requirements as the most penetrable buyer segment. Pursue SAF blending infrastructure partnerships with airport authorities rather than greenfield refinery investment.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated majors with certified low-carbon product pipelines and direct aviation offtake contracts. Long-term viability hinges on hydrogen refinery integration execution and EU ETS credit generation capacity. Monitor F-Gas Regulation retrofit completion rates as the inflection signal for operational compliance risk.
| Strategic Initiative | Industry Significance |
|---|---|
| SAF Blending Infrastructure Deployment | ReFuelEU Aviation mandates at Charles de Gaulle create dedicated offtake contracts for certified producers. |
| Carbon Capture and Storage Integration | Le Havre-Rouen cluster projects target low-carbon hydrogen production for Normandy chemical manufacturers. |
| Digital Fuel Card Platform Launch | Real-time consumption tracking enables direct refiner-contractor relationships bypassing wholesale intermediaries. |
| Bio-Intermediate Supply Agreement | |
| Hydrogen Refinery Feedstock Switching | Green hydrogen integration preserves asset viability under France's national low-carbon fuel standard timelines. |
Research Methodology
Independent corroboration across refinery operations executives, aviation fuel procurement managers, logistics fleet directors, and EU regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from EU ETS transaction registries, ANSM product quality filings, ReFuelEU Aviation implementation reports, and customs crude import documentation. Bottom-up volume modeling triangulates against top-down macroeconomic energy demand projections.
Comparable-period anchoring to pre-pandemic aviation demand baselines and post-Fit for 55 regulatory implementation phases structures the forecast window. Segmentation dimensions span product type, application, distribution channel, and end-user archetype across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating freight electrification timeline uncertainty and SAF mandate compliance trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under OPEC+ supply disruption scenarios and accelerated battery technology cost reduction. Assumptions reflect documented policy implementation schedules and infrastructure investment commitments. Material deviation in hydrogen refinery integration timelines or ReFuelEU Aviation enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
Petcoke Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
Europe Ethane Market
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
Automotive Oil Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
North Africa Refined Petroleum Products Market
Petroleum Products
Oil Shale Market
Petroleum Products
Balanos Oil Market
Petroleum Products
Green Petcoke Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
Germany Refined Petroleum Products Market
Petroleum Products
Europe Refined Petroleum Products Market
Petroleum Products
Petroleum Wax Market