
 Global Petroleum Coke Market | 2026-2036
Global Petroleum Coke Market Size, Share, and Industry Trends Forecast 2026-2036
Global Petroleum Coke Market Intelligence
The value gap between high-purity needle coke for electrodes and commodity high-sulfur fuel-grade petcoke is expanding, forcing strategic choices for refiners and specialized producers. Marathon Petroleum Corporation leverages its extensive refining network to supply multiple grades. Rain Industries Limited specializes in the downstream calcination process to create higher-value products. Shell operates a complex global logistics network to place different coke qualities into suitable markets.
Petroleum coke is a carbon-rich solid byproduct derived from the coker units in oil refineries. It is characterized by high calorific value and low volatile matter, making it a potent energy source or carbon input. Calcined Petcoke grades are essential for aluminum production anodes, commanding a premium. In contrast, lower-quality Fuel Petcoke finds large-volume application in cement manufacturing and power generation, where its energy content is prioritized over purity.
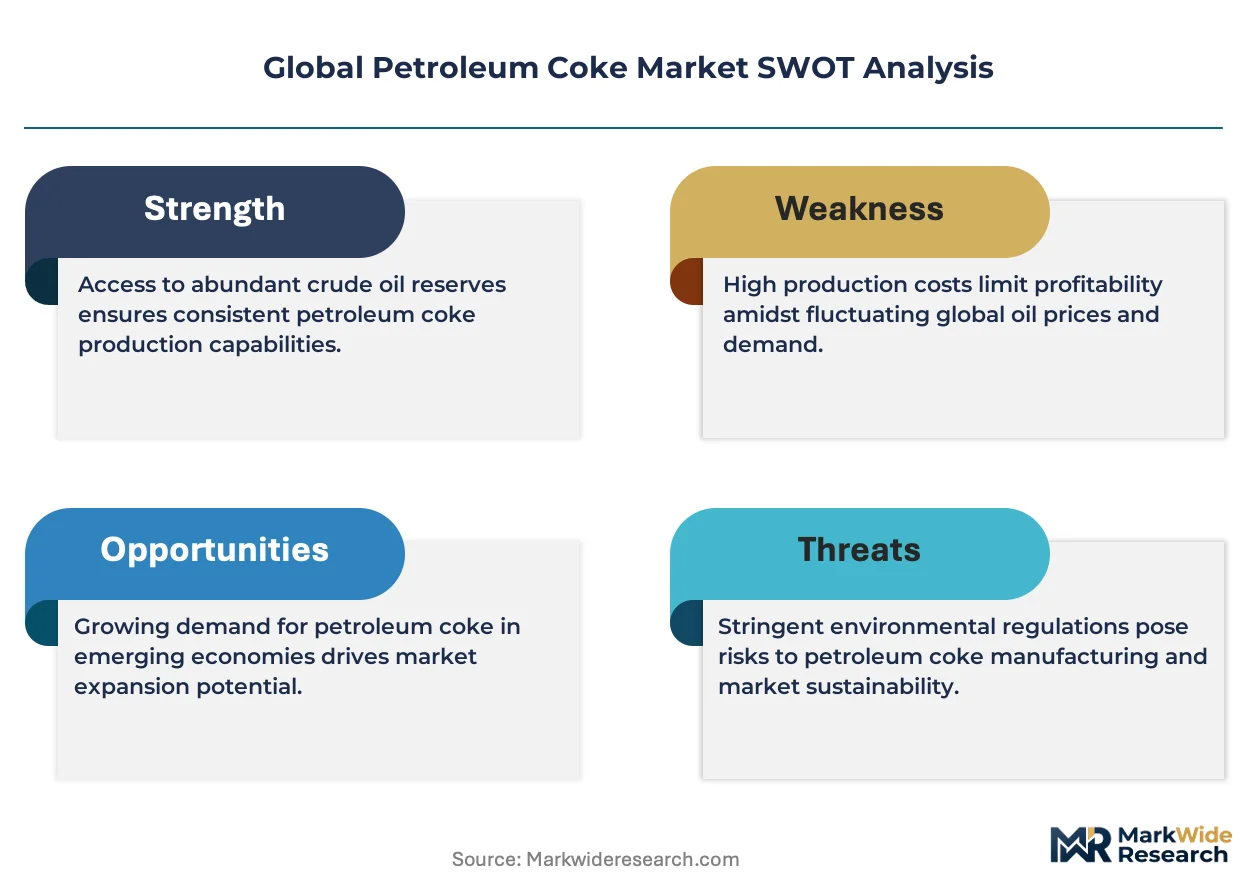
Regulatory frameworks from the US Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE) heavily influence market dynamics. These regulations set stringent limits on sulfur content in fuels, impacting the use of high-sulfur petcoke. Refiners must therefore decide whether to invest in upgrading technologies to produce higher-value, compliant coke or to compete in the more volatile, lower-margin fuel-grade segment.
Market Dynamics
The widening value and quality chasm between high-purity calcined grades and high-sulfur fuel grades is the central force shaping the petroleum coke market, driven by stringent environmental regulations and specialized industrial demand for aluminum production.
Growth Catalysts
- Aluminum Sector Expansion:Sustained output in the global aluminum industry requires a consistent supply of high-purity calcined petroleum coke for anode production, acting as a primary demand driver for premium grades.
- Indian Cement Production:India's rapidly growing cement industry provides a large-volume destination for fuel-grade petcoke, valued for its high calorific content and cost-effectiveness compared to coal.
- Upgrading Technologies:Advances in solvent deasphalting and coker unit efficiency enable refiners to extract more value from heavy crude oil residues, increasing the overall production volume of petroleum coke feedstock.
Market Restraints
- Sulfur Emission Regulations:Mandates from the US EPA and China's MEE restricting sulfur dioxide emissions directly limit the use of high-sulfur fuel-grade petcoke in power generation and industrial boilers without flue-gas desulfurization.
- Crude Slate Volatility:The quality of available crude oil directly impacts the sulfur and metal content of the resulting petcoke, creating supply variability and challenges for end-users requiring consistent specifications.
- Fuel Substitution Threat:In power and cement applications, increasing price competitiveness and policy support for natural gas and renewable energy sources present a significant substitution risk for fuel-grade petcoke.
Strategic Opportunities
- Gasification Feedstock:Petcoke can be used as a low-cost feedstock in gasification processes to produce synthesis gas (syngas) for chemicals, hydrogen, and power, offering a higher-value outlet for lower-quality grades.
- Specialty Carbon Products:Developing advanced purification and graphitization techniques opens pathways for petcoke to be used in high-performance materials, including lithium-ion battery anodes and specialty graphite components.
- Emerging Industrial Hubs:Industrializing nations in Southeast Asia and Africa represent new market frontiers for fuel-grade petcoke, particularly where environmental regulations on sulfur content are less developed.
Industry Challenges
- Capital-Intensive Upgrades:The significant capital expenditure required to construct or upgrade delayed coker units and downstream calcination plants presents a high barrier to entry and expansion for producers.
- Logistics and Handling Complexity:Managing the global transportation of a dusty, and sometimes hazardous, bulk material requires specialized port infrastructure, vessels, and dust control measures, adding significant operational costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Petroleum Coke Market |
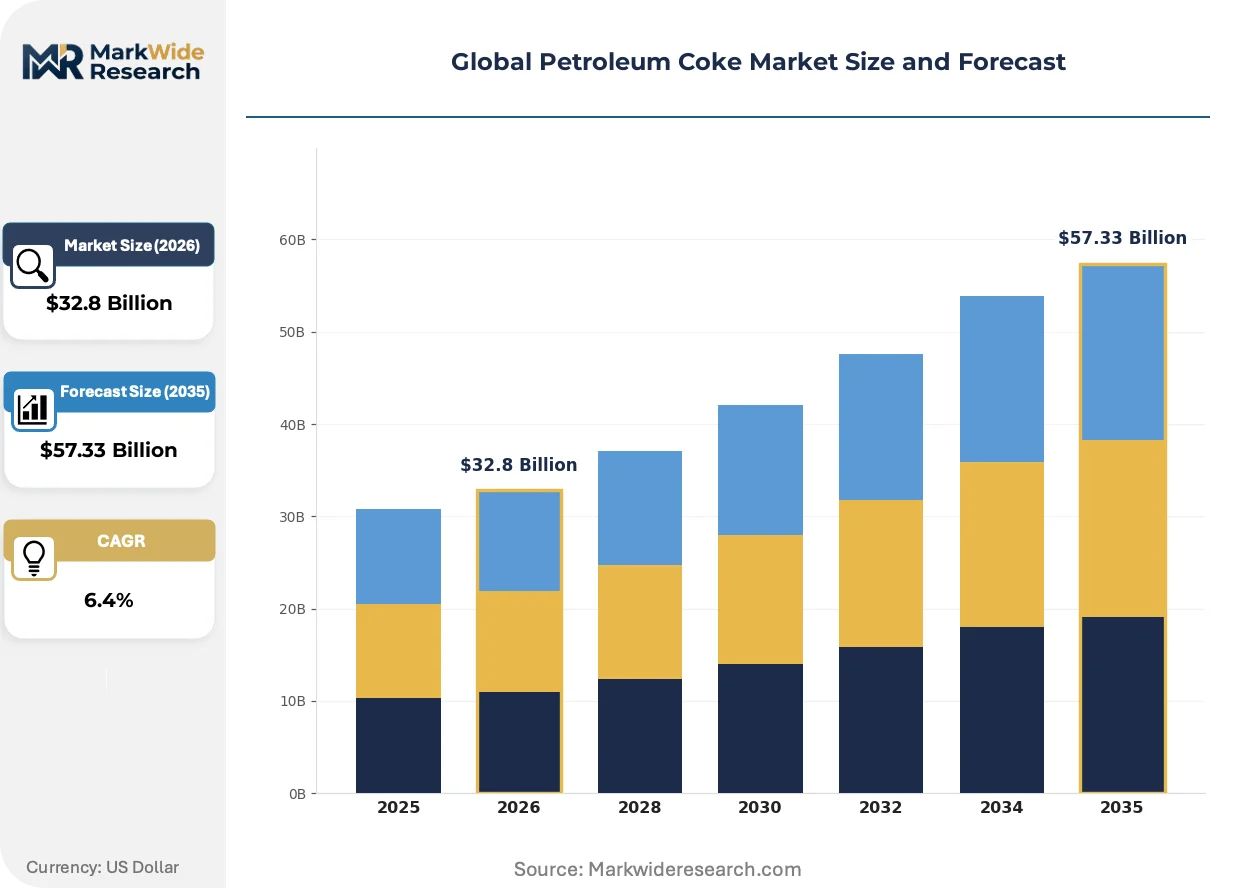
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcined Petcoke, Fuel Petcoke, Sponge Petcoke, Needle Petcoke Application: Power Generation, Cement Manufacturing, Aluminum Production, Steel Manufacturing, Carbon Electrode Fabrication End User Industry: Utilities, Building Materials Manufacturers, Metal Foundries, Carbon Products Manufacturers, Chemical Producers Packaging Type: Bags, Bulk, Pallets, Drums |
| Companies Covered | Marathon Petroleum Corporation, Chevron Corporation, Shell, Saudi Aramco, BP, ExxonMobil, ConocoPhillips, Rain Industries Limited, Valero Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Petroleum Coke Market Strategic Shifts & Innovations
The petroleum coke market is bifurcating into a premium, specification-driven segment and a volatile, energy-content-driven commodity segment. This divergence is driven by a combination of advanced material science, evolving environmental policy, and shifting procurement behaviors in major end-use industries.
Advanced calcination technology transforms green petroleum coke into a highly pure carbon material essential for manufacturing. Major aluminum smelters and specialty carbon producers are the primary adopters, demanding consistent quality for anode production. This technology is expanding into the production of anode materials for lithium-ion batteries, creating a new, high-value application beyond its traditional use in metallurgy.
International Maritime Organization (IMO) regulations limiting sulfur content in marine fuels have profoundly altered refinery economics. This rule diverted high-sulfur fuel oil components away from the bunker fuel market and into coker units, increasing the global supply of high-sulfur petcoke. Consequently, the fuel-grade segment faces persistent supply-side pressure, impacting pricing for cement and power producers.
A clear shift from long-term, fixed-price contracts toward index-linked and spot-market purchasing is transforming fuel-grade petcoke procurement. This change disrupts the historically stable relationships between oil refiners and large industrial consumers like cement manufacturers. The trend is most pronounced in the high-volume import markets of India and Turkey, where buyers seek to leverage market volatility for cost advantages.
Global Petroleum Coke Market Segmentation
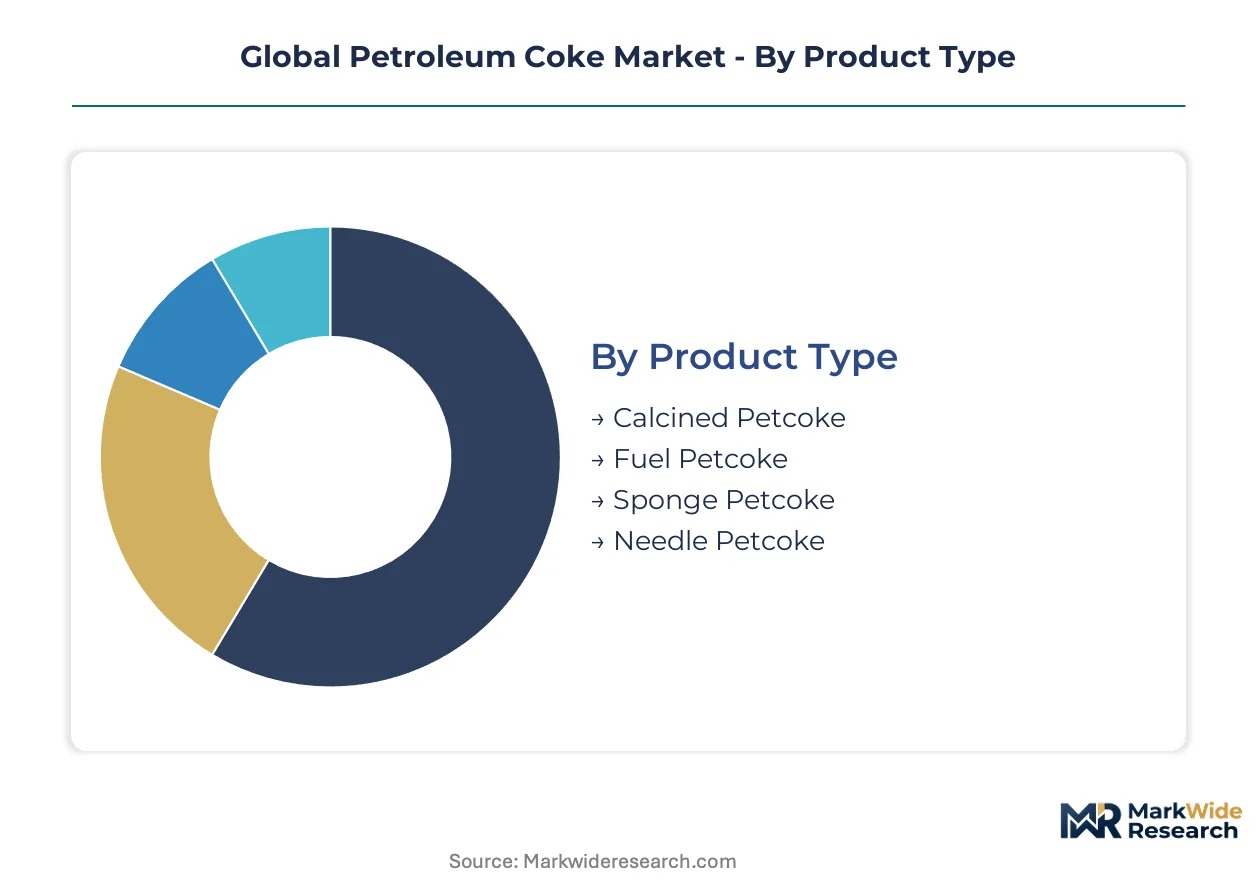
The global petroleum coke market bifurcates across distinct product types, applications, end-user industries, and packaging methods. Each segment possesses unique value propositions and operational requirements, influencing investment decisions and supply chain configurations. Understanding these divisions helps stakeholders identify specialized niches and broad commodity flows.
Product Type:
The capital expenditure required to produce different petroleum coke product types varies significantly, influencing refiner investment strategies and market supply. Downstream processing for high-purity grades demands substantial infrastructure.
- Calcined Petcoke:This high-purity carbon material undergoes thermal treatment to remove volatile matter and moisture. Demand concentrates in global aluminum production, where its consistent quality is critical for anode manufacturing.
- Needle Petcoke:Featuring a highly ordered crystalline structure, needle petcoke is a premium grade with low thermal expansion. Its demand is prominent in advanced carbon electrode fabrication for electric arc furnaces and lithium-ion battery anodes.
- Fuel Petcoke:This commodity-grade petcoke possesses high calorific value, serving as a cost-effective energy source for heavy industries.
- Sponge Petcoke:Characterized by its porous structure, sponge petcoke is used in aluminum smelting and titanium dioxide production.
Fuel Petcoke absorbs the bulk of installed capacity; Needle Petcoke is expanding most quickly.
Application:
The volume requirements for petroleum coke vary widely across its diverse applications, from high-tonnage energy generation to specialized material inputs. This segmentation highlights the scale and scope of demand from different industrial sectors.
- Aluminum Production:This application requires high-purity calcined petroleum coke as a primary raw material for prebaked anodes used in electrolytic reduction cells. Demand is consistently driven by global primary aluminum smelters in China and the Middle East.
- Carbon Electrode Fabrication:Utilizing needle petcoke, this application manufactures electrodes for electric arc furnaces in steelmaking and specialized anodes for advanced battery technologies. Demand is significant in Asia's steel and EV battery industries.
- Power Generation:Fuel-grade petcoke powers industrial boilers and utility plants, particularly in regions with less stringent sulfur emission regulations like India.
- Cement Manufacturing:This sector consumes large volumes of fuel-grade petcoke for its high energy content in kiln operations, especially in India's construction boom.
- Steel Manufacturing:Petcoke finds use as a carbon additive in electric arc furnaces and as a fuel, contributing to the energy needs of steel production.
Aluminum Production drives demand for specialized grades, while Cement Manufacturing consumes the largest volumes of commodity petcoke.
End User Industry:
Customer type segmentation reveals distinct procurement behaviors and quality requirements for petroleum coke. Specialized industries prioritize consistent specifications, while bulk consumers focus on price and calorific value.
- Carbon Products Manufacturers:These specialized firms produce anodes, cathodes, and graphite electrodes, requiring stringent quality control for incoming high-purity petcoke. Their demand is notable in China and Japan for advanced material production.
- Building Materials Manufacturers:This segment, primarily cement producers, purchases large quantities of fuel-grade petcoke for energy generation in kilns. Demand is significant in India, driven by infrastructure development.
- Utilities:Power plants utilize fuel-grade petcoke as a primary or supplementary energy source, especially in countries with lower natural gas availability.
- Metal Foundries:Aluminum smelters are key consumers, requiring calcined petcoke for their anode production processes across the Middle East and North America.
- Chemical Producers:Petcoke serves as a feedstock for various chemical processes, including the production of hydrogen and synthesis gas.
Producers focus on serving Carbon Products Manufacturers with tailored specifications, optimizing logistics for Building Materials Manufacturers.
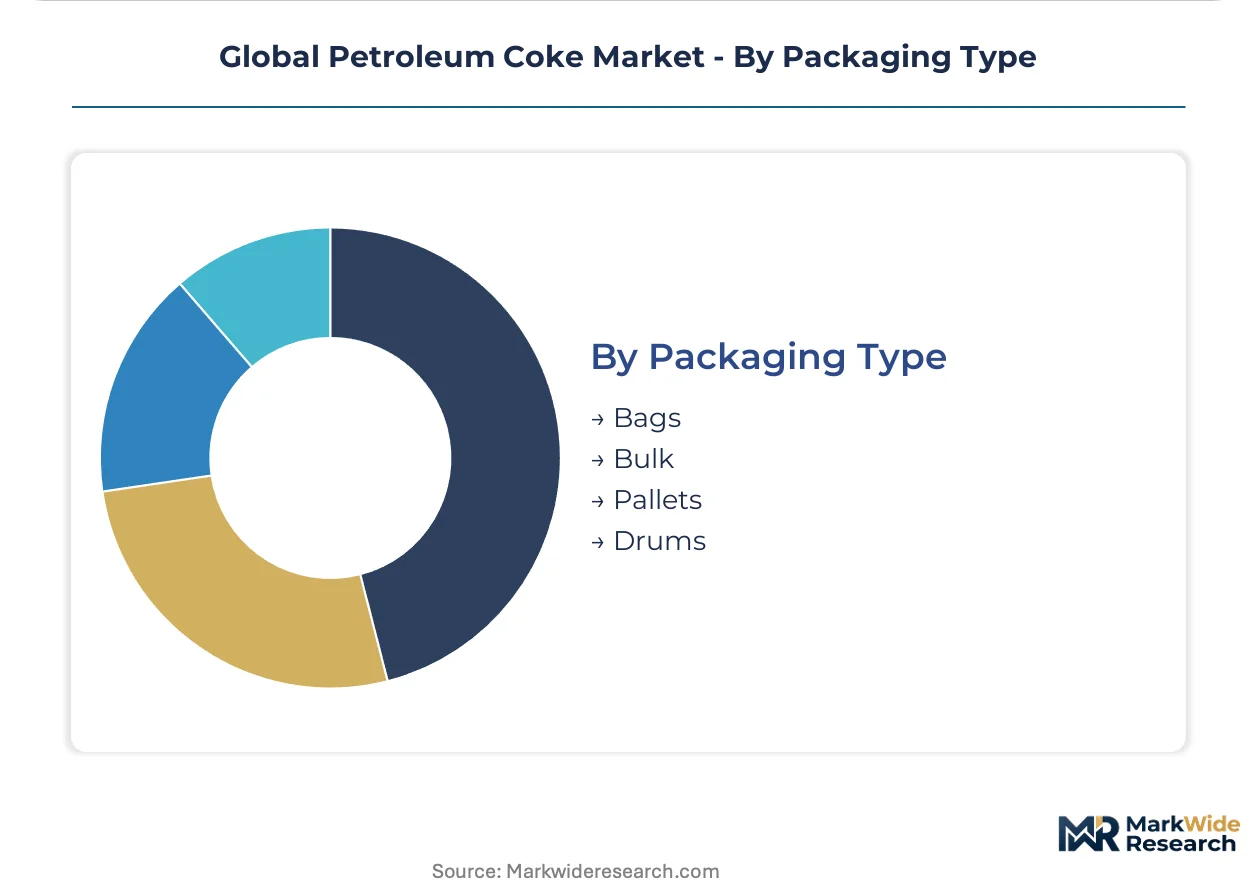
Packaging Type:
The margin profile for petroleum coke varies with its packaging type, reflecting differences in handling costs, transportation efficiency, and end-user requirements. Bulk shipments dominate commodity grades, while specialized packaging supports niche applications.
- Bulk:This packaging method is most common for high-volume, commodity-grade fuel petcoke, transported via ships, rail, or trucks. Its demand is prevalent for large industrial consumers like cement plants and power generators globally.
- Bags:Petcoke packaged in bags typically caters to smaller industrial users or specific applications requiring cleaner handling and precise quantities. This method is common for specialty grades in smaller markets.
- Pallets:Palletized shipments offer improved handling and storage efficiency for intermediate volumes, often used for specific grades in manufacturing facilities.
- Drums:Drums are used for very specialized, high-purity, or sensitive petcoke grades, ensuring protection and controlled dispensing for niche applications.
Efficient handling of Bulk petcoke is crucial for cost management, whereas Drums serve niche, high-value applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's industrial corridors, alongside other major port cities, serve as critical entry points for global petroleum coke trade, particularly for fuel-grade varieties. The market dynamics are heavily influenced by regional industrial demand for energy and materials. Environmental regulations from local and national bodies significantly shape the product mix and consumption patterns across diverse geographies.
India
India's construction boom drives substantial demand for fuel-grade petcoke in cement manufacturing, valued for its calorific content. The Bureau of Indian Standards (BIS) sets quality benchmarks for industrial fuels, influencing petcoke imports. Major cement clusters in Gujarat and Andhra Pradesh are large-volume consumers, integrating petcoke into their energy mix.
China
China's expanding aluminum sector and burgeoning EV battery industry require consistent supplies of high-purity calcined and needle petcoke. The Ministry of Ecology and Environment (MEE) mandates strict sulfur emission controls, impacting fuel-grade petcoke use. Shandong and Henan provinces host significant industrial hubs driving demand for specialized carbon materials.
United States
United States demand for calcined petcoke supports aluminum smelters and specialty carbon applications. The US Environmental Protection Agency (EPA) regulations on sulfur content significantly shape the quality and marketability of fuel-grade petcoke. Refineries along the Gulf Coast are primary production centers, adapting output to meet diverse industrial specifications.
Saudi Arabia
Saudi Arabia represents a significant market for calcined petcoke due to its expanding aluminum production capacity. The Kingdom's industrial development plans encourage efficient resource utilization within its petrochemical complexes. Jubail and Yanbu industrial cities are key consumption hubs, integrating petcoke into their material and energy supply chains.
Netherlands
The Netherlands serves as a key refining and trading hub for petroleum coke, supporting industrial energy needs across Europe. European Union environmental directives, including the F-Gas Regulation, push industries towards lower-emission fuels. The Port of Rotterdam facilitates extensive imports and exports, positioning it as a critical gateway for petcoke distribution.
Global Petroleum Coke Market Key Industry Players
Premium-margin players sit above commodity-margin players across the petroleum coke value chain, driven by product purity and specialized processing capabilities. The market exhibits a tiered structure, with integrated refiners operating alongside specialized calcination and carbon product manufacturers. Strategic archetypes include large-scale integrated oil companies, dedicated calcined coke producers, and regional fuel-grade suppliers. Companies pursue capacity expansion in calcination and strategic partnerships to secure feedstock and distribution channels.
At the scale-driven end, Marathon Petroleum Corporation and Chevron Corporation exemplify integrated oil majors leveraging extensive refining networks to produce diverse petroleum coke grades. These companies control significant upstream production, allowing them to supply various product types to global markets, from high-purity anode-grade to commodity fuel coke. Rain Industries Limited, conversely, represents a specialized producer focused on downstream calcination, transforming green coke into higher-value materials. This strategic positioning allows the company to cater to specific industrial demands for premium carbon products, particularly for aluminum smelting and specialty applications. Shell also operates a complex global logistics network to place different coke qualities into suitable markets, highlighting the importance of distribution.
| Leading Market Players |
|---|
| Marathon Petroleum Corporation |
| Chevron Corporation |
| Shell |
| Saudi Aramco |
| BP |
| ExxonMobil |
| ConocoPhillips |
| Rain Industries Limited |
| Valero Energy |
Cost & Logistics Intelligence
International Maritime Organization (IMO) regulations limiting sulfur content in marine fuels gate qualified supply of high-sulfur petcoke, influencing premium-tier pricing for compliant alternatives. This mandate redirects high-sulfur fuel oil components into coker units, impacting the overall market.
Pricing Analysis
Outcome-based pricing anchors the premium petroleum coke segment, where consistent quality directly impacts aluminum production yields. Price differentiation stems from product purity, particularly for needle coke, and geographic delivery costs to specialized manufacturers. Pricing softness runs through the fuel-grade segment due to persistent supply-side pressure from increased high-sulfur petcoke availability. Cement manufacturers are highly price-sensitive, while carbon products manufacturers prioritize consistent specifications over cost.
Supply Chain Analysis
Dual-sourcing requirements for calcined petcoke ensure supply stability for aluminum smelters, mitigating reliance on single producers. Supply concentration for petroleum coke largely resides in the United States, Saudi Arabia, and the Netherlands, driven by refinery locations. The supply chain relies on heavy crude oil residues as its primary input, alongside specialized coking and calcination technologies. Commodity price volatility for crude oil presents a significant supply chain risk. Distribution runs through a complex global logistics network, primarily via bulk shipping to major industrial hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The petroleum coke market remains a supply-constrained story, particularly for high-purity grades. Limited global calcination capacity for needle coke props pricing for advanced carbon products.
For Market Incumbents: Deploy advanced coker unit efficiency to maximize high-purity green coke feedstock production. Invest in expanding calcination plant capacity to meet the sustained demand from the aluminum sector, countering the threat of volatile fuel substitution. Secure long-term supply contracts with major aluminum smelters to stabilize revenue streams. Focus research and development on improving sulfur removal technologies to comply with evolving environmental regulations, defending market share.
For New Entrants and Emerging Players: The price-point gap between high-purity needle coke and commodity fuel-grade petcoke offers a significant entry opportunity. Target underpenetrated specialty carbon product segments, such as lithium-ion battery anodes, leveraging advanced purification techniques. Industrializing nations in Southeast Asia represent a penetrable geography for fuel-grade petcoke, where environmental regulations are less stringent. A go-to-market angle focused on cost-effective gasification feedstock solutions for lower-quality grades can establish market presence.
For Investors and Strategic Acquirers: Increased capital expenditure announcements for new calcination plants is the leading indicator that supply-side constraints are easing. The market demonstrates long-term viability over the next 5-10 years, driven by sustained demand for aluminum and emerging carbon applications. Target specialized calcined coke producers with proprietary purification technologies. Monitor the expansion of electric arc furnace steelmaking in Asia as a key signal for future needle coke demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Calcination | Meeting the sustained demand from global aluminum smelters requires significant investment in processing infrastructure. |
| Green Manufacturing Transition | Adopting lower-emission technologies addresses stringent environmental regulations from the US EPA and China's MEE. |
| Long-term Supply Agreement | Securing consistent feedstock for carbon product manufacturers stabilizes production and mitigates supply volatility. |
| Joint Venture in Gasification | Developing new outlets for lower-quality fuel-grade petcoke creates higher-value products like synthesis gas. |
| Advanced Purification Techniques | Producing high-purity needle coke supports the burgeoning demand from the lithium-ion battery anode market. |
Research Approach
Multi-period observation of global refining output and petcoke trade flows anchored the trend analysis, supplemented by interviews with refinery operations managers, calcined coke plant directors, and aluminum smelter procurement leads. Primary insights were validated against secondary data from the US EPA, China's MEE reports, and industry association publications. A rigorous process of bottom-up and top-down triangulation ensured data consistency and accuracy across the market.
The input-output matrix framework modeled market dynamics, projecting volume and value across the analysis window. Segmentation included product type, application, end-user industry, and regional environmental policy stringency. Compound annual growth rates were derived through a weighted average of historical trends and projected industrial output. Forecast inputs included global aluminum production forecasts and India's cement manufacturing growth projections.
Underlying measurement precision varies by segment; high-purity calcined petcoke carries tighter precision than commodity fuel-grade varieties. Forecasts reflect assumptions regarding crude oil slate stability and environmental regulation enforcement. A model refresh is warranted upon material change in global refinery upgrading investments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market
Petroleum Products
Oil Shale Market
Petroleum Products
India White Oil Market
Petroleum Products
Asia Pacific Base Oil Market
Petroleum Products
Automotive Oil Market
Petroleum Products
PAG Base Oil Market
Petroleum Products
Longitudinal Submerged-Arc Welded (LSAW) Pipes Market
Petroleum Products
South Africa Lubricants Market
Petroleum Products
East Africa Refined Petroleum Products Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Performance Oil Sales Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Floating Roof Tank Market
Petroleum Products
Australia Refined Petroleum Products Market