
 Orthodontic Equipment Market | 2026-2036
Orthodontic Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Orthodontic Equipment Market Analytics
Clear aligner subscription revenue is rewriting profit pool distribution across the orthodontic value chain. Align Technology leverages its proprietary thermoplastic material science to sustain premium positioning in direct-to-practitioner channels. 3M Company anchors its orthodontic portfolio through global manufacturing scale in conventional bracket systems. Dentsply Sirona competes by integrating intraoral scanning hardware with treatment planning software.
Orthodontic equipment encompasses fixed and removable appliances, diagnostic instruments, and digital systems engineered to correct dental malposition through controlled biomechanical force application, typically utilizing nickel-titanium or stainless-steel alloys with specified activation forces between 50-200 grams. These devices serve the primary commercial purpose of enabling precise tooth movement while minimizing patient discomfort and treatment duration. Digital impressions and CAD/CAM technology command expanding margin pools as chairside workflows reduce laboratory outsourcing costs. Self-ligating brackets occupy a mature growth tier where mechanical efficiency improvements face diminishing returns against premium pricing. 3D printing in aligner fabrication represents the fastest-expanding technology segment as throughput speeds and resin biocompatibility advance.
FDA 510(k) clearance pathways and EU MDR classification for active implantable devices govern market access timelines and clinical evidence requirements for novel orthodontic systems. ISO 13485 quality management standards and national dental board licensing protocols shape practitioner purchasing criteria and distributor qualification hurdles. Stakeholders must monitor regulatory divergence between accelerated approval frameworks for software-driven treatment planning and traditional mechanical device pathways.
Market Dynamics
Clear aligner manufacturing is migrating from centralized fabrication hubs toward distributed chairside production, compressing traditional laboratory intermediaries and redistributing margin capture toward orthodontic practices with in-house 3D printing capability.
Growth Catalysts
- EU MDR Class IIa alignment:Harmonized device classification across European markets is streamlining cross-border product registration for clear aligner systems, reducing redundant clinical testing burdens for manufacturers holding CE marking.
- Nickel-titanium archwire demand:Superelastic alloy formulations with optimized activation force ranges are expanding treatment applicability to complex malocclusion cases previously requiring surgical intervention.
- Adult aesthetic preference:Patient segments over age 35 in orthodontic clinics are selecting lingual brackets and transparent polymer systems at rates that reshape practitioner equipment procurement priorities.
Market Restraints
- Photopolymer resin supply concentration:Medical-grade aligner fabrication materials depend on specialty chemical production concentrated in German and Japanese suppliers, exposing manufacturers to input cost volatility and allocation constraints.
- FDA 510(k) clinical evidence requirements:Novel biomechanical force systems face extended regulatory timelines compared to predicate device pathways, delaying market entry for incremental bracket design innovations.
- Direct-to-consumer aligner substitution:Remote orthodontic monitoring platforms are capturing price-sensitive patient segments that conventional practices and their equipment suppliers previously served.
Strategic Opportunities
- India dental infrastructure buildout:Government health insurance expansion into orthodontic coverage is creating first-mover advantage for equipment suppliers establishing distribution partnerships with emerging clinic chains in tier-2 cities.
- Intraoral scanner-AI convergence:Real-time treatment outcome simulation combining hardware capture with predictive modeling software is enabling case acceptance rates that justify premium equipment pricing.
- US IRA preventive care incentives:Tax-advantaged health savings account expansion for orthodontic services is shifting patient payment timing in ways that favor equipment financing arrangements for practice owners.
Industry Challenges
- Digital workflow integration:Orthodontic practices face capital deployment decisions between closed ecosystem scanner-aligner systems and open-architecture alternatives with uncertain interoperability standards.
- Biocompatibility certification timelines:ISO 10993 testing protocols for novel thermoplastic materials are extending product development cycles beyond traditional metal appliance innovation cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthodontic Equipment Market |
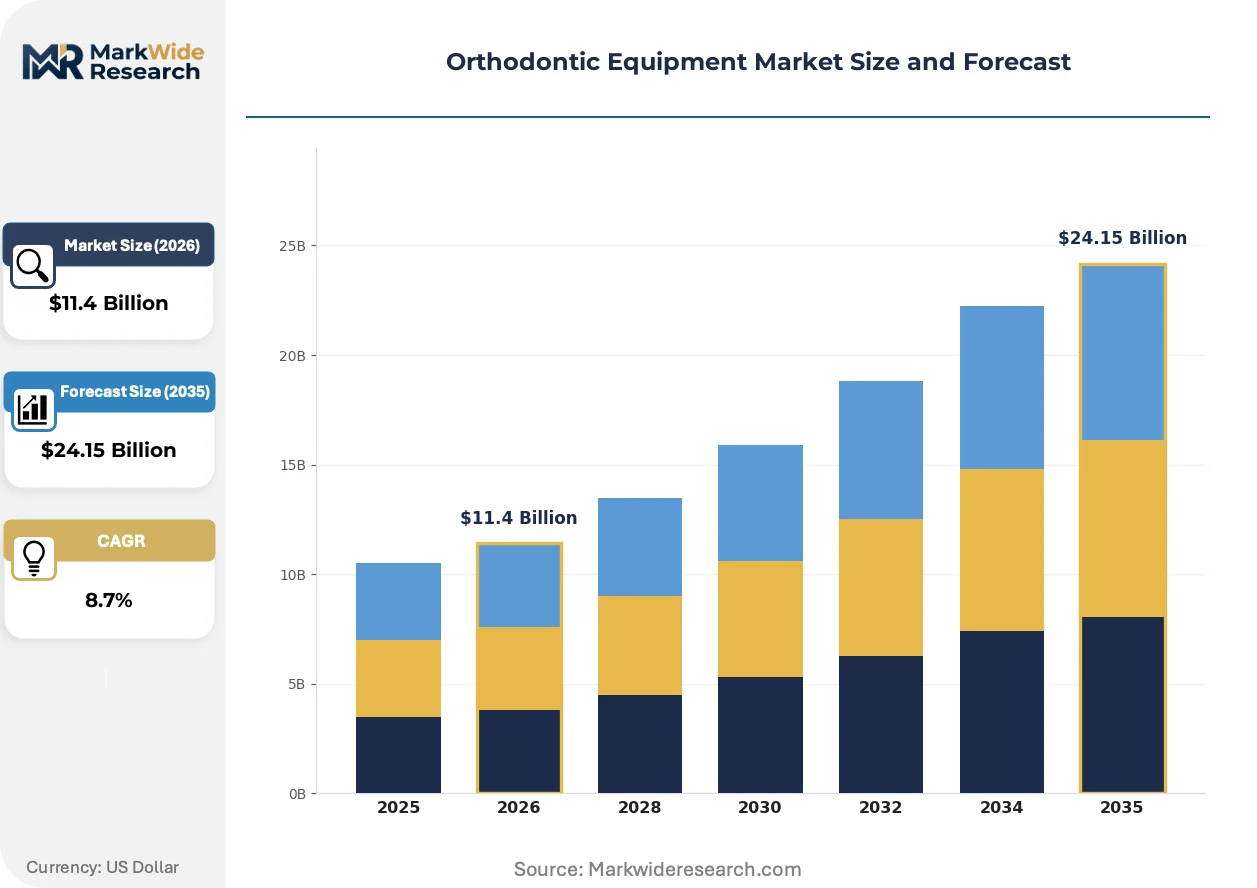
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brackets, Archwires, Bands, Buccal Tubes Technology: Digital Impressions, 3D Printing, Self-Ligating, CAD/CAM End User: Orthodontic Clinics, Dental Hospitals, Academic Institutions, Home Care Application: Malocclusion Treatment, Preventive Care, Cosmetic Adjustments, Interceptive Care |
| Companies Covered | Align Technology, 3M Company, Dentsply Sirona, Envista Holdings Corporation, Henry Schein, American Orthodontics, Ormco Corporation, Patterson Companies, Institut Straumann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthodontic Equipment Market Evolving Landscape
Orthodontic equipment design is converging around patient-specific biomechanical optimization, with digital fabrication methods displacing standardized appliance inventories and enabling mass customization at unit economics competitive with conventional production.
AI-powered treatment planning software is migrating from cloud-based subscription models toward embedded edge computing in intraoral scanning hardware. Mid-sized orthodontic practices in Germany and the United States are adopting these integrated systems to reduce per-case data transmission latency and maintain patient record control. This architecture shift is compressing the addressable market for standalone software vendors while expanding hardware attachment rates for scanner manufacturers.
EU MDR technical documentation requirements for active implantable devices are compelling orthodontic manufacturers to restructure quality management systems around post-market clinical follow-up protocols. Device sponsors must now maintain systematic registries tracking long-term material degradation in intraoral environments. Small-to-mid tier bracket suppliers without existing clinical affairs infrastructure are outsourcing regulatory compliance to specialized consultancies, fragmenting market access pathways.
Subscription-based aligner procurement is displacing per-case ordering among multi-location orthodontic groups seeking to stabilize monthly cash outflows. Large practice management organizations in Texas, Florida, and California are negotiating volume-commitment contracts that bundle hardware, consumables, and remote monitoring services. This purchasing consolidation is pressuring independent distributors and favoring direct manufacturer relationships with procurement decision-makers at corporate dental entities.
Orthodontic Equipment Market Segmentation
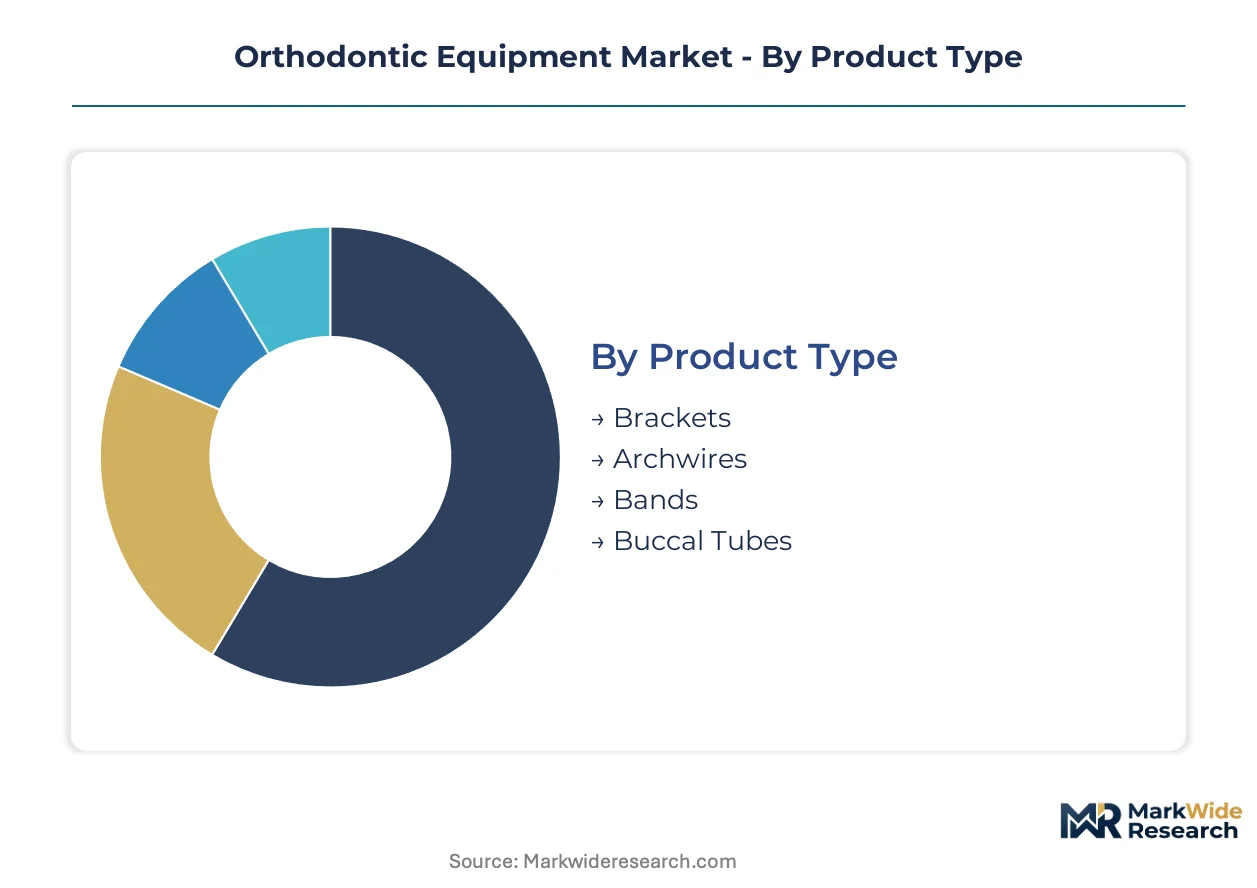
Orthodontic equipment segmentation reveals divergent margin profiles across mechanical versus digital modalities. Product architecture choices determine whether manufacturers capture value through precision metal fabrication or software-enabled treatment customization.
Product Type:
Mature bracket systems anchor volume economics while emerging aligner platforms reshape revenue composition.
- Brackets:Stainless steel and ceramic brackets deliver controlled force application through bonded attachment points with prescribed slot dimensions. Demand concentrates in Germany and China where orthodontic clinic density supports high-volume bracket procurement. Self-ligating variants command premium positioning against conventional ligature-dependent designs.
- Archwires:Nickel-titanium alloys with superelastic properties enable continuous light force delivery across broad activation ranges. United States orthodontic practices prioritize thermally activated formulations that reduce appointment frequency and chair time. Archwires represent the consumable foundation of fixed appliance therapy with recurring replacement cycles.
- Bands:Pre-formed stainless steel rings cemented to molars provide anchorage for auxiliary appliances.
- Buccal Tubes:Welded or bonded attachments on molar bands facilitate headgear and auxiliary force systems.
Brackets retain volume leadership; archwires hold the steepest expansion curve through alloy formulation advances.
Technology:
Cost tier stratification separates capital-intensive digital infrastructure from accessible mechanical innovations.
- Digital Impressions:Intraoral scanning hardware captures three-dimensional dental anatomy with sub-millimeter accuracy, eliminating physical impression materials and laboratory shipping delays. United States and German orthodontic clinics deploy these systems to compress treatment initiation timelines and improve patient comfort metrics. Scanner-software bundles dominate procurement decisions among multi-location practice groups.
- 3D Printing:Photopolymer resin systems fabricate aligner molds and indirect bonding trays at chairside or centralized production facilities. China-based equipment suppliers are expanding resin formulation portfolios to reduce dependence on German and Japanese chemical inputs. Throughput speed improvements are narrowing the unit cost gap with thermoforming methods.
- Self-Ligating:Passive and active clip mechanisms reduce friction and appointment intervals in fixed appliance therapy.
- CAD/CAM:Computer-aided design and manufacturing link diagnostic imaging directly to appliance production workflows.
Digital impressions retain volume leadership; 3D printing holds the steepest expansion curve.
End User:
Customer type determines equipment specification requirements and purchasing authority structures.
- Orthodontic Clinics:Specialized practices concentrate demand for comprehensive fixed and removable appliance portfolios with integrated digital workflow capability. United States clinic chains in Texas and California negotiate enterprise procurement contracts bundling hardware, consumables, and remote monitoring services. Capital deployment decisions favor closed-ecosystem scanner-aligner systems with predictable interoperability.
- Dental Hospitals:Academic medical centers and public hospital dental departments prioritize durable mechanical systems with established maintenance protocols and training infrastructure.
- Academic Institutions:Dental schools require equipment platforms supporting standardized curriculum delivery and research reproducibility.
- Home Care:Remote orthodontic monitoring platforms serve price-sensitive patient segments with reduced clinical touchpoint frequency.
Orthodontic clinics retain volume leadership; home care holds the steepest expansion curve.
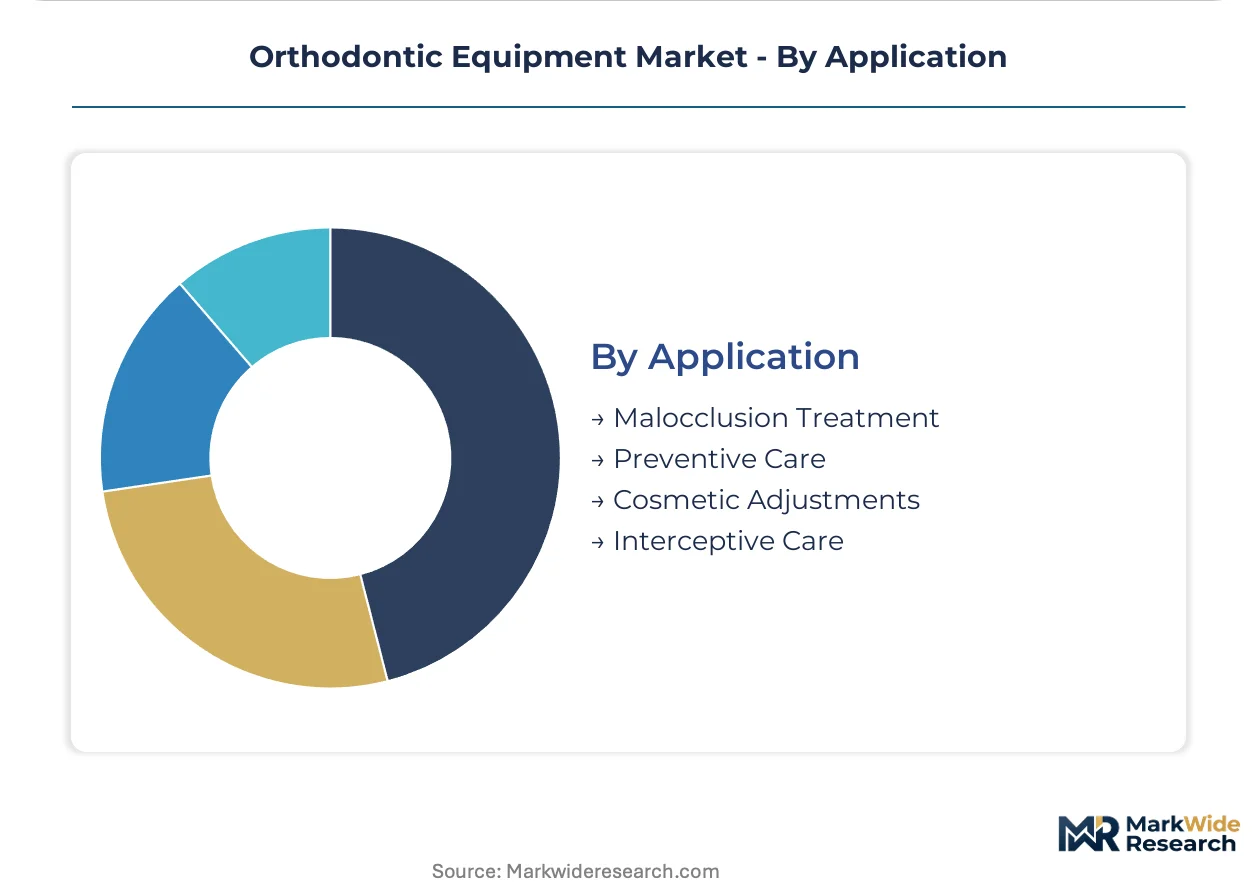
Application:
Margin concentration varies across therapeutic versus elective procedure categories.
- Malocclusion Treatment:Corrective therapy for dental and skeletal misalignment represents the clinical foundation of orthodontic practice with established reimbursement pathways. Complex case referrals concentrate in United States and German academic centers with surgical-orthodontic collaboration infrastructure.
- Cosmetic Adjustments:Elective aesthetic enhancement drives clear aligner demand among adult patient segments over age 35 seeking discreet treatment modalities. China and United States markets exhibit strongest preference for transparent polymer systems and lingual bracket configurations.
- Preventive Care:Early intervention protocols address developing malocclusion in pediatric populations.
- Interceptive Care:Growth modification appliances guide craniofacial development during mixed dentition stages.
Malocclusion treatment retains volume leadership; cosmetic adjustments hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthodontic equipment consumption patterns diverge sharply between mature digital infrastructure markets and economies where fixed appliances still dominate patient access. The United States and Germany prioritize chairside digital workflows and clear aligner platforms, while China and India concentrate procurement on conventional bracket-archwire systems serving volume-driven clinic expansion.
United States
Adult aesthetic demand and employer-sponsored dental benefits drive premium equipment procurement across Texas and California clinic chains. FDA 510(k) clearance pathways govern clear aligner system market access, with software-driven treatment planning facing accelerated review timelines compared to mechanical devices. Dallas-Fort Worth orthodontic groups negotiate enterprise scanner-aligner bundles that compress per-case technology costs.
Germany
EU MDR Class IIa harmonization streamlines cross-border product registration for aligner manufacturers holding CE marking. Superelastic nickel-titanium archwire formulations from Bavarian metallurgy suppliers serve complex malocclusion cases across Central European academic centers. Munich-based orthodontic practices integrate intraoral scanning with CAD/CAM production to minimize laboratory outsourcing.
China
NMPA medical device registration and provincial health insurance expansion into orthodontic coverage stimulate equipment demand in tier-2 cities. Yangtze River Delta manufacturing clusters produce photopolymer resins and 3D printing hardware for domestic aligner fabrication. Shanghai orthodontic chains adopt chairside production systems to reduce dependence on centralized laboratory networks.
India
Government health insurance expansion into orthodontic coverage creates first-mover opportunities for equipment suppliers partnering with emerging clinic chains. CDSCO medical device rules govern import registration for foreign-manufactured brackets and archwires. Maharashtra dental infrastructure buildout concentrates procurement decisions in Mumbai and Pune metropolitan markets.
Japan
PMDA quality management standards and aging demographic demand for discreet adult treatment options reshape equipment specifications. Tokyo-Osaka orthodontic corridors prioritize lingual bracket systems and transparent polymer aligners for professional patient segments. METI industrial policy supports domestic 3D printing resin development to reduce import dependence.
Orthodontic Equipment Market Competitive Landscape
Capability concentration sits with digital-integrated specialists; scale advantage sits with diversified dental conglomerates. The market structure separates into three functional tiers: proprietary material science holders, hardware-software integrators, and distribution-anchored full-line suppliers. Competitive dynamics revolve around M&A activity targeting digital workflow capabilities and strategic partnerships bridging scanner manufacturing with aligner fabrication.
Within the material-science tier, Align Technology exemplifies proprietary thermoplastic positioning. Among diversified dental technology groups, Dentsply Sirona occupies integration-focused positioning. 3M Company represents manufacturing-scale anchoring in conventional mechanical systems. These three archetypes illustrate divergent paths to margin capture across digital and mechanical modality segments.
| Leading Market Players |
|---|
| Align Technology |
| 3M Company |
| Dentsply Sirona |
| Envista Holdings Corporation |
| Henry Schein |
| American Orthodontics |
| Ormco Corporation |
| Patterson Companies |
| Institut Straumann |
| Others |
Value Network & Pricing Analysis
German and Japanese photopolymer resin suppliers anchor upstream concentration in clear aligner fabrication, directing margin capture toward orthodontic practices with in-house 3D printing capability and compressing traditional laboratory intermediaries. This concentration creates pricing leverage for specialty chemical producers while forcing equipment manufacturers to absorb input volatility or pass through to clinic buyers.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between multi-location orthodontic groups and aligner manufacturers, with volume-commitment bundles spanning hardware, consumables, and remote monitoring services. Price differentiation rests on ISO 13485 certification tier and customization depth, with FDA-cleared systems commanding substantial premiums over CE-marked alternatives. Cost compression in standard bracket systems is intensifying because Chinese manufacturing scale is flooding mid-tier distribution channels. Corporate dental entities in Texas and Florida exhibit lowest price sensitivity due to enterprise purchasing power, while independent single-practice orthodontists face acute margin pressure from subscription-based aligner procurement.
Supply Chain Analysis
Export-control restrictions on precision photopolymer formulations limit resin flows from German and Japanese specialty chemical producers to emerging Asian fabrication hubs. Manufacturing capacity concentrates in China, Germany, and the United States, with Yangtze River Delta clusters producing 3D printing hardware and Bavarian metallurgy suppliers dominating nickel-titanium archwire feedstock. Raw material dependencies center on medical-grade thermoplastics, superelastic alloys, and optical-grade resins. Single-source vulnerability from concentrated photopolymer supply creates exposure to allocation constraints during demand surges. Distribution runs through direct manufacturer relationships with corporate dental procurement officers, bypassing independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multi-location orthodontic groups and corporate dental entities, with enterprise procurement contracts displacing traditional distributor relationships across Texas, Florida, and California markets.
For Market Incumbents: Insulate proprietary material science positions through backward integration into photopolymer resin development, reducing dependence on German and Japanese chemical suppliers. Lock in enterprise procurement relationships with volume-commitment contracts bundling scanner hardware, aligner consumables, and AI-powered treatment planning software. Direct-to-consumer aligner substitution and regulatory divergence between FDA 510(k) and EU MDR pathways threaten established margin structures. For New Entrants and Emerging Players: Pursue white-space opportunities in India's tier-2 city clinic buildout, where government health insurance expansion into orthodontic coverage is outpacing established supplier distribution networks. Target chairside 3D printing hardware for mid-sized practices seeking to escape closed-ecosystem scanner-aligner dependencies. A software-agnostic aligner fabrication platform with open-architecture interoperability offers the most penetrable entry angle against incumbent ecosystem lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward digital-integrated specialists with embedded AI treatment planning and proprietary thermoplastic portfolios, rather than mechanical bracket manufacturers facing diminishing innovation returns. Long-term viability across the analysis window favors companies bridging intraoral scanning hardware with predictive modeling software. The inflection signal to watch is FDA 510(k) clearance velocity for novel biomechanical force systems, which would validate accelerated regulatory pathways and unlock premium valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa alignment streamlines cross-border registration for aligner manufacturers. |
| Hospital System Partnership | Academic medical center collaborations build surgical-orthodontic referral infrastructure. |
| Software Companion Development | AI-powered treatment planning embedded in intraoral scanners compresses standalone software markets. |
| Reimbursement Strategy | US IRA preventive care incentives reshape patient payment timing for practice equipment financing. |
| Backward Integration | In-house photopolymer resin development reduces exposure to German and Japanese supply concentration. |
Research Methodology
The analysis maps fixed appliance systems, clear aligner platforms, digital impression hardware, and 3D printing fabrication methods, each validated through orthodontic practice owners, dental group procurement officers, biomedical engineers, and regulatory affairs specialists at aligner manufacturers. Primary interview intelligence triangulates against FDA 510(k) filings, EU MDR technical documentation, NMPA registration databases, and hospital procurement contract records. Bottom-up equipment unit economics and top-down market sizing reconstructions cross-validate volume and value estimates.
Assumptions held fixed include current regulatory classification pathways, existing photopolymer resin supply concentration, and prevailing reimbursement frameworks across analyzed geographies. The projection framework models product type, technology modality, end-user customer type, and application purpose dimensions. CAGRs derive from segmented growth rate analysis applied to base-year market estimates. Forecast inputs incorporate nickel-titanium alloy formulation advances, intraoral scanner-AI convergence adoption curves, and adult aesthetic preference shifts toward transparent polymer systems.
Sensitivities concentrate around EU MDR post-market clinical follow-up protocol stringency, FDA software-driven treatment planning review acceleration, and photopolymer resin supply allocation disruptions. Forecasts reflect documented assumptions on regulatory timelines, material biocompatibility certification cadences, and digital workflow interoperability standards. Material shifts in FDA-EU regulatory divergence, photopolymer supply chain restructuring, or direct-to-consumer aligner platform viability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wearable Defibrillators Market
Medical Devices
IV Therapy and Vein Access Devices Market
Medical Devices
Sleeve Gastrectomy Devices Market
Medical Devices
US C-Arms Market
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
MRI Guided Drug Delivery Market
Medical Devices
Laparoscopic Devices Market
Medical Devices
Compression Therapy Devices Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
Intraoral Scanners Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Bioactive Fillings Market
Medical Devices
Cervical Retractors Market