
 Asia Pacific Base Oil Market | 2026-2036
Asia Pacific Base Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Base Oil Market Insights
The Asia Pacific base oil landscape is shifting along a widening quality divide. Premium Group II and Group III grades command stronger margins as automotive OEMs enforce tighter viscosity specifications, while commodity Group I volumes face structural compression. Exxon Mobil Corporation leverages integrated refining and lubricant manufacturing positions across Thailand and Singapore to secure captive offtake. SK Enmove anchors South Korea's export-oriented base oil complex, sustaining capacity utilization through long-term supply contracts with Japanese and Southeast Asian blenders. Indian Oil Corporation Ltd. competes on domestic scale, operating the largest Group I base oil refinery in India while navigating gradual portfolio upgrading.
Base oil constitutes refined petroleum or synthetic hydrocarbon stock formulated as the primary fluid component in lubricants, with viscosity index, pour point, and oxidation stability determining performance classification under API Group designations. Hydrocracking technology yields Group II and III stocks with sulfur below 0.03 percent and viscosity indexes exceeding 110, serving the dominant automotive lubricant application where OEM drain interval extensions require thermal stability. Group III production occupies the fastest-expanding margin pool as Japanese and Korean automakers specify 0W-20 and 0W-16 grades, while Group I solvent-refined capacity matures across older Chinese and Indian facilities facing feedstock cost pressure. Metalworking fluids represent a structurally stable industrial application segment, with synthetic and semi-synthetic formulations displacing neat oil systems in precision manufacturing across Taiwan and Vietnam.
China's MIIT enforces dual carbon targets that constrain new Group I capacity approvals while incentivizing hydrocracker investments, and India's BIS lubricant standards mandate minimum performance tiers that elevate Group II baseline demand. REACH-equivalent chemical registration frameworks emerging across ASEAN jurisdictions shape market access requirements for imported additive packages and finished lubricants. Stakeholders must monitor refinery upgrade timelines in South Korea and Singapore against Japanese OEM specification evolution to align capacity commitments with premium grade demand trajectories.
Market Dynamics
Asia Pacific base oil markets are compressing around a quality bifurcation where hydrocracking investments in South Korea and Singapore pull premium capacity eastward while aging solvent-refining assets in India and China face accelerated obsolescence under tightening emission protocols.
Growth Catalysts
- MIIT dual carbon enforcement:China's Ministry of Industry and Information Technology constrains new Group I approvals while incentivizing hydrocracker construction, redirecting capital toward Group II and III capacity expansion.
- Automotive OEM viscosity specifications:Japanese and Korean automakers mandate 0W-16 and 0W-20 lubricant grades, forcing blenders to source higher viscosity index base stocks from specialized East Asian refiners.
- BIS lubricant standard tiering:India's Bureau of Indian Standards establishes minimum performance baselines that elevate Group II offtake across domestic automotive lubricant formulators.
Market Restraints
- Feedstock cost volatility:Vacuum gas oil and heavy neutral feedstocks track crude differentials that compress margins for Group I operators lacking integrated hydrocracking capability.
- Supply concentration in East Asian refining clusters:South Korea and Singapore control disproportionate premium base oil export capacity, exposing buyers to single-source dependency risks during turnaround seasons.
- Group III technical ceiling:Current hydrocracker catalyst systems cannot economically reach API Group III+ specifications without prohibitively expensive wax isomerization add-ons.
Strategic Opportunities
- Vietnam precision manufacturing expansion:Synthetic and semi-synthetic metalworking fluid demand rises as Taiwanese and Japanese machinery suppliers establish machining clusters around Hanoi and Ho Chi Minh City.
- ASEAN REACH-equivalent frameworks:Emerging chemical registration requirements create first-mover advantages for additive package suppliers pre-positioning compliant lubricant formulations.
- Re-refining technology convergence:Advanced vacuum distillation and hydrotreating of used lubricants is unifying circular supply chains with virgin base oil distribution networks in Japan and South Korea.
Industry Challenges
- Hydrocracker catalyst engineering expertise:Refiners struggle to recruit process specialists capable of optimizing selective cracking severity for consistent Group III yield structures.
- Multi-standard certification timelines:Lubricant blenders face overlapping BIS, JIS, and OEM factory fill approval cycles that delay product commercialization by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Base Oil Market |
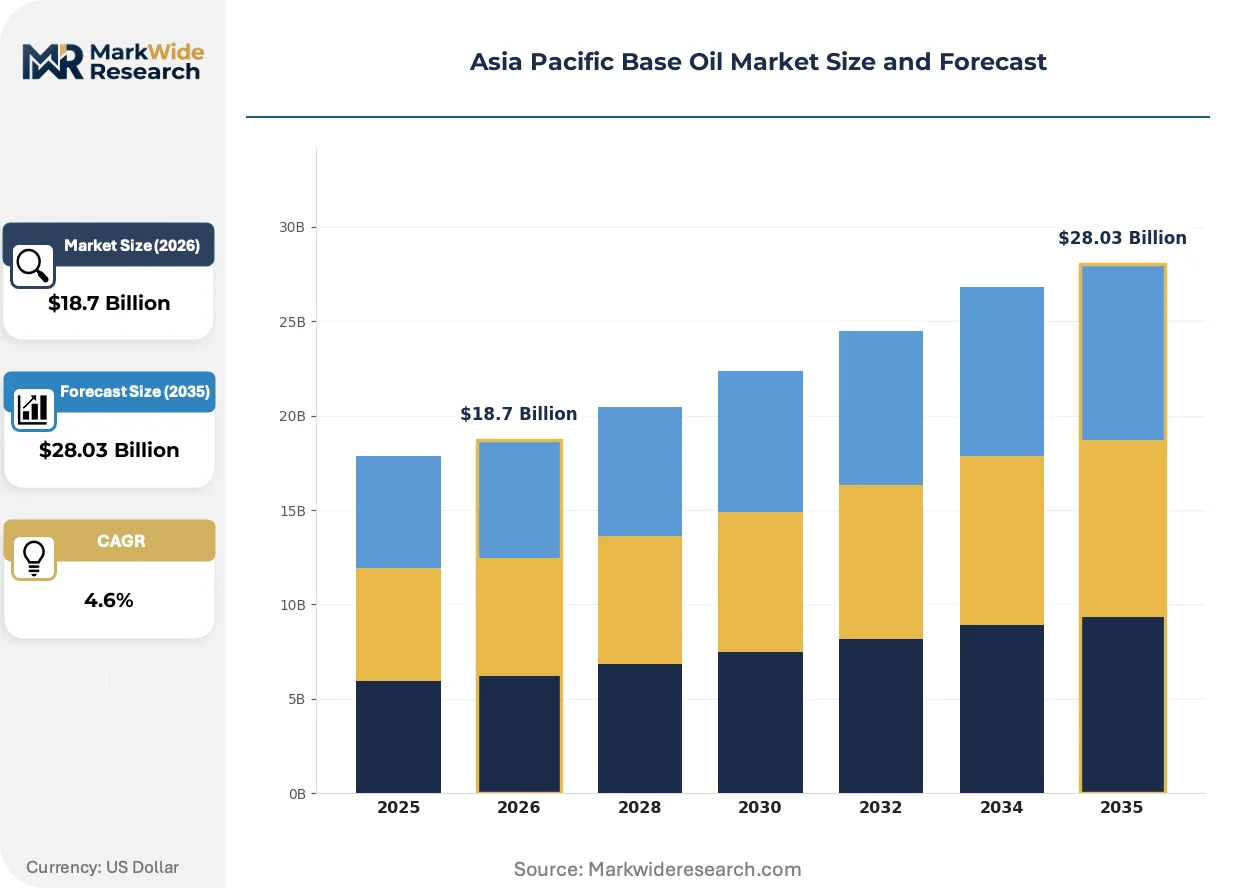
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Group I, Group II, Group III, Group IV Application: Automotive Lubricants, Industrial Lubricants, Metalworking Fluids, Hydraulic Oils Technology: Hydrocracking, Solvent Extraction, De-waxing, Base Oil Blending End User: OEMs, Aftermarket, Marine, Power Generation |
| Companies Covered | Exxon Mobil Corporation, Chevron Corporation, GS Caltex Corporation, China Petrochemical Corporation, S-Oil Corporation, Petroliam Nasional Berhad, Indian Oil Corporation Ltd., SK Enmove, Neste, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Base Oil Market Trends and Innovations
Base oil production technology and procurement patterns are diverging sharply between premium hydrocracked grades and legacy solvent-refined stocks, with digital supply chain tools emerging as the coordinating layer between fragmented buyers and concentrated suppliers.
Hydrocracking catalyst systems with integrated dewaxing functionality are unifying the production of Group II and Group III base oils within single-train refinery configurations. South Korean refiners deploy these systems to swing output between automotive and industrial lubricant feedstocks based on real-time margin signals. The structural consequence compresses the premium commanded by Group III relative to high-quality Group II, narrowing the historical price band between API classifications.
China's MIIT dual carbon goals enforce carbon intensity benchmarks that disqualify new Group I capacity from provincial development approvals. Refiners respond by retrofitting existing solvent-refining units with hydrogenation stages or mothballing uneconomic assets entirely. The policy most affects inland Chinese facilities serving domestic industrial lubricant markets, accelerating import dependency for automotive-grade stocks.
Japanese OEM procurement teams now specify lubricant performance through drain interval guarantees rather than base oil group minimums, forcing blenders to certify formulations through extended field trials. This behavioral shift elevates the importance of additive system compatibility testing over base oil origin claims. The pattern concentrates most visibly among Toyota and Honda supply chains, where 100,000-kilometer service intervals have become standard contract terms.
Asia Pacific Base Oil Market Segmentation
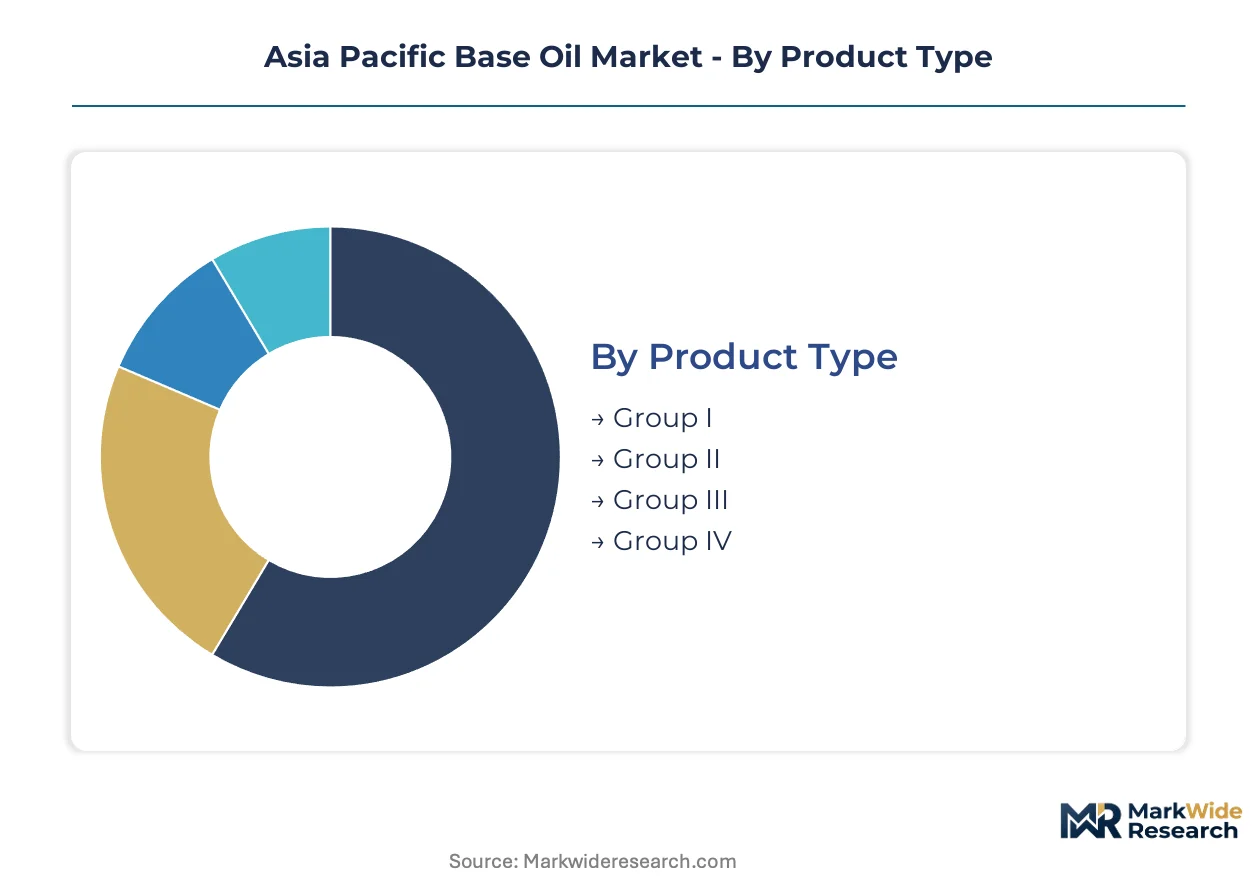
Base oil procurement in Asia Pacific diverges sharply across specification tiers, with automotive OEMs demanding hydrocracked grades while industrial buyers tolerate solvent-refined stocks. Segment boundaries increasingly blur as refiners deploy swing capacity between Group II and III production.
Product Type:
Customization intensity rises from commodity Group I through specialized Group IV synthetics, with mid-tier hydrocracked grades commanding the largest capital deployment.
- Group I:Solvent-refined base stocks with sulfur above 0.03 percent and viscosity indexes below 120 serve legacy industrial lubricant formulators in inland China and India. Aging capacity faces MIIT carbon intensity benchmarks that block new project approvals.
- Group II:Hydrocracked stocks achieve sulfur below 0.03 percent and viscosity indexes of 110-119, anchoring automotive lubricant supply chains across Thailand and Indonesia. South Korean refiners optimize these units for maximum throughput.
- Group III:Severe hydrocracking yields viscosity indexes exceeding 120 for 0W-16 and 0W-20 engine oils specified by Japanese automakers. Singapore and South Korea concentrate export-oriented capacity.
- Group IV:Polyalphaolefin synthetics serve extreme-temperature aerospace and racing applications with limited regional production.
Most installed capacity flows through Group II. Expansion is steepest in Group III.
Application:
Volume concentration tilts toward automotive service fill, though industrial segments retain structural importance in manufacturing-intensive economies.
- Automotive Lubricants:Engine and transmission oils consume the majority of Group II and III offtake as OEM drain intervals extend. Chinese and Indian emission norms tighten viscosity specifications.
- Industrial Lubricants:Compressor and gear oils in steel and cement plants absorb residual Group I supply. Demand concentrates in China's rust-belt provinces.
- Metalworking Fluids:Synthetic and semi-synthetic coolants displace neat oils in Taiwanese and Japanese machining clusters around Hanoi and Ho Chi Minh City.
- Hydraulic Oils:Construction and mining equipment fleets across Australia and Indonesia drive steady Group II consumption.
Automotive lubricants dominate volume. Metalworking fluids are climbing the fastest.
Technology:
Capital intensity separates batch-mode legacy units from continuous hydrocracking trains with integrated dewaxing.
- Hydrocracking:Dual-stage hydrogenation and cracking units with selective dewaxing catalysts produce Group II and III stocks in single-train configurations. South Korean refiners lead catalyst optimization.
- Solvent Extraction:Furfural or N-methyl-2-pyrrolidone separation of aromatics yields Group I base stocks. Chinese inland facilities face rising feedstock costs.
- De-waxing:Catalytic dewaxing or solvent-based wax removal adjusts pour points for cold-climate lubricants. Integrated with hydrocracking for premium grades.
- Base Oil Blending:In-line mixing of base stocks with additive packages produces finished lubricants. Singapore and Thailand host major blending hubs.
Most investment flows through hydrocracking. De-waxing integration is gaining share fastest.
End User:
Specification authority concentrates with OEM factory fill approvers, while aftermarket buyers prioritize cost over performance certification.
- OEMs:Toyota, Honda, and Hyundai specify 100,000-kilometer drain intervals requiring Group III base stocks with additive compatibility certification. Procurement teams mandate field trial validation.
- Aftermarket:Independent workshops and retail channels across India and Southeast Asia absorb Group II volumes. Price sensitivity limits premium grade penetration.
- Marine:Cylinder and system oils for container shipping face IMO sulfur regulations affecting base oil selection. Singapore bunkering hub concentrates demand.
- Power Generation:Gas turbine and transformer oils require high oxidation stability. Australian and Japanese utilities specify narrow viscosity ranges.
Aftermarket channels handle most volume. OEM specification is tightening fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea and Singapore concentrate premium hydrocracking capacity, while China and India grapple with legacy solvent-refining obsolescence under tightening emission protocols. This divergence shapes procurement patterns across the region.
China
MIIT dual carbon enforcement blocks new Group I capacity approvals in inland provinces while redirecting investment toward hydrocracker retrofits. Vacuum gas oil feedstock costs pressure older solvent-refining units in Shandong and Liaoning. The Yangtze River Delta absorbs imported Group III stocks for automotive lubricant blending.
India
BIS lubricant standard tiering elevates Group II baseline demand among domestic formulators serving passenger vehicle OEMs. Indian Oil Corporation operates the largest Group I refinery while navigating gradual portfolio upgrading. Gujarat and Maharashtra host the principal blending clusters for aftermarket distribution.
South Korea
SK Enmove anchors export-oriented hydrocracking capacity serving Japanese and Southeast Asian blenders. Ulsan refining complexes sustain utilization through long-term supply contracts. The country concentrates regional catalyst optimization expertise for selective cracking severity.
Singapore
Jurong Island hydrocracking trains swing output between Group II and III grades based on real-time margin signals. The city-state functions as the dominant bunkering hub for marine lubricant demand under IMO sulfur regulations. Exxon Mobil leverages integrated refining positions for captive offtake.
Japan
Toyota and Honda procurement teams mandate 100,000-kilometer drain interval guarantees rather than base oil group minimums. Chubu and Kansai machining clusters drive synthetic metalworking fluid demand. METI standards shape additive package registration requirements for finished lubricants.
Asia Pacific Base Oil Market Competitive Landscape
Top-tier vendors anchor integrated refining-lubricant positions, while mid-scale operators compete on domestic scale and export contract reliability. The structure concentrates around three strategic archetypes: multinational integrated majors with captive supply chains, national oil companies leveraging domestic distribution networks, and specialized East Asian refiners optimized for premium grade exports. Capacity expansion and backward integration into vacuum gas oil sourcing represent the dominant competitive vectors.
Within the integrated multinational tier, Exxon Mobil Corporation exemplifies refinery-to-blender coordination across Thailand and Singapore. Chevron Corporation occupies a position among North American majors with Asia-Pacific distribution reach. SK Enmove anchors the specialized premium refiner archetype, representing South Korea's export-focused hydrocracking complex. These three entities illustrate how scale, integration depth, and geographic positioning stratify competitive advantage.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Chevron Corporation |
| GS Caltex Corporation |
| China Petrochemical Corporation |
| S-Oil Corporation |
| Petroliam Nasional Berhad |
| Indian Oil Corporation Ltd. |
| SK Enmove |
| Neste |
| Others |
Pricing and Supply Chain Analysis
Vacuum gas oil feedstock costs cascade through Asia Pacific base oil tiers, with South Korean and Singaporean hydrocracker operators passing through lower marginal costs while inland Chinese solvent-refiners absorb volatile heavy neutral differentials. This input-cost divergence stratifies pricing power between integrated East Asian exporters and legacy domestic suppliers serving industrial lubricant buyers.
Pricing Analysis
Capacity additions in South Korea and Singapore are reshaping price floors for Group II and III grades, compressing historical premiums between API classifications. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified Group III from aftermarket Group II and residual Group I industrial stocks. Price differentiation hinges on viscosity index certification and BIS/JIS compliance tier, with automotive blenders least sensitive and inland Chinese industrial buyers most responsive to spot differentials. Cost compression in Group I is intensifying because vacuum gas oil tracks Brent volatility without hydrocracker yield advantages.
Supply Chain Analysis
China's MIIT domestic-content benchmarks and India's BIS lubricant standards are reshaping sourcing patterns toward locally certified hydrocracked stocks. Supply concentrates in South Korea, Singapore, and Thailand, with vacuum gas oil, hydrocracking catalysts, and additive packages as critical inputs. Single-source vulnerability runs through South Korean turnaround seasons when Japanese and Southeast Asian blenders lack alternative Group III suppliers. Distribution runs through Jurong Island and Ulsan export terminals into regional blending hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific base oil markets represent a late-cycle quality story as automotive OEMs enforce 100,000-kilometer drain intervals that eliminate Group I from factory-fill specifications. This specification escalation rewards hydrocracker operators while stranding solvent-refining assets.
For Market Incumbents: Anchor long-term supply contracts with Japanese OEM procurement teams before rival hydrocracker expansions reach commissioning. Lock in vacuum gas oil offtake agreements with Middle Eastern suppliers to defend against feedstock cost spikes. SK Enmove and Exxon Mobil's integrated positions demonstrate how captive refining-lubricant coordination withstands margin compression from Chinese state-refiner Group II expansions. For New Entrants and Emerging Players: The price-point gap between premium Group III and economy Group I creates entry space for mid-tier Group II specialists serving Indian aftermarket distributors. Target BIS-compliant domestic blending in Gujarat and Maharashtra where Indian Oil Corporation's Group I dominance leaves service-fill quality tiers underserved. A toll-processing arrangement with stranded Chinese solvent-refiners seeking hydrocracker retrofits offers capital-light capacity access. For Investors and Strategic Acquirers: Consolidation pressure builds where aging Group I facilities face MIIT carbon intensity disqualification without viable retrofit economics. Five-to-ten year viability favors hydrocracker-equipped refiners with catalyst optimization expertise and long-term OEM supply contracts. Watch Japanese OEM procurement teams shifting from base oil group minimums to drain interval guarantees as the signal for additive-compatibility testing investments displacing commodity base oil premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocracker Capacity Expansion | SK Enmove and Singapore refiners capture Japanese OEM specification escalation through selective dewaxing investments. |
| Backward Integration into Vacuum Gas Oil | Integrated majors secure Middle Eastern feedstock offtake ahead of Chinese state-refiner capacity additions. |
| BIS/JIS Certification Investment | Domestic Indian blenders qualify for passenger vehicle OEM supply chains previously closed to Group I suppliers. |
| Long-term Supply Agreement | South Korean exporters lock in Southeast Asian blender utilization through multi-year Group II and III contracts. |
| Re-refining Technology Deployment | Japanese and South Korean operators unify circular supply chains with virgin base oil distribution networks. |
Research Methodology
Multiple input streams — refinery operations data, lubricant blender procurement records, and regulatory filing analysis — were reconciled to construct supply-demand balances across the Asia Pacific region. Primary interviews with hydrocracker process engineers, lubricant formulator procurement leads, and OEM technical specification managers were validated against secondary sources including MIIT carbon intensity disclosures, BIS lubricant standard drafts, and customs trade data for vacuum gas oil and base oil movements. Bottom-up capacity modeling and top-down demand segmentation were triangulated against refinery utilization reports.
Data-stream reconciliation anchored volume projections across the modeling period, with segmentation by API Group classification, automotive versus industrial application, and hydrocracking versus solvent-refining technology. CAGRs were derived from capacity expansion timelines against OEM specification evolution curves. Forecast inputs included Japanese automaker drain interval guarantee adoption rates and Chinese provincial dual carbon enforcement intensity.
Caveats apply where MIIT policy implementation timelines or Japanese OEM procurement specification shifts could materially shift the outlook for Group I displacement velocity. Forecasts reflect assumptions about hydrocracker catalyst yield optimization and additive package registration timelines under emerging ASEAN chemical frameworks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Balanos Oil Market
Petroleum Products
Performance Oil Sales Market
Petroleum Products
Pyrolysis Oil Market
Petroleum Products
South Africa Petroleum Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
India White Oil Market
Petroleum Products
Tar Oil Market
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Natural Gas Liquid Market
Petroleum Products
Green Petcoke Market
Petroleum Products
Spindle Oil Market
Petroleum Products
West Africa Refined Petroleum Products Market
Petroleum Products
Australia Refined Petroleum Products Market
Petroleum Products
Pale Oil Market