
 Organic Biogas Market | 2026-2036
Organic Biogas Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Biogas Market Intelligence
The displacement of fossil-based natural gas with upgraded biomethane is restructuring the economics of distributed power generation and vehicle fuel. EnviTec Biogas AG leverages its specialized expertise in agricultural biogas plant construction and operation to capture this shift. Wärtsilä Corporation competes by offering integrated gas processing and liquefaction technology solutions for large-scale municipal and industrial projects.
Organic biogas is a gaseous fuel primarily composed of 50-75% methane, produced through the anaerobic digestion of biodegradable materials. Its principal commercial purpose is to serve as a renewable energy source for electricity, heating, or as a vehicle fuel after purification. Agricultural residue and food waste constitute the dominant feedstock types due to high availability and energy potential. In terms of end-use, power generation remains the largest application, while transportation fuel presents a significant growth vector.
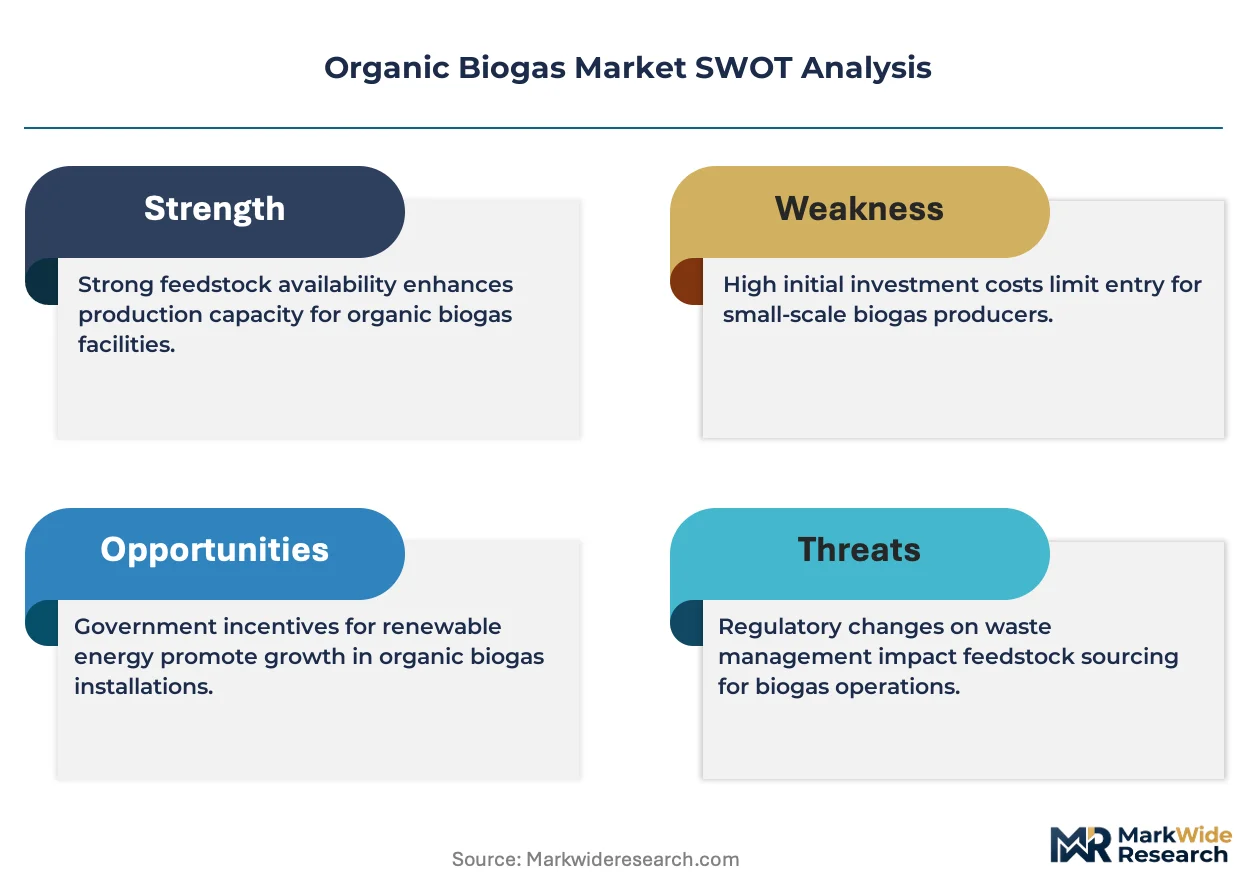
Regulatory mandates, including the US EPA's Renewable Fuel Standard and the EU Green Deal's Fit for 55 package, create guaranteed markets for biogas-derived fuels. In parallel, China's dual carbon goals are driving investment in waste-to-energy projects that utilize organic biogas technologies. Stakeholder success now depends on securing long-term feedstock supply chains and navigating complex, region-specific incentive programs.
Market Dynamics
The organic biogas market is structurally defined by government mandates that create guaranteed offtake markets for renewable natural gas. This policy-driven demand, particularly from transportation and utility sectors, underwrites the financial viability of new project development and infrastructure investment.
Growth Catalysts
- Policy Mandates:The EU Green Deal and the US EPA's Renewable Fuel Standard create durable, high-value markets for biomethane, de-risking investment in new production capacity and upgrading facilities.
- Feedstock Availability:Circular economy initiatives in countries like Germany and France are promoting the segregation and utilization of agricultural residues and municipal food waste, expanding the available feedstock pool for anaerobic digestion.
- Transportation Sector Decarbonization:The heavy-duty vehicle sector's demand for renewable natural gas (RNG) as a low-carbon diesel alternative provides a primary growth vector for upgraded and purified biomethane.
Market Restraints
- Feedstock Competition:Increasing demand for organic waste from biogas, composting, and animal feed sectors creates localized price volatility and competition for high-quality, consistent feedstock supplies.
- High Capital Expenditure:The significant upfront investment required for anaerobic digesters, gas upgrading systems, and grid interconnection infrastructure presents a substantial barrier for smaller agricultural producers and municipalities.
- Grid Injection Hurdles:A lack of standardized gas quality specifications and complex interconnection requirements across different utility territories can delay projects and increase costs for producers seeking to sell biomethane into the natural gas network.
Strategic Opportunities
- Geographic Expansion:Agricultural economies in South America, such as Brazil, and Southeast Asia possess vast, underutilized biomass resources from crops like sugarcane, presenting significant greenfield opportunities for waste-to-energy projects.
- Bio-LNG for Maritime:The production of liquefied biomethane (LBG/Bio-LNG) offers a direct pathway to decarbonize the maritime shipping industry, which faces stringent emissions regulations from the International Maritime Organization.
- Carbon-Negative Fuels:Integrating biogas production with carbon capture and storage (CCS) technologies enables the creation of carbon-negative fuels, which can command premium pricing under low-carbon fuel standards.
Industry Challenges
- Logistical Complexity:Managing the collection, transport, and storage of dispersed, variable, and often seasonal organic feedstocks like manure or crop residues poses a significant operational challenge for plant operators.
- Interoperability and Standardization:The absence of uniform international standards for biomethane quality and sustainability certification complicates cross-border trade and market access for producers.
- Specialized Labor Scarcity:A shortage of trained plant operators, microbiologists, and maintenance technicians with expertise in anaerobic digestion systems constrains the efficient operation and expansion of biogas facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Biogas Market |
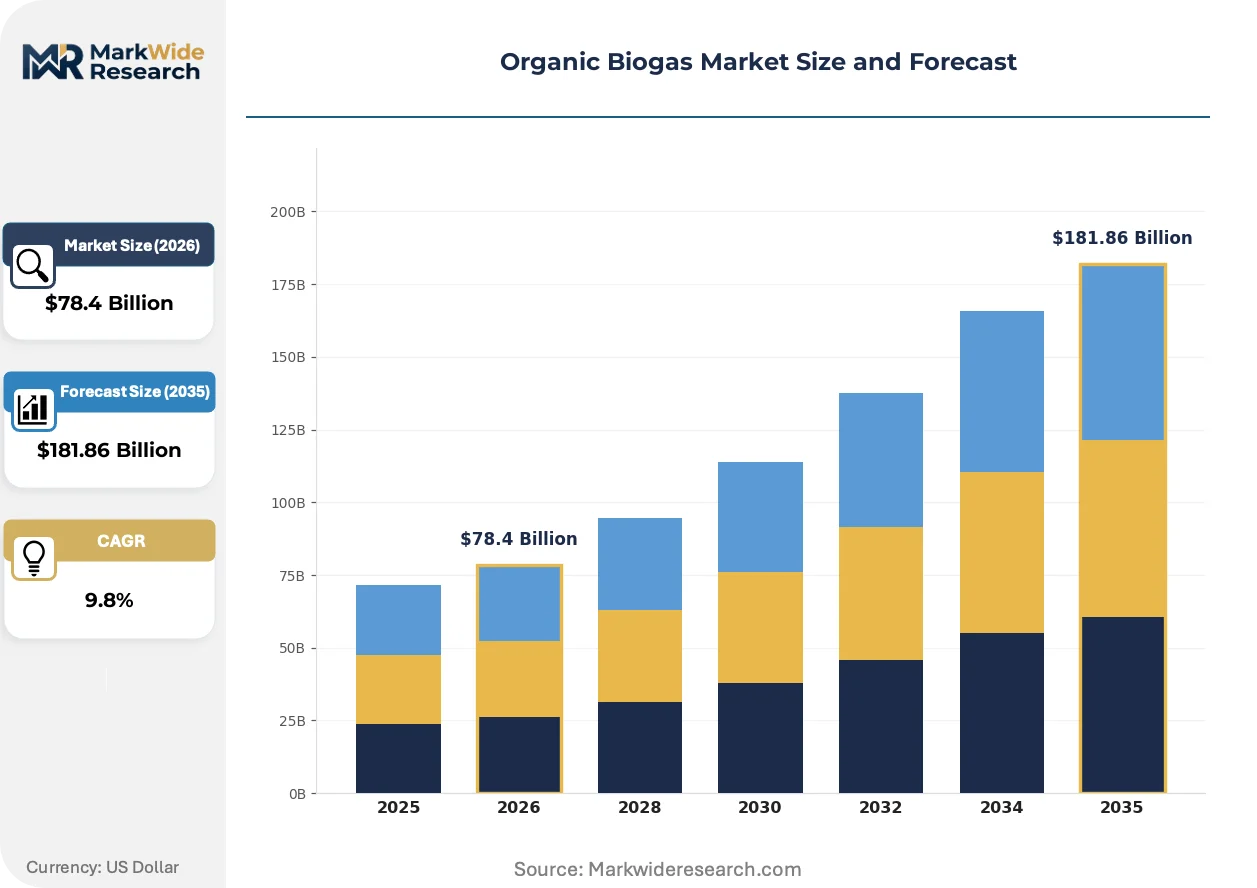
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $181.86 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Food Waste, Agricultural Residue, Animal Manure, Yard Waste Technology: Anaerobic Digestion, Fermentation, Gasification, Pyrolysis End User: Power Generation, Transportation Fuel, Heating, Industrial Use Application: Waste Treatment, Renewable Energy Production, Combined Heat and Power, Waste-to-Energy |
| Companies Covered | EnviTec Biogas AG, PlanET Biogas Global GmbH, Hitachi Zosen Inova AG, Wärtsilä Corporation, WELTEC BIOPOWER GmbH, Air Liquide, Gasum Oy, DMT Environmental Technology, Schmack Biogas GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Biogas Market Strategic Shifts & Innovations
Technological refinement in gas upgrading and process optimization is transforming the economic calculus of biogas projects. This maturation allows producers to pivot from simple waste management and power generation toward becoming suppliers of high-purity, pipeline-grade renewable fuel.
Advanced membrane separation technology provides a modular and energy-efficient method for upgrading raw biogas into high-purity biomethane. Large-scale agricultural cooperatives and municipal waste facilities are rapidly adopting these systems to maximize revenue. This technology is absorbing the high operational costs and chemical handling requirements of older purification methods, thereby improving the overall financial performance of waste-to-energy projects.
China's national dual carbon goals are stimulating significant investment in anaerobic digestion infrastructure. The policy provides direct subsidies and favorable grid access for waste-to-energy projects that utilize organic biogas technologies. Consequently, municipal solid waste operators and large industrial food producers are now integrating biogas capture and utilization as a core part of their environmental compliance and revenue strategy.
A distinct shift in offtake strategy is occurring, with project developers prioritizing long-term contracts for renewable natural gas (RNG) over traditional electricity-focused power purchase agreements. This trend directly impacts the viability of older, power-only biogas plants, creating a competitive advantage for facilities equipped with gas upgrading and grid injection capabilities. This pattern is most pronounced in North America, where utilities and fuel suppliers seek RNG to meet state-level low-carbon fuel standards.
Organic Biogas Market Segmentation
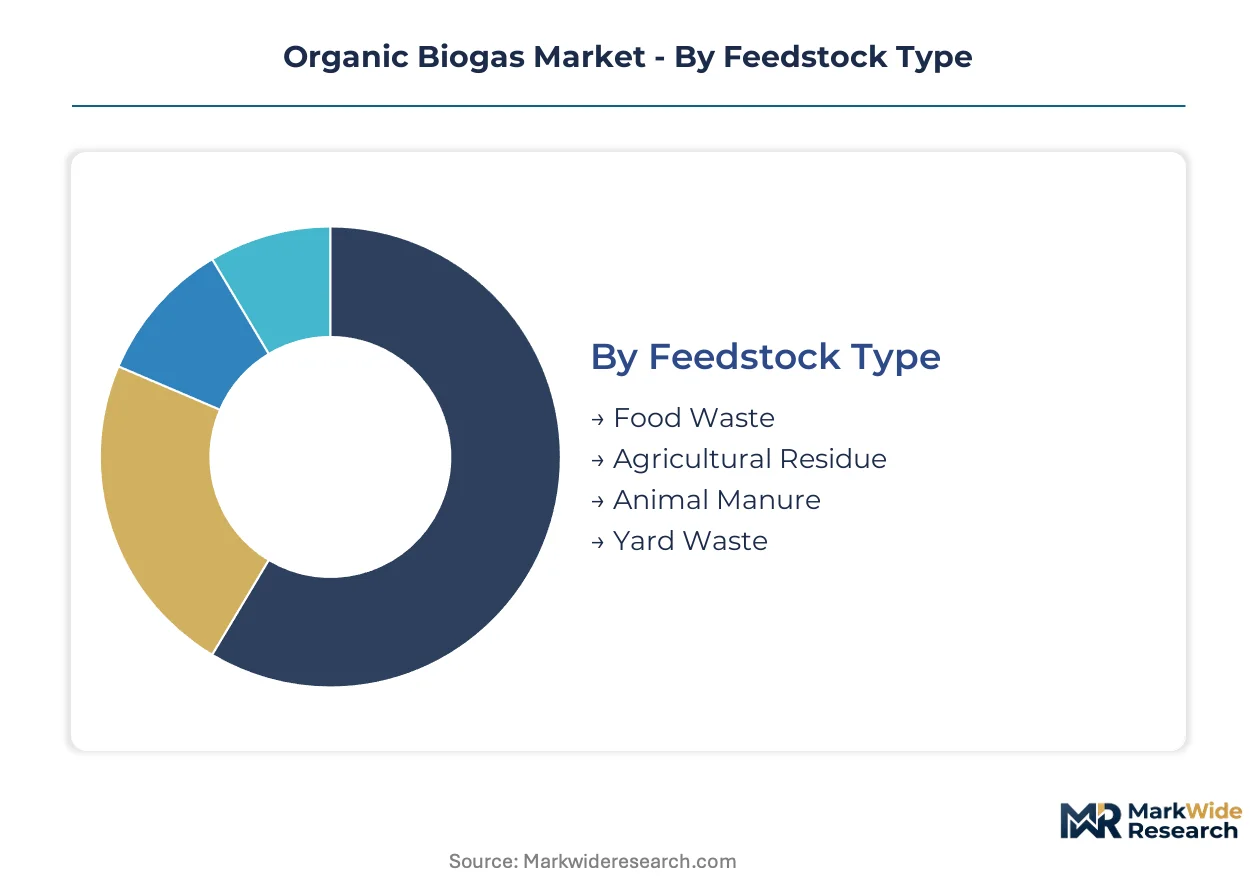
Market segmentation provides a critical lens for understanding the diverse drivers and opportunities within the organic biogas sector. Analyzing the market by feedstock, technology, end-user, and application reveals distinct value propositions and investment priorities for stakeholders. This granular view helps identify specific growth pockets and areas requiring tailored technological or regulatory support.
Feedstock Type:
The upgrade cycle for existing waste management infrastructure frequently prioritizes feedstocks that offer both high energy potential and consistent availability, driving investment decisions.
- Agricultural Residue:Comprises crop byproducts like straw, corn stover, and manure, offering a widely available and renewable biomass source for anaerobic digestion. Demand concentrates in agricultural economies like Germany and Brazil, driven by circular economy initiatives and large-scale farming operations.
- Food Waste:Includes pre-consumer and post-consumer organic discards from households, restaurants, and food processing industries, characterized by high organic content. Demand is increasing in urban centers across Europe and North America, propelled by landfill diversion policies and renewable energy mandates.
- Animal Manure:Consists of excrement from livestock, providing a consistent and nutrient-rich substrate for biogas production, especially in rural areas. This feedstock is crucial for integrated farm-scale biogas projects, improving nutrient management.
- Yard Waste:Encompasses grass clippings, leaves, and other vegetative debris from landscaping activities, offering a seasonal but readily available organic material. Municipal waste management programs increasingly utilize yard waste for composting or anaerobic digestion.
Volume placements concentrate in Agricultural Residue; the faster expansion belongs to Food Waste.
Technology:
Application-specific requirements determine technology selection, with certain processes optimized for particular feedstock characteristics or desired output forms.
- Anaerobic Digestion:A biological process where microorganisms break down organic matter in the absence of oxygen, producing biogas rich in methane. This technology forms the bedrock of most commercial organic biogas plants, particularly for wet organic feedstocks.
- Fermentation:A metabolic process that converts organic compounds into acids, gases, or alcohol, often employed as a pre-treatment or for specific types of biomass. Demand for fermentation processes is emerging in specialized applications focusing on specific product yields beyond methane, such as bio-alcohols.
- Gasification:A thermochemical process converting carbonaceous materials into synthesis gas (syngas) at high temperatures with controlled oxygen, offering an alternative for drier biomass. This technology is gaining interest for its ability to process a wider range of solid biomass, including some agricultural residues.
- Pyrolysis:A thermochemical decomposition of organic material at elevated temperatures in the absence of oxygen, yielding bio-oil, syngas, and biochar. Pyrolysis systems are being explored for their potential to produce multiple valuable products from organic waste, enhancing economic viability.
The market favors Anaerobic Digestion for its versatility, while Fermentation technologies show promise for specialized applications.
End User:
Customer type and their specific energy demands significantly influence the configuration of organic biogas projects, from plant scale to purification requirements.
- Power Generation:Involves converting biogas into electricity using combustion engines, turbines, or fuel cells, often combined with heat recovery for efficiency. This remains the largest end-use segment, with utilities and industrial facilities in Germany and the US seeking decentralized energy solutions.
- Transportation Fuel:Requires upgrading raw biogas to biomethane (renewable natural gas, RNG) for use in vehicles, offering a direct substitute for fossil natural gas. Demand in North America and Europe is accelerating, driven by decarbonization targets for heavy-duty fleets and public transportation.
- Heating:Utilizes biogas directly for industrial processes, commercial buildings, or residential heating, either on-site or injected into natural gas grids. This application provides a direct pathway for energy substitution in local communities.
- Industrial Use:Employs biogas as a direct fuel source for manufacturing processes, replacing fossil fuels in energy-intensive industries. Industries like food processing and chemical manufacturing integrate biogas to lower operational costs and reduce carbon footprints.
Power Generation commands the largest share of current output, but Transportation Fuel exhibits the steepest expansion trajectory.
Application:
Supply concentration of specific organic waste streams often dictates the most viable application for biogas, balancing local demand with feedstock logistics.
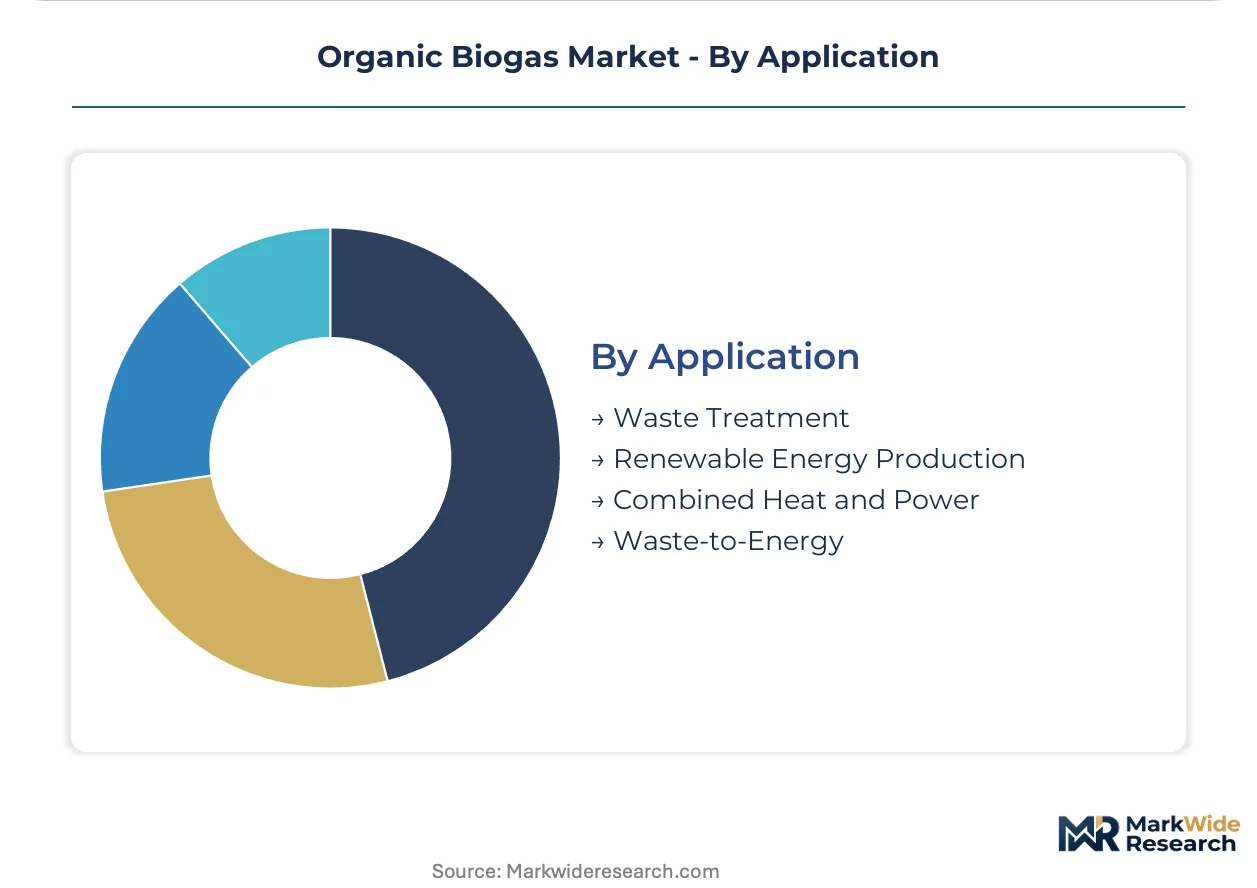
- Renewable Energy Production:Focuses on generating clean energy (electricity, heat, or fuel) from organic waste, contributing to national renewable energy targets. This application represents the primary commercial driver for organic biogas projects globally, supported by various incentive schemes.
- Waste-to-Energy:Integrates waste management with energy generation, converting organic municipal, agricultural, or industrial waste into usable energy forms. China's dual carbon goals specifically stimulate investment in waste-to-energy initiatives, leveraging biogas technologies.
- Waste Treatment:Utilizes anaerobic digestion to stabilize organic waste, reduce its volume, and mitigate greenhouse gas emissions from decomposition. This function is foundational for many municipal solid waste and wastewater treatment facilities, improving environmental compliance.
- Combined Heat and Power (CHP):Produces both electricity and useful heat from biogas in a single process, maximizing energy efficiency and reducing overall emissions. CHP systems are favored in industrial settings and district heating networks for their economic and environmental benefits.
Renewable Energy Production accounts for the bulk of commercial activity, and Waste-to-Energy projects are gaining significant traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for organic biogas concentrates in regions with strong renewable energy mandates and abundant organic waste streams. Policy frameworks in key economies drive significant investment in biomethane production and utilization. This market expansion is particularly pronounced in agricultural and urbanized areas across several continents.
Germany
Germany's organic biogas demand centers on agricultural residue and food waste utilization for energy production. The EU Green Deal and national circular economy targets incentivize these feedstock streams. Bavaria's agricultural sector actively develops farm-scale biogas plants, converting manure and crop residues into renewable energy.
United States
United States demand for organic biogas stems from transportation fuel decarbonization and decentralized power generation needs. The US EPA's Renewable Fuel Standard and state-level low-carbon fuel standards create guaranteed markets. California's dairy farms increasingly adopt anaerobic digestion for RNG production, supplying gas to heavy-duty vehicle fleets.
China
China's dual carbon goals stimulate significant investment in waste-to-energy projects and rural energy supply using biogas. National policies provide direct subsidies and favorable grid access for these initiatives. Municipal solid waste operators in the Yangtze River Delta integrate biogas capture, reducing landfill emissions and generating power.
Brazil
Brazil possesses vast, underutilized biomass resources from sugarcane and agricultural waste, driving organic biogas potential. National renewable energy policies and incentives for bioenergy support project development. The São Paulo state leverages sugarcane bagasse and vinasse for biogas, supporting its industrial and agricultural energy needs.
France
France's organic biogas market is propelled by circular economy initiatives and agricultural residue valorization. The EU Green Deal and national targets for biomethane injection into the gas grid foster growth. Brittany's farming communities implement biogas projects, converting livestock manure into renewable heat and electricity for local consumption.
Organic Biogas Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the organic biogas market. The industry exhibits a tiered structure, ranging from large-scale integrated solution providers to specialized component manufacturers. Strategic archetypes include EPC contractors, technology licensors, and project developers. Companies pursue competitive moves like geographic expansion into emerging agricultural economies and strategic partnerships for feedstock security.
Specialists in integrated biogas solutions include EnviTec Biogas AG, a German-based company known for its agricultural biogas plant construction expertise. Wärtsilä Corporation, a Finnish technology group, occupies a position among providers of large-scale gas processing and liquefaction technology solutions. PlanET Biogas Global GmbH, another German entity, exemplifies developers focusing on comprehensive biogas plant engineering and operational services. These entities anchor distinct segments of the market by offering diverse product and service portfolios.
| Leading Market Players |
|---|
| EnviTec Biogas AG |
| PlanET Biogas Global GmbH |
| Hitachi Zosen Inova AG |
| Wärtsilä Corporation |
| WELTEC BIOPOWER GmbH |
| Air Liquide |
| Gasum Oy |
| DMT Environmental Technology |
| Schmack Biogas GmbH |
| Others |
Cost & Logistics Intelligence
Specialized labor scarcity in advanced anaerobic digestion operations, particularly in Germany, creates distinct labor-cost differentials that contribute to pricing-tier spreads for upgraded biomethane projects.
Pricing Analysis
Volume-focused generation projects often operate on lower margins compared to high-purity biomethane for transportation fuel. The dominant pricing structure is contract-based long-term offtake, especially for renewable natural gas. Price differentiation drivers include biomethane purity for grid injection and the associated carbon credit value. Pricing softness stems from intense feedstock competition and the high capital expenditure for upgrading facilities. Utilities and fuel suppliers purchasing renewable natural gas exhibit lower price sensitivity due to decarbonization mandates, while smaller power-only producers remain highly price-sensitive.
Supply Chain Analysis
Regional distribution centers for feedstock aggregation, combined with hub-and-spoke patterns for biogas collection, define the organic biogas market's supply logistics. Geographic supply concentration centers in Germany, the United States, and China, reflecting policy support and feedstock availability. Raw material dependencies include agricultural residue, food waste, and specialized anaerobic digester components. Logistical complexity in managing dispersed and variable feedstocks presents a significant supply chain risk. Downstream distribution typically involves localized collection networks feeding centralized processing facilities or direct injection into existing natural gas grids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a vertical-integration race, with players actively pursuing control over feedstock aggregation and downstream renewable natural gas distribution.
For Market Incumbents: Deepen proprietary technology development for advanced gas upgrading and carbon capture and storage to maintain competitive advantage. Secure long-term feedstock supply contracts with large agricultural cooperatives or municipal waste operators to mitigate feedstock competition. Invest in next-generation anaerobic digester designs to improve efficiency against the threat of alternative biofuel technologies. Expand operational footprints into high-growth regions like South America, leveraging existing expertise.
For New Entrants and Emerging Players: A significant price-point gap exists between premium pipeline-grade biomethane and standard electricity-focused biogas, offering entry opportunities. Target underutilized biomass resources in agricultural economies, particularly in Southeast Asia, where feedstock is abundant and policy support is emerging. Focus on offering bundled waste management and energy solutions to municipalities and large industrial food producers. Develop modular, scalable biogas solutions for smaller agricultural producers to penetrate the farm-scale segment.
For Investors and Strategic Acquirers: The window for entry favors those seeking long-term assets aligned with global decarbonization trends and circular economy initiatives. Prioritize acquisition targets with proven operational track records and secured long-term offtake agreements for biomethane. Seek technology licensors offering proprietary gas upgrading solutions or project developers with strong regional feedstock relationships. The expansion of low-carbon fuel standards beyond transportation into industrial heating represents a key signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Long-Term Feedstock Contracts | Ensures consistent input supply, mitigating price volatility and operational risk for plant operators. |
| Invest in Biomethane Upgrading Technology | Enables production of high-value renewable natural gas, accessing premium transportation and grid markets. |
| Geographic Expansion into Agricultural Economies | Captures untapped biomass resources and new policy-driven demand in emerging markets like Brazil. |
| Develop Carbon Capture Integration | Creates carbon-negative fuel pathways, commanding premium pricing under stringent low-carbon fuel standards. |
| Form Strategic Partnerships with Utilities | Guarantees long-term offtake for renewable natural gas, de-risking project financing and market access. |
Research Approach
National energy agency reports, environmental agency filings like the US EPA's Renewable Fuel Standard data, and academic literature formed the secondary backbone for this analysis. Primary research involved interviews with project developers, plant operators, feedstock suppliers, and regulatory analysts. This approach ensured a robust understanding of market dynamics by triangulating insights from both top-down regulatory frameworks and bottom-up operational realities.
A bottom-up modeling approach, validated by top-down market sizing, defined the forecast framework across the analysis window. Segmentation dimensions modeled include feedstock type, technology, end-user, application, and regional policy impact. Compound Annual Growth Rates (CAGRs) were derived from historical growth trends and projected impacts of decarbonization policies. Key forecast inputs included renewable energy mandates and feedstock availability projections.
Inputs from national energy agencies and industry associations were available through the study window; gaps in emerging technology adoption rates introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and continued investment in renewable energy infrastructure. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioenergy
Biopower Market
Bioenergy
Bioenergy Market
Bioenergy
Europe Bioenergy Market
Bioenergy
Biogas Market
Bioenergy
Biomass Solid Fuel Market
Bioenergy
Europe Biogas Market
Bioenergy
Micro-Scale Biogas Plant Market
Bioenergy
Global Biomass Briquette Market
Bioenergy
Bio CHP Market
Bioenergy
Biopellets Energy Market
Bioenergy
Biomass Wood Chip Market
Bioenergy
Biomass Molding Fuel Market