
 Africa Refined Petroleum Products Market | 2026-2036
Africa Refined Petroleum Products Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Refined Petroleum Products Market Outlook
Natural gas is expanding its role as a transport fuel substitute for diesel in select African corridors, altering the competitive calculus for refiners. TotalEnergies SE leverages its integrated LNG-to-power infrastructure to anchor downstream positions in Senegal and Mozambique. Sasol Limited sustains synthetic fuel dominance through its coal-to-liquids technology base in South Africa. Engen Petroleum Ltd competes aggressively in retail outlet density across Southern African Development Community markets.
Africa refined petroleum products comprise hydrocarbon fuels produced through atmospheric and vacuum distillation, catalytic cracking, and hydrotreating of crude oil, with sulfur content specifications typically ranging from 10 to 500 parts per million depending on regional mandate. These products power internal combustion engines, industrial boilers, and aviation turbines across a continent where grid electricity remains unreliable for productive uses. Diesel leads product type volume through its dominance in freight logistics and backup power generation for commercial and industrial end users. Jet fuel represents the fastest-growing product category as intra-African aviation liberalization under the Single African Air Transport Market expands route networks. Retail outlets capture margin concentration in urban centers, while bulk distribution channels serve mining and agricultural off-takers with direct supply contracts.
Nigeria's Petroleum Industry Act, South Africa's Clean Fuels 2 specifications, and Ghana's National Petroleum Authority quality enforcement collectively tighten product standards and import access rules across major demand centers. These frameworks force refinery upgrades or accelerate import dependency where domestic upgrading lags specification timelines. Stakeholders must monitor regulatory divergence between sub-regional economic communities to anticipate compliance cost fragmentation and arbitrage opportunities in cross-border fuel movements.
Market Dynamics
Compressed natural gas substitution in East African heavy-duty trucking corridors is fragmenting diesel demand concentration, forcing refiners to rebalance product slate economics around residual fuel oil and jet fuel arbitrage windows.
Growth Catalysts
- Nigeria's Petroleum Industry Act:The legislation mandates domestic crude supply obligations for license holders, anchoring feedstock security for the Dangote refinery and associated downstream infrastructure.
- Aviation turbine fuel demand:The Single African Air Transport Market liberalization is expanding intra-African route networks, pulling jet fuel consumption growth above other product categories.
- Coal-to-liquids technology base:Sasol's Secunda complex sustains synthetic fuel output independent of crude import volatility, securing supply continuity for South Africa's Gauteng industrial corridor.
Market Restraints
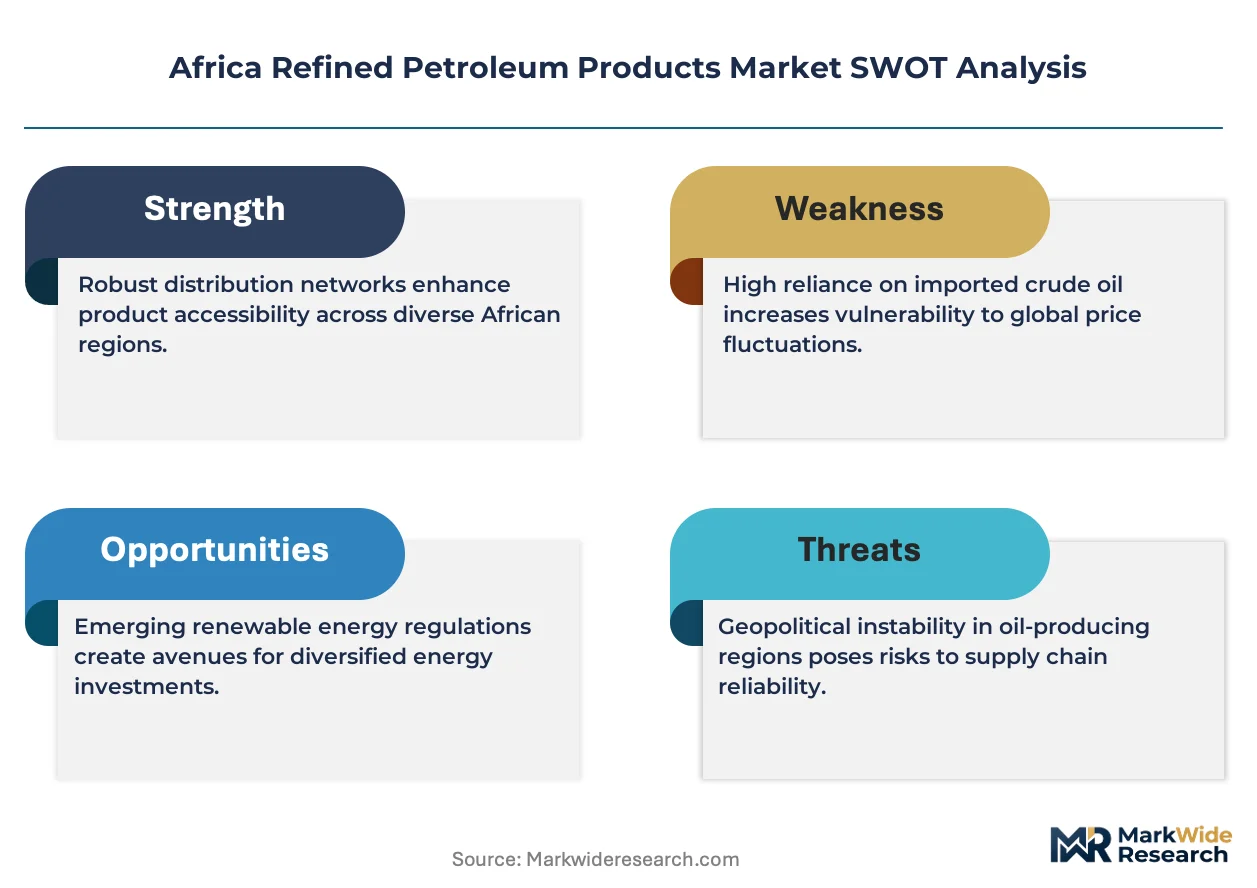
- Crude import dependency:West African refining capacity operates on Nigerian Bonny Light and imported Middle Eastern grades, exposing margin compression when Brent-Dubai spreads widen.
- Sulfur specification divergence:Ghana's National Petroleum Authority enforces 50 ppm diesel standards ahead of Nigerian timelines, fragmenting cross-border product fungibility.
- Natural gas substitution:CNG retail infrastructure along the Northern Corridor from Mombasa to Kigali is capturing heavy-freight kilometers from diesel offtake.
Strategic Opportunities
- Mozambique LNG-to-power integration:TotalEnergies' Afungi peninsula infrastructure enables coastal bunkering and power-plant offtake agreements for residual fuel oil.
- Clean Fuels 2 alignment:South Africa's 10 ppm sulfur mandate creates upgrade project demand for hydrotreater engineering services and catalyst supply contracts.
- Retail outlet densification:Engen Petroleum's SADC network expansion captures transport fuel margin in secondary cities underserved by integrated oil company presence.
Industry Challenges
- Hydrotreater catalyst procurement:Refinery upgrades to meet sulfur specifications require specialized cobalt-molybdenum catalysts with 18-24 month order lead times.
- Product import logistics:Lagos Apapa port congestion and South African pipeline capacity constraints force costly coastal tanker movements and storage leasing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Refined Petroleum Products Market |
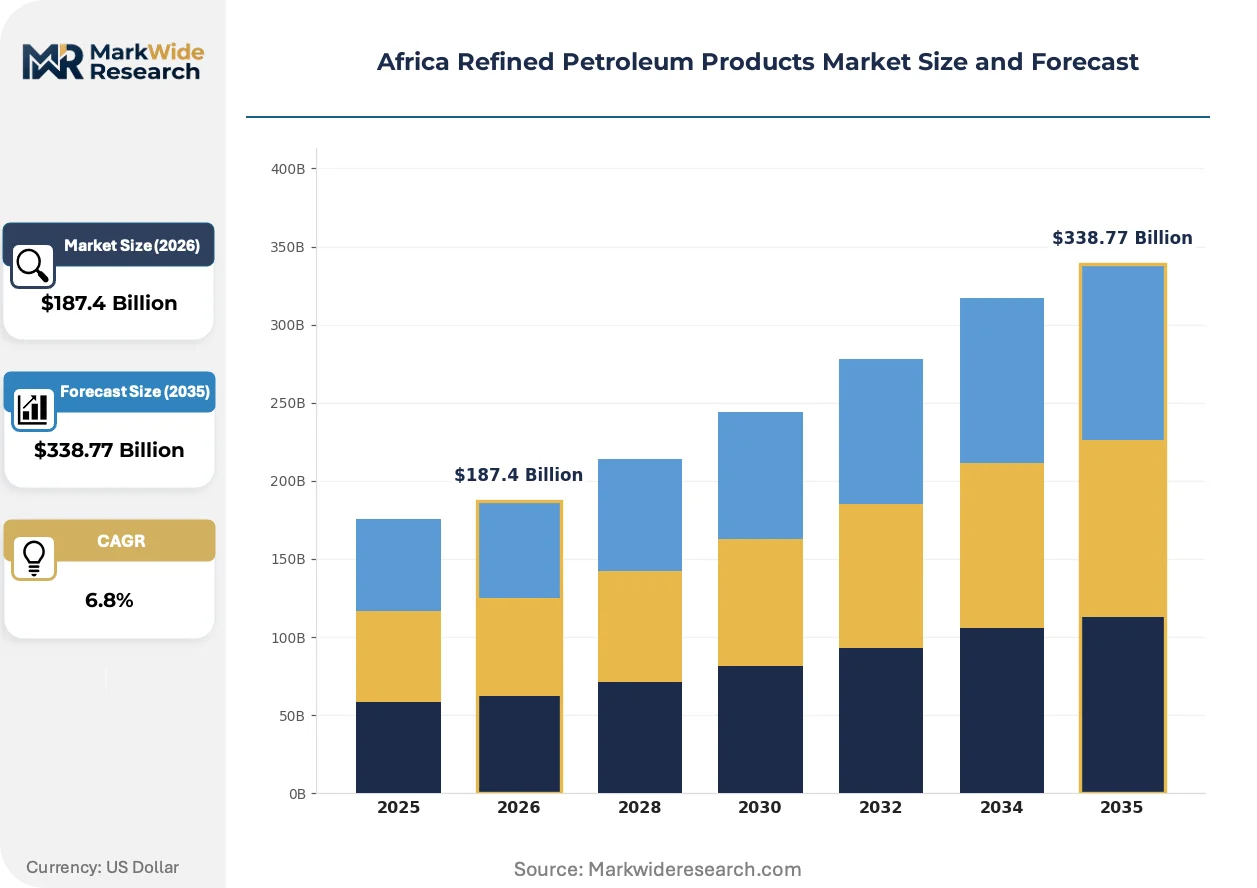
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Kerosene End User: Transportation, Industrial, Residential, Commercial Distribution Channel: Retail Outlets, Wholesale, Direct Supply, Online Sales Packaging Type: Drums, Tankers, Cylinders, Bulk |
| Companies Covered | TotalEnergies SE, Shell plc, Puma Energy Holdings Pte Ltd, Nigerian National Petroleum Corporation, Vivo Energy Plc, Oando PLC, Sasol Limited, Engen Petroleum Ltd, NNPC Limited, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Refined Petroleum Products Market Strategic Shifts
Digital fuel monitoring systems and specification harmonization pressures are compressing arbitrage windows while opening new service revenue streams around compliance verification and supply chain traceability.
Fuel marking and authentication technologies using molecular DNA tracers and blockchain verification protocols are expanding into government tax enforcement and subsidy fraud prevention programs. National petroleum authorities in Nigeria and Ghana deploy these systems to track product from import discharge through retail pump delivery. The structural consequence is that illicit bunkering and cross-border smuggling economics are compressing, forcing informal distributors toward formal channel integration.
South Africa's Clean Fuels 2 specifications and Ghana's National Petroleum Authority quality enforcement are tightening sulfur and benzene limits ahead of sub-regional economic community harmonization timelines. Refinery upgrade capex requirements are accelerating asset retirement decisions for aged coastal plants in Senegal and Côte d'Ivoire. The import-dependent West African markets are responding by negotiating long-term supply contracts with Middle Eastern and Indian refiners positioned on the new specification curve.
Direct supply contracting between mining houses and trading houses is displacing traditional wholesale distributor intermediation in copper-belt fuel procurement. Glencore and Trafigura now manage inventory positions at Zambian and DRC mine sites, replacing national oil company allocations. This pattern is most visible in the Copperbelt region spanning Zambia's Copperbelt Province and Haut-Katanga, where diesel consumption for haul truck fleets dominates offtake volumes.
Africa Refined Petroleum Products Market Segmentation
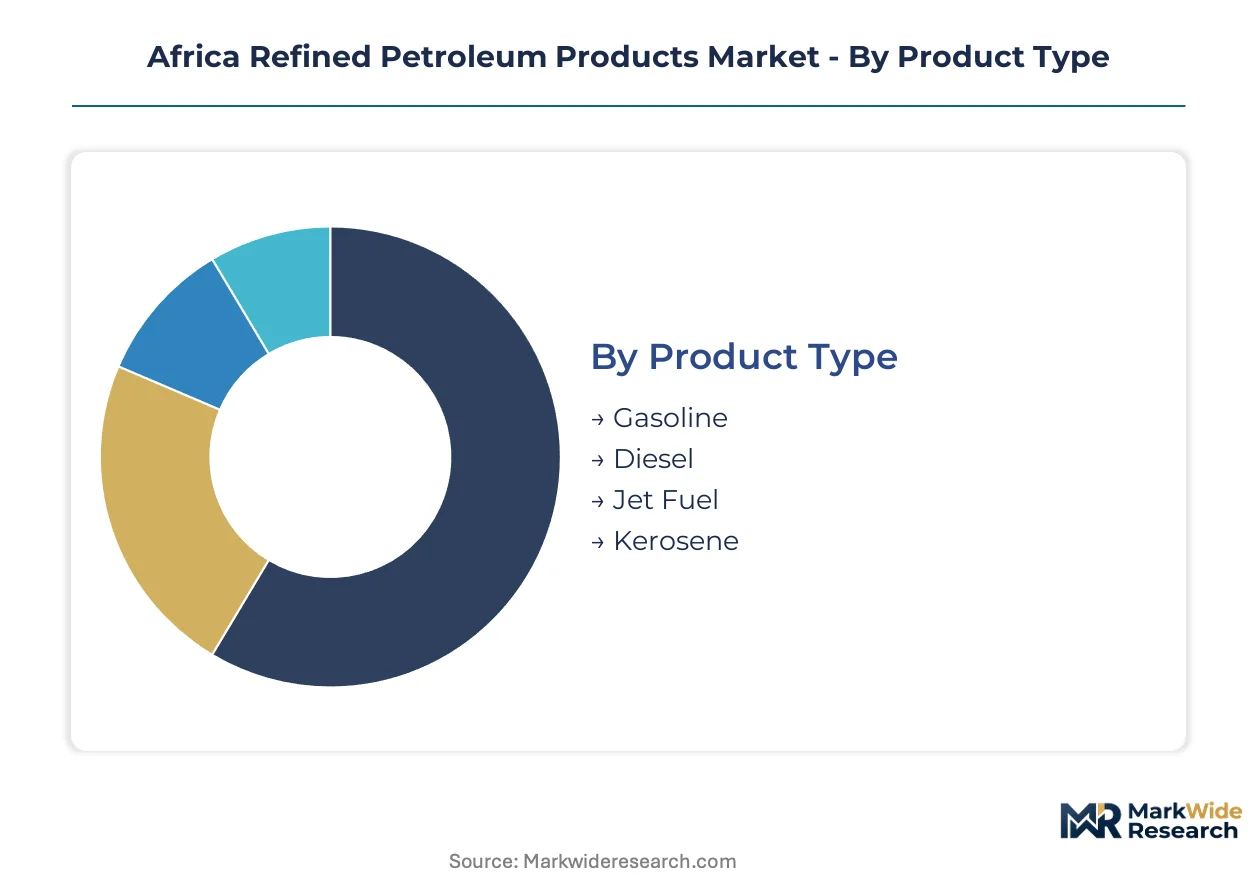
Refined petroleum products in Africa fragment across four dimensions that determine margin capture, logistics configuration, and regulatory exposure. Product type dictates refinery economics and sulfur compliance costs. End-user concentration shapes demand predictability and contract structures.
Product Type:
Buyers in this category differentiate by energy density requirements, sulfur tolerance thresholds, and combustion efficiency specifications for their specific applications.
- Gasoline:Light distillate with 91-95 octane ratings dominates private vehicle fleets in urban Nigeria and South Africa. Lagos-Ibadan corridor traffic congestion sustains premium gasoline offtake despite gradual hybrid vehicle penetration.
- Diesel:Middle distillate with 10-500 ppm sulfur specifications powers heavy freight logistics and backup generators across the continent. Compressed natural gas substitution along East African trucking corridors is eroding diesel's historical transport monopoly.
- Jet Fuel:Kerosene-based aviation turbine fuel with strict flash point and freezing point specifications serves expanding intra-African route networks.
- Kerosene:Light heating fuel with wide-cut boiling ranges supports residential cooking and lighting in grid-deficient rural settlements.
Volume sits with diesel; growth tilts toward jet fuel.
End User:
Application intensity and price elasticity separate buyers, with mining houses and airlines commanding direct supply terms while residential users absorb retail markups.
- Transportation:Road freight, aviation, and marine bunkering consume the majority of refined product volumes. Single African Air Transport Market liberalization is expanding aviation turbine fuel demand above historical growth rates.
- Industrial:Manufacturing plants, mining operations, and power generation facilities require consistent bulk supply with sulfur specifications aligned to equipment warranties. Copperbelt mining houses in Zambia and DRC now contract directly with trading houses, bypassing national oil company allocations.
- Residential:Household cooking and lighting applications concentrate in peri-urban settlements with unreliable grid electricity. Kerosene demand is compressing as LPG cylinder distribution expands.
- Commercial:Retail fuel stations, hospitality generators, and construction equipment operators purchase through wholesale channels with volume-based pricing tiers.
Transportation commands volume concentration; industrial procurement is shifting fastest toward direct supply contracting.
Distribution Channel:
Margin capture and working capital intensity distinguish channel participants, with integrated oil companies dominating retail while traders manage bulk arbitrage.
- Retail Outlets:Branded service stations with forecourt convenience operations generate highest per-liter margins in urban centers. Engen Petroleum's Southern African Development Community network densification targets secondary cities underserved by major oil company presence.
- Wholesale:Regional distributors with storage terminal access supply independent retailers and commercial bulk buyers. Lagos Apapa port congestion forces costly coastal tanker movements to alternative discharge points.
- Direct Supply:Mining houses, airlines, and power plants negotiate long-term offtake agreements bypassing intermediary markups. Trafigura and Glencore now manage inventory positions at Zambian and DRC mine sites.
- Online Sales:Digital fuel ordering platforms with GPS-tracked delivery are emerging in Nigerian urban markets for commercial and residential bulk purchases.
Retail outlets capture margin concentration; direct supply channels are expanding most quickly among large-volume industrial offtakers.
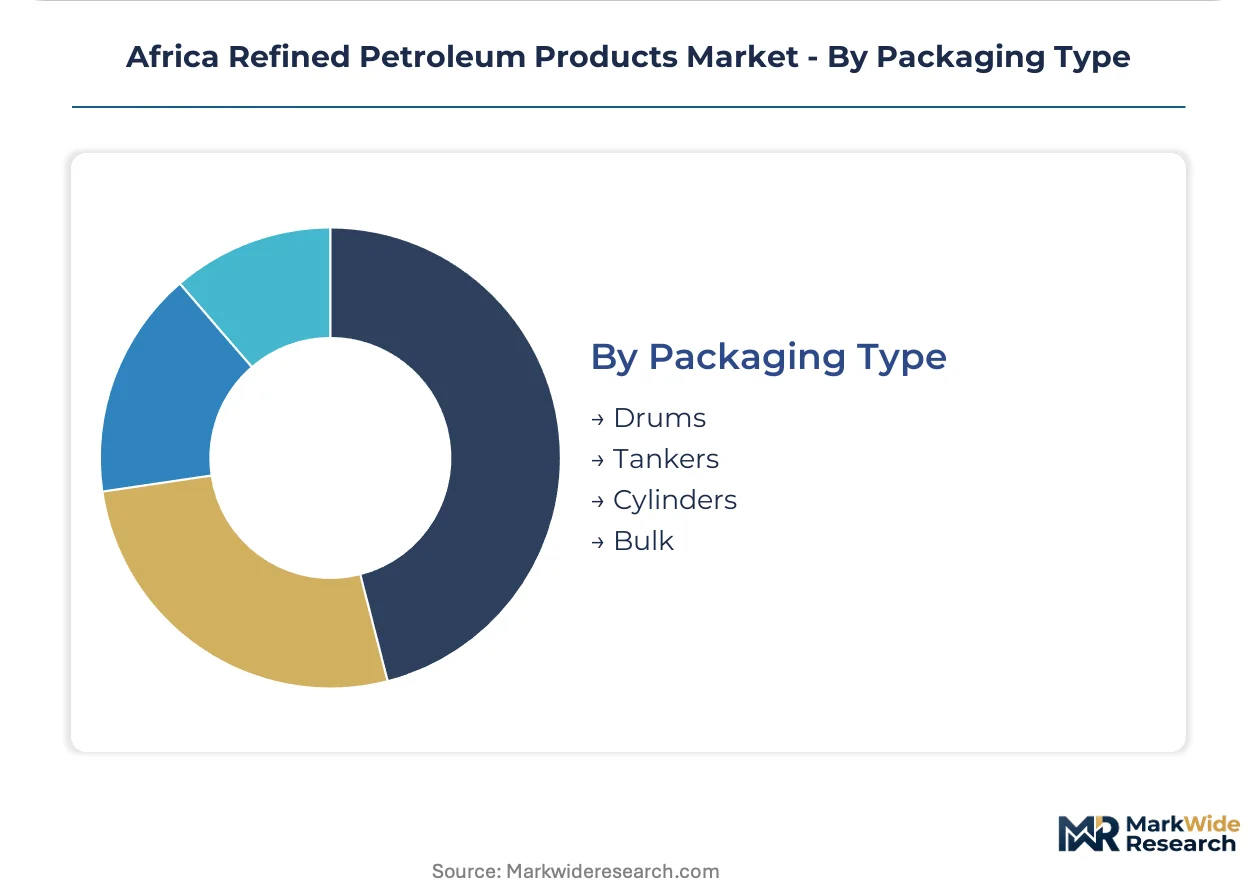
Packaging Type:
Logistics cost structures and contamination risk profiles determine packaging selection, with bulk movements dominating high-volume corridors and drums serving dispersed demand.
- Drums:200-liter steel containers serve agricultural mechanization and construction sites with intermittent consumption patterns. Drums enable product traceability for government fuel marking programs in Nigeria and Ghana.
- Tankers:Articulated road tankers with compartmentalized trailers distribute refined products from coastal import terminals to inland depots. Road tanker fleets face sulfur specification divergence challenges at Ghana-Nigeria border crossings.
- Cylinders:Pressurized containers serve LPG and compressed natural gas retail distribution, displacing kerosene in residential cooking applications.
- Bulk:Pipeline, coastal barge, and rail tank car movements serve mining complexes, power plants, and aviation fuel hydrant systems. South African pipeline capacity constraints force costly storage leasing at coastal terminals.
Bulk movements dominate volume; drum packaging retains relevance in agricultural mechanization corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Nigeria's Lagos-Ibadan industrial corridor and South Africa's Gauteng refining hub, with regulatory divergence between national petroleum authorities fragmenting cross-border product fungibility.
Nigeria
The Dangote refinery anchors feedstock security through Petroleum Industry Act domestic crude supply obligations, while Lagos Apapa port congestion forces costly coastal tanker movements to alternative discharge points. Lagos-Ibadan corridor traffic sustains premium gasoline offtake despite gradual hybrid penetration.
South Africa
Sasol's Secunda coal-to-liquids complex secures synthetic fuel output independent of crude import volatility for Gauteng industrial demand. Clean Fuels 2 specifications mandate 10 ppm sulfur standards, creating upgrade project demand for hydrotreater engineering services.
Ghana
National Petroleum Authority enforcement of 50 ppm diesel standards ahead of Nigerian timelines fragments regional product arbitrage opportunities. Tema port infrastructure serves as a coastal import terminal for landlocked Sahelian markets.
Kenya
Compressed natural gas retail infrastructure along the Northern Corridor from Mombasa to Kigali captures heavy-freight kilometers from diesel offtake. Mombasa port throughput constraints accelerate direct supply contracting between mining houses and trading houses.
Mozambique
TotalEnergies' Afungi peninsula LNG-to-power infrastructure enables coastal bunkering and power-plant offtake agreements for residual fuel oil. Maputo corridor positioning supports regional distribution into landlocked Southern African Development Community markets.
Africa Refined Petroleum Products Market Competitive Environment
Capacity expansion dominates the current landscape as integrated oil companies and national oil companies reposition around refinery upgrades and retail outlet densification. The vendor base separates into three strategic archetypes: European majors with LNG-to-power integration, African national oil companies with domestic crude obligations, and regional retail specialists with SADC network density. M&A activity concentrates on terminal and storage asset acquisition, while strategic partnerships anchor long-term offtake agreements with mining houses and airlines.
Among European-based majors, TotalEnergies SE exemplifies integrated LNG-to-power infrastructure positioning, while Shell plc represents the global trading and retail archetype. Sasol Limited anchors synthetic fuel production through coal-to-liquids technology independence. These three occupy distinct competitive positions: coastal LNG integration, global trading scale, and feedstock security through synthetic production.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Shell plc |
| Puma Energy Holdings Pte Ltd |
| Nigerian National Petroleum Corporation |
| Vivo Energy Plc |
| Oando PLC |
| Sasol Limited |
| Engen Petroleum Ltd |
| NNPC Limited |
| Others |
Value Chain & Pricing Dynamics
Mining houses and airlines commanding direct supply contracts anchor pricing power in Africa's refined petroleum products market, compressing wholesale distributor margins while elevating spot-market volatility for residual volume. Bulk offtakers negotiate sulfur-specification premiums against retail channels absorbing specification divergence costs at Ghana-Nigeria border crossings.
Pricing Analysis
Volume concentrates in diesel contract structures while margins concentrate in jet fuel and retail gasoline. Three-tier pricing structure across premium low-sulfur, standard regional-grade, and high-sulfur residual tiers reflects sulfur specification compliance costs and transport logistics premiums. Pricing pressure stems from compressed natural gas substitution eroding diesel transport monopoly along East African corridors. Mining houses exhibit lowest price sensitivity due to equipment warranty requirements and supply continuity premiums, while peri-urban residential kerosene buyers face highest elasticity as LPG cylinder distribution expands.
Supply Chain Analysis
Nigeria's Petroleum Industry Act domestic crude supply obligations and South Africa's Clean Fuels 2 specifications are reshaping sourcing patterns toward captive feedstock security and upgrade infrastructure investment. Supply concentrates in Nigerian Bonny Light term contracts, Middle Eastern spot cargoes, and Sasol's Secunda synthetic output. Cobalt-molybdenum hydrotreater catalysts, specialized low-sulfur crude blends, and coastal storage terminal access constitute critical input dependencies. Single-source vulnerability runs through 18-24 month catalyst procurement lead times. Distribution runs through coastal import terminals, pipeline networks to inland depots, and direct supply contracting with mining and aviation offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compressed natural gas retail infrastructure is displacing diesel demand in heavy-freight corridors, forcing a technology-transition phase where legacy refiners must rebalance product slates or cede transport fuel volume to gas-to-power integration plays.
For Market Incumbents: Lock in feedstock security through Petroleum Industry Act domestic crude obligations and anchor long-term offtake agreements with Copperbelt mining houses before trading houses consolidate inventory management positions. Upgrade hydrotreater capacity to meet Ghana's 50 ppm and South Africa's 10 ppm sulfur mandates ahead of sub-regional harmonization timelines. Vertical integration into coastal LNG-to-power infrastructure offers margin defense against diesel demand erosion. For New Entrants and Emerging Players: Secondary cities in the Southern African Development Community with underserved retail outlet density present the most penetrable white-space target for transport fuel margin capture. Compressed natural gas retail infrastructure along Northern Corridor trucking routes offers equipment-leasing and station-buildout revenue streams independent of refinery capex. Direct supply contracting with emerging copper-belt mining operations bypasses national oil company allocation bottlenecks. For Investors and Strategic Acquirers: The window for entry favors terminal and storage asset specialists with coastal positioning and specification-upgrade flexibility. Long-term viability hinges on exposure to jet fuel growth under Single African Air Transport Market liberalization rather than diesel-dependent logistics plays. Watch for hydrotreater catalyst procurement bottlenecks as the inflection signal for refinery upgrade capex acceleration and associated engineering service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Refinery Sulfur Upgrade | Clean Fuels 2 alignment in South Africa mandates 10 ppm hydrotreater investment and catalyst supply contracts. |
| LNG-to-Power Integration | TotalEnergies' Afungi peninsula infrastructure anchors coastal bunkering and residual fuel oil offtake agreements. |
| Retail Network Densification | Engen Petroleum's SADC secondary city expansion captures transport fuel margin in underserved markets. |
| Direct Supply Contracting | Trafigura and Glencore inventory positions at Zambian and DRC mine sites displace national oil company intermediation. |
| CNG Infrastructure Buildout | East African Northern Corridor retail stations erode diesel demand concentration in heavy-freight logistics. |
Study Parameters
Multi-period observation of refinery utilization rates, sulfur specification enforcement actions, and LNG-to-power project milestones anchored the trend analysis, supplemented by interviews with refinery operations directors, National Petroleum Authority compliance officers, mining house fuel procurement managers, and coastal storage terminal operators. Secondary validation drew from Nigerian National Petroleum Corporation discharge records, South African Petroleum Industry Association consumption surveys, Ghana Tema port throughput statistics, and International Energy Agency Africa energy outlooks. Bottom-up product volume modeling and top-down macroeconomic scenario triangulation ensured cross-verification.
Segment-weighting approaches applied differential growth assumptions across diesel, gasoline, jet fuel, and residual fuel oil categories, with sulfur specification compliance costs and natural gas substitution elasticities as industry-specific demand shapers. End-user segmentation incorporated transportation, industrial, residential, and commercial consumption patterns with channel-specific margin structures. CAGRs were derived from regression analysis against GDP growth, vehicle fleet expansion, and aviation route liberalization indicators across the projection horizon.
Revisions become necessary when regulatory specification timelines accelerate, hydrotreater catalyst supply disruptions materialize, or CNG retail infrastructure deployment exceeds baseline assumptions in East African corridors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Automotive Oil Strainer Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
Oil Storage Sales Market
Petroleum Products
West Africa Refined Petroleum Products Market
Petroleum Products
Tar Oil Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
North Africa Refined Petroleum Products Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Naphtha Market
Petroleum Products
Marine Minerals Market
Petroleum Products
Spindle Oil Market
Petroleum Products
Petcoke Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Crude Oil Pour Point Depressant Market
Petroleum Products
Natural Gas Liquid Market
Petroleum Products
Oil Refinery Market