
 United States Refined Petroleum Products Market | 2026-2036
United States Refined Petroleum Products Market Size, Share, and Industry Trends Forecast 2026-2036
United States Refined Petroleum Products Market Analytics
The Permian Basin is rewriting downstream logistics economics as associated gas and crude output strain existing pipeline and refining infrastructure. Marathon Petroleum dominates Midwest retail and refining integration. Valero Energy anchors Gulf Coast export capacity. ExxonMobil leverages its Beaumont refinery expansion to sustain premium product yields.
Refined petroleum products encompass hydrocarbon fuels derived from crude oil through thermal and catalytic processing, with specifications governed by ASTM distillation curves, sulfur content limits, and octane or cetane ratings. These products power transportation networks, industrial heat systems, and residential heating across the United States. Gasoline retains the largest volume share in the product type dimension, though jet fuel exhibits the fastest demand recovery trajectory. The transportation usage sector absorbs the majority of output, while wholesale distribution channels capture margin pools through term contracts with fleet operators and airlines.
EPA sulfur regulations, California Air Resources Board low-carbon fuel standards, and OSHA refinery safety mandates collectively shape product blending investments and facility upgrade cycles. NHTSA corporate average fuel economy rules indirectly constrain gasoline demand growth by mandating vehicle efficiency gains. Stakeholders must monitor renewable diesel capacity additions and carbon intensity scoring mechanisms that could reclassify competitive positioning across the refined products slate.
Market Dynamics
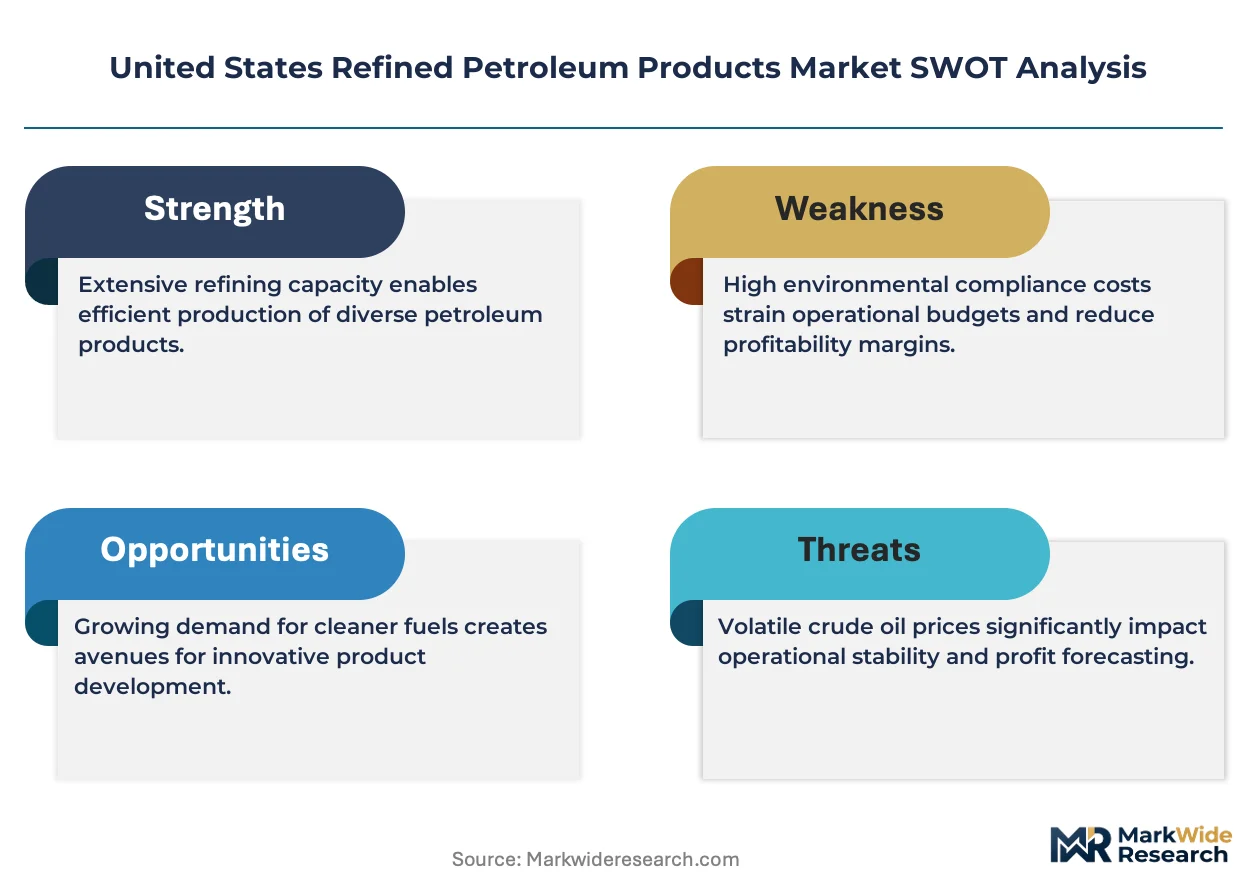
EPA Tier 3 sulfur standards and California's Low Carbon Fuel Standard are forcing Gulf Coast refiners to reconfigure hydroprocessing units and blending infrastructure, compressing margin pools for high-sulfur feedstock processors while rewarding complex coking and alkylation investments.
Growth Catalysts
- Post-pandemic aviation recovery:Commercial airlines are rebuilding flight schedules and fleet utilization, pulling jet fuel demand above pre-2020 baselines in hub markets.
- California LCFS credit markets:Low-carbon fuel standard credits incentivize renewable diesel co-processing at existing refineries, opening margin streams from biofeedstock integration.
- Permian associated gas liquids:NGL output from West Texas oil fields is expanding regional feedstock availability for Gulf Coast petrochemical and gasoline blending operations.
Market Restraints
- Crude price volatility:WTI-Brent spreads and OPEC+ supply decisions inject input cost uncertainty that compresses refinery crack spreads without warning.
- Gulf Coast concentration risk:Over 50 percent of national refining capacity sits within hurricane exposure zones, creating single-point failure vulnerabilities for gasoline and diesel supply.
- Renewable diesel substitution:Neste and Diamond Green Diesel capacity additions threaten middle distillate market share as fleet operators secure lower-carbon intensity fuel contracts.
Strategic Opportunities
- Midwest renewable fuel hubs:Iowa and Illinois soybean crush expansions position local refiners for integrated renewable diesel and sustainable aviation fuel production.
- Hydrogen refinery integration:Electrolyzer and blue hydrogen projects at Texas and Louisiana facilities can decarbonize hydrocracker hydrogen supply while capturing IRA production tax credits.
- Marine fuel 0.5% sulfur compliance:IMO 2020 residual fuel oil demand shifts create VLSFO blending opportunities for complex refiners with coking and visbreaking capacity.
Industry Challenges
- Process control engineering scarcity:Refinery digitalization and advanced process control implementation face talent gaps as experienced operators retire from Texas and Louisiana facilities.
- Turnaround schedule compression:EPA consent decree compliance work and catalyst replacement cycles are colliding, forcing extended outages at aging fluid catalytic cracking units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Refined Petroleum Products Market |
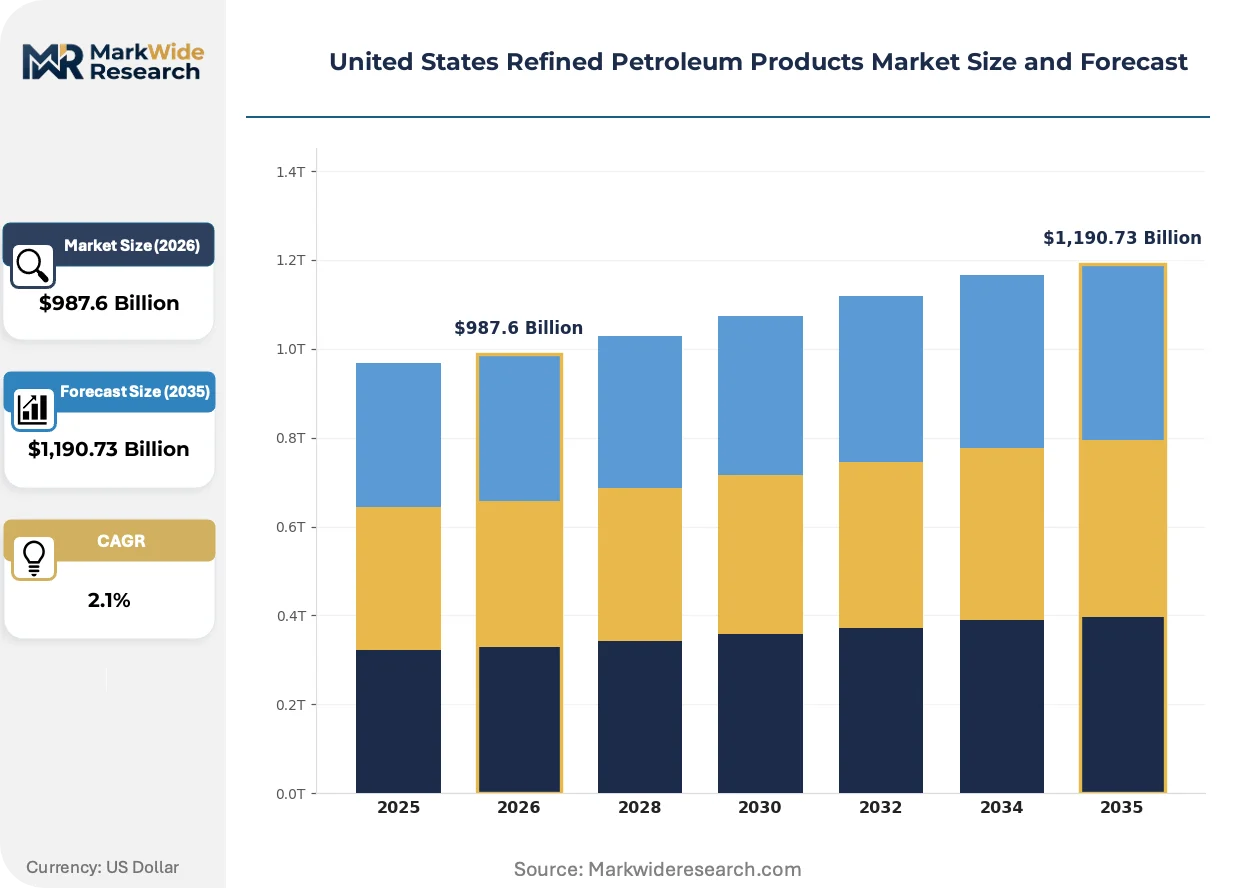
| Market Size in 2026 | $987.6 Billion |
| Market Size in 2035 | $1,190.73 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Kerosene Usage Sector: Transportation, Industrial, Residential, Commercial Distribution Channel: Retail, Wholesale, Direct Sales, E-commerce Refining Process: Hydrocracking, Catalytic Reforming, Distillation, Hydrotreating |
| Companies Covered | Marathon Petroleum, Valero Energy, ExxonMobil, Phillips 66, PBF Energy, Chevron Corporation, Citgo, HF Sinclair, BP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Refined Petroleum Products Market Evolving Landscape
Refined product markets are bifurcating between legacy hydrocarbon processors and integrated low-carbon fuel producers, with technology choices made today determining competitive position through the energy transition.
Renewable diesel co-processing technology is collapsing the capital barrier between conventional refining and biofuel production. Valero, Marathon, and Phillips 66 are retrofitting hydrotreaters at a pace that halves the cost of standalone renewable diesel facilities. This retrofit pathway is compressing the timeline for low-carbon fuel supply expansion and threatening merchant biodiesel economics.
California Air Resources Board is tightening carbon intensity scoring methodologies for the LCFS program, penalizing indirect land-use change emissions from soybean-based renewable diesel while rewarding waste feedstocks. Refiners with secured used cooking oil and tallow supply chains are repositioning product slates toward compliance-advantaged fuels. The state's transportation fuel pool is experiencing the most acute specification divergence from national ASTM standards.
Fleet operators are consolidating fuel procurement through long-term offtake agreements with integrated refiners, bypassing traditional wholesale rack distributors. Large trucking carriers and airlines are locking in multi-year jet fuel and diesel contracts with Marathon, Valero, and ExxonMobil to secure price certainty and carbon intensity documentation. This concentration is most visible in California and Texas markets where sustainability reporting requirements pressure supply chain transparency.
United States Refined Petroleum Products Market Segmentation
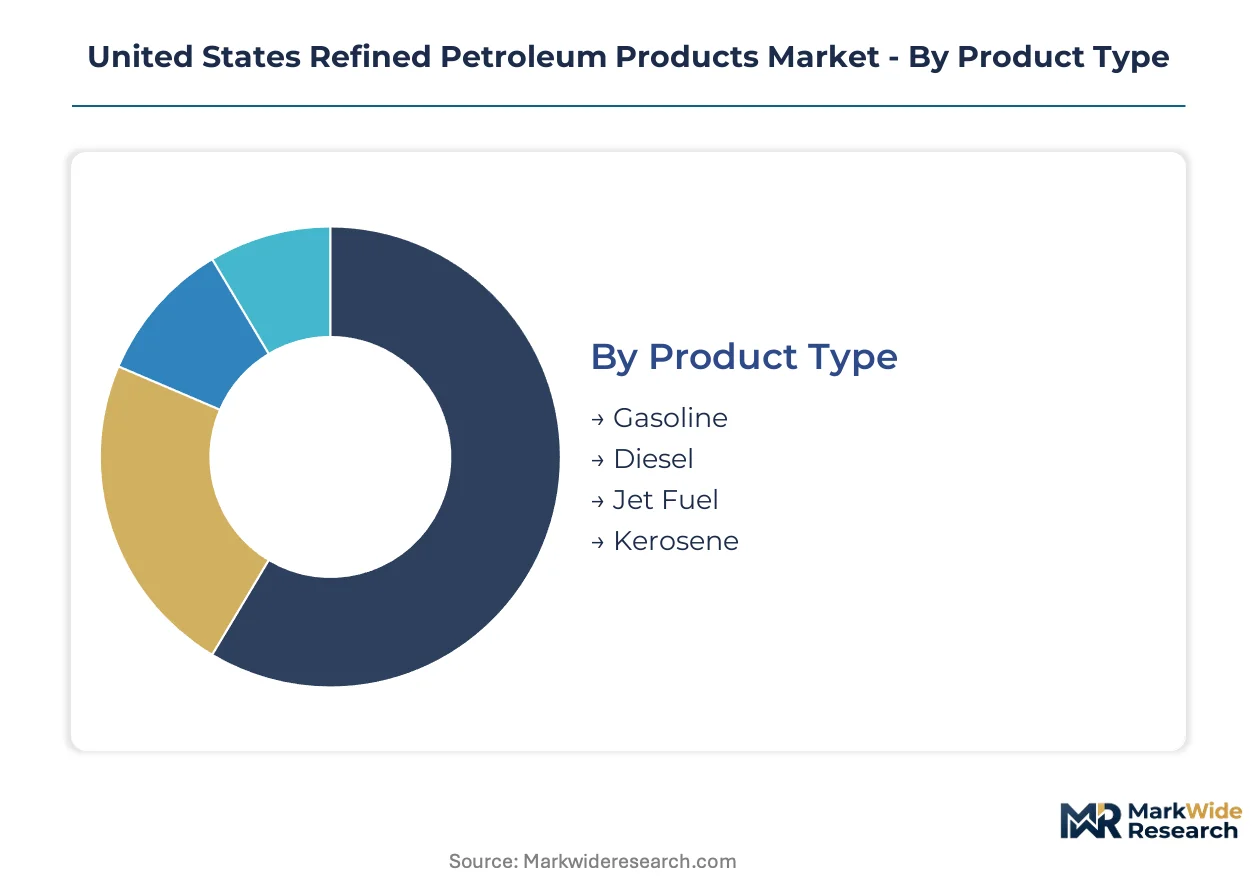
Segmentation reveals how regulatory pressure and feedstock economics fragment margin pools across the United States refined products slate. Product specifications, distribution channels, and refining complexity tiers determine which assets capture value as California LCFS rules diverge from national ASTM standards.
Product Type:
Cost tier differentiation separates commodity fuels from premium specification products with sulfur and aromatics constraints.
- Gasoline:Blended to meet ASTM D4814 volatility and octane specifications with ethanol oxygenate mandates varying by state. Demand concentrates in suburban commuting corridors and Sun Belt metropolitan expansion zones where VMT per capita exceeds national baselines. EPA Tier 3 sulfur limits at 10 ppm force continuous hydrotreater investment.
- Jet Fuel:Kerosene-range distillate meeting ASTM D1655 freeze point and thermal stability requirements for turbine operation. Commercial aviation recovery at Dallas-Fort Worth, Atlanta Hartsfield-Jackson, and Los Angeles International is pulling demand above pre-pandemic levels. California's sustainable aviation fuel mandates are compressing conventional jet fuel share in the state's transportation pool.
- Diesel:Middle distillate governed by ASTM D975 cetane and sulfur specifications for compression ignition engines.
- Kerosene:Light distillate used in residential heating and industrial process heat applications.
Gasoline holds installed capacity. Jet Fuel is rotating up the share rankings.
Usage Sector:
Application intensity varies by thermal efficiency requirements and emissions accountability mechanisms.
- Transportation:Absorbs the majority of gasoline and diesel output through light-duty vehicle fleets, heavy trucking corridors, and commercial aviation networks. Demand concentrates along Interstate highway corridors and airport hub-and-spoke systems where fuel logistics infrastructure achieves scale economies.
- Industrial:Process heat and combined heat-and-power applications in petrochemical complexes, steel mills, and cement kilns. Gulf Coast chemical manufacturing clusters and Permian Basin oilfield operations anchor diesel and fuel oil consumption for drilling rigs and fracturing equipment.
- Residential:Heating oil demand concentrated in New England and Mid-Atlantic states with legacy tank infrastructure.
- Commercial:Standby generator fuel and building heat in institutional and retail facilities.
Transportation holds installed capacity. Industrial is rotating up the share rankings.
Distribution Channel:
Customer type determines margin capture through contract structure and volume commitment terms.
- Retail:Branded and unbranded gasoline stations serving individual consumers through rack purchases and proprietary terminal networks. Major oil companies and independent marketers compete on location convenience and loyalty program economics.
- Wholesale:Term contracts with fleet operators, airlines, and industrial accounts bypassing retail markup structures. Rack pricing at Gulf Coast and Midwest terminals sets regional benchmarks for diesel and jet fuel procurement.
- Direct Sales:Refinery-to-end-user pipelines and dedicated barge deliveries for large-volume industrial accounts.
- E-commerce:Digital procurement platforms for commercial fuel ordering with delivery logistics coordination.
Retail holds installed capacity. Wholesale is rotating up the share rankings.
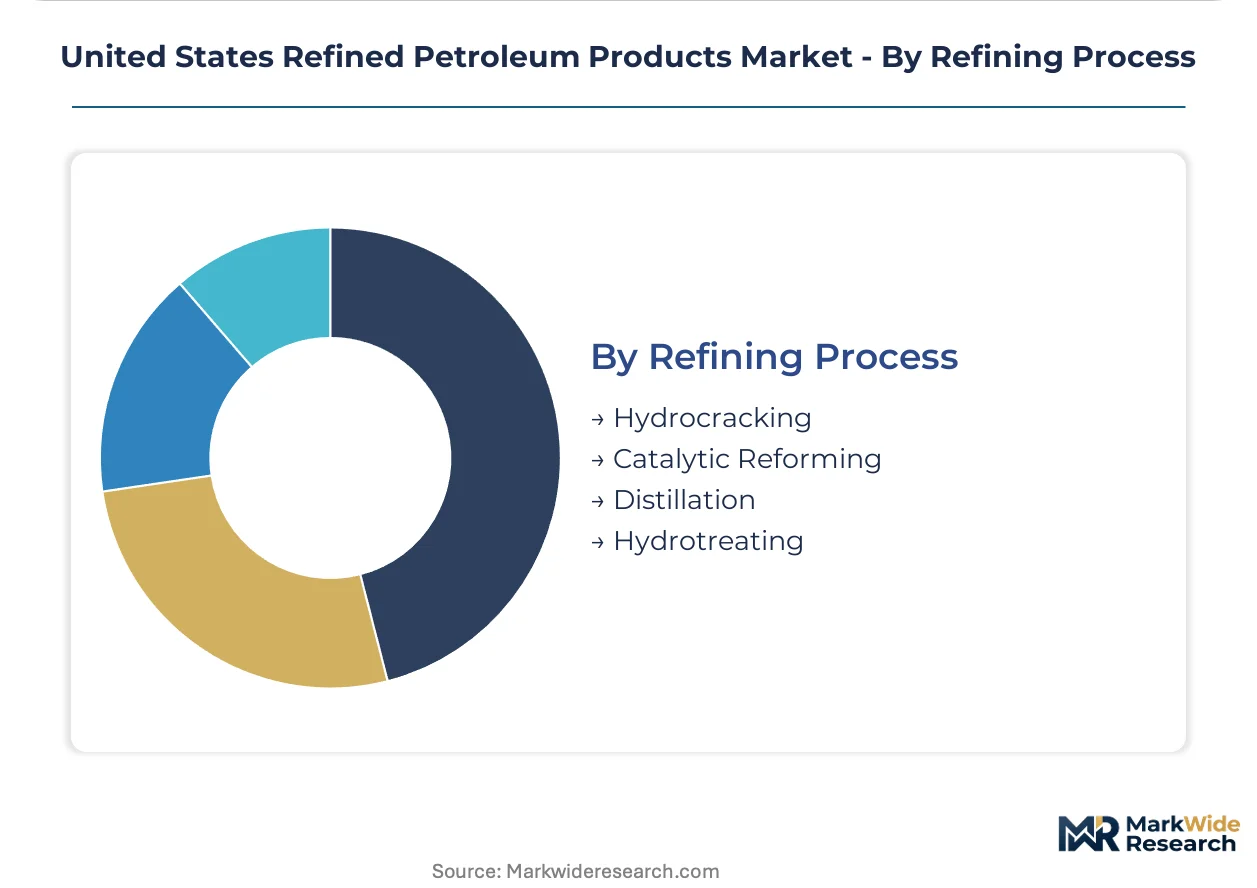
Refining Process:
Maturity and capital intensity separate legacy distillation assets from complex conversion units.
- Hydrocracking:High-pressure hydrogen addition to crack heavy gas oils into middle distillate and naphtha range products. Gulf Coast refiners with hydrocracker capacity capture premium margins on low-sulfur diesel and jet fuel production.
- Catalytic Reforming:Platinum-catalyst conversion of naphtha into high-octane reformate for gasoline blending pool upgrade. Texas and Louisiana facilities with continuous catalyst regeneration achieve superior aromatics yields.
- Distillation:Atmospheric and vacuum separation of crude oil into fractionated boiling range cuts.
- Hydrotreating:Catalytic hydrogenation to remove sulfur, nitrogen, and oxygen heteroatoms from intermediate streams.
Distillation holds installed capacity. Hydrocracking is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between the Gulf Coast refining corridor and the demand-heavy coasts. The former processes heavy sour crudes for export markets while the latter imports refined products through marine terminals to meet transportation and heating requirements.
Texas Gulf Coast
Refinery throughput along the Houston Ship Channel and Port Arthur complex supplies gasoline and diesel to the Southeast and Midwest markets. EPA Tier 3 sulfur mandates force continuous hydrotreater investment at Beaumont and Baytown facilities. The Permian Basin's associated gas liquids feed regional petrochemical expansion.
California
Transportation fuel demand concentrates in Los Angeles and San Francisco metropolitan corridors with stringent CARB low-carbon fuel standards. The state's sustainable aviation fuel mandates compress conventional jet fuel market share. Refiners with secured waste feedstock supply chains capture LCFS credit premiums.
Louisiana
The Mississippi River corridor hosts complex coking and alkylation capacity serving barge markets upriver to Chicago and eastward to Florida. OSHA refinery safety mandates shape turnaround scheduling at aging fluid catalytic cracking units. Baton Rouge and Lake Charles facilities anchor Gulf Coast export capacity.
Midwest
Iowa and Illinois soybean crush expansions position regional refiners for integrated renewable diesel production. Marathon Petroleum's retail and refining integration dominates local gasoline distribution. Chicago rack pricing sets regional benchmarks for diesel and jet fuel procurement.
Northeast
Heating oil demand concentrates in New England and Mid-Atlantic states with legacy tank infrastructure. Marine terminals at New York Harbor and Philadelphia supply refined products from Gulf Coast and foreign sources. Winter specification changes for gasoline volatility create seasonal logistics challenges.
United States Refined Petroleum Products Market Competitive Landscape
Capability concentration sits with integrated majors possessing complex conversion capacity; scale advantage sits with independent refiners with geographic positioning. The market structure tiers between national integrated operators with retail networks and independent refiners focused on wholesale rack sales. Three archetypes dominate: Gulf Coast export-oriented complexes, Midwest retail-integrated systems, and renewable diesel retrofit specialists. Competitive moves center on hydrotreater co-processing investments and long-term offtake contracting with fleet operators.
Within the integrated major tier, Marathon Petroleum, Valero Energy, and ExxonMobil exemplify divergent strategic positioning. Marathon anchors Midwest retail and refining integration with terminal networks extending into the Southeast. Valero occupies a position at the Gulf Coast export nexus with marine terminal access and international trading operations. ExxonMobil represents the capital-intensive complex refinery archetype with premium product yield optimization. These three entities collectively illustrate how geographic positioning and downstream integration depth determine margin capture in a regulatory environment tightening product specifications.
| Leading Market Players |
|---|
| Marathon Petroleum |
| Valero Energy |
| ExxonMobil |
| Phillips 66 |
| PBF Energy |
| Chevron Corporation |
| Citgo |
| HF Sinclair |
| BP |
| Others |
Value Network & Pricing Analysis
Gulf Coast refinery utilization rates above 90 percent are compressing crack spreads and forcing buyers into longer-term procurement commitments. This tightness rewards complex facilities with hydrocracking and coking capacity while squeezing simple refiners on margin capture.
Pricing Analysis
Long-term offtake agreements now dominate jet fuel and diesel procurement as fleet operators seek price certainty against WTI volatility. Three-tier pricing structure across premium low-sulfur, standard highway diesel, and economy residual fuel oil segments reflects sulfur content and cetane specifications. Cost compression in the residual fuel tier is intensifying because IMO 2020 marine fuel shifts have redirected bunker demand toward VLSFO blending. Wholesale rack buyers exhibit highest price sensitivity due to thin margin structures, while airlines with carbon reporting obligations show lowest sensitivity to secure LCFS-compliant supply.
Supply Chain Analysis
Extended payment terms from integrated majors to Permian crude suppliers are reshaping working capital dynamics across the value chain. Feedstock sourcing draws from Texas, Louisiana, and Oklahoma production basins with heavy reliance on West Texas Intermediate, Permian associated gas liquids, and imported heavy sour crudes. Single-source vulnerability concentrates in the Houston Ship Channel logistics corridor where hurricane disruption risks cascade through national gasoline supply. Distribution runs through pipeline networks to Midwest terminals, barge movements up the Mississippi River, and marine exports from Gulf Coast ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's Low Carbon Fuel Standard credit markets are accelerating a bifurcation between legacy hydrocarbon processors and integrated biofuel producers, creating asymmetric returns for first movers in renewable diesel retrofit.
For Market Incumbents: Insulate hydrocracker margins by securing long-term tallow and used cooking oil supply chains before waste feedstock premiums escalate. Accelerate hydrogen refinery integration at Texas and Louisiana facilities to capture IRA production tax credits and decarbonize process hydrogen supply. These moves defend against Neste and Diamond Green Diesel capacity additions threatening middle distillate market share.
For New Entrants and Emerging Players: Iowa and Illinois soybean crush corridors offer underpenetrated entry points for integrated renewable diesel and sustainable aviation fuel production. Target Midwest fleet operators with carbon intensity documentation requirements through direct offtake contracting rather than wholesale rack competition. Partner with existing terminal networks to bypass billion-dollar greenfield refinery capital barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across renewable diesel retrofit projects as hydrotreater co-processing halves standalone facility costs. The five-to-ten-year viability window favors refiners with secured waste feedstock supply chains and LCFS credit generation capacity. Watch California Air Resources Board carbon intensity scoring methodology revisions as the signal for feedstock cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrotreater Co-Processing Retrofit | Valero and Marathon are collapsing capital barriers between conventional refining and biofuel production. |
| Long-Term Fleet Offtake Agreements | Marathon and ExxonMobil are locking multi-year jet fuel contracts with airlines requiring carbon intensity documentation. |
| Blue Hydrogen Refinery Integration | Texas and Louisiana facilities can decarbonize hydrocracker hydrogen supply while capturing IRA production tax credits. |
| Midwest Renewable Fuel Hub Development | Iowa and Illinois soybean crush expansions position regional refiners for integrated renewable diesel production. |
| Waste Feedstock Supply Chain Securement | Refiners with tallow and used cooking oil contracts capture LCFS credit premiums as CARB penalizes soybean indirect land-use change emissions. |
Research Methodology
Initial hypotheses were tested against primary input from refinery operations managers, fuel procurement directors at fleet operators, EPA regulatory affairs specialists, and renewable diesel project developers and refined through secondary validation. Refinery utilization data from EIA, EPA Tier 3 compliance filings, California Air Resources Board LCFS credit transaction records, and SEC 10-K disclosures from integrated majors anchored quantitative assessment. Bottom-up capacity modeling and top-down demand projection triangulation ensured segment-level consistency.
Demand-supply-balance dynamics across the projection horizon anchored the analytical framework with segmentation across product type, usage sector, distribution channel, and refining process complexity tiers. CAGRs were derived from rolling average investment cycles and regulatory compliance timelines rather than single-year anomalies. Permian Basin associated gas liquids output trajectories and sustainable aviation fuel mandate implementation schedules served as critical forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by merchant renewable diesel specialists or integrated oil majors accelerating hydrogen refinery investments would shift outcomes. Macroeconomic deviation, EPA sulfur standard revisions, or breakthroughs in electrochemical fuel synthesis would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Oil Refinery Market
Petroleum Products
Underground Storage Tanks Market
Petroleum Products
Petroleum Benzine Market
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Pyrolysis Oil Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Base Oil Market
Petroleum Products
Oil Refining Market
Petroleum Products
Oil Storage Sales Market
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
Oil Shale Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market
Petroleum Products
Malaysia Refined Petroleum Products Market