
 Oil Shale Market | 2026-2036
Oil Shale Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Shale Market Intelligence
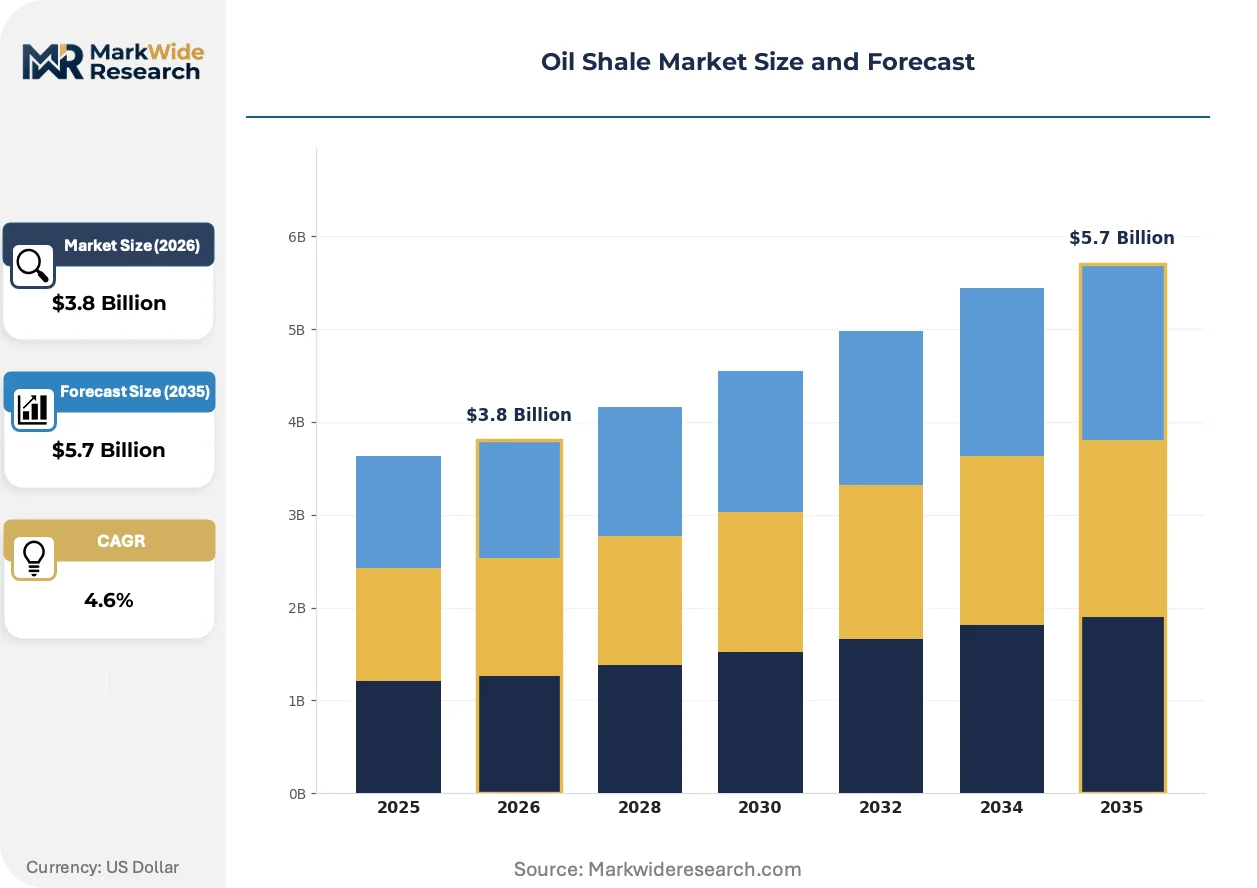
The United Nations Framework Classification for Resources (UNFC) is rotating the basis of project bankability from purely volumetric estimates to commercially recoverable reserves. This shift favors operators with proven, environmentally compliant extraction technologies. Shell PLC leverages its extensive research into in-situ heating processes to unlock complex formations. Meanwhile, ExxonMobil sustains its market position through large-scale project management capabilities and integrated downstream infrastructure that processes the synthetic crude oil.
Oil shale is a fine-grained sedimentary rock rich in kerogen, an organic chemical compound. Through processes like pyrolysis, the kerogen is heated to high temperatures in the absence of oxygen, converting it into a synthetic crude oil and combustible gas. Its primary purpose is to serve as an alternative source for liquid transportation fuels and as a fuel for power generation. Analysis of extraction methods shows in-situ conversion gaining preference over surface mining due to a smaller environmental footprint. In end-use applications, power generation remains the dominant segment, though its use as a chemical feedstock for petrochemical manufacturing is expanding.
The regulatory environment is defined by stringent environmental oversight. In the United States, the Environmental Protection Agency (EPA) enforces regulations on water usage and air emissions from processing facilities. Concurrently, China's national 'dual carbon goals' create long-term uncertainty for fossil fuel investments, impacting capital allocation for new oil shale projects. Stakeholders must now navigate a complex trade-off between energy security objectives and mounting pressure to meet climate-related disclosure and performance standards.
Market Dynamics
The primary structural force shaping the oil shale market is the reclassification of reserves under frameworks like the United Nations Framework Classification for Resources (UNFC). This change prioritizes commercially recoverable and environmentally compliant projects, steering investment away from purely volumetric resource estimates.
Growth Catalysts
- In-Situ Technology Advancement:The development of more efficient in-situ conversion processes reduces the environmental footprint and improves project economics. This technological progress makes oil shale extraction more viable under increasingly strict environmental oversight.
- Energy Security Objectives:Demand for alternative domestic energy sources supports oil shale development, particularly in countries seeking to reduce reliance on imported crude oil. Power generation remains a primary end-use driving this demand.
- Concentrated Resource Deposits:The vast, geographically concentrated deposits within the United States, specifically the Green River Formation, create economies of scale for infrastructure development, R&D, and specialized labor pools.
Market Restraints
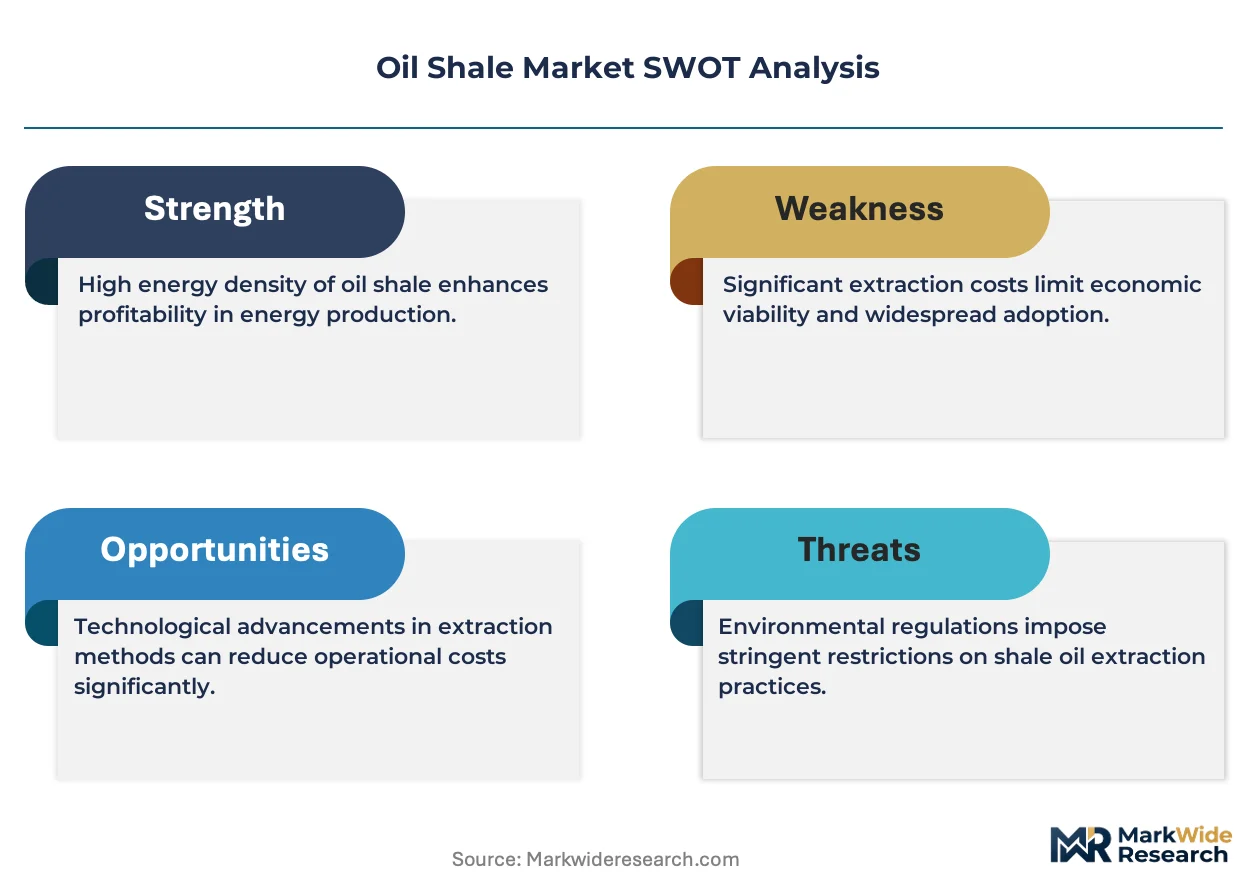
- Stringent Environmental Regulations:Rules enforced by bodies like the US Environmental Protection Agency (EPA) on water usage and air emissions add significant compliance costs. In parallel, China's 'dual carbon goals' create long-term capital investment uncertainty.
- High Input Intensity:The pyrolysis process is inherently energy- and water-intensive, establishing a high cost floor for production. This makes project profitability highly sensitive to fluctuations in global crude oil prices and local utility costs.
- Renewable Energy Substitution:The decreasing cost of renewable energy sources, such as solar and wind power, presents a significant long-term substitution threat for oil shale in the power generation sector.
Strategic Opportunities
- Petrochemical Feedstock Diversification:Utilizing synthetic crude oil derived from kerogen as a feedstock for producing high-value chemicals presents a significant opportunity. This diversifies revenue streams beyond liquid transportation fuels and power generation.
- Carbon Capture Integration:Co-locating carbon capture, utilization, and storage (CCUS) systems with in-situ processing facilities can help projects meet climate targets. This approach can improve social license and access to green financing.
- Development of Untapped Resources:Exploring and developing significant oil shale deposits outside of the US, such as those in Jordan and Morocco, represents a long-term growth frontier for operators with proven extraction technologies.
Industry Challenges
- High Capital Expenditure:Securing the substantial, long-term financing required for large-scale in-situ heating grids and upgrading facilities remains a primary operational hurdle for project developers.
- Water Resource Management:Operating in the often arid regions where oil shale is found, like the western United States, creates complex logistical and regulatory challenges related to sourcing, using, and disposing of large volumes of water.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Shale Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Extraction Method: Surface Mining, In-situ Conversion, Retorting, Hydraulic Fracturing End Use Application: Power Generation, Chemical Feedstock, Lubricants, Petrochemical Manufacturing Processing Technology: Direct Combustion, Pyrolysis, Gasification, Carbonization Consumer Segment: Refineries, Industrial Fuel Users, Energy Producers, Infrastructure Developers |
| Companies Covered | ExxonMobil, Occidental Petroleum, Chevron Corporation, Shell PLC, ConocoPhillips, Marathon Oil Corporation, AuraSource, Inc., Expand Energy, Shale Energy International, LLC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Shale Market Strategic Shifts & Innovations
Technological advancements are converging with stringent environmental standards to redefine project viability. This dynamic forces a focus on processes that minimize surface disruption and manage emissions, influencing both extraction methods and end-use applications across the market.
Advanced in-situ heating methods, such as targeted radio frequency (RF) heating, enable more precise and efficient kerogen conversion deep underground. Project operators are increasingly adopting these modular techniques to develop smaller, less capital-intensive sites. This shift toward smaller, targeted extraction is fragmenting the traditional large-scale, single-site project model into a portfolio of more manageable, staged developments.
China's national 'dual carbon goals' aim for carbon neutrality and place long-term pressure on all fossil fuel industries. The policy framework creates significant investment uncertainty and tightens capital allocation for new, large-scale oil shale projects within the country. Consequently, domestic operators are compelled to prioritize research into cleaner extraction technologies and integrated carbon management to align with state directives.
A clear shift in project financing criteria is occurring, with investors prioritizing commercially proven reserves over speculative volumetric estimates. This displaces the old model of funding based on total resource-in-place, favoring operators who can demonstrate bankable reserves under frameworks like the UNFC. This trend is most pronounced in the United States, where access to capital for Green River Formation projects now depends on showing a clear path to commercial production with manageable environmental risk.
Oil Shale Market Segmentation
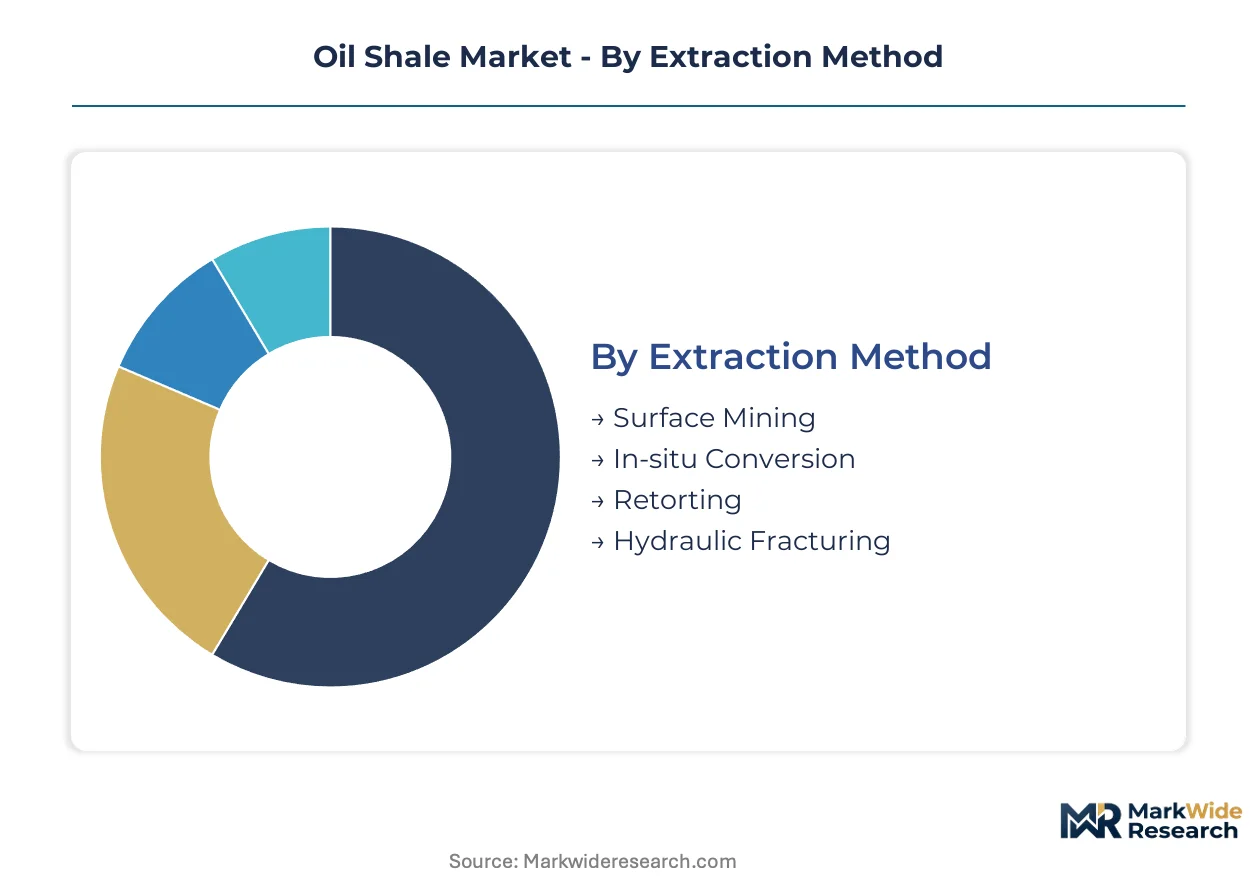
The oil shale market's segmentation reflects the complex interplay of resource extraction, processing technologies, and diverse end-use applications. Understanding these distinct segments is crucial for stakeholders to identify areas of commercial viability and navigate evolving regulatory landscapes in the United States and other resource-rich regions.
Extraction Method:
Regulatory differentiation heavily influences the adoption of various oil shale extraction methods, particularly concerning environmental impact and resource efficiency. The US Environmental Protection Agency (EPA) scrutinizes water usage and emissions, favoring less disruptive techniques.
- In-situ Conversion:This method involves heating kerogen underground, converting it into synthetic crude oil and gas that can be pumped to the surface. Its smaller environmental footprint and reduced surface disruption make it increasingly preferred under stringent environmental oversight, particularly for Green River Formation projects.
- Surface Mining:Traditional surface mining techniques involve excavating oil shale rock from open pits, which is then transported for processing. This method is capital-intensive and faces significant environmental challenges related to land disturbance and waste disposal, particularly in regions with sensitive ecosystems.
- Retorting:External retorting processes heat mined oil shale in above-ground vessels to extract synthetic crude oil. This technology requires substantial energy input and generates large volumes of spent shale, posing waste management challenges for operators.
- Hydraulic Fracturing:While not a primary method for oil shale, hydraulic fracturing can be used to enhance permeability in certain kerogen-rich formations, facilitating fluid flow for in-situ processes.
Established volume favors Surface Mining; emerging adoption favors In-situ Conversion.
End Use Application:
Market demand and utility drive the segmentation of oil shale products across various end-use applications. The versatility of synthetic crude oil and combustible gas enables its deployment in multiple industrial sectors.
- Power Generation:Oil shale serves as a direct fuel source for thermal power plants, contributing significantly to electricity grids in regions with abundant deposits. This application remains the dominant segment due to energy security objectives in countries like the United States.
- Chemical Feedstock:Synthetic crude oil derived from kerogen can be processed into various chemical building blocks for industrial manufacturing. This segment represents a significant diversification opportunity, expanding revenue streams beyond traditional energy applications.
- Lubricants:Specific fractions of synthetic crude oil can be refined to produce base oils for lubricants used in various machinery and industrial equipment. This niche application leverages the unique chemical properties of kerogen-derived products.
- Petrochemical Manufacturing:Oil shale derivatives can feed into the petrochemical industry to produce plastics, resins, and other synthetic materials. This segment aligns with broader trends toward diversifying feedstocks for chemical production.
Demand for Power Generation provides stability, while Chemical Feedstock represents a significant diversification opportunity.
Processing Technology:
Technical efficiency and environmental considerations differentiate the various processing technologies employed to convert oil shale into usable energy products. Each method presents unique advantages and challenges for project developers.
- Pyrolysis:This core process involves heating kerogen to high temperatures in the absence of oxygen, converting it into synthetic crude oil and combustible gas. Advanced pyrolysis methods, including targeted radio frequency (RF) heating, enhance efficiency and reduce the environmental footprint.
- Gasification:Oil shale gasification converts the solid rock into a synthesis gas (syngas), a mixture of hydrogen, carbon monoxide, and other gases. Syngas can be used for power generation or as a chemical feedstock, offering flexible energy output.
- Direct Combustion:Direct combustion involves burning raw oil shale directly in boilers to generate heat for steam production, primarily for power generation. This method is less efficient and produces higher emissions compared to other processing technologies.
- Carbonization:Carbonization processes aim to produce a carbon-rich solid residue (char) alongside liquid and gaseous products. This technology can be integrated with other processes to optimize resource recovery.
Pyrolysis remains a foundational approach, but Gasification offers enhanced resource utilization.
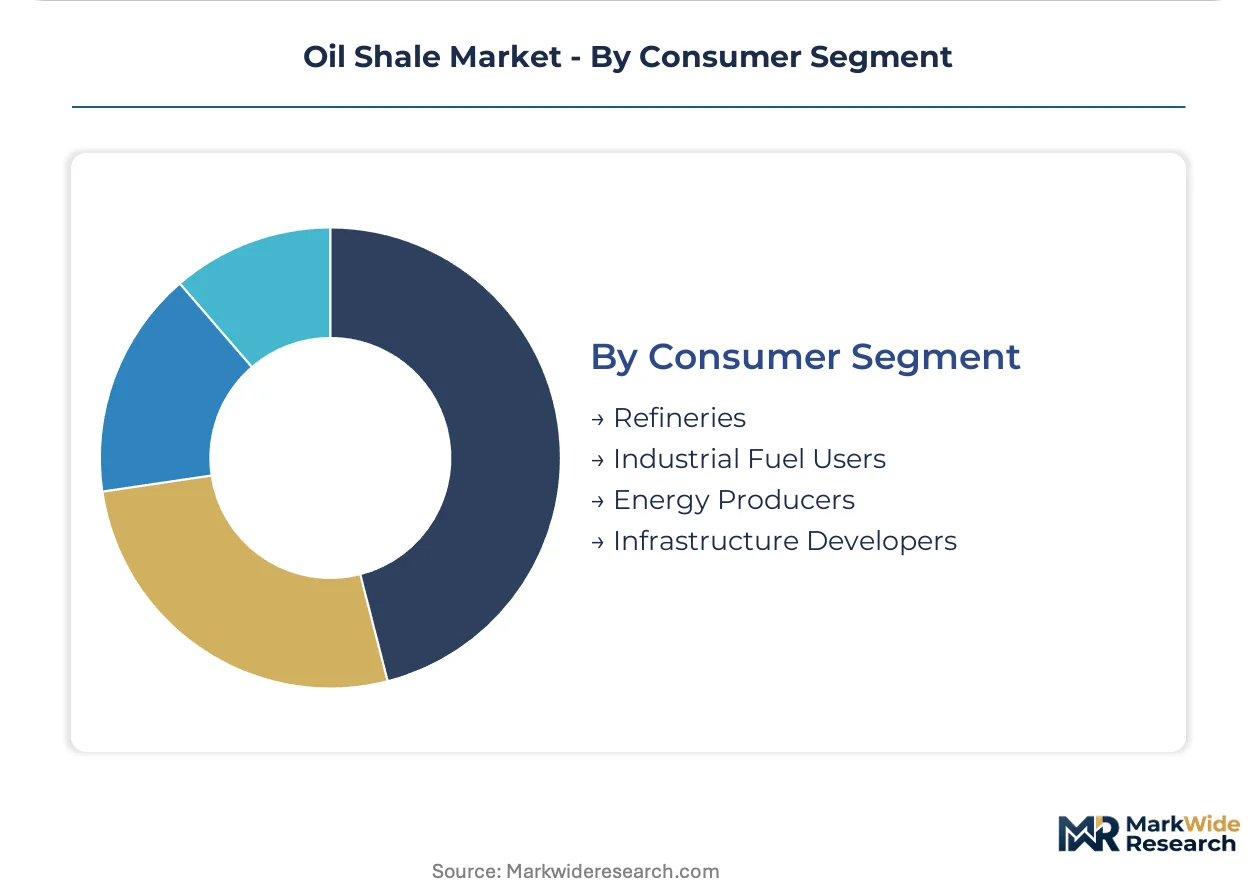
Consumer Segment:
The operational scale and strategic integration define customer groups within the oil shale market, influencing demand patterns and supply chain dynamics. These segments interact at various stages of the value chain.
- Energy Producers:Companies involved in the direct extraction and initial processing of oil shale fall into this segment. They focus on optimizing conversion technologies and managing the primary resource.
- Refineries:Refineries process the synthetic crude oil derived from oil shale into various petroleum products, including transportation fuels and chemical feedstocks. Their demand is driven by the need for alternative crude sources.
- Industrial Fuel Users:This segment comprises industries that utilize oil shale or its derivatives directly as a fuel source for their operations. Their consumption is often tied to local availability and cost-effectiveness compared to other fuels.
- Infrastructure Developers:Entities responsible for building and maintaining the necessary infrastructure for oil shale projects, such as pipelines, processing plants, and power transmission lines, form this segment. Their involvement is critical for project viability.
Energy Producers drive primary production, while Refineries integrate the synthetic crude into broader energy systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The extensive pipeline networks facilitating crude transport underwrite the United States' pivotal role in oil shale development. These critical infrastructure assets enable the efficient movement of synthetic crude oil from extraction sites to processing facilities, supporting regional market dynamics. Significant investments in upgrading processing capabilities further support market growth across these geographies.
United States
The United States' demand for alternative domestic energy sources supports oil shale development, particularly for power generation. The US Environmental Protection Agency (EPA) enforces stringent regulations on water usage and air emissions from processing facilities, adding compliance costs. The Green River Formation, spanning Colorado, Utah, and Wyoming, concentrates significant in-situ conversion projects for commercial viability.
China
China's energy security objectives drive interest in its vast oil shale deposits, aiming to reduce reliance on imported energy. The national 'dual carbon goals' create long-term uncertainty for fossil fuel investments, compelling research into cleaner extraction technologies. Domestic operators in regions like Fushun are prioritizing integrated carbon management solutions to align with state directives.
Jordan
Jordanian efforts to achieve energy independence are increasing focus on indigenous oil shale resources for power generation. Government initiatives support the exploration and development of these strategic reserves, attracting international investment for large-scale projects. The Attarat Um Ghudran project exemplifies a major undertaking for power generation in the country's energy sector.
Morocco
Morocco's strategic objective to diversify its energy mix includes leveraging its oil shale potential for industrial growth. National energy policies encourage the assessment of viable extraction technologies and resource utilization. The Tarfaya oil shale deposits are attracting attention from operators with proven in-situ conversion expertise for future development.
Oil Shale Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of oil shale extraction and processing technologies. The market structure features large integrated energy majors alongside smaller, technology-focused developers. Strategic archetypes include resource holders, in-situ technology innovators, and downstream refiners. Dominant competitive moves involve technology licensing and strategic partnerships to navigate complex regulatory environments.
Integrated energy majors like ExxonMobil and Shell PLC represent established players with extensive capital and project management capabilities, securing their market position through integrated downstream infrastructure. These global entities process synthetic crude oil into various products, maintaining a broad energy portfolio and supply chain control. Meanwhile, AuraSource, Inc. exemplifies a technology-focused specialist, contributing to the market's technological evolution with advanced extraction methods. Such specialized firms often partner with larger players to deploy efficient in-situ conversion processes and manage complex resource development projects, focusing on niche solutions and environmental compliance.
| Leading Market Players |
|---|
| ExxonMobil |
| Occidental Petroleum |
| Chevron Corporation |
| Shell PLC |
| ConocoPhillips |
| Marathon Oil Corporation |
| AuraSource, Inc. |
| Expand Energy |
| Shale Energy International, LLC. |
| Others |
Cost & Logistics Intelligence
Renewable energy substitution for oil shale in power generation reshapes supply geography and pricing economics. This shift reorients investment towards lower-carbon alternatives and impacts long-term oil shale project viability.
Pricing Analysis
Contract-based long-term offtake agreements dominate the oil shale market, providing stability for large-scale projects. Project scale and environmental compliance certifications drive price differentiation, reflecting investment in sustainable practices. Pricing softness reflects decreasing costs of renewable energy alternatives, particularly for power generation applications. Power generation utilities are highly price-sensitive, while chemical feedstock buyers show moderate sensitivity due to diversification needs.
Supply Chain Analysis
Water resource availability in arid regions underwrites operational viability for oil shale projects. The United States (Green River Formation), China, and Jordan concentrate global oil shale resources. Large-scale in-situ heating grids and water are critical inputs for extraction. Regulatory restrictions on water usage pose a significant structural supply chain risk. Distribution runs through integrated pipeline networks to refineries and power plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oil shale market presents a service-attach opportunity, with carbon capture integration and environmental compliance services expanding faster than primary extraction hardware deployment. This emphasizes value creation beyond raw resource production.
For Market Incumbents: Secure long-term offtake agreements with power generation utilities to stabilize revenue against renewable energy substitution. Invest in advanced in-situ conversion R&D to maintain cost competitiveness against emerging alternatives. Acquire specialized technology firms focusing on water management and emission reduction to mitigate regulatory threats. Vertical integration into petrochemical processing offers a key lever for value capture.
For New Entrants and Emerging Players: Differentiate on environmental compliance and resource efficiency using advanced in-situ technologies. Target the chemical feedstock segment in regions like the United States, which values feedstock diversification from traditional crude sources. Focus on developing smaller, modular projects in the Green River Formation. Partner with established energy majors to leverage their capital and downstream infrastructure.
For Investors and Strategic Acquirers: The market sits at a mature development phase that favors technology-focused specialists with proven environmental compliance. Long-term viability rests on successful integration of carbon capture and water management solutions. Seek out innovative firms like AuraSource, Inc. with proprietary in-situ conversion technologies. The signal to watch is the broader adoption rate of CCUS in fossil fuel projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced In-Situ RF Heating | Improves kerogen conversion efficiency and reduces surface disruption, aligning with US EPA regulations. |
| Develop Carbon Capture, Utilization, and Storage (CCUS) | Helps projects meet China's dual carbon goals and improves access to green financing for operators. |
| Expand Petrochemical Feedstock Processing | Diversifies revenue streams for ExxonMobil beyond liquid fuels, leveraging synthetic crude oil. |
| Secure Long-Term Offtake Agreements | Stabilizes demand for oil shale from power generation utilities amid energy transition pressures. |
| Partner for Water Resource Management | Addresses critical operational challenges in arid regions like the Green River Formation for project viability. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews, validated by secondary data. Stakeholders included refinery procurement managers, power utility planning officers, in-situ technology R&D directors, and environmental compliance specialists. Secondary sources comprised government energy agency reports (EIA), corporate financial filings (SEC 10-K), and academic research on kerogen conversion. This approach ensured robust bottom-up and top-down triangulation.
The market forecast, spanning across the analysis window, segments by extraction method, end-use application, processing technology, and regional regulatory frameworks. Compound annual growth rates were derived from historical data analysis and projected technological adoption curves. Key forecast inputs included global crude oil price trends and renewable energy cost trajectories.
Material uncertainties—including shifts in climate policy and unforeseen technological breakthroughs—sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory stability and energy security priorities. Practitioners should keep alternative scenarios live as global energy markets evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
India White Oil Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Automotive Oil Market
Petroleum Products
Uganda Petroleum Products Market
Petroleum Products
Crude Oil Market
Petroleum Products
Naphtha Market
Petroleum Products
Balanos Oil Market
Petroleum Products
Floating Roof Tank Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
North Africa Refined Petroleum Products Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market
Petroleum Products
Helical Submerged Arc Welded Pipe Market
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
United States Refined Petroleum Products Market