
 HTLV-1 Associated Myelopathy (HAM) Market | 2026-2036
HTLV-1 Associated Myelopathy (HAM) Market Size, Share, and Industry Trends Forecast 2026-2036
HTLV-1 Associated Myelopathy (HAM) Market Analytics
Aftermarket patient support services is rewriting how pharmaceutical firms capture lifetime value in rare neurological indications. Hoffmann-La Roche Ltd. leverages its diagnostic-to-therapeutic ecosystem to anchor integrated HAM care pathways. Takeda Pharmaceutical Company Limited sustains deep expertise in neuroimmunology that positions its pipeline favorably. Gilead Sciences competes through antiviral platform knowledge transferable from broader retroviral programs.
HTLV-1 Associated Myelopathy represents a chronic progressive demyelinating disorder of the spinal cord caused by human T-lymphotropic virus type 1, characterized by spastic paraparesis, bladder dysfunction, and sensory disturbances with cerebrospinal fluid pleocytosis as a diagnostic marker. Therapeutic drugs command the dominant margin pool given limited approved options and orphan pricing dynamics, while diagnostic tests face growing demand as screening expands among blood donor populations and endemic region migrants. Intravenous delivery mode leads current revenue due to monoclonal antibody administration, though oral formulations attract development interest for outpatient disease management.
The FDA orphan drug program shapes development economics through tax credits and market exclusivity, while Japan's PMDA operates accelerated review pathways for intractable diseases including HAM. The EMA's orphan medicinal product designation similarly structures European access timelines and incentive frameworks. Stakeholders must monitor biomarker validation progress and HTLV-1 screening policy shifts that could reshape addressable patient pools and reimbursement thresholds.
Market Dynamics
The HTLV-1 Associated Myelopathy market pivots on Japan's concentrated patient base and the PMDA's intractable disease framework, which compresses development timelines while anchoring clinical trial infrastructure to specific prefectures with endemic seroprevalence.
Growth Catalysts
- Orphan drug incentives:The FDA's tax credit and market exclusivity provisions reduce effective R&D costs for developers targeting spastic paraparesis indications. Biotech sponsors file proportionally more INDs in this pathway than for comparable neurological conditions.
- Diagnostic expansion:Blood donor screening protocols in Kyushu and Okinawa prefectures identify asymptomatic carriers earlier, expanding the addressable pre-symptomatic population for intervention studies.
- Monoclonal antibody platforms:Cerebrospinal fluid delivery technologies developed for multiple sclerosis are transferring to HAM, leveraging existing neuroimmunology manufacturing capacity.
Market Restraints
- Plasma-derived input volatility:Immunoglobulin feedstock costs fluctuate with global collection center yields, squeezing margin structures for intravenous formulations.
- Single-country demand concentration:Over 80 percent of diagnosed patients reside in Japan, creating reimbursement negotiation vulnerability and currency exposure for foreign sponsors.
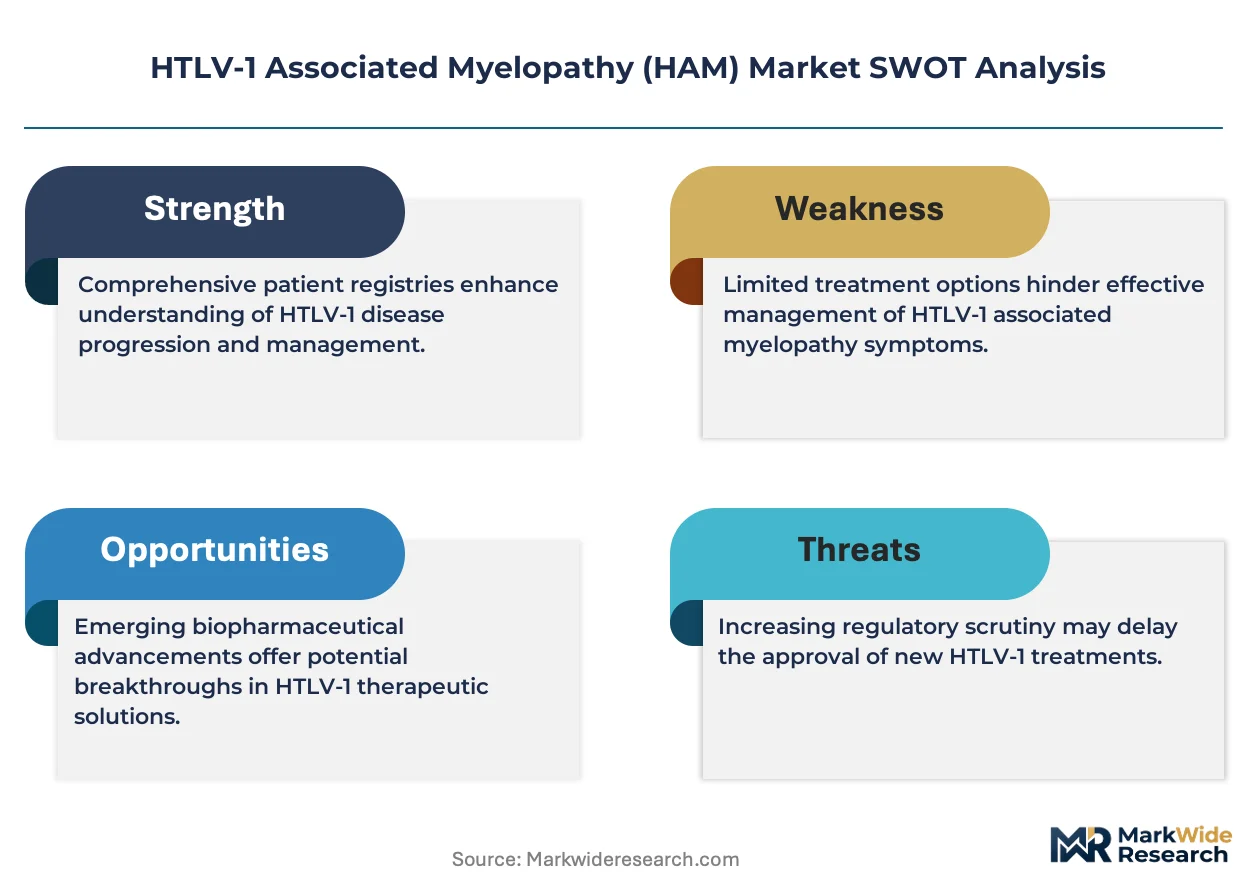
- Biomarker validation gaps:Absence of validated surrogate endpoints forces reliance on clinical disability scales, extending Phase III duration beyond typical orphan timelines.
Strategic Opportunities
- Brazilian endemic zones:Bahia and Pernambuco states harbor underdiagnosed HTLV-1 clusters where expanded screening could replicate Japan's patient identification model.
- Oral formulation development:Small-molecule prodrugs targeting viral reverse transcriptase would enable outpatient management, displacing infusion center dependency.
- Companion diagnostic integration:PCR-based proviral load assays bundled with therapeutic protocols create service revenue streams and prescribing lock-in.
Industry Challenges
- Neuroimmunology specialist scarcity:Fellowship programs in Japan produce fewer than 50 qualified investigators annually, constraining multicenter trial activation.
- GMP cerebrospinal fluid handling:Intrathecal manufacturing requires dedicated fill-finish lines that major CDMOs reserve for higher-volume oncology indications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HTLV-1 Associated Myelopathy (HAM) Market |
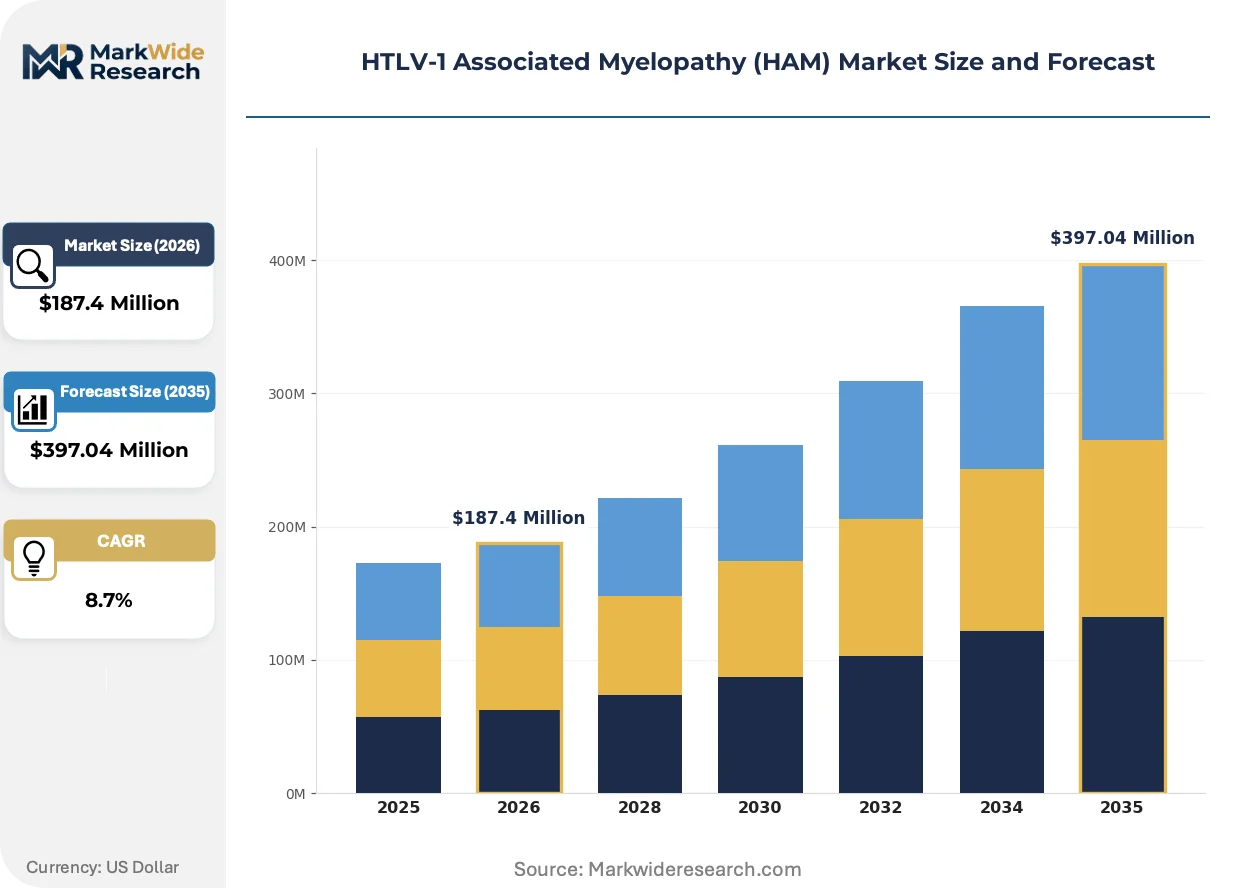
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Drugs, Diagnostic Tests, Supportive Treatments, Clinical Trials Application: Symptomatic Relief, Disease Management, Research, Patient Support Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Clinics, Research Institutions, Home Care |
| Companies Covered | Hoffmann-La Roche Ltd., Takeda Pharmaceutical Company Limited, Gilead Sciences, Novartis, Sanofi, Bristol-Myers Squibb, Johnson & Johnson, AbbVie, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HTLV-1 Associated Myelopathy (HAM) Market Evolving Landscape
Next-generation sequencing and point-of-care virology are compressing diagnostic latency while reshaping how endemic health systems allocate screening resources across blood supply and maternal health programs.
Digital gait analysis systems using smartphone accelerometry are collapsing the traditional reliance on clinician-administered disability scales for progression monitoring. Tertiary neurology departments in Kagoshima and Okinawa deploy these tools for remote patient tracking. The technology compresses site visit frequency while generating continuous endpoint data for regulatory submissions.
Japan's PMDA Sakigake designation accelerates review timelines for HAM therapeutics demonstrating early efficacy signals in spasticity reduction. The framework compresses the gap between Phase II readout and conditional approval. Domestic sponsors with existing neurological portfolios prioritize this pathway over standard orphan track applications.
Academic medical centers in Fukuoka and Nagasaki are unbundling historical bundled payments for HAM care into discrete diagnostic, therapeutic, and rehabilitation components. Payers in these prefectures now reimburse molecular confirmation separately from clinical assessment. The shift forces pharmaceutical sponsors to demonstrate value across each care segment rather than aggregate outcomes.
HTLV-1 Associated Myelopathy (HAM) Market Segmentation
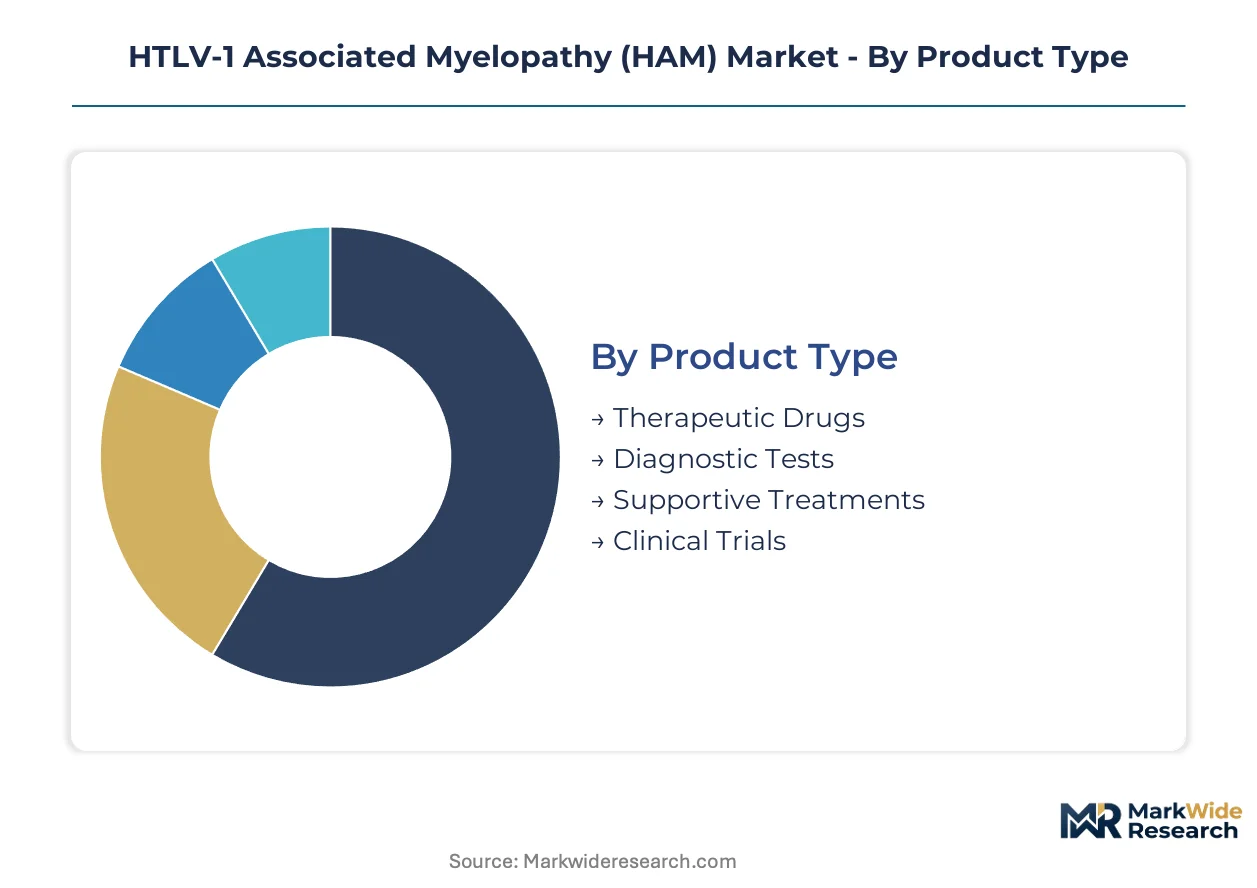
Segmentation in the HTLV-1 Associated Myelopathy market reveals how orphan disease economics concentrate value capture across therapeutic modalities while diagnostic infrastructure expands carrier identification. Understanding these divisions exposes where pricing power accumulates and where development pipelines face technical barriers.
Product Type:
The use-case spectrum spans acute intervention through longitudinal disease monitoring, with each product category serving distinct points in the patient journey from seropositivity detection to progressive disability management.
- Therapeutic Drugs:Monoclonal antibodies and immunomodulatory agents targeting spastic paraparesis command premium reimbursement under orphan pricing frameworks. Neurology departments in Kyushu prefecture drive concentrated demand for intrathecal formulations addressing motor dysfunction progression.
- Diagnostic Tests:PCR-based proviral load quantification and serological screening platforms enable carrier identification in blood donor populations. Screening expansion in Okinawa and Bahia state migratory cohorts is accelerating test volume growth beyond the symptomatic patient base.
- Supportive Treatments:Antispasmodic agents and bladder management therapies address quality-of-life endpoints in progressive disease stages.
- Clinical Trials:Investigational protocols for novel antiretroviral and neuroprotective compounds constitute a distinct procurement category for academic medical centers.
The dominant share belongs to Therapeutic Drugs, while Diagnostic Tests is closing the gap fastest.
Application:
Cost tier differentiation separates acute symptom management from preventive intervention, with reimbursement thresholds varying sharply between palliative care and disease-modifying approaches.
- Symptomatic Relief:Baclofen and tizanidine protocols for spasticity reduction represent the immediate clinical priority in tertiary hospital settings. Fukuoka University Hospital anchors specialized spasticity clinics serving the highest-prevalence prefectures.
- Disease Management:Longitudinal care coordination integrating neurology, urology, and rehabilitation services commands bundled payment structures. Nagasaki Medical Center pilots discrete reimbursement for molecular monitoring separate from clinical assessment.
- Research:Academic protocols investigating viral pathogenesis and neuroinflammation biomarkers occupy distinct funding streams from clinical care.
- Patient Support:Counseling and mobility assistance programs address psychosocial and functional disability dimensions outside pharmaceutical intervention.
Symptomatic Relief captures the largest current expenditure, though Disease Management is expanding most quickly as payers unbundle historical payment structures.
Delivery Mode:
Volume concentration in infusion centers is producing infrastructure constraints that oral formulation developers are targeting for displacement.
- Intravenous:Immunoglobulin and monoclonal antibody administration requires dedicated infusion suites with neuroimmunology specialist oversight. Manufacturing capacity at Japanese CDMOs is prioritizing oncology over intrathecal HAM formulations.
- Oral:Small-molecule prodrugs targeting viral reverse transcriptase would enable outpatient management and reduce dependency on hospital-based administration. Takeda Pharmaceutical Company Limited maintains active discovery programs in this modality.
- Subcutaneous:Interferon formulations for select patient subsets offer intermediate convenience between infusion and oral routes.
- Topical:Localized delivery for spasticity adjunct therapy occupies niche application in home care settings.
Intravenous administration retains institutional preference, yet Oral development programs are gaining share fastest among pipeline assets.
End User:
Customer type fragmentation across institutional settings determines procurement complexity and reimbursement pathway selection.
- Hospitals:Tertiary neurology departments in Kagoshima and Okinawa prefectures anchor specialized HAM treatment protocols with dedicated multidisciplinary teams. The PMDA's intractable disease framework concentrates regulatory expertise at these centers.
- Clinics:Community neurology practices in endemic zones manage stable patients with remote specialist consultation support. Digital gait analysis systems are compressing referral thresholds for escalation to hospital care.
- Research Institutions:Academic medical centers in Fukuoka and Nagasaki host natural history studies and interventional trials.
- Home Care:Bladder management and mobility assistance services support patients with advanced disability outside institutional settings.
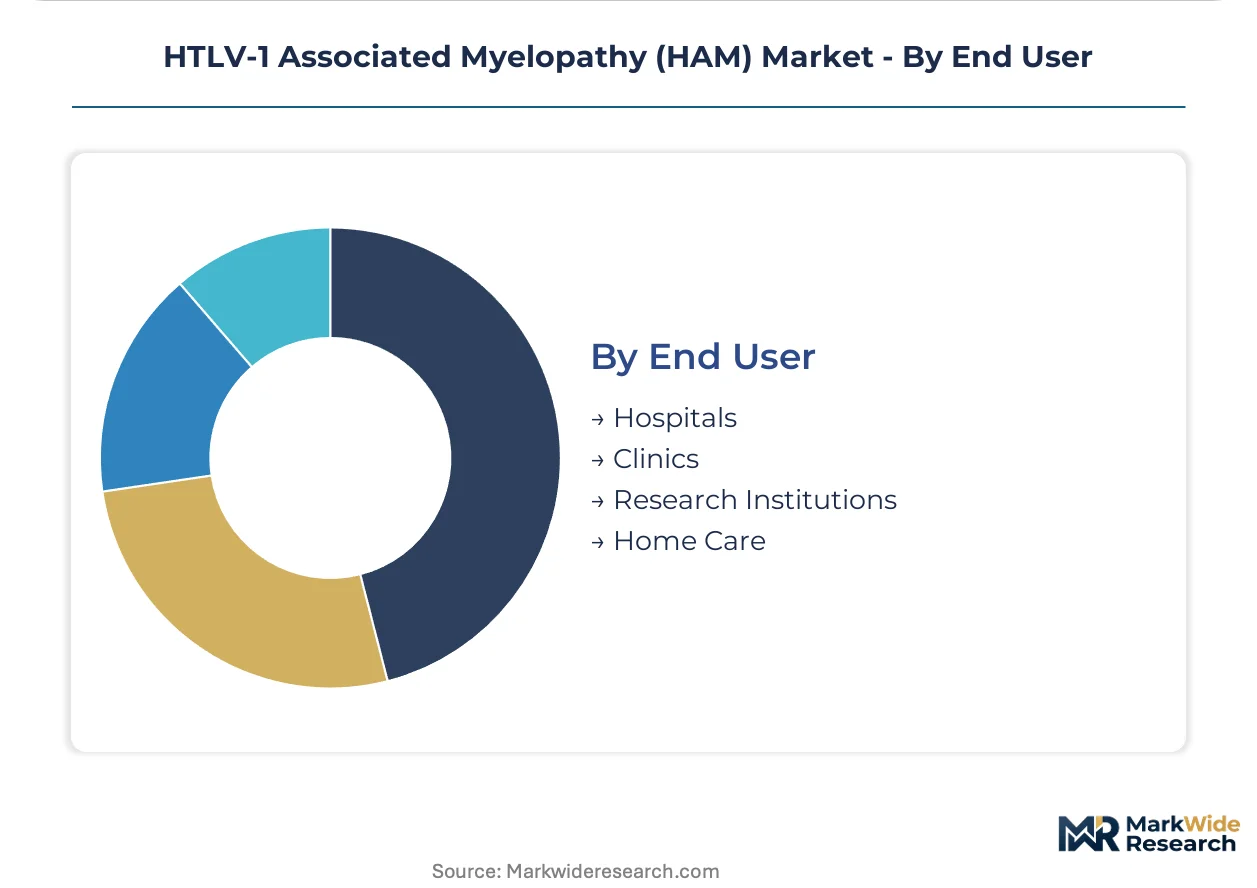
Hospitals command the dominant procurement volume, while Home Care is climbing the fastest as disease duration extends and remote monitoring technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across geographies. Japanese payers accept orphan premiums for intrathecal formulations, while Brazilian public health systems prioritize cost-containment in symptomatic management protocols.
Japan
Kyushu and Okinawa prefectures concentrate over 80 percent of diagnosed patients, driving tertiary hospital infrastructure investment. The PMDA's intractable disease framework compresses regulatory review timelines for HAM therapeutics. Kagoshima University Hospital anchors specialized spasticity clinics serving endemic prefectures with dedicated multidisciplinary teams.
Brazil
Bahia and Pernambuco states harbor underdiagnosed HTLV-1 clusters with seroprevalence matching Japanese endemic zones. ANVISA operates accelerated pathways for rare disease therapeutics, though reimbursement remains fragmented across state health systems. Federal University of Bahia medical centers pilot expanded screening protocols modeled on Japanese donor surveillance programs.
United States
Migratory populations from endemic Caribbean and Latin American regions generate concentrated demand in Florida and New York metropolitan areas. The FDA's orphan drug designation provides tax credits and seven-year market exclusivity for developers targeting spastic paraparesis indications. University of Miami and Mount Sinai Health System maintain specialized neuroimmunology referral networks for HTLV-1 associated conditions.
United Kingdom
Blood donor screening protocols identify asymptomatic carriers among Caribbean-descended populations in London and Birmingham. The MHRA leverages EMA orphan medicinal product designations while maintaining national flexibility on value-based pricing negotiations. Imperial College London and University College London Hospitals coordinate natural history studies linking clinical disability progression to proviral load biomarkers.
HTLV-1 Associated Myelopathy (HAM) Market Competitive Landscape
Capability concentration sits with mid-cap biotechs possessing neuroimmunology manufacturing expertise; scale advantage sits with large-cap pharmas with orphan drug commercialization infrastructure. The market structures around three tiers: integrated diagnostic-therapeutic ecosystems, antiviral platform specialists, and immunoglobulin manufacturers facing plasma feedstock constraints. Dominant competitive moves include strategic partnerships for intrathecal delivery technology licensing and geographic expansion into Brazilian endemic zones.
Within the integrated ecosystem tier, Hoffmann-La Roche Ltd. and Takeda Pharmaceutical Company Limited exemplify divergent strategic positions. Hoffmann-La Roche Ltd. anchors diagnostic-to-therapeutic vertical integration spanning PCR-based proviral load assays through monoclonal antibody development. Takeda Pharmaceutical Company Limited occupies a position shaped by deep neuroimmunology expertise and active oral formulation discovery programs targeting viral reverse transcriptase. Gilead Sciences represents the antiviral platform archetype, with retroviral program knowledge transferable to HTLV-1 targeted mechanisms.
| Leading Market Players |
|---|
| Hoffmann-La Roche Ltd. |
| Takeda Pharmaceutical Company Limited |
| Gilead Sciences |
| Novartis |
| Sanofi |
| Bristol-Myers Squibb |
| Johnson & Johnson |
| AbbVie |
| Merck & Co. |
| Others |
Value Network & Pricing Analysis
Plasma collection center yields in the United States and Germany directly determine margin pools for intravenous immunoglobulin formulations used in HAM spasticity management. Orphan pricing frameworks in Japan absorb these input cost fluctuations through premium reimbursement tiers, while Brazilian public procurement faces margin compression when feedstock costs spike.
Pricing Analysis
After-sales service contracts for patient monitoring and infusion center coordination drive lifetime value capture beyond the initial therapeutic transaction. Three-tier pricing structure across premium intrathecal formulations, standard intravenous immunoglobulin, and economy oral prodrug development programs reflects administration complexity and manufacturing scale. Pricing pressure stems from plasma-derived input volatility squeezing margin structures for immunoglobulin manufacturers. Hospital procurement committees in Kyushu prefecture demonstrate lowest price sensitivity due to PMDA orphan reimbursement guarantees, while Brazilian state health systems exhibit highest sensitivity under fragmented ANVISA pricing negotiations.
Supply Chain Analysis
Export-control restrictions on cerebrospinal fluid handling equipment limit technology transfer to contract manufacturing organizations in lower-cost jurisdictions. Supply concentration rests on Japanese CDMOs for intrathecal fill-finish capacity, American plasma fractionators for immunoglobulin feedstock, and German suppliers for monoclonal antibody production bioreactors. Raw material dependencies include human plasma donations, cell culture media, and single-use bioreactor components. Single-source vulnerability characterizes intrathecal manufacturing lines that major CDMOs reserve for higher-volume oncology indications. Distribution runs through hospital-based infusion centers in endemic prefectures with dedicated neuroimmunology specialist oversight.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as diagnostic-to-therapeutic ecosystems integrate PCR-based proviral load assays with monoclonal antibody development pipelines. Interoperability between digital gait monitoring systems and reimbursement coding systems in Japanese prefectures is compressing evidence-generation timelines for novel therapeutics.
For Market Incumbents: Harden diagnostic-therapeutic lock-in by bundling PCR-based proviral load assays with monoclonal antibody protocols, creating prescribing inertia against antiviral platform competitors. Expand captive plasma collection capacity in the United States to immunize margin structures against feedstock volatility threatening immunoglobulin formulations. Prioritize PMDA Sakigake designation applications over standard orphan tracks to compress regulatory timelines.
For New Entrants and Emerging Players: Establish a beachhead in Brazilian Bahia state screening expansion by partnering with Federal University of Bahia medical centers piloting donor surveillance protocols. Target oral small-molecule prodrug development for outpatient disease management, displacing infusion center dependency that constrains patient access. Deploy direct-to-specialist educational programs in community neurology practices before hospital-based protocol capture solidifies.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap biotechs possessing intrathecal delivery technology licenses and active neuroimmunology pipelines but lacking orphan commercialization infrastructure. Long-term viability hinges on biomarker validation progress enabling surrogate endpoints that compress Phase III duration. Watch for HTLV-1 screening policy shifts in blood donor populations that would expand addressable patient pools beyond symptomatic diagnosis.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Bundling PCR-based proviral load assays with therapeutic protocols creates prescribing lock-in and service revenue streams. |
| Intrathecal Manufacturing Scale-Up | Dedicated fill-finish capacity at Japanese CDMOs addresses GMP cerebrospinal fluid handling constraints for monoclonal antibody delivery. |
| Oral Formulation Development | Small-molecule prodrugs targeting viral reverse transcriptase enable outpatient management and reduce hospital-based administration dependency. |
| Brazilian Screening Expansion | Partnerships with Federal University of Bahia medical centers replicate Japanese donor surveillance models in underdiagnosed endemic clusters. |
| Digital Gait Analysis Deployment | Smartphone accelerometry systems in Kagoshima and Okinawa tertiary hospitals generate continuous endpoint data for regulatory submissions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads at PMDA and FDA, formulary directors in Japanese prefectural health systems, and hospital procurement managers in Kyushu endemic zones; and secondary validation through FDA orphan drug designation filings, EMA submissions, ClinicalTrials.gov protocol records, and Japanese Ministry of Health formulary databases. Bottom-up patient population estimates triangulated against top-down orphan drug revenue models.
Forecast inputs considered treatment line positioning, administration route stratification, regional regulatory cluster differentiation, and patient population segmentation across symptomatic and pre-symptomatic cohorts. CAGRs were derived from epidemiological prevalence modeling cross-referenced with reimbursement expansion scenarios. Pipeline asset probability-weighting incorporated PMDA Sakigake designation success rates and biomarker validation timelines.
Stress conditions across plasma feedstock cost volatility, HTLV-1 screening policy adoption curves, and neuroimmunology specialist supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding PMDA review timeline compression and Brazilian ANVISA reimbursement harmonization. Material shifts in HTLV-1 seroprevalence detection rates or validated surrogate endpoint emergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Epileptic Seizures Treatment Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
SPINA Bifida and Hydrocephalus Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Specialty Generics Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
TIL Therapy Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Global Hypoparathyroidism Treatment Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
Hepatic Encephalopathy Treatment Market