
 Global Rotator Cuff Treatment Market | 2026-2036
Global Rotator Cuff Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rotator Cuff Treatment Market Foresight
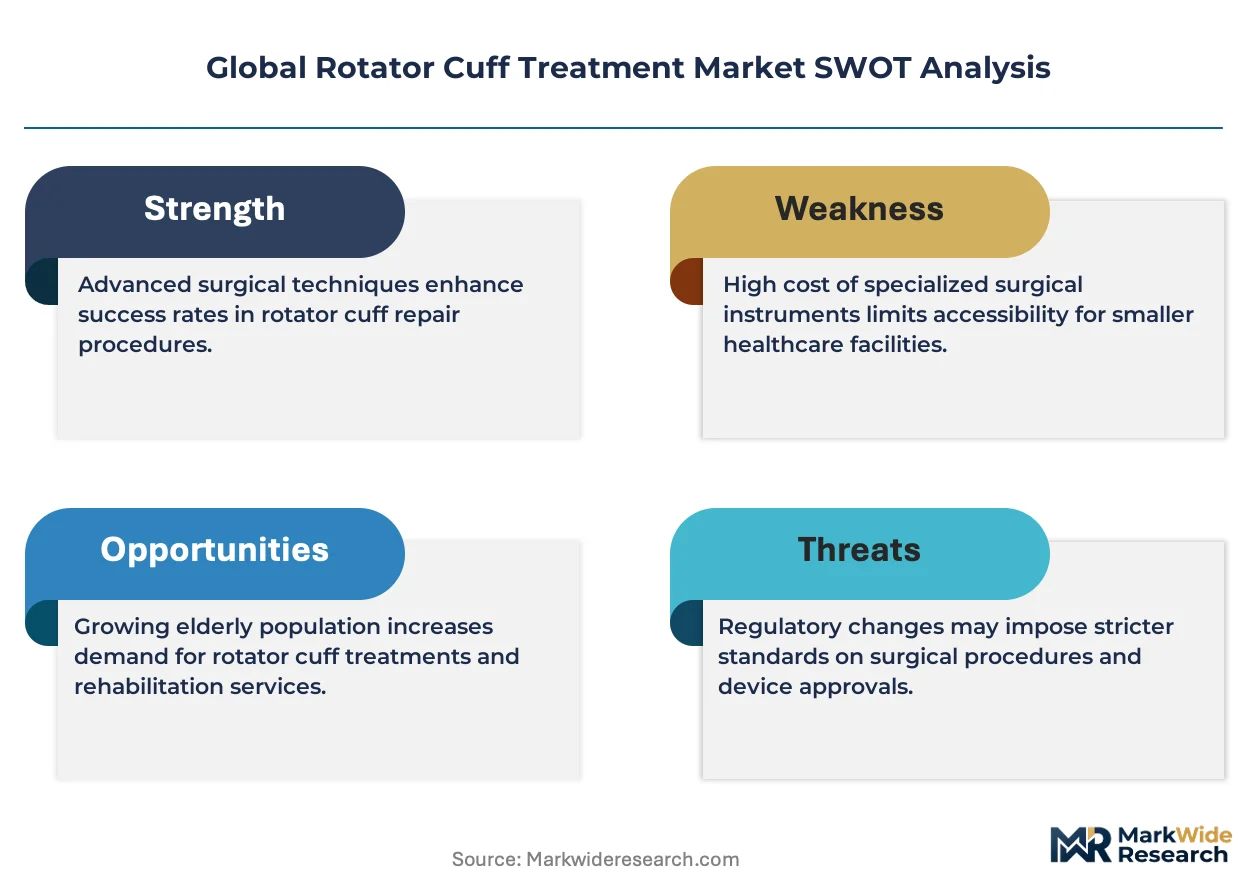
Orthopedic implant manufacturing in Ireland is decoupling from traditional European supply chains as firms seek dual-source resilience. Stryker leverages its broad suture anchor portfolio to sustain market presence across ambulatory and hospital settings. Arthrex differentiates through specialized arthroscopic instrumentation and surgeon education programs. Zimmer Biomet anchors its position with integrated soft-tissue repair platforms that span diagnosis through rehabilitation.
Rotator cuff treatment encompasses surgical and non-surgical interventions to repair torn tendons connecting shoulder muscles to bone, typically involving arthroscopic or open techniques with suture anchors, grafts, or biologics to restore mechanical function and reduce pain. Suture anchors remain the dominant product category due to their established reimbursement and surgeon familiarity, though biological patches and platelet-rich plasma are gaining traction in early-stage and partial-thickness repairs. Arthroscopic surgery applications command the largest volume share, while tendon transfer procedures represent a specialized, higher-margin segment for complex revision cases.
FDA 510(k) clearance pathways shape product development timelines for U.S. market entry, while the EU MDR demands more extensive clinical data for implantable devices, raising compliance costs for smaller manufacturers. ISO 13485 quality management certification has become a baseline requirement for supplier qualification by major hospital purchasing groups. Stakeholders must monitor evolving CMS reimbursement decisions for biologic adjuncts, as coverage determinations will directly influence adoption curves for higher-cost regenerative approaches.
Market Dynamics
Arthroscopic suture anchor systems are compressing procedural timelines while EU MDR compliance costs are restructuring supplier tiers, forcing manufacturers to absorb clinical evidence burdens or exit implantable categories entirely.
Growth Catalysts
- Aging demographics in the United States:The 65-plus population expansion sustains primary rotator cuff repair volumes as degenerative tears outpace sports-related injuries in absolute procedure counts.
- EU Medical Device Regulation (MDR) Article 10:Stricter clinical evidence requirements for Class III implantable devices are accelerating consolidation toward well-capitalized manufacturers capable of funding post-market surveillance.
- Platelet-rich plasma protocols:Orthobiologic adjuncts are penetrating ambulatory surgery centers as physician-owned facilities seek differentiation through regenerative service lines.
Market Restraints
- Polyetheretherketone (PEEK) raw material concentration:Suture anchor substrate supply concentrates among three European compounders, exposing manufacturers to input cost volatility and allocation risk.
- FDA 510(k) predicate device limitations:Novel anchor geometries face heightened scrutiny when substantial equivalence claims rely on decade-old predicates, elongating clearance timelines.
- Non-operative management protocols:Structured physical therapy and corticosteroid injection pathways capture partial-thickness tear patients before surgical candidacy, compressing addressable incidence.
Strategic Opportunities
- Japan's aging surgical workforce:Surgeon training gaps in arthroscopic techniques create demand for simulation-based education platforms and simplified instrumentation.
- Biological patch augmentation:Xenograft and allograft scaffolds for massive irreparable tears represent unmet need in revision settings where primary repair fails.
- India's PLI scheme for medical devices:Production-linked incentives for domestic manufacturing attract anchor assembly operations seeking cost-competitive export bases.
Industry Challenges
- ISO 13485:2016 transition audits:Certificate renewal backlogs at notified bodies delay supplier qualification for hospital purchasing group tenders.
- Arthroscopic technician specialization:Operating room staff proficient in fluid management pump calibration and anchor delivery system loading command wage premiums that inflate case costs.
- Legacy EMR integration:Implant tracking systems for Unique Device Identification compliance require middleware development to interface with hospital inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rotator Cuff Treatment Market |
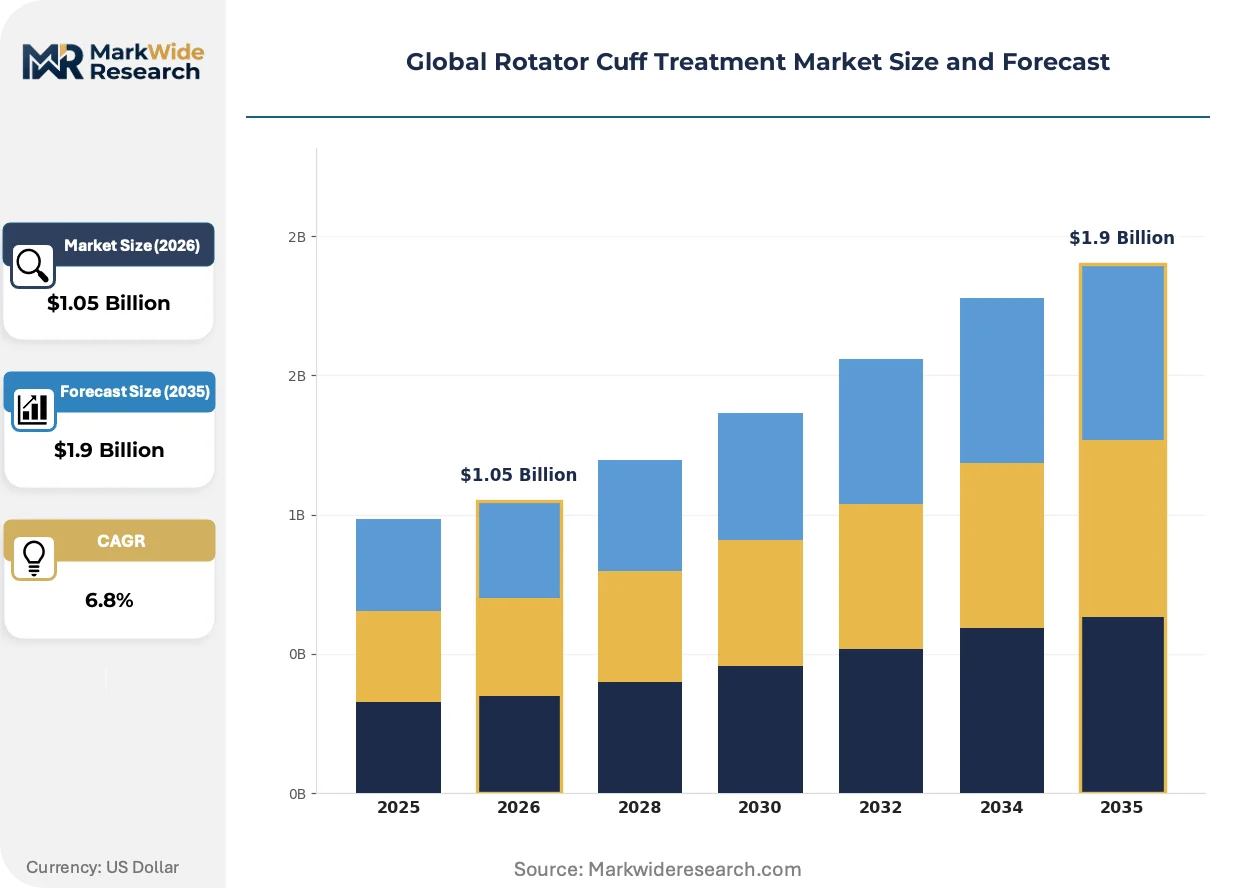
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.9 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Suture Anchors, Biological Patches, Synthetic Grafts, Growth Factors, Platelet-Rich Plasma, Scaffolds Application: Partial Tear Repair, Full Thickness Repair, Tendon Transfer, Debridement, Arthroscopic Surgery, Open Surgery Procedure Setting: Orthopedic Clinics, Ambulatory Surgery Centers, Specialty Hospitals, Trauma Centers, Rehabilitation Facilities, Sports Medicine Centers End User: Orthopedic Surgeons, Sports Physicians, Physiotherapists, Rehabilitation Specialists, Athletic Trainers, Pain Management Experts |
| Companies Covered | Arthrex, Stryker, Zimmer Biomet, Johnson & Johnson, Smith & Nephew, CONMED Corporation, Integra LifeSciences, Medtronic, FH Orthopedics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rotator Cuff Treatment Market Shifts & Advancements
Regenerative biologics and knotless anchor designs are compressing the traditional suture-tensioning workflow while ambulatory migration reconfigures site-of-service economics.
Knotless suture anchor technology is rewriting procedural efficiency standards in outpatient shoulder surgery. Sports medicine fellows graduating from specialized arthroscopy programs adopt all-suture anchors at accelerating rates in United States ambulatory surgery centers. The elimination of arthroscopic knot-tying steps is compressing operative time and reducing implant bulk while enabling earlier rehabilitation protocols.
EU MDR Annex XIV post-market clinical follow-up requirements are restructuring evidence generation obligations for implantable orthopedic manufacturers. Smaller anchor producers face capital constraints when funding PMCF studies for legacy device families. The regulatory burden is concentrating CE-marked product portfolios among firms with dedicated clinical affairs infrastructure.
Site-of-service migration toward physician-owned ambulatory surgery centers is fragmenting traditional hospital purchasing leverage. United States orthopedic groups are consolidating ancillaries to capture facility fees previously retained by acute-care institutions. This channel shift rewards manufacturers with direct-to-practice distribution capabilities and compressed delivery cycles.
Global Rotator Cuff Treatment Market Segmentation
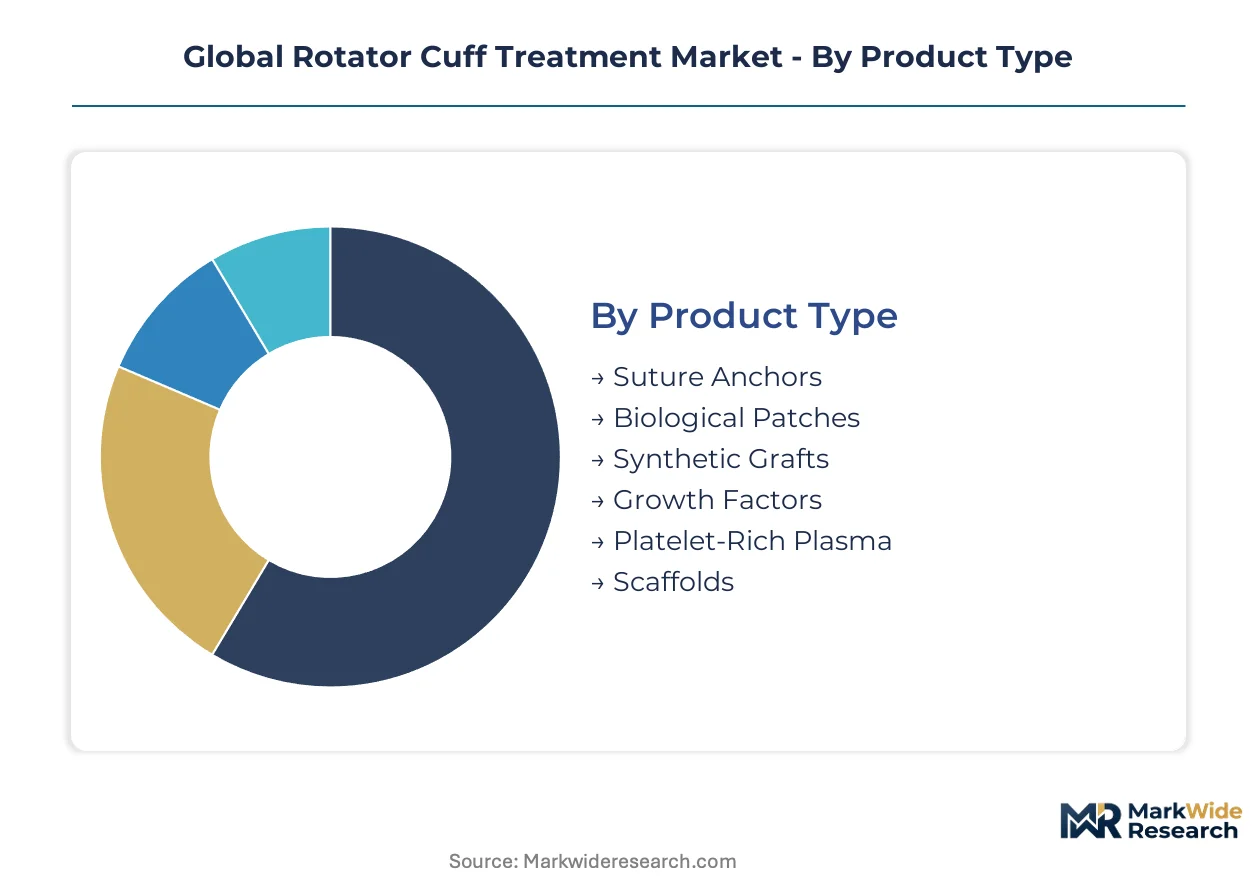
Rotator cuff treatment markets fragment across four dimensions that shape procurement patterns and clinical adoption curves. Product type determines reimbursement tier and supply chain complexity, while application and setting dictate instrumentation requirements and sales channel strategy.
Product Type:
Reimbursement pathways and surgeon training depth anchor purchasing decisions across implant categories.
- Suture Anchors:Titanium, PEEK, and all-suture constructs provide tendon-to-bone fixation through arthroscopic or open delivery systems. United States ambulatory surgery centers drive volume concentration as physician-owned facilities standardize on knotless designs for efficiency gains.
- Biological Patches:Xenograft and allograft scaffolds reinforce repairs in massive or revision tears where native tissue quality is compromised. Demand concentrates in academic medical centers performing complex reconstructions, constrained by CMS coverage variability for biologic adjuncts.
- Synthetic Grafts:Polymer-based reinforcements offer off-the-shelf availability without tissue bank dependency.
- Growth Factors:Recombinant proteins and bone morphogenetic proteins accelerate healing in select patient populations.
- Platelet-Rich Plasma:Autologous concentrates require centrifugation infrastructure but bypass implantable device regulatory pathways.
- Scaffolds:Resorbable matrices provide temporary mechanical support during tendon remodeling.
Volume sits with suture anchors; growth tilts toward biological patches.
Application:
Procedure complexity and failure risk stratify addressable patient populations across the tear spectrum.
- Partial Tear Repair:Debridement with or without augmentation addresses articular- or bursal-sided defects before progression to full-thickness failure. Sports medicine centers in the United States capture volume concentration from aging recreational athletes seeking activity preservation.
- Full Thickness Repair:Complete tendon retraction requiring mobilization and footprint restoration represents the procedural standard. Academic hospitals anchor demand for double-row fixation techniques, though cost pressures favor single-row alternatives in community settings.
- Tendon Transfer:Latissimus dorsi or pectoralis major transfer salvages irreparable massive tears.
- Debridement:Subacromial smoothing and partial resection address impingement without formal repair.
- Arthroscopic Surgery:Minimally invasive visualization dominates contemporary practice patterns.
- Open Surgery:Extensile approaches persist for revision cases and specific tear configurations.
Full thickness repair commands the highest absolute procedure count; arthroscopic techniques are climbing the fastest.
Procedure Setting:
Capital equipment requirements and anesthesia staffing determine site feasibility for shoulder arthroscopy.
- Orthopedic Clinics:Office-based ultrasound-guided injections and non-operative management capture early-stage patients. United States metropolitan markets concentrate demand as integrated practice units seek to retain patients within system walls.
- Ambulatory Surgery Centers:Freestanding facilities with dedicated orthopedic focus achieve cost and throughput advantages over hospital outpatient departments. United States certificate-of-need states constrain supply growth, creating geographic pockets of pricing power.
- Specialty Hospitals:Dedicated orthopedic institutions offer scale economies in high-volume markets.
- Trauma Centers:Acute injury pathways require 24-hour operative availability.
- Rehabilitation Facilities:Postoperative physical therapy protocols influence long-term functional outcomes.
- Sports Medicine Centers:Athlete-specific care coordination spans diagnosis through return-to-play clearance.
Ambulatory surgery centers are expanding capacity fastest; orthopedic clinics retain the largest patient touchpoint volume.
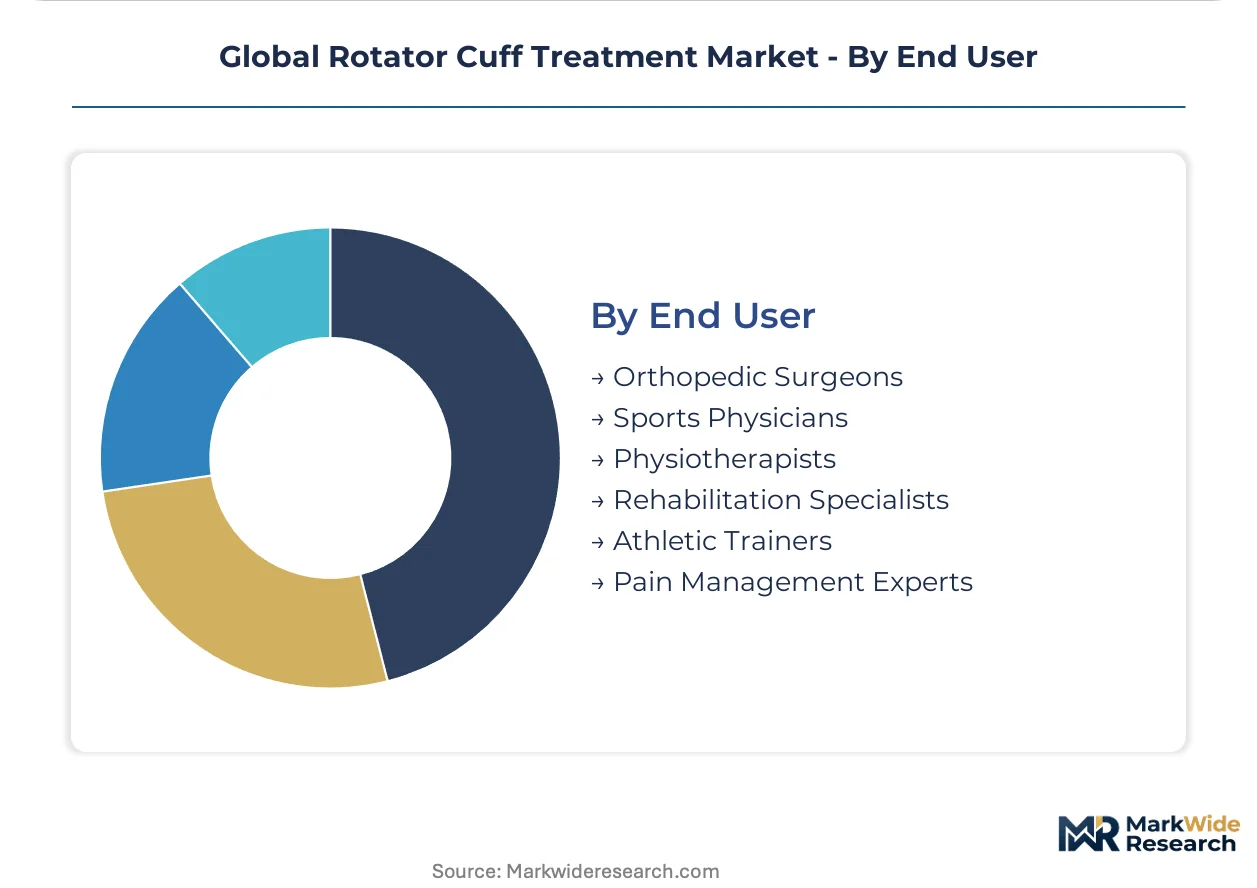
End User:
Credentialing scope and referral relationships shape product specification authority across provider types.
- Orthopedic Surgeons:Fellowship-trained shoulder specialists command implant selection authority in operative cases. United States private practice consolidation is concentrating purchasing leverage within multi-specialty groups.
- Sports Physicians:Primary care and emergency medicine physicians with sports focus manage initial injury triage. United States collegiate and professional team affiliations create branded referral pathways that influence patient routing.
- Physiotherapists:Direct access laws in select states enable independent non-operative management.
- Rehabilitation Specialists:Postoperative protocol design affects implant performance perception.
- Athletic Trainers:Sideline assessment determines immediate care and referral urgency.
- Pain Management Experts:Interventional procedures bridge non-operative and surgical pathways.
Orthopedic surgeons control operative implant decisions; sports physicians are gaining the fastest share of initial patient capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyetheretherketone compounding capacity in Germany anchors European anchor substrate supply, while titanium forging clusters in the United States and Japan shape implant manufacturing geography. Regional procurement patterns diverge across reimbursement systems, regulatory stringency, and ambulatory surgery center penetration.
United States
The 65-plus population expansion and sports medicine center proliferation sustain arthroscopic procedure volumes. FDA 510(k) clearance pathways compress product development timelines for domestic market entry. Warsaw, Indiana anchors orthopedic implant manufacturing concentration, with Stryker and Zimmer Biomet maintaining integrated production footprints.
Germany
EU MDR compliance infrastructure and notified body density attract CE-marked product development investment. The country's national pharmaceutical regulator enforces Annex XIV post-market clinical follow-up for Class III implantables. Tuttlingen clusters arthroscopic instrumentation manufacturing, with specialized suppliers serving Stryker and Arthrex assembly operations.
Japan
Aging surgical workforce demographics and arthroscopic training gaps create demand for simplified instrumentation. PMDA consultation pathways shape product registration timelines for foreign manufacturers. Osaka-Kobe industrial corridor concentrates precision metalworking capacity serving orthopedic device subcontractors.
India
PLI scheme production-linked incentives for medical devices attract anchor assembly operations seeking cost-competitive export bases. CDSCO medical device rules govern import registration and quality system requirements. Gujarat and Karnataka industrial corridors host emerging contract manufacturing for suture anchor components.
Switzerland
Swissmedic maintains stringent clinical evidence requirements that filter market access toward well-capitalized manufacturers. Precision machining heritage supports high-value orthopedic component production. Solothurn-Jura region clusters watchmaking-adjacent micro-mechanical engineering serving implantable device supply chains.
Global Rotator Cuff Treatment Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capability and surgeon education infrastructure. The vendor base stratifies into three tiers: diversified orthopedic conglomerates with full soft-tissue repair portfolios, arthroscopy-focused specialists with concentrated instrumentation depth, and emerging contract manufacturers serving private-label distribution. Dominant competitive moves include M&A for biologic patch technology access and capacity expansion into India's PLI-subsidized manufacturing zones.
Within the diversified conglomerate tier, Stryker, Zimmer Biomet, and Johnson & Johnson occupy positions defined by integrated platform breadth spanning diagnosis through rehabilitation. Arthrex exemplifies the arthroscopy-specialist archetype with concentrated instrumentation and education program investment. Smith & Nephew and CONMED Corporation sit within the mid-tier segment, representing European and North American regional champions respectively. Medtronic and Integra LifeSciences anchor positions in adjacent soft-tissue repair categories with partial rotator cuff overlap.
| Leading Market Players |
|---|
| Arthrex |
| Stryker |
| Zimmer Biomet |
| Johnson & Johnson |
| Smith & Nephew |
| CONMED Corporation |
| Integra LifeSciences |
| Medtronic |
| FH Orthopedics |
| Others |
Supply & Pricing Matrix
Backward integration into PEEK compounding anchors both supply security and pricing power for anchor manufacturers facing EU MDR compliance burdens. Captive control over titanium forging operations in Warsaw, Indiana and Tuttlingen, Germany insulates tier-one suppliers from raw material allocation shocks while supporting premium positioning against contract manufacturers.
Pricing Analysis
Warranty and surgeon education bundling separates premium anchor portfolios from unbundled commodity alternatives. Three-tier pricing structure across premium knotless systems, standard screw-in designs, and economy all-suture anchors reflects ISO 13485 certification depth and clinical training investment. Pricing pressure stems from hospital purchasing group consolidation demanding volume discounts on standard constructs. Ambulatory surgery centers exhibit highest price sensitivity due to thin facility fee margins, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital purchasing groups require qualification of alternative PEEK compounders in Germany and titanium forgers in Japan. Raw material dependencies center on polyetheretherketone resin, titanium bar stock, and high-strength suture fiber. Single-source vulnerability concentrates in European PEEK substrate supply among three compounders. Distribution runs through orthopedic distributor networks with direct-to-practice channels gaining share in ambulatory settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Knotless anchor technology is displacing traditional knot-tying constructs across ambulatory surgery centers, compressing procedural timelines and retraining requirements.
For Market Incumbents: To counter all-suture anchor commoditization, deepen backward integration into PEEK compounding and titanium forging to secure substrate allocation priority. Expand surgeon education infrastructure in Japan to address arthroscopic training gaps and anchor premium positioning through clinical outcomes data. For New Entrants and Emerging Players: Direct-to-practice digital channels bypass entrenched distributor relationships and capture ambulatory surgery center procurement decisions. Target biological patch augmentation for massive irreparable tears in academic medical centers, where CMS coverage variability has suppressed incumbent investment and clinical evidence requirements filter out undercapitalized competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified orthopedic conglomerates seeking biologic patch technology and EU MDR-compliant clinical affairs infrastructure. Long-term viability favors manufacturers with captive raw material positions and dedicated post-market surveillance capabilities. Watch FDA 510(k) predicate device policy evolution as inflection indicator for novel anchor geometry clearance timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Investment | Post-market surveillance infrastructure secures CE marking for Class III implantable anchors under Annex XIV requirements. |
| Surgeon Education Platform Expansion | Simulation-based training programs in Japan address arthroscopic technique gaps and accelerate knotless adoption curves. |
| Biological Patch Portfolio Acquisition | Xenograft and allograft scaffold access captures revision case volume in academic medical centers. |
| India PLI Manufacturing Footprint | Production-linked incentive zones in Gujarat and Karnataka enable cost-competitive export base for anchor assembly operations. |
| Direct-to-Practice Distribution Buildout | Bypassing traditional orthopedic distributors captures ambulatory surgery center procurement decisions and facility fee economics. |
Research Methodology
FDA 510(k) filings, EU MDR notified body guidance documents, and hospital procurement databases formed the secondary backbone of this analysis. Primary interviews with orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers validated segmentation assumptions and pricing dynamics. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Historical trendline analysis of arthroscopic procedure migration from hospital outpatient departments to ambulatory surgery centers informed site-of-service projections. Segmentation modeling incorporated product type, application complexity, procedure setting, and end-user credentialing scope. CAGR derivation rested on procedure volume growth, reimbursement trajectory, and technology substitution rates for knotless versus traditional anchor designs.
Inputs from CMS coverage determinations and EU MDR implementation timelines were available through the study window; gaps in real-time ambulatory surgery center capacity expansion data introduce uncertainty bands around site-of-service projections. Deviation in FDA predicate device policy or EU MDR notified body capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Mexico Hair Transplant Market
Medical Treatment
Facial Spasm Treatment Market
Medical Treatment
Global Medication Management Market
Medical Treatment
Birch Allergy Treatment Market
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Necrotizing Skin Infections Treatment Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Precocious Puberty Treatment Market
Medical Treatment
Asthma Treatment Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Histiocytosis Treatment Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Allergic Rhinitis Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market