
 Hyponatremia Treatment Market | 2026-2036
Hyponatremia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hyponatremia Treatment Market Foresight
Precision electrolyte monitoring platforms is tilting hyponatremia management toward algorithm-driven dosing and real-time sodium correction protocols. Otsuka Pharmaceutical Co., Ltd. dominates oral vasopressin receptor antagonist development through sustained investment in tolvaptan formulations. Fresenius Kabi AG anchors hospital infusion channel control with specialized parenteral sodium chloride solutions. Baxter International Inc. leverages its critical care portfolio to compete in intensive care unit electrolyte management workflows.
Hyponatremia treatment encompasses pharmacological and fluid-based interventions designed to correct serum sodium imbalances, with tolvaptan functioning as a selective vasopressin V2-receptor antagonist that promotes aquaresis without sodium loss, while hypertonic saline solutions deliver controlled osmotic correction in acute cerebral edema scenarios. The indication dimension shows acute hyponatremia commanding the largest addressable patient base due to emergency department presentation frequency, though SIADH-specific protocols represent the fastest-growing subsegment as diagnostic criteria standardize across health systems. Delivery mode preferences reveal infusion-based therapy retaining dominance in critical care settings where precise sodium correction rates prevent osmotic demyelination syndrome, while oral tablet formulations expand into outpatient chronic management where patient stability permits.
FDA REMS requirements for tolvaptan and EMA pharmacovigilance frameworks for vasopressin antagonists collectively elevate safety documentation burdens and restrict prescriber pools to certified clinicians. The EU MDR transition imposes additional clinical evidence requirements on electrolyte monitoring devices used in sodium correction protocols. Stakeholders must track evolving hepatotoxicity surveillance mandates and their impact on formulary positioning across hospital pharmacy committees.
Market Dynamics
FDA REMS requirements for tolvaptan and EMA pharmacovigilance frameworks are restructuring prescriber certification requirements and hospital formulary access protocols across major health systems.
Growth Catalysts
- SIADH Diagnostic Standardization:Health systems across Germany, Japan, and the United States are implementing uniform diagnostic criteria that accelerate protocol adoption and expand addressable patient populations for targeted therapies.
- Hypertonic Saline Protocol Expansion:Emergency medicine departments are formalizing controlled osmotic correction procedures to prevent osmotic demyelination syndrome in acute cerebral edema presentations.
- Critical Care Electrolyte Monitoring:Algorithm-driven dosing platforms with real-time sodium correction capabilities are penetrating intensive care unit workflows in tertiary centers.
Market Restraints
- Hepatotoxicity Surveillance Burden:FDA REMS mandates for tolvaptan require certified prescriber pools and ongoing liver function monitoring that restrict prescriber flexibility and elevate documentation costs.
- EU MDR Clinical Evidence Requirements:Electrolyte monitoring devices used in sodium correction protocols face additional clinical validation burdens that extend regulatory timelines and increase development expenditure.
- Infusion Channel Concentration:Hospital pharmacy committees control specialized parenteral sodium chloride procurement through limited vendor contracts that constrain product switching.
Strategic Opportunities
- Outpatient Chronic Management:Oral tablet formulations for stable patients present expansion potential beyond acute hospital settings where infusion therapy currently dominates.
- Precision Monitoring Convergence:Integration of point-of-care sodium sensors with electronic health record systems is virtualizing dosing decisions and reducing correction variability.
- Pharmacovigilance Framework Alignment:Standardized EMA safety documentation requirements create pathways for cross-border protocol harmonization and streamlined multi-market registration.
Industry Challenges
- Specialized Nephrology-Intensivist Coordination:Acute hyponatremia management requires synchronized expertise across emergency medicine, critical care, and nephrology functions that many health systems lack.
- Legacy Infusion Infrastructure Integration:Algorithm-driven dosing platforms must interface with existing pump systems and electronic health records, creating implementation friction and training requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyponatremia Treatment Market |
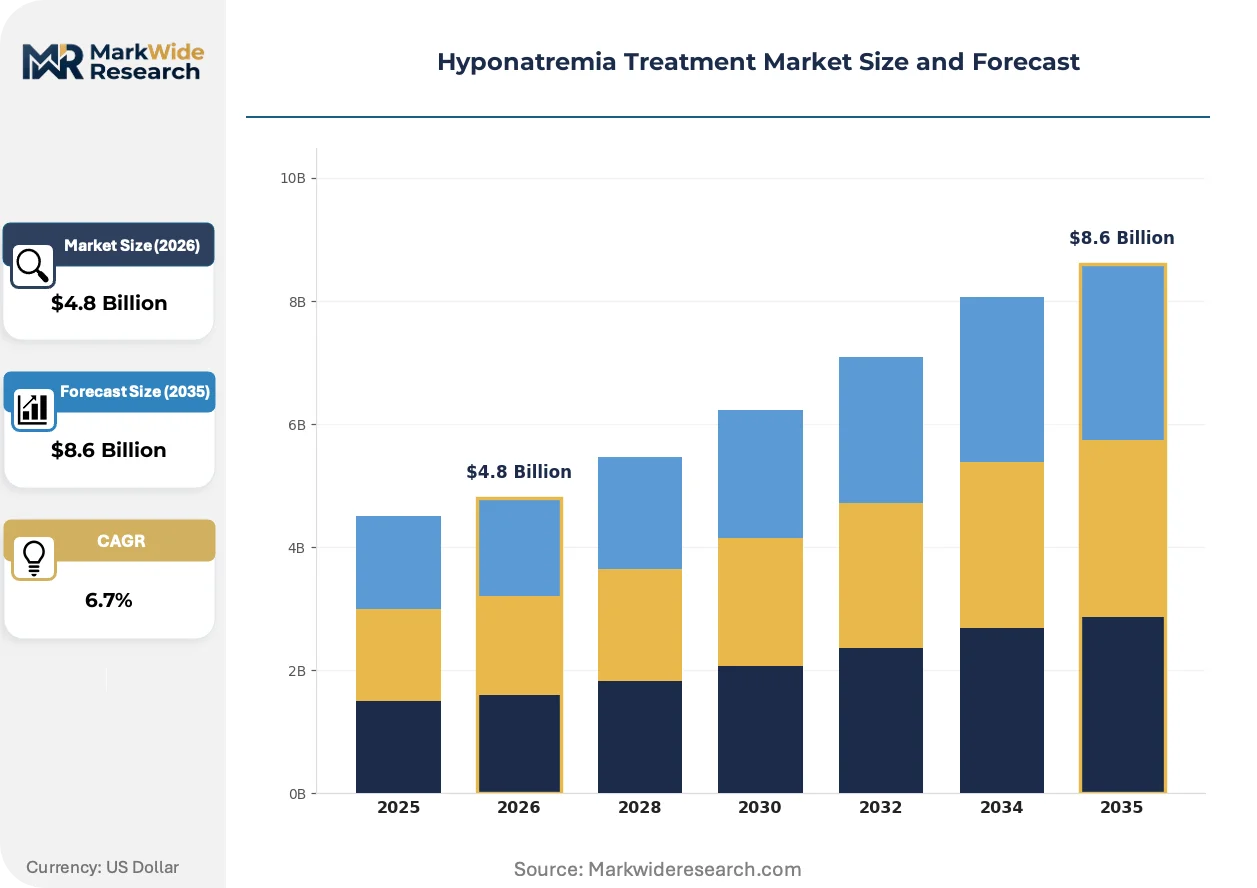
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desmopressin, Sodium Chloride,Lithium Carbonate, Tolvaptan Delivery Mode: Injection, Oral Tablet, Solution, Infusion End User: Hospitals, Clinics, Home Healthcare, Rehabilitation Centers Indication: Acute Hyponatremia, Chronic Hyponatremia, Pediatric Hyponatremia, Syndrome of Inappropriate Antidiuretic Hormone (SIADH) |
| Companies Covered | Ferring Pharmaceuticals, Fresenius Kabi AG, Otsuka Pharmaceutical Co., Ltd., Sun Pharmaceutical Industries Ltd., Astellas Pharma US, Inc., Pfizer Inc., Baxter International Inc., Alkem Laboratories Ltd., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyponatremia Treatment Market Shifts & Advancements
Electrolyte management is transitioning from reactive correction to predictive, protocol-driven intervention models that embed decision support into clinical workflows.
Continuous sodium monitoring biosensors with closed-loop alert systems are virtualizing the traditional laboratory turnaround model. Intensive care units in tertiary centers across the United States and Germany are piloting these platforms to compress time-to-correction intervals. Real-time data streams are enabling dynamic infusion rate adjustments that manual protocols cannot replicate.
EMA pharmacovigilance frameworks for vasopressin antagonists are elevating post-market surveillance requirements beyond FDA REMS baselines. Manufacturers must now maintain active liver function registries and submit periodic safety updates that extend compliance costs across product lifecycles. Hospital pharmacy committees in France and Italy are incorporating these documentation burdens into formulary evaluation criteria.
Centralized pharmacy oversight of hypertonic saline administration is displacing individual physician discretion in emergency departments. Protocol-driven authorization systems with predefined correction rate ceilings are standardizing care patterns across hospital networks. This shift is most visible in United States academic medical centers where quality metrics increasingly tie reimbursement to adherence scores.
Hyponatremia Treatment Market Segmentation
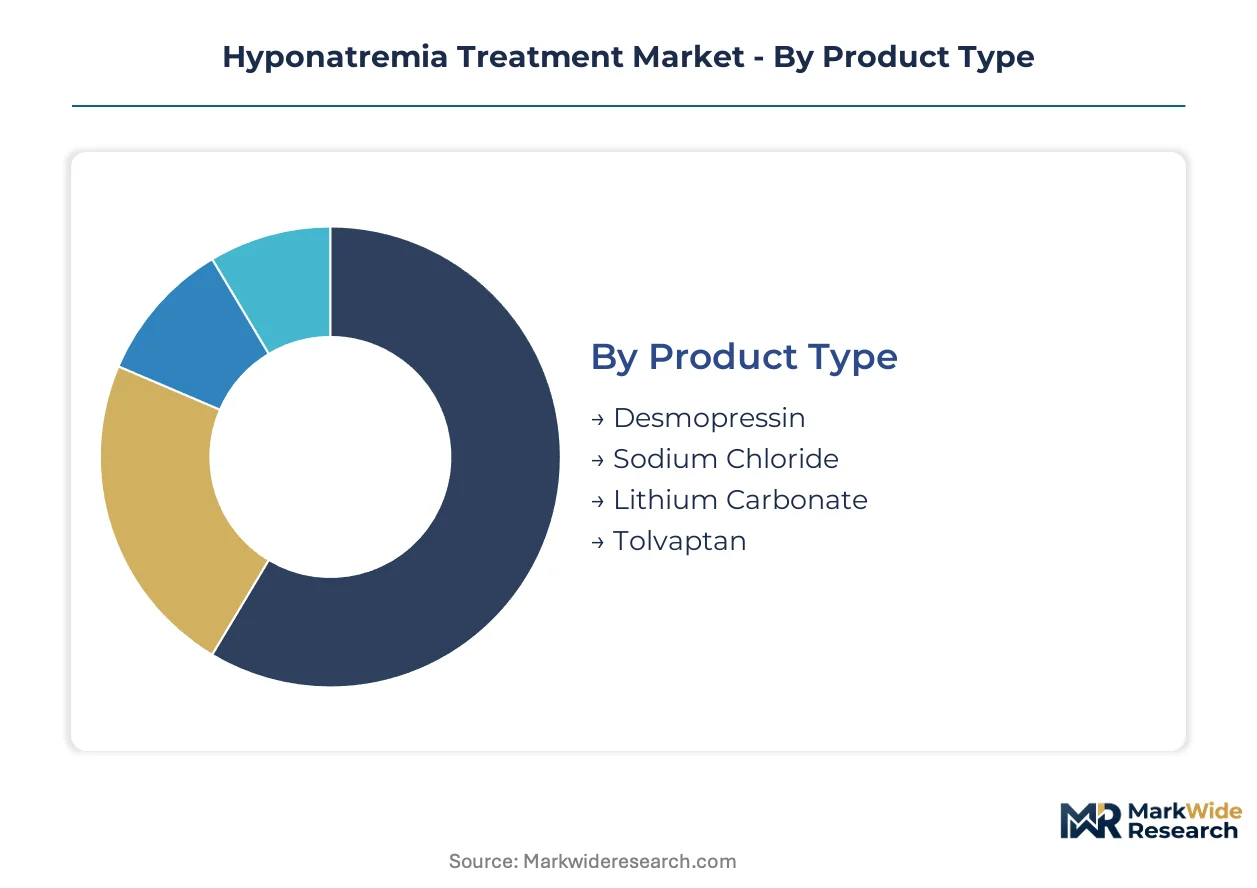
Hyponatremia treatment modalities span pharmacological antagonists, electrolyte replacement fluids, and receptor-targeted therapies that demand precise matching to patient acuity, care setting, and underlying etiology. Segmentation reveals how acute hospital protocols differ fundamentally from chronic outpatient management pathways.
Product Type:
Pharmacological options range from hormone analogs to selective receptor blockers, each occupying distinct positions in the therapeutic algorithm based on mechanism and safety profile.
- Tolvaptan:Selective vasopressin V2-receptor antagonist promoting aquaresis without sodium excretion. Tertiary care centers in Germany and the United States favor this agent for SIADH management, though FDA REMS hepatotoxicity surveillance restricts prescriber pools and elevates documentation burdens.
- Sodium Chloride:Hypertonic and isotonic formulations deliver controlled osmotic correction in emergency settings. Hospital pharmacy committees in Japan and the United States concentrate procurement through limited vendor contracts that constrain switching flexibility.
- Desmopressin:Synthetic vasopressin analog used in diabetes insipidus-related hyponatremia presentations.
- Lithium Carbonate:Nonspecific vasopressin antagonist employed in refractory SIADH cases where first-line options fail.
The dominant share belongs to Sodium Chloride, while Tolvaptan is closing the gap fastest.
Delivery Mode:
Route selection hinges on correction urgency, patient consciousness, and care setting infrastructure capabilities.
- Infusion:Intravenous hypertonic saline enables precise sodium correction rates in critical care workflows. Intensive care units across United States academic medical centers deploy algorithm-driven pump systems to prevent osmotic demyelination syndrome.
- Oral Tablet:Tolvaptan tablets facilitate outpatient chronic management where patient stability permits. Japanese health systems are expanding tablet dispensing beyond hospital walls to reduce readmission frequency.
- Injection:Parenteral bolus administration for emergency department presentations requiring rapid intervention.
- Solution:Pre-mixed electrolyte preparations for standardized ward-level administration.
Infusion retains the dominant position in revenue terms, though Oral Tablet formats are expanding most quickly into ambulatory settings.
End User:
Care setting determines therapy intensity, monitoring sophistication, and reimbursement pathways.
- Hospitals:Tertiary centers command the highest patient acuity and protocol standardization requirements. German university hospitals anchor SIADH diagnostic standardization efforts that shape regional treatment patterns.
- Home Healthcare:Remote monitoring platforms enable stable chronic patients to transition from inpatient supervision. United States Medicare reimbursement shifts are accelerating home infusion service expansion.
- Clinics:Outpatient facilities manage stable chronic cases with periodic laboratory monitoring.
- Rehabilitation Centers:Post-acute settings address hyponatremia in recovering stroke and trauma populations.
Hospitals capture the dominant share, while Home Healthcare is gaining share fastest as risk-bearing contracts push care outside institutional walls.
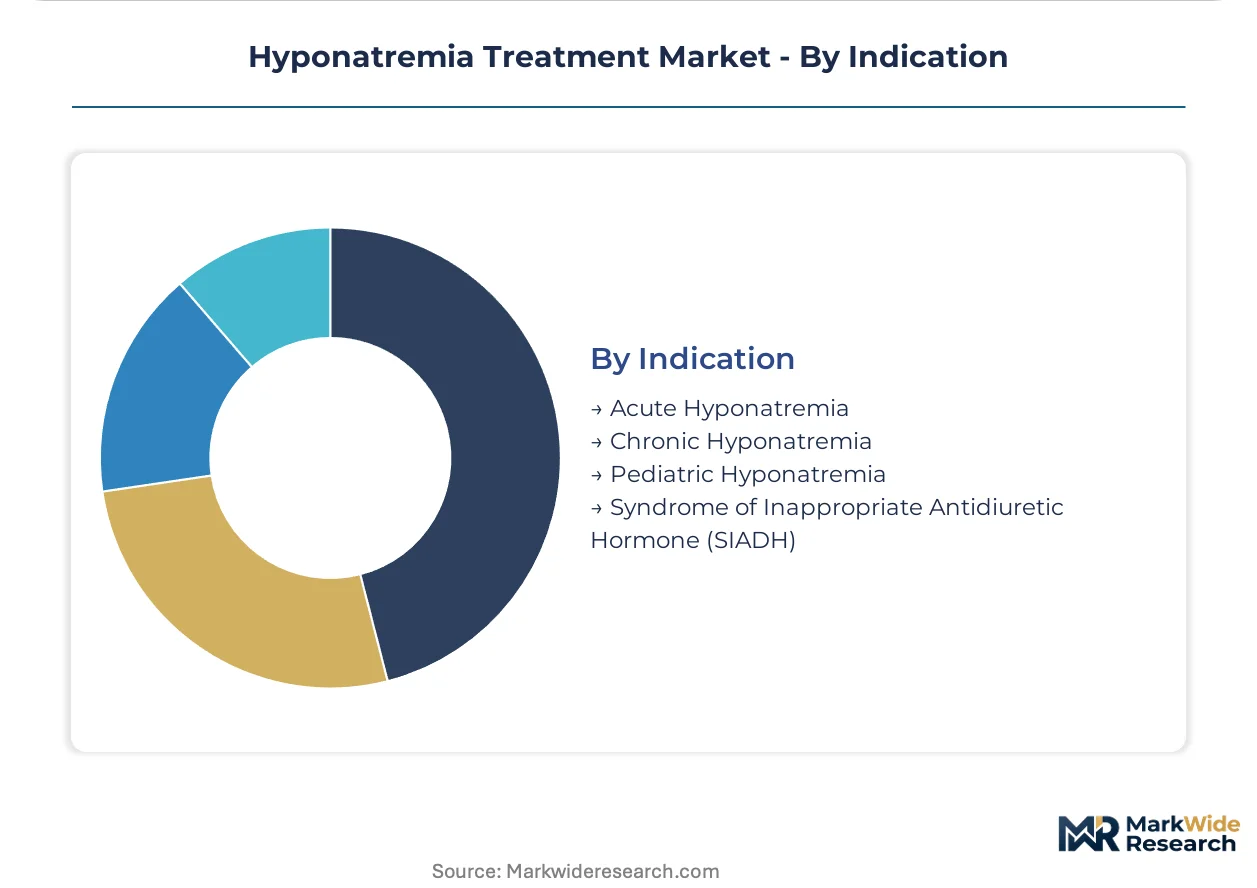
Indication:
Etiology-specific protocols are replacing one-size-fits-all correction approaches as diagnostic criteria sharpen.
- Syndrome of Inappropriate Antidiuretic Hormone (SIADH):Tolvaptan-responsive volume-expanded hyponatremia with standardized diagnostic algorithms. Health systems across the United States and Germany are implementing uniform criteria that accelerate targeted therapy adoption.
- Acute Hyponatremia:Emergency presentations with seizure or cerebral edema requiring immediate osmotic correction. Japanese emergency medicine departments are formalizing controlled correction rate ceilings to prevent neurological complications.
- Chronic Hyponatremia:Gradual-onset cases permitting slower correction schedules in outpatient frameworks.
- Pediatric Hyponatremia:Weight-based dosing protocols with distinct safety margins for developing patients.
Acute Hyponatremia commands the largest patient volume currently, while SIADH shows the steepest expansion trajectory as diagnostic precision improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized parenteral sodium chloride formulations to tertiary care networks across Western Europe, while Japan ships precision electrolyte monitoring devices to hospital systems in East Asia and North America.
United States
FDA REMS mandates for tolvaptan and SIADH-related hospitalizations in academic medical centers drive protocol standardization. The FDA's hepatotoxicity surveillance requirements restrict prescriber pools to certified clinicians. Boston and New York Metro anchor algorithm-driven dosing platform pilots in intensive care workflows.
Germany
EMA pharmacovigilance frameworks and uniform SIADH diagnostic criteria accelerate targeted therapy adoption across university hospitals. The EU MDR transition imposes additional clinical evidence requirements on electrolyte monitoring devices. Bavarian university hospitals lead diagnostic standardization efforts that shape regional treatment patterns.
Japan
PMDA oversight of vasopressin antagonists and expanding tablet dispensing beyond hospital walls reduce readmission frequency for chronic patients. METI promotes remote monitoring platform integration into outpatient frameworks. Tokyo and Osaka medical centers pilot continuous sodium monitoring biosensors with closed-loop alert systems.
United Kingdom
NHS England's quality metrics tie reimbursement to adherence scores for controlled osmotic correction procedures in emergency departments. MHRA post-market surveillance requirements align with EMA safety documentation standards. London and Southeast England concentrate tertiary center capacity for acute electrolyte management.
India
CDSCO regulatory pathways for generic vasopressin antagonists and expanding hospital pharmacy infrastructure drive market access in metropolitan areas. The government's PLI scheme for pharmaceutical manufacturing attracts domestic production investment. Maharashtra and Gujarat host expanding infusion therapy manufacturing clusters serving South Asian markets.
Hyponatremia Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across infusion therapy and oral formulation segments. Hospital pharmacy committees concentrate procurement through limited vendor contracts, creating defensive moats for established suppliers. Three archetypes dominate: multinational critical care portfolio holders, specialized parenteral solution manufacturers, and regional generic pharmaceutical suppliers. Competitive moves center on formulary positioning through safety documentation bundling and backward integration into active pharmaceutical ingredient production.
Within the critical care portfolio tier, Baxter International Inc. and Fresenius Kabi AG exemplify channel-controlling players with hospital infusion infrastructure leverage. Otsuka Pharmaceutical Co., Ltd. occupies a distinct position as a selective vasopressin receptor antagonist specialist with prescriber certification program dependencies. These three anchors illustrate how regulatory compliance burdens and procurement concentration shape competitive differentiation across acute and chronic management settings.
| Leading Market Players |
|---|
| Ferring Pharmaceuticals |
| Fresenius Kabi AG |
| Otsuka Pharmaceutical Co., Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Astellas Pharma US, Inc. |
| Pfizer Inc. |
| Baxter International Inc. |
| Alkem Laboratories Ltd. |
| Sanofi |
| Others |
Supply & Pricing Matrix
Undercapacity in sterile parenteral solution manufacturing across Western Europe is compressing supplier flexibility and elevating contract pricing power for hospital-grade sodium chloride formulations. German and United States health systems now face extended lead times that force premium positioning for guaranteed supply slots.
Pricing Analysis
Next-generation algorithm-driven dosing platforms command substantial premiums over conventional infusion pump systems, while legacy hypertonic saline solutions face commoditization pressure from hospital pharmacy consolidation. Three-tier pricing structure across FDA REMS-certified tolvaptan, standard hypertonic saline, and economy-grade isotonic solutions reflects certification burden and monitoring cost differentials. Price erosion runs through the isotonic saline tier as Indian and Chinese manufacturers expand sterile filling capacity. Emergency departments exhibit highest price sensitivity due to budget caps, while intensive care units prioritize correction precision over unit cost.
Supply Chain Analysis
Fresenius Kabi AG and Baxter International Inc. control the majority of contract manufacturing capacity for specialized parenteral sodium chloride solutions across Germany, the United States, and Japan. Active pharmaceutical ingredient production for vasopressin antagonists draws from Swiss and Italian chemical synthesis clusters, with tolvaptan intermediates sourced from captive Japanese facilities. Single-source vulnerability concentrates in sterile fill-finish operations where EU MDR compliance has thinned qualified supplier pools. Distribution runs through hospital pharmacy committee contracts with limited vendor panels that restrict product substitution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous sodium monitoring biosensors and closed-loop correction algorithms are disrupting acute electrolyte management, with FDA breakthrough device designations accelerating clinical validation timelines.
For Market Incumbents: Entrench formulary positioning through bundled safety documentation services that address FDA REMS hepatotoxicity surveillance burdens for hospital pharmacy committees. Deepen backward integration into active pharmaceutical ingredient production to offset margin pressure from Indian generic vasopressin antagonist entrants. Prioritize certification investment in EU MDR-compliant electrolyte monitoring devices to defend against emerging point-of-care sensor competitors. For New Entrants and Emerging Players: Establish a beachhead in home healthcare infusion services where United States Medicare reimbursement shifts are decoupling chronic hyponatremia management from hospital walls. Target the outpatient oral tablet segment in Japanese and German markets where diagnostic standardization is expanding addressable patient populations beyond acute settings. Deploy remote patient monitoring platforms with pharmacy partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-integrated electrolyte monitoring device manufacturers with hospital information system connectivity. Long-term viability favors companies with dual exposure to acute hospital protocols and expanding chronic management channels. Acquisition targets should demonstrate FDA REMS certification infrastructure or EU MDR technical documentation capabilities. Monitor PMDA and FDA breakthrough device designation announcements as inflection indicators for platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Certification Infrastructure Buildout | FDA-mandated prescriber programs lock in exclusive tolvaptan distribution relationships with tertiary centers. |
| Point-of-Care Sensor Platform Integration | Closed-loop sodium monitoring with Epic and Cerner EHR connectivity commands premium positioning in academic medical centers. |
| Home Infusion Service Expansion | Medicare reimbursement shifts in the United States accelerate chronic patient decoupling from hospital-based care. |
| EU MDR Technical Documentation Investment | Electrolyte monitoring devices face elevated clinical evidence requirements that thin competitive field. |
| Active Pharmaceutical Ingredient Backward Integration | Captive tolvaptan intermediate production insulates margins from Indian generic API pricing pressure. |
Research Methodology
Operator-level perspectives from hospital pharmacy directors, critical care intensivists, nephrology department heads, and formulary committee chairs anchored the qualitative base for this study. Primary interviews across tertiary care centers in Germany, Japan, and the United States were cross-validated against FDA REMS program documentation, EMA pharmacovigilance safety updates, PMDA approval records, and hospital procurement database extracts. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation ensured segmentation consistency across acute and chronic management pathways.
Scenario-bracketing around SIADH diagnostic standardization velocity, FDA REMS modification timelines, and EU MDR transition compliance costs framed the analytical envelope across the projection horizon. Segmentation dimensions included treatment acuity, delivery mode, underlying etiology, and regional regulatory cluster. CAGRs were derived from epidemiological trend extrapolation, protocol adoption curves, and pricing trajectory assumptions for vasopressin antagonist and hypertonic saline categories. Forecast inputs incorporated SIADH-related hospitalization rates from United States academic medical centers and German university hospital diagnostic coding patterns.
Stress conditions across FDA REMS enforcement intensity, EU MDR clinical evidence requirement scope, and generic vasopressin antagonist market entry timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding diagnostic algorithm adoption and reimbursement policy continuity. Quarterly review of FDA breakthrough device designations, EMA safety signal communications, and PMDA manufacturing inspection outcomes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Malaria Treatment Market
Medical Treatment
Single-Dose Therapy Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Gangrene Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Epiglottitis Treatment Market
Medical Treatment
Mercury Poisoning Treatment Market
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market
Medical Treatment
US Direct Anterior Approach (Total Hip Replacement) Market
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Global Medication Management Market
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market
Medical Treatment
CINV Treatment Market