
 Internal Trauma Fixation Device Market | 2026-2036
Internal Trauma Fixation Device Market Size, Share, and Industry Trends Forecast 2026-2036
Internal Trauma Fixation Device Market Intelligence
Orthopedic clinics is rotating toward outpatient surgical centers as the preferred setting for stable fracture fixation, shifting volume away from traditional hospital admissions. DePuy Synthes leverages its integrated trauma platform to dominate North American plate and screw supply chains. Stryker Corporation sustains competitive intensity through robotic-assisted trauma surgery ecosystems that bundle hardware with navigation. Zimmer Biomet anchors its position in emerging markets through localized manufacturing of intramedullary nails.
Internal trauma fixation devices comprise metallic or bioresorbable implants—typically titanium alloy, stainless steel, or poly-L-lactic acid constructs—engineered to stabilize bone fragments under physiological load through mechanical compression or intramedullary splinting. These devices restore anatomical alignment and permit early mobilization across fracture repair applications, where plates and screws retain the largest installed base but face margin compression from commoditization. Intramedullary nails command premium pricing in long-bone trauma due to biomechanical superiority and reduced soft-tissue disruption, while 3D printed solutions represent the fastest-expanding technology segment as patient-specific anatomical matching improves surgical efficiency and reduces revision rates.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations enforce stringent biocompatibility and fatigue-testing protocols that elevate barriers for new entrants while accelerating consolidation among established manufacturers. ISO 5832 material standards and ASTM F138 specifications govern implant metallurgy, ensuring traceability from raw stock through sterilization. Stakeholders must monitor evolving reimbursement thresholds for outpatient fixation procedures and assess whether biodegradable technology platforms can achieve mechanical parity with permanent implants before committing capital to capacity expansion.
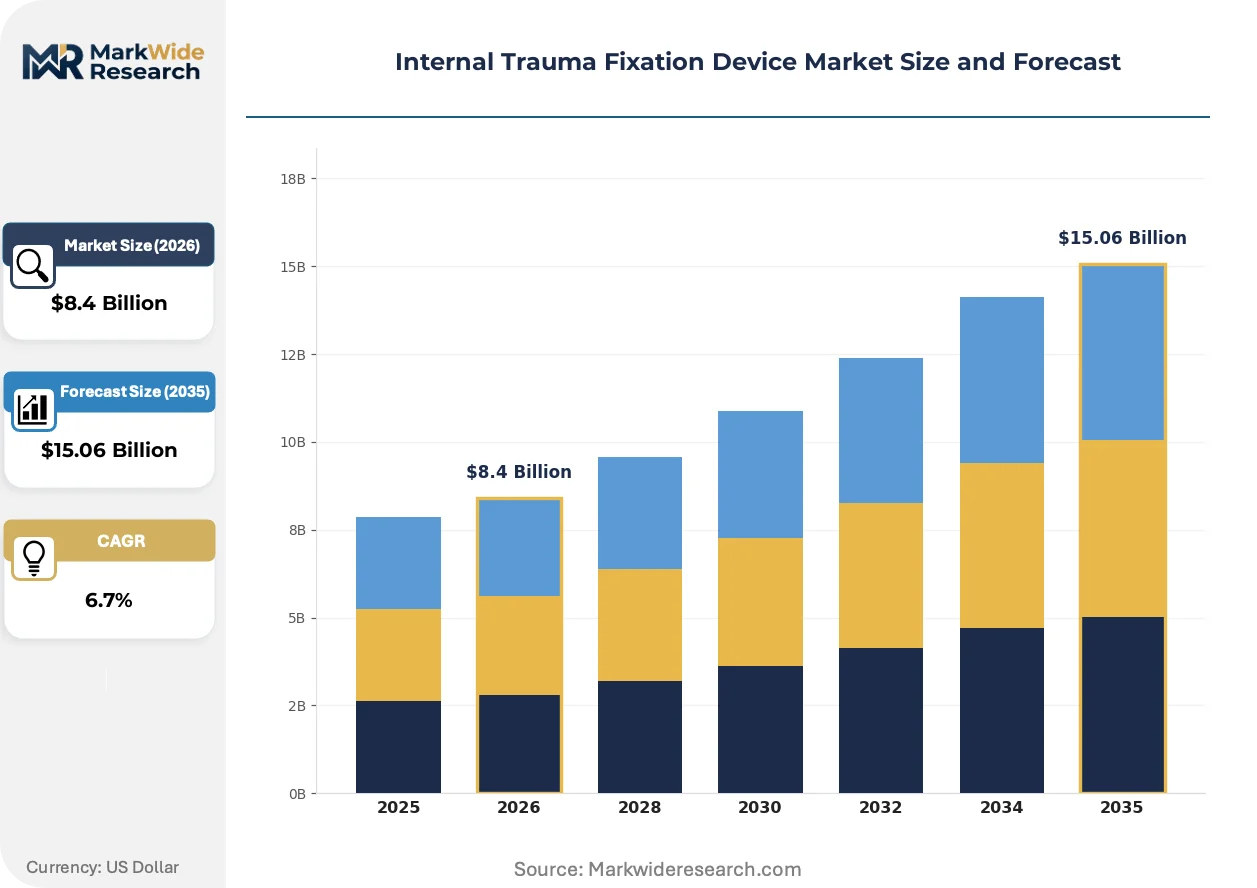
Market Dynamics
Patient-specific 3D printed fixation is compressing lead times for complex fracture cases while EU MDR technical documentation obligations force manufacturers to consolidate testing capabilities under centralized quality systems.
Growth Catalysts
- Trauma center network expansion:Germany, China, and the United States are commissioning dedicated orthopedic emergency facilities that standardize internal fixation protocols and concentrate surgical volume.
- FDA 510(k) pathway efficiency:Predicate device clearance mechanisms for titanium alloy constructs accelerate commercialization timelines compared with de novo submissions.
- Bioresorbable polymer advancement:Poly-L-lactic acid formulations with controlled degradation profiles eliminate secondary removal surgeries in pediatric and geriatric populations.
Market Restraints
- Titanium sponge supply concentration:Russian and Ukrainian feedstock disruptions have elevated raw material costs for implant-grade Ti-6Al-4V alloy production.
- EU MDR notified body capacity:Technical documentation review backlogs extend conformity assessment timelines to 18-24 months for Class III implantable devices.
- Biomechanical performance gap:Bioresorbable plates lack fatigue strength parity with permanent metals in load-bearing long-bone applications.
Strategic Opportunities
- Outpatient surgical center penetration:Ambulatory settings in the United States are capturing stable fracture cases previously routed to inpatient admissions.
- India trauma infrastructure buildout:Government hospital modernization programs under Ayushman Bharat create procurement scale for cost-optimized intramedullary nail systems.
- ISO 5832-14 beta-titanium adoption:Enhanced elasticity modulus matching with cortical bone drives substitution of conventional stainless steel in distal radius plating.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization studies face laboratory capacity constraints that delay regulatory submissions.
- Additive manufacturing qualification:Powder bed fusion process validation for 3D printed patient-specific implants requires extensive mechanical testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internal Trauma Fixation Device Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Screws, Intramedullary Nails, Bone Grafts End User: Hospitals, Outpatient Surgical Centers, Rehabilitation Centers, Orthopedic Clinics Technology: Active Fixation, Passive Fixation, Biodegradable Technology, 3D Printed Solutions Application: Fracture Repair, Joint Reconstruction, Osteotomy Procedures, Trauma Surgery |
| Companies Covered | DePuy Synthes, Stryker Corporation, Zimmer Biomet, B. Braun Melsungen AG, Smith & Nephew plc, Arthrex Inc., Globus Medical Inc., Medartis AG, Orthofix Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internal Trauma Fixation Device Market Strategic Shifts & Innovations
Digital surgical planning and point-of-care manufacturing are collapsing the traditional 12-16 week implant procurement cycle into 48-hour turnaround windows for emergency trauma cases.
Locking plate systems with variable-angle screw technology are replacing conventional compression plating in periarticular fracture repair. Orthopedic trauma surgeons at academic medical centers in the United States and Germany are standardizing these constructs for distal femur and proximal humerus applications. Hardware footprint is miniaturizing through low-profile plate designs that reduce soft-tissue irritation and postoperative implant removal rates.
EU MDR post-market surveillance requirements mandate systematic implant registry data collection and periodic safety update reports. Manufacturers must maintain clinical evidence portfolios across their entire product lifecycle. Small-to-mid sized orthopedic device firms are exiting the European market rather than absorbing compliance infrastructure costs.
Hospital procurement departments are consolidating supplier relationships through single-source contracts for trauma hardware categories. Group purchasing organizations in the United States are negotiating exclusive plate-and-screw agreements that displace fragmented multi-vendor purchasing. This concentration is most pronounced in integrated delivery networks across Texas, Florida, and California.
Internal Trauma Fixation Device Market Segmentation
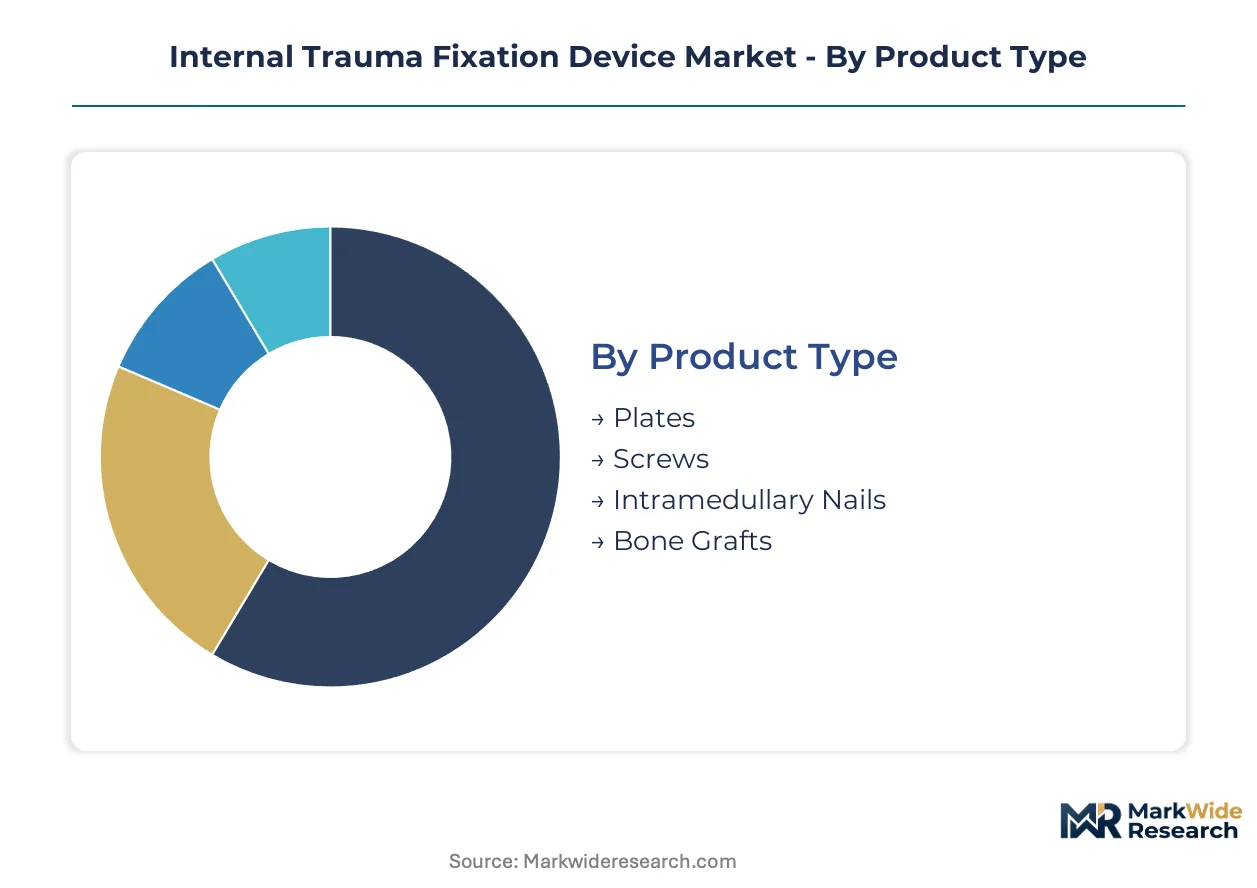
Segmentation in the internal trauma fixation device market reveals divergent supply chain configurations and regulatory pathways across product categories. Each dimension exposes distinct margin structures, from commoditized plate-and-screw systems to premium patient-specific implants.
Product Type:
Domestic production concentrates in plates and screws for high-volume trauma centers, while intramedullary nails and bone grafts flow through specialized export channels to emerging markets.
- Plates:Titanium alloy and stainless steel constructs provide rigid fixation for diaphyseal and periarticular fractures. Demand clusters in United States trauma networks seeking low-profile designs that minimize soft-tissue irritation and secondary removal rates.
- Screws:Cortical, cancellous, and locking screw variants deliver compression or angular stability depending on fracture pattern. German orthopedic clinics are standardizing variable-angle locking systems for complex distal radius and proximal humerus cases.
- Intramedullary Nails:Titanium or stainless steel intramedullary splints dominate long-bone trauma with superior biomechanical performance and reduced surgical exposure.
- Bone Grafts:Synthetic, allograft, and autograft materials supplement mechanical fixation in comminuted or open fractures.
Plates command the established base. The steepest expansion runs through intramedullary nails.
End User:
Cost tier stratification separates capital-intensive hospital installations from lean outpatient operations seeking disposable-heavy procedural models.
- Hospitals:Academic medical centers and Level I trauma centers maintain comprehensive implant inventories across all fixation modalities. United States integrated delivery networks in Texas and California are consolidating vendor contracts to single-source agreements for trauma hardware.
- Outpatient Surgical Centers:Ambulatory facilities capture stable fracture cases with streamlined plate-and-screw procedures that bypass inpatient admission costs. Medicare reimbursement shifts are accelerating site-of-service migration for eligible trauma repairs.
- Rehabilitation Centers:Post-acute facilities coordinate with implanting surgeons for hardware removal scheduling and mobilization protocols.
- Orthopedic Clinics:Specialized practices in Germany and China are expanding procedural capacity for minimally invasive fracture fixation under local anesthesia.
Hospitals retain the volume anchor. Outpatient surgical centers are climbing the fastest as reimbursement incentives realign.
Technology:
Application maturity spans decades-old passive fixation through experimental biodegradable platforms still seeking mechanical parity.
- Active Fixation:Dynamic compression plates and interfragmentary screw systems generate controlled micromotion that stimulates callus formation. FDA 510(k) predicate pathways accelerate commercialization for titanium alloy active fixation constructs.
- Passive Fixation:Locking plate systems with fixed-angle stability protect periarticular bone stock in osteoporotic patients. EU MDR technical documentation requirements are extending conformity timelines for legacy passive fixation portfolios.
- Biodegradable Technology:Poly-L-lactic acid implants eliminate secondary removal surgeries in pediatric populations where growth plates remain active.
- 3D Printed Solutions:Patient-specific anatomical matching improves surgical efficiency and reduces revision rates in complex pelvic and acetabular trauma.
Passive fixation holds the installed majority. 3D printed solutions are gaining share fastest as point-of-care manufacturing compresses procurement cycles.
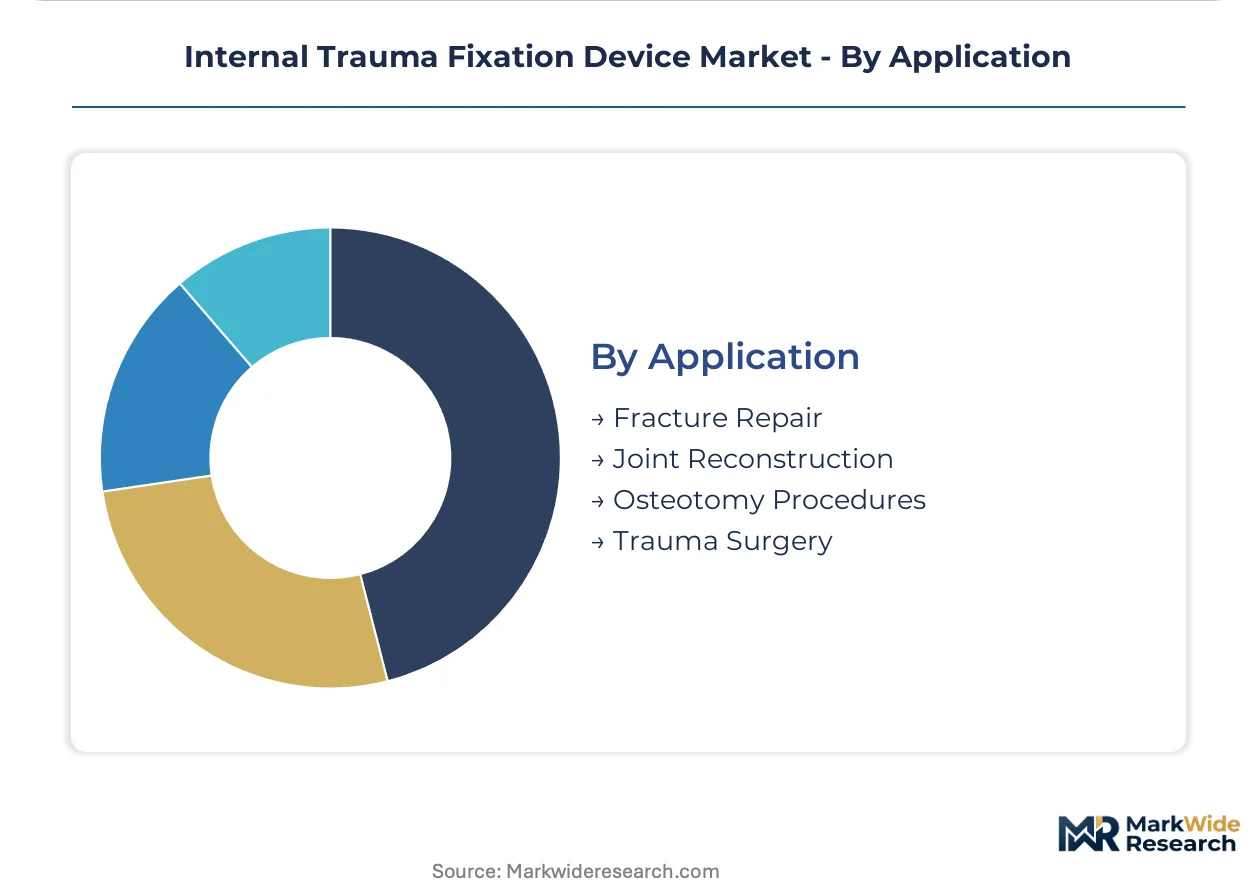
Application:
Volume concentration in trauma surgery creates procurement scale, while joint reconstruction commands premium pricing for revision-tolerant implant systems.
- Fracture Repair:Diaphyseal, metaphyseal, and articular fracture stabilization represents the core volume driver across all product categories. China's expanding trauma center network under hospital modernization programs is scaling demand for cost-optimized fixation systems.
- Joint Reconstruction:Periarticular fracture fixation and arthroplasty-adjacent procedures require anatomically contoured plates with locking screw options. German academic centers are standardizing these constructs for distal femur and proximal tibia applications.
- Osteotomy Procedures:Corrective bone cuts for deformity correction rely on precise plate fixation with controlled compression.
- Trauma Surgery:Emergency operative intervention for polytrauma patients demands rapid implant availability across the full fixation spectrum.
Fracture repair anchors procedure volume. Joint reconstruction carries the steepest expansion trajectory as aging demographics drive periarticular trauma incidence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in European orthopedic logistics, channeling titanium alloy feedstock and finished implants across Central European trauma networks. This infrastructure anchors a regional supply chain that distributes to Level I trauma centers from Berlin to Vienna.
United States
Level I trauma center expansion in Texas, Florida, and California is concentrating surgical volume for complex fracture repair. FDA 510(k) predicate device pathways accelerate commercialization timelines for titanium alloy constructs. The Dallas-Fort Worth metroplex hosts integrated delivery networks consolidating vendor contracts into single-source agreements for trauma hardware.
Germany
Academic medical centers in Berlin and Munich are standardizing variable-angle locking plate systems for periarticular fractures. EU MDR technical documentation requirements extend conformity assessment timelines for Class III implantable devices. The Tuttlingen surgical instrument cluster supplies precision-machined fixation components to domestic and export markets.
China
Hospital modernization programs under the national health infrastructure plan are scaling trauma center networks across provincial capitals. NMPA regulatory harmonization with international standards streamlines approval pathways for imported fixation devices. The Yangtze River Delta manufacturing corridor produces cost-optimized intramedullary nail systems for domestic consumption and Southeast Asian export.
India
Ayushman Bharat government hospital modernization is creating procurement scale for trauma fixation systems in tier-2 and tier-3 cities. CDSCO medical device rules enforce post-market surveillance obligations for imported and domestically manufactured implants. Maharashtra's Pune-Ahmednagar industrial belt hosts contract manufacturers supplying stainless steel plates to regional distributors.
Japan
Aging demographics are driving periarticular fracture incidence and demand for anatomically contoured locking plates. PMDA pharmaceutical and medical device agency maintains stringent biocompatibility testing protocols that elevate barriers for new market entrants. The Kobe medical device cluster specializes in precision-forged titanium components for domestic orthopedic OEMs.
Internal Trauma Fixation Device Market Key Industry Players
Concentration sits with diversified orthopedic conglomerates that leverage integrated trauma platforms across hardware, navigation, and surgical planning ecosystems. The vendor base stratifies into three tiers: multinational device manufacturers with full fixation portfolios, regional specialists in intramedullary nail or plate systems, and emerging point-of-care 3D printing service providers. Dominant competitive moves include vertical integration into raw titanium processing and strategic partnerships with academic trauma centers for clinical evidence generation.
Within the multinational tier, DePuy Synthes and Stryker Corporation exemplify archetypes of platform breadth, while Zimmer Biomet occupies a position emphasizing emerging market localization. These three entities anchor the competitive structure through contrasting geographic and technological positioning strategies.
| Leading Market Players |
|---|
| DePuy Synthes |
| Stryker Corporation |
| Zimmer Biomet |
| B. Braun Melsungen AG |
| Smith & Nephew plc |
| Arthrex Inc. |
| Globus Medical Inc. |
| Medartis AG |
| Orthofix Medical Inc. |
| Others |
Cost & Logistics Intelligence
High-volume titanium sponge processing in China and Russia anchors cost floors for implant-grade Ti-6Al-4V alloy, concentrating upstream leverage among a handful of feedstock suppliers while downstream OEMs absorb volatility through long-term offtake contracts. This scale asymmetry compresses margins for mid-tier plate and screw manufacturers that lack backward integration into raw material streams.
Pricing Analysis
Volume-discount tiering structures separate premium patient-specific 3D printed constructs from standard intramedullary nails and economy-grade stainless steel plates. Price differentiation hinges on ISO 5832-14 beta-titanium certification tier and customization depth for complex pelvic trauma. Cost compression in commoditized plate-and-screw categories is intensifying because group purchasing organizations in Texas and Florida are consolidating supplier rosters. Academic medical centers exhibit lowest price sensitivity due to bundled navigation ecosystem contracts, while outpatient surgical centers in the United States drive hardest bargain for disposable-heavy procedural kits.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes through the Port of Hamburg elevate inbound logistics costs for German orthopedic manufacturers sourcing titanium alloy feedstock. Geographic supply concentration centers on China for sponge processing, Ukraine for vacuum arc remelting capacity, and the United States for precision forging of distal radius plates. Raw material dependencies encompass titanium sponge, cobalt-chrome bar stock, and poly-L-lactic acid polymer resin. Single-source vulnerability in Russian sponge supply creates structural risk exposure. Distribution runs through specialized orthopedic distributors to hospital procurement departments and direct-to-manufacturer contracts with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through single-source vendor consolidation by United States integrated delivery networks, fragmenting supplier negotiating leverage across trauma hardware categories.
For Market Incumbents: Secure captive titanium sponge supply through long-term offtake agreements with Chinese or Japanese feedstock processors to insulate margin structure from commodity volatility. Defend installed base in locking plate systems by accelerating FDA 510(k) submissions for variable-angle constructs before EU MDR documentation backlogs clear for European competitors. For New Entrants and Emerging Players: Differentiate on point-of-care 3D printing service models that collapse procurement cycles for complex pelvic trauma cases underserved by standard inventory. Target outpatient surgical centers in Florida and Texas seeking patient-specific fixation without capital investment in additive manufacturing infrastructure. Pursue hospital system partnership go-to-market angle through risk-sharing agreements on revision rate guarantees. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract manufacturers with sterilization validation capabilities and exclusive GPO agreements. Five-to-ten year viability favors targets with EU MDR technical documentation already filed rather than legacy portfolios facing conformity assessment backlogs. Monitor FDA 510(k) clearance velocity for beta-titanium constructs as inflection signal for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Filing | Accelerates market access for Class III implants ahead of notified body capacity constraints. |
| Point-of-Care 3D Printing Partnership | Compresses procurement cycles from weeks to hours for emergency trauma cases. |
| Hospital System Risk-Sharing Agreement | Aligns implant pricing with clinical outcomes and revision rate performance. |
| Beta-Titanium Alloy Adoption | Enables elasticity modulus matching with cortical bone in distal radius plating. |
| Group Purchasing Organization Contract | Locks in volume commitment across integrated delivery network trauma centers. |
Research Approach
Initial hypotheses were tested against primary input from orthopedic trauma surgeons, hospital purchasing committee chairs, biomedical engineers at implant manufacturers, and GPO contracts managers, then refined through secondary validation against FDA 510(k) premarket notification databases, EU MDR notified body technical documentation filings, hospital procurement contract registries, and ISO 5832 material standard certification records. Bottom-up demand modeling across procedure volumes and implant ASPs was triangulated with top-down market sizing from manufacturer revenue disclosures.
Variance decomposition across product type, end user facility tier, technology platform, and application anatomy drove segmentation-level growth attribution throughout the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical procedure volume trajectories and reimbursement rate evolution. Forecast inputs incorporated trauma center network expansion timelines, EU MDR notified body capacity constraints, and titanium sponge supply concentration dynamics.
Material uncertainties — regulatory approval delays, raw material supply disruptions, and reimbursement threshold revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions about predicate device clearance efficiency and biocompatibility testing laboratory capacity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Next Generation Surgical Robotics Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Global Joint Pain Injections Market
Medical Devices
Hybrid Grafts Market
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
Neonatal Hearing Screening Devices Market
Medical Devices
Pharmaceutical Robots Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Human Anatomical Models Market
Medical Devices
Indonesia Devices Market
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
Radiofrequency-Based Aesthetic Devices Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Epidural Anesthesia Sets Market