
 Disc Top Caps Market | 2026-2036
Disc Top Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Disc Top Caps Market Outlook
Pharmaceutical-grade specification upgrades is bifurcating the disc top caps landscape into validated cleanroom production and standard commercial molding tiers. AptarGroup, Inc. leverages its medical dispensing heritage to dominate high-barrier segments. Berry Global, Inc. sustains broad plastics manufacturing scale across North American and European facilities. Silgan Holdings Inc. anchors metal closure expertise that extends into hybrid disc top designs for regulated applications.
Disc top caps are single-dose or metered-dispensing closures featuring a depressed center disc that opens flow channels under fingertip pressure, typically molded from polypropylene or polyethylene with Shore D hardness ratings between 60 and 75 for snap-fit retention. Their primary purpose is controlled liquid dispensing in personal care, pharmaceutical, and household chemical containers where drip-free reseal and one-hand operation prove essential. Plastic closures occupy the volume lead across cosmetics and household products, though child-resistant closure types command premium positioning in pharmaceutical applications where FDA 16 CFR 1700 compliance is mandatory. Flip-top configurations are maturing in mass-market shampoo and body wash segments, while squeeze-actuated disc tops represent the fastest-growing format for travel-size and on-the-go personal care SKUs.
FDA 16 CFR 1700 poison prevention standards govern child-resistant disc top designs in the United States, while the EU Packaging and Packaging Waste Regulation drives recycled content minimums across European supply chains. REACH compliance through ECHA restricts certain plasticizers and colorants in closures contacting cosmetic formulations. ISO 8317 certification for reclosable child-resistant packaging shapes qualification requirements for pharmaceutical disc top entrants. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to invest in closed-loop recycling partnerships or prioritize lightweighting innovations that reduce material exposure to regulatory thresholds.
Market Dynamics
Refillable packaging mandates across the EU are forcing cosmetic brands to redesign primary containers, elevating disc top specifications toward premium sealing performance and material traceability that standard closures cannot satisfy.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content minimums are pulling post-consumer polypropylene into closure supply chains, qualifying disc top producers for green procurement tenders from multinational personal care brands.
- Child-resistant packaging standards:FDA 16 CFR 1700 compliance requirements in pharmaceutical applications are creating certified production niches that command sustained price premiums over commodity cosmetic closures.
- Travel-size personal care expansion:Squeeze-actuated disc tops are capturing SKU growth in airline-compliant and gym-channel formats where one-handed dispensing determines purchase conversion.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer prices track naphtha and natural gas liquid markets, compressing margin predictability for high-volume disc top molders serving mass-market shampoo and body wash segments.
- Tooling concentration in German mold-making:Precision multi-cavity disc top molds require 6-8 month lead times from specialized suppliers around Stuttgart and Munich, constraining capacity expansion for North American and Asian converters.
- Child-resistant certification timelines:ISO 8317 testing protocols demand 12-18 month validation cycles that delay pharmaceutical disc top launches and tie up working capital in inventory buffers.
Strategic Opportunities
- Indian personal care manufacturing:Contract manufacturers near Mumbai and Chennai are localizing disc top sourcing to reduce landed costs for domestic brands expanding into tier-2 and tier-3 cities.
- Mono-material packaging convergence:All-polyethylene bottle-and-closure systems are aligning with EU recycling stream requirements, positioning compatible disc top designs for preferential placement in retailer sustainability scorecards.
- Direct-to-consumer subscription channels:Replenishment models for skincare and haircare are specifying custom-colored disc tops with brand-embossed discs that differentiate unboxing experiences.
Industry Challenges
- Cleanroom production qualification:Pharmaceutical-grade disc tops require ISO Class 8 molding environments and automated vision inspection systems that demand capital outlays beyond mid-tier converter balance sheets.
- Legacy press retrofit complexity:Existing injection molding fleets designed for standard closures require screw and barrel modifications to process high-flow recycled polypropylene without degradation.
- Cross-border extended producer responsibility registration:Disc top producers selling into France, Italy, and Spain must navigate divergent packaging registry systems with non-harmonized fee structures and reporting cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disc Top Caps Market |
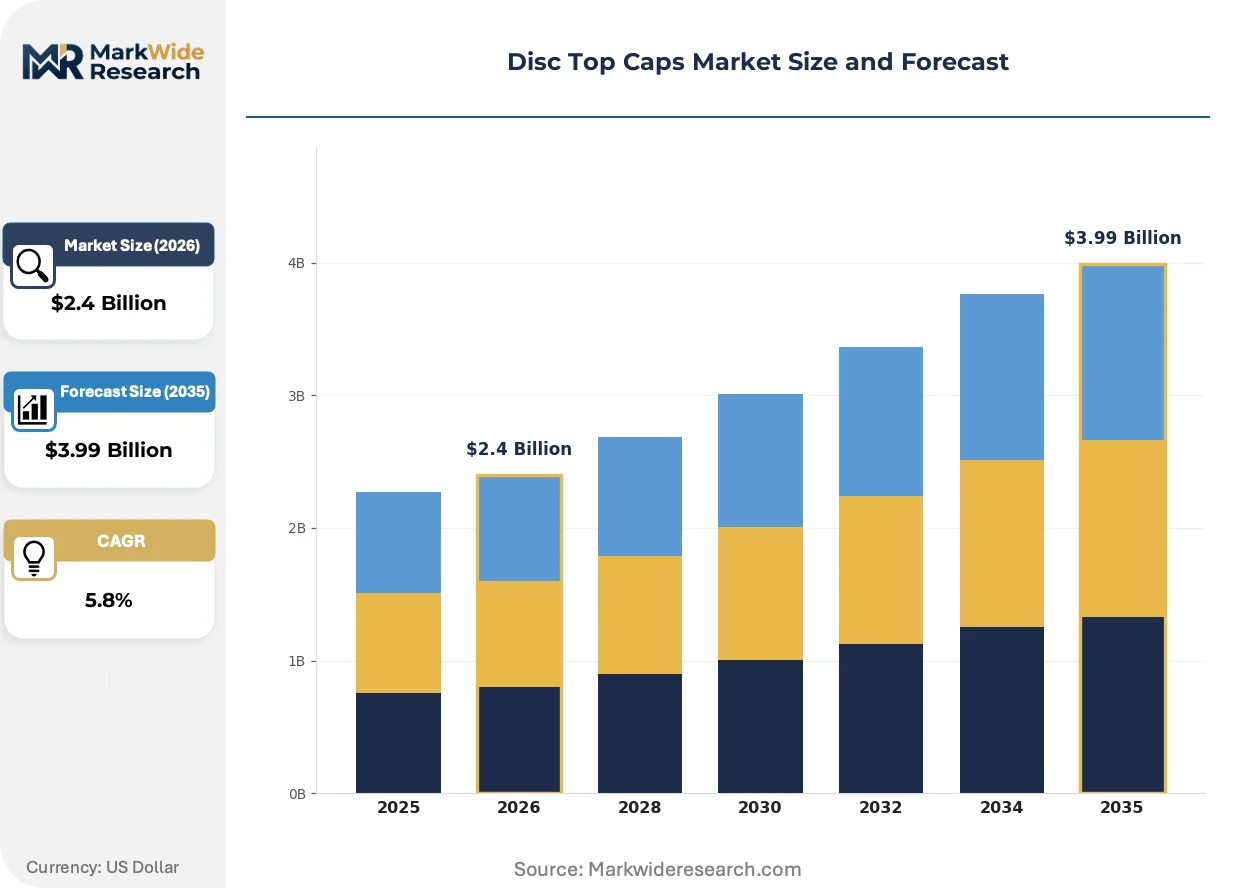
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Glass, Composites Application: Cosmetics, Pharmaceuticals, Food & Beverages, Household Products Closure Type: Child-Resistant, Twist-Off, Flip-Top, Squeeze End User: Manufacturers, Retailers, Distributors, Wholesalers |
| Companies Covered | AptarGroup, Inc., Berry Global, Inc., Silgan Holdings Inc., Albea Group, RPC Group Plc, Guala Closures S.p.A, BERICAP, Alpla Werke Alwin Lehner GmbH & Co KG, TricorBraun, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disc Top Caps Market Strategic Shifts
Material science breakthroughs and regulatory tightening are converging to redefine disc top performance specifications, with sustainability metrics now weighted equally alongside functional reliability in buyer evaluations.
Biobased polypropylene derived from renewable feedstocks is displacing fossil-based resin in premium cosmetic disc tops. European luxury skincare brands are specifying mass-balance certified closures to meet corporate net-zero commitments. This displacement is compressing conventional resin demand in the high-margin prestige segment while creating supply bottlenecks for certified biobased material.
REACH restrictions on certain phthalate plasticizers and colorants are compelling reformulation of disc top masterbatches across European supply chains. ECHA substance evaluations are disqualifying legacy additive packages that previously provided UV stability and processing lubricity. Pharmaceutical and cosmetic disc top producers are accelerating migration to alternative stabilizer systems to maintain compliance without sacrificing Shore D hardness specifications.
Buyers are consolidating closure procurement under centralized sustainability sourcing functions that evaluate suppliers on carbon footprint disclosure and recycling stream compatibility. Mass-market personal care brands are disintermediating regional distributors to contract directly with disc top molders capable of verified post-consumer content certificates. This concentration is most visible in Germany, where Hamburg and Düsseldorf headquarters of major cosmetic manufacturers are driving standardization of supplier audit protocols.
Disc Top Caps Market Segmentation
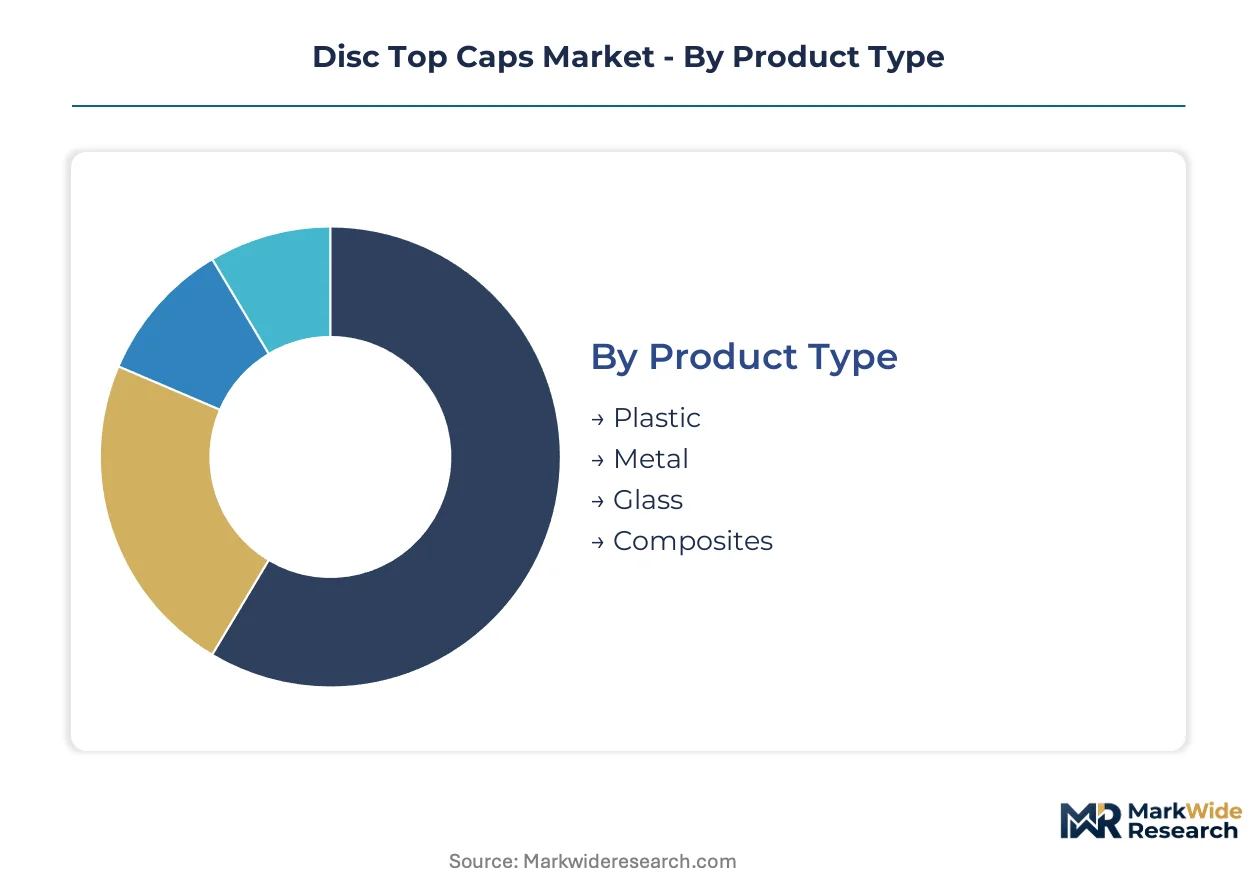
Disc top caps segmentation reveals divergent margin profiles across material technologies and regulatory tiers. Pharmaceutical-grade specifications command sustained premiums over commodity cosmetic formats, while child-resistant certification creates defensible production niches.
Product Type:
Polypropylene and polyethylene formulations concentrate margin pools in high-volume personal care, though metal hybrid designs capture value in regulated pharmaceutical channels.
- Plastic:Polypropylene dominates volume with Shore D hardness ratings between 60 and 75 for snap-fit retention. Hamburg and Düsseldorf cosmetic manufacturers are standardizing post-consumer recycled content specifications that disqualify conventional fossil-based resin from green procurement tenders.
- Metal:Aluminum and tinplate hybrids integrate with disc top mechanisms for high-barrier pharmaceutical applications. FDA 16 CFR 1700 compliance requirements sustain price premiums over standard commercial molding tiers.
- Glass:Borosilicate and soda-lime closures serve premium skincare segments requiring inert contact surfaces.
- Composites:Multi-layer barrier structures combine polymer substrates with metallized films for aggressive chemical resistance.
Plastic holds installed capacity. Metal is rotating up the share rankings.
Application:
Volume concentrates in personal care refillable systems, though pharmaceutical validation timelines extend contract durations and improve capital recovery.
- Cosmetics:Refillable packaging mandates across the EU are elevating disc top specifications toward premium sealing performance. Mass-balance certified biobased polypropylene is displacing fossil-based resin in prestige skincare segments.
- Pharmaceuticals:ISO 8317 certification for reclosable child-resistant packaging shapes qualification requirements. Cleanroom production environments demand capital outlays that filter mid-tier converters from certified supply chains.
- Food & Beverages:Dispensing closures for sauces and condiments prioritize oxygen barrier properties over aesthetic customization.
- Household Products:Aggressive chemical formulations require modified polypropylene with enhanced stress-crack resistance.
Cosmetics maintains volume leadership. Pharmaceuticals is climbing the fastest on value contribution.
Closure Type:
Regulatory certification tiers separate pricing structures, with child-resistant designs sustaining premiums through mandatory retesting protocols.
- Child-Resistant:FDA 16 CFR 1700 compliance requires 12-18 month validation cycles that tie up working capital. ISO 8317 testing protocols delay pharmaceutical launches but create production niches with limited supplier competition.
- Squeeze:Actuated disc tops are capturing SKU growth in airline-compliant and gym-channel formats. One-handed dispensing determines purchase conversion in travel-size personal care expansion.
- Twist-Off:Conventional threaded designs serve mass-market shampoo and body wash segments with minimal functional differentiation.
- Flip-Top:Hinged configurations mature in standard personal care applications where reseal reliability outweighs single-handed operation.
Child-Resistant holds certification infrastructure. Squeeze is gaining share fastest in emerging format demand.
End User:
Procurement consolidation under centralized sustainability functions is disintermediating traditional distribution layers.
- Manufacturers:Personal care brands near Mumbai and Chennai are localizing disc top sourcing to reduce landed costs. Direct contracting with molders capable of verified post-consumer content certificates is replacing regional distributor relationships.
- Retailers:Sustainability scorecards at German mass-market chains prioritize mono-material packaging compatibility. All-polyethylene bottle-and-closure systems align with EU recycling stream requirements for preferential placement.
- Distributors:Inventory buffers for pharmaceutical certification timelines demand working capital capacity that favors consolidated players.
- Wholesalers:Bulk procurement of standard cosmetic closures competes on logistics efficiency rather than technical specification.
Manufacturers anchor demand concentration. Retailers is rotating up the share rankings on sustainability-driven sourcing authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Disc top cap manufacturing clusters around specialized mold-making centers in southern Germany, where six-to-eight-month lead times for precision multi-cavity tooling constrain capacity expansion elsewhere. Demand concentration follows personal care brand headquarters and pharmaceutical packaging hubs across multiple continents.
Germany
Cosmetic manufacturers cluster around Hamburg and Düsseldorf, driving standardization of supplier audit protocols for post-consumer recycled content. The EU Packaging and Packaging Waste Regulation mandates recycled content minimums that qualify local molders for green procurement tenders. Stuttgart and Munich host specialized mold-making suppliers whose six-to-eight-month lead times bottleneck North American and Asian converter expansion.
United States
Pharmaceutical-grade disc top demand concentrates around FDA-regulated packaging corridors in New Jersey and North Carolina. FDA 16 CFR 1700 poison prevention standards govern child-resistant designs, creating certified production niches with sustained price premiums. Chicago-area converters serve mass-market shampoo and body wash segments where polypropylene feedstock volatility compresses margin predictability.
India
Contract manufacturers near Mumbai and Chennai localize disc top sourcing to reduce landed costs for domestic brands expanding into tier-2 and tier-3 cities. BIS standards shape quality benchmarks for imported closure components. The PLI scheme for specialty chemicals indirectly supports upstream polymer stabilization additive production.
China
Yangtze River Delta personal care exporters specify disc tops compatible with mono-material polyethylene bottle systems for EU retail sustainability scorecards. GB standards govern food-contact closure safety, while MEE environmental inspections tighten emissions compliance for injection molding operations. Guangdong Province converters supply squeeze-actuated formats for airline-compliant travel-size SKUs.
France
Paris-headquartered luxury skincare brands specify mass-balance certified biobased polypropylene closures to meet corporate net-zero commitments. ANSM oversees pharmaceutical packaging material safety, while extended producer responsibility registration requirements diverge from Italian and Spanish systems. Lyon-area cosmetic chemistry clusters drive demand for REACH-compliant additive packages.
Disc Top Caps Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with medical-grade cleanroom capabilities separating premium-tier suppliers from commodity molders. The market exhibits tiered consolidation: multinational packaging conglomerates with medical dispensing heritage dominate high-barrier pharmaceutical segments, while regional plastics specialists capture mass-market personal care volume. Three archetypes prevail: integrated healthcare packaging platforms, broad-scale plastics manufacturers with closure divisions, and precision mold-making specialists extending into finished closure production. Competitive moves center on backward integration into recycled resin sourcing and geographic expansion through distributor acquisition in high-growth Asian markets.
Among North American healthcare packaging platforms, AptarGroup, Inc. and Berry Global, Inc. exemplify divergent strategic positions. AptarGroup occupies the medical dispensing heritage archetype, while Berry Global represents broad plastics manufacturing scale. Silgan Holdings Inc. anchors metal closure expertise that extends into hybrid disc top designs, sitting within the specialty materials tier. These three names illustrate how regulatory certification infrastructure, rather than unit volume alone, determines sustainable margin capture.
| Leading Market Players |
|---|
| AptarGroup, Inc. |
| Berry Global, Inc. |
| Silgan Holdings Inc. |
| Albea Group |
| RPC Group Plc |
| Guala Closures S.p.A |
| BERICAP |
| Alpla Werke Alwin Lehner GmbH & Co KG |
| TricorBraun, Inc. |
| Others |
Value Chain & Pricing Dynamics
Biobased polypropylene displacement of fossil-based resin simultaneously redraws procurement geography toward European mass-balance certification hubs and compresses margin structures for uncertified molders locked into conventional feedstock contracts. This substitution dynamic concentrates pricing power among suppliers with verified renewable content pipelines while fragmenting the commodity tier.
Pricing Analysis
FDA 16 CFR 1700 dictates the pricing tier structure across pharmaceutical and personal care applications. Three-tier pricing separates ISO 8317-certified child-resistant closures from standard cosmetic formats and uncertified commodity moldings. Price differentiation rests on certification grade and cleanroom production qualification. Cost compression in mass-market shampoo segments is intensifying because polypropylene feedstock volatility erodes contract margin predictability. Mass-market personal care brands exhibit highest price sensitivity, while pharmaceutical buyers prioritize compliance assurance over unit cost.
Supply Chain Analysis
Germany anchors precision multi-cavity mold production for disc top mechanisms, with Stuttgart and Munich suppliers commanding six-to-eight-month lead times that bottleneck global converter expansion. Tooling fabrication draws from specialized metallurgy and CNC machining clusters, while closure molding rests on polypropylene resin flows from petrochemical hubs. Single-source vulnerability concentrates in German mold-making expertise. Distribution runs through direct contracting between brand sustainability offices and certified molders, bypassing traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as procurement consolidation under centralized sustainability functions disintermediates legacy distribution layers and splinters volume across specialized certification tiers.
For Market Incumbents: Fortify certification infrastructure against emerging biobased resin specialists by deepening backward integration into post-consumer polypropylene sourcing and expanding ISO Class 8 cleanroom capacity in pharmaceutical corridors. Child-resistant validation timelines and REACH-compliant additive reformulation demands raise defensive barriers against commodity molders lacking capital depth. For New Entrants and Emerging Players: Lead with mono-material polyethylene compatibility and verified mass-balance certification to capture green procurement tenders from Hamburg and Düsseldorf cosmetic headquarters. The Indian personal care manufacturing cluster near Mumbai offers the most penetrable geography, with domestic brands expanding into tier-2 and tier-3 cities seeking localized sourcing to reduce landed costs. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors cleanroom-capable platforms with pharmaceutical validation heritage. Long-term viability hinges on regulatory certification infrastructure rather than volume scale alone. Acquisition targets should display ISO 8317 testing capabilities and automated vision inspection systems. The signal to watch is EU Packaging and Packaging Waste Regulation enforcement tightening that accelerates post-consumer content mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin Sourcing | Captures post-consumer polypropylene streams required for EU green procurement tenders. |
| Cleanroom Production Qualification | Unlocks ISO 8317-certified pharmaceutical segments with sustained price premiums. |
| Geographic Expansion through Distributor Acquisition | Establishes presence in Mumbai and Chennai personal care manufacturing clusters. |
| Mono-Material Packaging Convergence | Aligns disc top designs with EU recycling stream requirements for retailer sustainability scorecards. |
| Direct-to-Consumer Subscription Channel Development | Captures replenishment model demand for custom-colored, brand-embossed disc tops. |
Study Parameters
Operator-level perspectives from injection molding plant managers, cosmetic brand sustainability officers, pharmaceutical packaging procurement leads, and specialized mold-making engineers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 16 CFR 1700 compliance databases, ECHA REACH substance restriction updates, and EU Packaging and Packaging Waste Regulation implementation guidance. Customs records tracking polypropylene resin flows, SEC filings from packaging conglomerates, and German mechanical engineering association tooling production statistics furnished quantitative triangulation. Bottom-up volume estimates from individual molder capacity and top-down demand calibration from personal care brand SKU expansion plans converged on segment-level outputs.
Sensitivity analysis tested forecast robustness across propylene monomer price volatility scenarios and EU recycled content mandate acceleration pathways. The analytical framework modeled demand across material technology tiers, regulatory certification levels, application segments, closure actuation types, and geographic manufacturing clusters. CAGRs derived from elasticity-adjusted volume projections and value-per-unit trends across premium and commodity tiers. Industry-specific inputs included pharmaceutical validation cycle durations, mold-making lead time distributions, and biobased resin supply bottleneck assessments.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or abrupt polypropylene feedstock price dislocation would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and post-consumer resin quality consistency. Recalibration cycles align with material shifts in EU Packaging and Packaging Waste Regulation implementation and biobased polypropylene supply expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Fez Caps Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
Global Aluminum Caps for Packaging Market
Caps and Closures
PVC-Free Cap Liners Market
Caps and Closures
PET Dome Lids Market
Caps and Closures
Polypropylene Screw Caps Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
PCR Closures Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Bar Top Corks Market