
 Morocco Plastic Caps and Closures Market | 2026-2036
Morocco Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Plastic Caps and Closures Market Insights
Polypropylene is hardening its position as the dominant resin in Morocco's closure manufacturing, displacing heavier PVC alternatives across beverage and food packaging lines. Mutandis leverages its integrated blow-molding and cap-making footprint to supply Moroccan mineral water brands with flip-top and sports-cap formats. Bericap Holding GmbH anchors its Maghreb strategy through technical service centers that calibrate dispensing-cap torque specifications for local bottling speeds. ALPLA Group competes by extending its preform-to-closure logistics model into Agadir and Tangier Med free zone operations.
Plastic caps and closures are injection-molded or compression-molded thermoplastic components, typically specified by thread finish, seal liner composition, and opening torque, designed to ensure product integrity, consumer safety, and controlled dispensing across liquid and semi-solid contents. Screw caps dominate volume in Morocco's beverage packaging channel, where standard PCO and BPF thread profiles accommodate regional glass and PET bottle neck finishes. Dispensing caps represent the fastest-growing product category, driven by pharmaceutical sector demand for metered-dose and dropper closures that reduce contamination risk in Casablanca's expanding generic drug cluster. Polyethylene retains margin strength in food-industry snap-on applications where hermetic seal performance and cold-chain flexibility justify premium resin grades.
Morocco's national standardization body enforces food-contact migration limits aligned with EU REACH principles, while CDSCO-equivalent pharmaceutical regulators mandate child-resistant closure certification for OTC and prescription packaging. These frameworks shape converter investment toward in-house testing laboratories and traceable resin documentation systems. Stakeholders must monitor how pending extended producer responsibility regulations will restructure post-consumer collection obligations and recycled-content quotas for domestic closure producers.
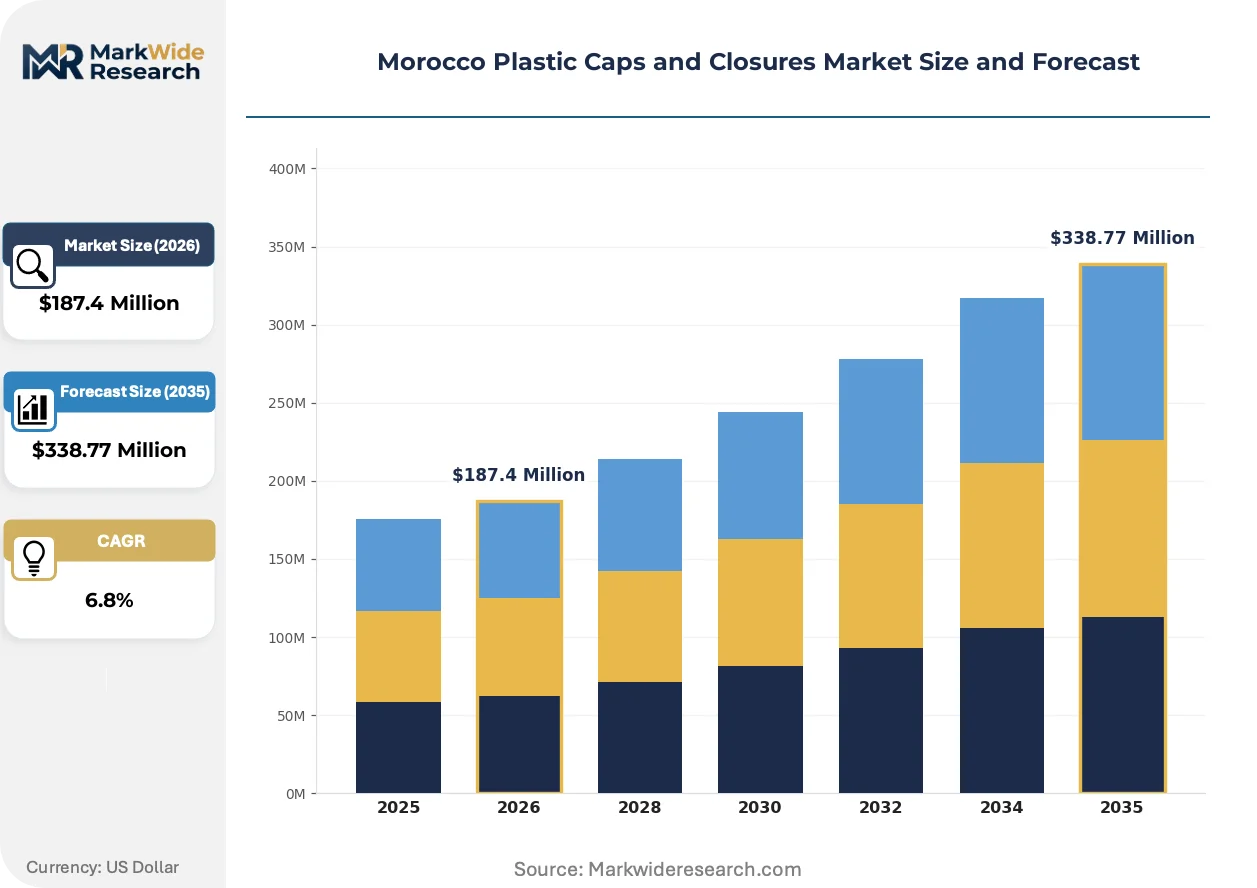
Market Dynamics
Polypropylene resin migration is compressing closure weights across Morocco's beverage packaging sector, forcing converters to retool injection lines for thinner-wall dispensing formats while maintaining seal integrity under Casablanca's ambient temperature cycles.
Growth Catalysts
- REACH-aligned food-contact mandates:Morocco's national standardization body enforces migration limits that push domestic converters toward certified virgin resin streams, creating captive demand for compliant closure suppliers.
- Pharmaceutical line retrofitting:Casablanca's generic drug manufacturers are installing child-resistant and tamper-evident screw-cap systems to serve export contracts into francophone African markets.
- Agadir-Tangier logistics corridors:Free zone infrastructure expansion enables just-in-time closure delivery to mineral water bottlers operating across the Atlantic and Mediterranean coasts.
Market Restraints
- Polypropylene feedstock volatility:Moroccan converters face margin compression when global propylene prices spike, as local resin production remains insufficient for packaging-grade specifications.
- Single-source tooling dependency:High-cavitation injection molds for PCO thread profiles are concentrated among European equipment suppliers, extending lead times for capacity expansion.
- Recycled-content contamination thresholds:Current mechanical recycling streams cannot reliably produce food-contact-grade polypropylene, limiting circular material adoption in beverage closures.
Strategic Opportunities
- Extended producer responsibility pre-positioning:Pending regulations on post-consumer collection obligations will reward early movers with integrated recycling infrastructure in the Casablanca-Rabat corridor.
- Dropper closure specialization:Metered-dose pharmaceutical formats remain underpenetrated relative to regional demand growth, offering white space for torque-calibrated dispensing systems.
- Agadir port zone backward integration:Captive resin compounding and color-masterbatch production can compress logistics costs for exporters targeting West African markets.
Industry Challenges
- Multi-cavity mold commissioning timelines:Validating high-speed closure production for beverage bottlers requires 12-18 month qualification cycles that strain working capital.
- Child-resistant certification backlog:Morocco's pharmaceutical regulator maintains limited testing laboratory capacity, delaying market entry for novel tamper-evident designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Plastic Caps and Closures Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip-top Caps, Dispensing Caps, Screw Caps, Snap-on Caps Material: Polypropylene, Polyethylene, Polyester, PVC End User: Beverage Industry, Food Industry, Pharmaceutical Sector, Cosmetics Industry Application: Packaging, Sealing, Dispensing, Containment |
| Companies Covered | Mutandis, Bericap Holding GmbH, ALPLA Group, Sacmi Imola S.C., Tetra Pak International S.A., Amcor Plc, Mondi Pap Sac Maghreb SA, Multisac SA, Afrimag Glue, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Plastic Caps and Closures Market Trends and Innovations
Automation of quality assurance and lightweighting protocols is compressing cycle times across Moroccan converter floors, while regulatory alignment with EU frameworks reshapes material qualification pathways.
All-electric injection molding with integrated cavity-pressure monitoring is automating real-time defect rejection in high-volume beverage closure production. Moroccan mineral water bottlers in the Casablanca-Rabat corridor are adopting these systems at replacement-cycle pace. The technology is automating workforce reduction in quality-control functions while tightening dimensional tolerance bands for PCO thread compatibility.
Morocco's national standardization body is tightening food-contact migration limits that mirror EU REACH substance restrictions. Domestic converters must now document resin traceability from polymerization through final article formation. Pharmaceutical packaging lines serving CDSCO-equivalent certification requirements face the steepest compliance burden, driving investment in in-house extraction testing laboratories.
Buyer consolidation among Moroccan mineral water brands is compressing supplier negotiation cycles from annual to quarterly frameworks. Large bottlers in the Sidi Ali and Oulmès supply chains are unbundling closure procurement from preform contracts, forcing specialized converters to bid independently. This pattern is most visible in the Casablanca industrial zone where three bottlers control two-thirds of national volume.
Morocco Plastic Caps and Closures Market Segmentation
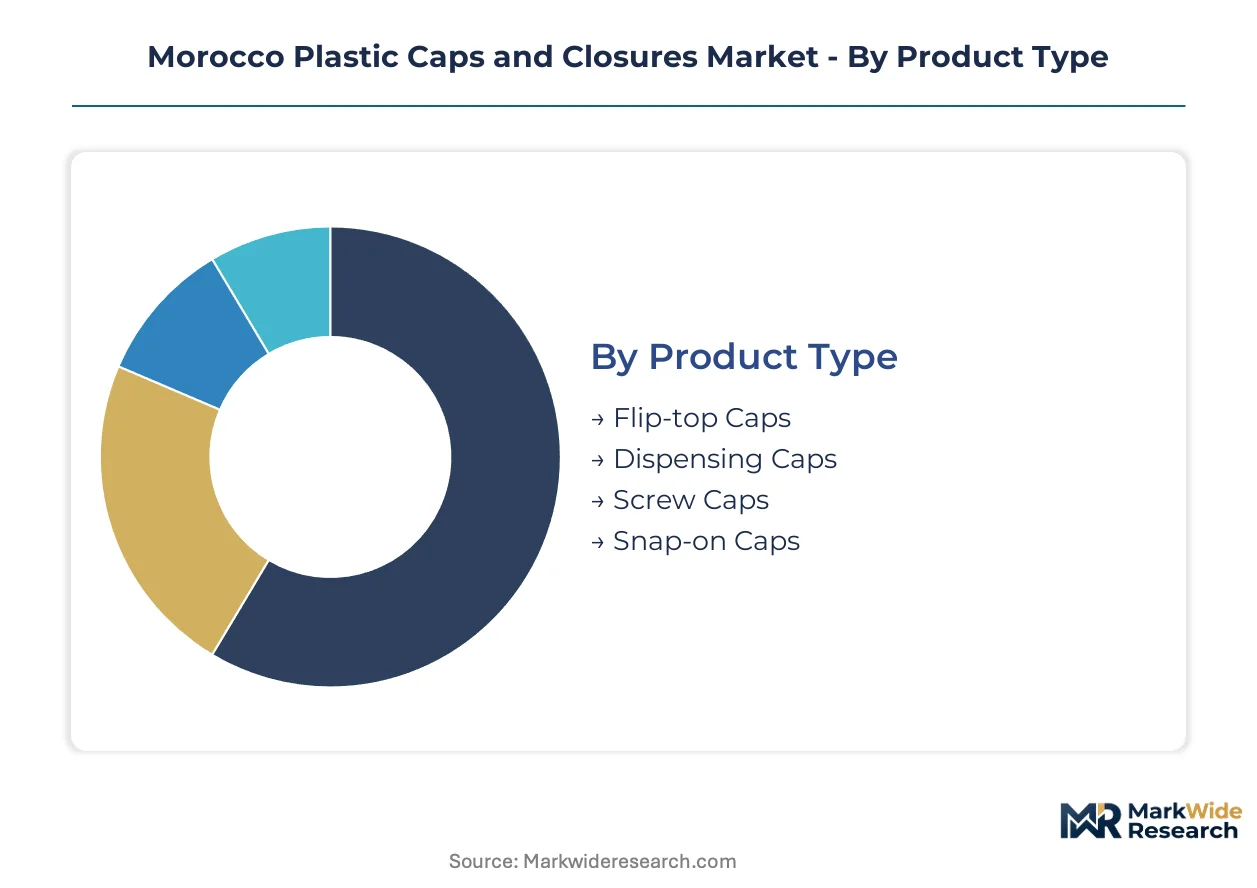
Morocco's closure market fragments across four intersecting dimensions that determine resin selection, tooling investment, and regulatory compliance burden. Understanding these segment boundaries reveals where converters must anchor certification capabilities versus where cost competition dominates procurement decisions.
Product Type:
Certification intensity varies sharply by child-resistance mandates and tamper-evidence requirements, with pharmaceutical-grade formats demanding CDSCO-equivalent testing laboratory validation that beverage closures escape.
- Screw Caps:Threaded thermoplastic closures specified by PCO or BPF thread profiles for secure sealing across glass and PET bottle necks. Casablanca's generic drug manufacturers are retrofitting lines for child-resistant and tamper-evident screw caps to serve francophone African export contracts, tightening torque specification tolerances.
- Dispensing Caps:Metered-dose and controlled-flow formats incorporating orifice reducers, flip-spouts, or pump mechanisms for precise liquid delivery. Demand concentrates in Casablanca's expanding pharmaceutical cluster where contamination risk reduction drives specification for dropper closures calibrated to local bottling speeds.
- Flip-top Caps:Hinged single-piece designs enabling one-handed opening for sports and convenience beverage applications. Moroccan mineral water brands across the Casablanca-Rabat corridor specify these for premium positioning in retail channels.
- Snap-on Caps:Press-fit closures relying on interference fit rather than threading, common in food-industry applications where hermetic seal performance justifies polyethylene resin grades with cold-chain flexibility.
Screw caps sit at the top of the volume ranking, with dispensing caps climbing the fastest.
Material:
Raw material cost tiers separate premium certified streams from commodity grades, with REACH-aligned migration limits pushing converters toward documented virgin resin supply chains.
- Polypropylene:Semi-crystalline thermoplastic dominating beverage closure economics through density advantages and chemical resistance. Mutandis and ALPLA Group are retooling injection lines for thinner-wall dispensing formats while maintaining seal integrity under Casablanca's ambient temperature cycles.
- Polyethylene:Flexible polymer retaining margin strength in snap-on food packaging where hermetic performance and low-temperature ductility justify premium grades. Agadir-Tangier logistics corridors enable just-in-time delivery to processors serving Atlantic and Mediterranean coast bottlers.
- Polyester:Engineering resin selected for clarity and barrier properties in cosmetic and specialty pharmaceutical applications. Limited local compounding capacity extends lead times for color-masterbatch customization.
- PVC:Legacy material being displaced across beverage lines due to density penalties and regulatory pressure from EU REACH-aligned substance restrictions in Morocco's national standardization framework.
Polypropylene commands the largest volume position, while polyethylene maintains the most stable margin structure.
End User:
Customer consolidation patterns determine supplier negotiation leverage, with large bottlers unbundling closure procurement from preform contracts and compressing sourcing cycles.
- Beverage Industry:Mineral water bottlers in the Sidi Ali and Oulmès supply chains driving standard PCO thread profile demand. Three Casablanca-zone bottlers control two-thirds of national volume, forcing specialized converters to bid independently rather than through integrated preform-closure packages.
- Pharmaceutical Sector:Generic drug manufacturers requiring child-resistant certification for OTC and prescription packaging. Morocco's pharmaceutical regulator maintains limited testing laboratory capacity, creating qualification backlogs for novel tamper-evident designs.
- Food Industry:Processors specifying snap-on and screw formats for hermetic seal performance under cold-chain distribution. REACH-aligned food-contact mandates from the national standardization body enforce migration limits that push converters toward certified virgin resin documentation.
- Cosmetics Industry:Premium positioning brands demanding dispensing pumps and specialized orifice designs. Smaller order quantities relative to beverage volumes favor flexible tooling configurations over high-cavitation dedicated lines.
Beverage applications anchor volume scale, with pharmaceutical demand expanding most quickly.
Application:
Functional performance requirements stratify tooling investment intensity, with multi-cavity mold commissioning timelines stretching 12-18 months for high-speed beverage production.
- Packaging:Primary containment function across all end-use sectors, with thread finish compatibility determining bottle-closure system integration. All-electric injection molding with cavity-pressure monitoring is automating real-time defect rejection in high-volume Moroccan converter operations.
- Dispensing:Controlled flow and metered-dose functionality concentrated in pharmaceutical and cosmetic segments. Dropper closure specialization remains underpenetrated relative to regional demand growth, offering white space for torque-calibrated systems.
- Sealing:Hermetic integrity performance critical for food-industry cold-chain applications and carbonated beverage pressure retention. Seal liner composition specifications vary by contents chemistry and shelf-life requirements.
- Containment:Structural integrity under mechanical stress and temperature cycling, with polypropylene's crystalline structure outperforming polyethylene in Casablanca's ambient conditions.
Packaging dominates absolute volume, while dispensing applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Casablanca-Rabat anchors Morocco's plastic caps and closures demand through beverage bottler concentration and pharmaceutical packaging expansion. The analysis examines industrial clusters across five sub-regions where converter investment and regulatory enforcement shape competitive positioning.
Casablanca-Rabat Industrial Corridor
Mineral water bottlers Sidi Ali and Oulmès drive screw-cap procurement volumes for standard PCO thread profiles. The national standardization body enforces REACH-aligned food-contact migration limits that push converters toward certified virgin resin documentation. All-electric injection molding with cavity-pressure monitoring automates defect rejection in high-volume converter operations across Mohammedia and Ain Sebaâ zones.
Tangier Med Free Zone
Logistics infrastructure enables just-in-time closure delivery to Mediterranean coast bottlers and West African export channels. Free zone status attracts preform-to-closure integrated operations seeking tariff advantages for re-export. ALPLA Group extends its logistics model into this zone to serve Atlantic and Mediterranean distribution networks.
Agadir Port Zone
Atlantic coast mineral water processors specify flip-top and sports-cap formats for retail channel premium positioning. The zone's backward integration potential for resin compounding and color-masterbatch production compresses logistics costs. Captive supply infrastructure here targets West African market access.
Fez-Meknes Manufacturing Belt
Food-industry processors concentrate snap-on closure demand where hermetic seal performance justifies polyethylene resin grades with cold-chain flexibility. REACH-aligned mandates from the national standardization body enforce traceable resin documentation systems. Local converters serve dairy and condiment packaging lines with press-fit formats.
Marrakech-Safi Pharmaceutical Cluster
Generic drug manufacturers retrofit lines for child-resistant and tamper-evident screw caps serving francophone African export contracts. The country's pharmaceutical regulator maintains limited testing laboratory capacity, creating qualification backlogs for novel tamper-evident designs. Metered-dose dispensing formats remain underpenetrated relative to regional demand growth.
Morocco Plastic Caps and Closures Market Competitive Landscape
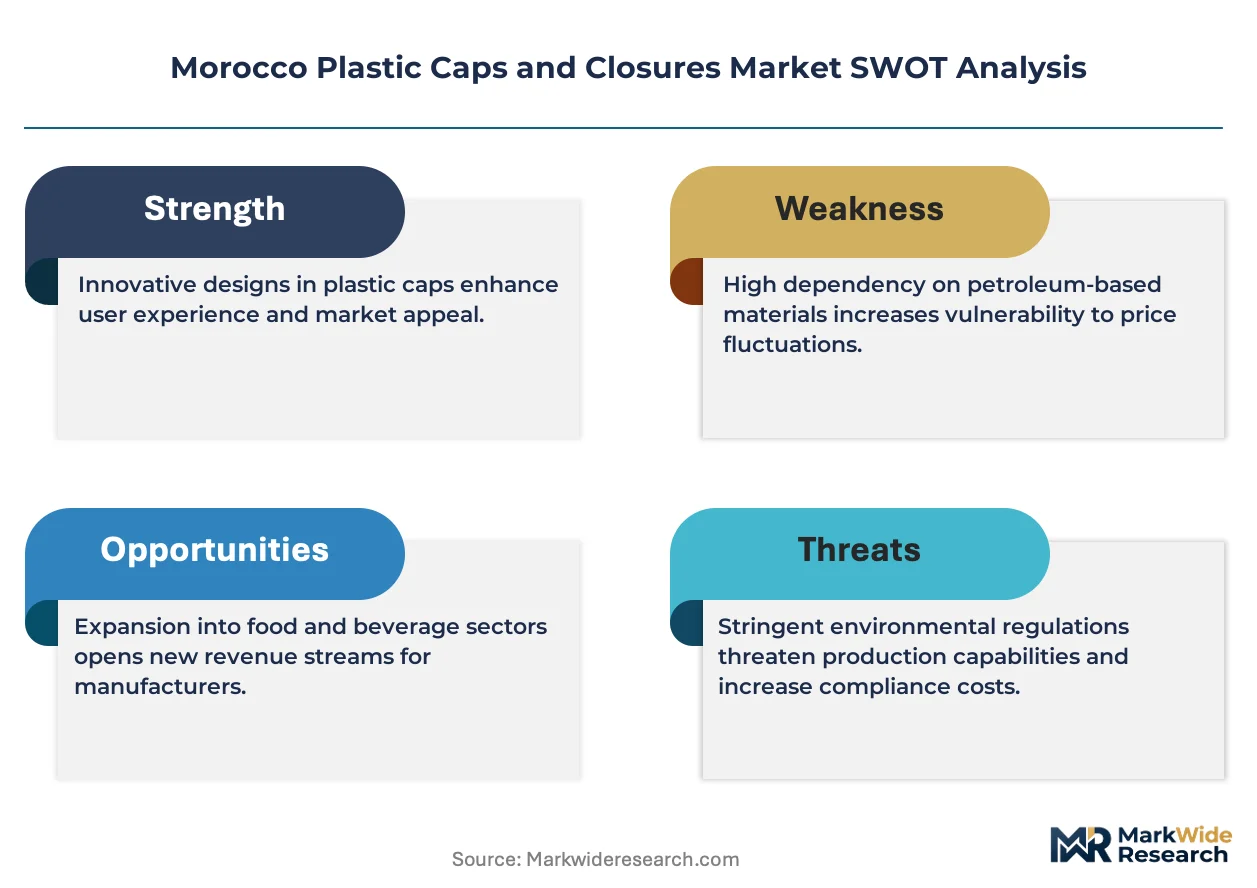
Global majors compete with regional champions across resin sourcing, tooling access, and regulatory certification capabilities. The market structure tiered: integrated packaging conglomerates with blow-molding and cap-making footprints, specialized European closure technologists with technical service centers, and domestic converters serving local food and beverage accounts. Three archetypes dominate: resin-integrated players controlling upstream polymer flows, equipment-linked specialists leveraging Sacmi molding technology, and logistics-optimizers exploiting free zone infrastructure. Competitive moves concentrate on capacity expansion in Tangier Med and Agadir zones, plus strategic partnerships with mineral water bottlers unbundling closure procurement from preform contracts.
Within the integrated packaging tier, Mutandis anchors Moroccan mineral water supply chains through combined blow-molding and cap-making operations. Among European-based closure technologists, Bericap Holding GmbH exemplifies the technical-service-center model calibrating dispensing-cap specifications for local bottling speeds. At the multinational logistics end, ALPLA Group occupies a position extending preform-to-closure systems into North African free zone operations. These three represent distinct competitive vectors: captive resin integration, application engineering depth, and geographic footprint expansion.
| Leading Market Players |
|---|
| Mutandis |
| Bericap Holding GmbH |
| ALPLA Group |
| Sacmi Imola S.C. |
| Tetra Pak International S.A. |
| Amcor Plc |
| Mondi Pap Sac Maghreb SA |
| Multisac SA |
| Afrimag Glue |
| Others |
Pricing and Supply Chain Analysis
Injection-molding technicians concentrated in the Casablanca-Rabat industrial corridor anchor Morocco's closure manufacturing labor pool, with skill premiums widening pricing spreads between certified pharmaceutical-grade suppliers and commodity beverage converters. Labor-cost differentials between this corridor and peripheral zones compress margin structures for standard PCO thread closures while sustaining premium tiers for child-resistant certification.
Pricing Analysis
Polypropylene resin cost pass-through dominates Morocco's closure pricing structure, with converters indexing contract terms to global propylene benchmarks. Three-tier pricing separates pharmaceutical-certified suppliers from standard beverage-grade producers and economy food-industry converters. Price differentiation hinges on migration-limit certification status and volume scale, with Sidi Ali and Oulmès bottlers extracting quarterly renegotiation leverage. Cost compression in beverage-grade polypropylene is intensifying because Moroccan resin production cannot meet packaging-grade specifications.
Supply Chain Analysis
Direct-to-bottler channels handle hyperscale mineral water demand across the Casablanca-Rabat corridor, while distributor networks serve fragmented food and cosmetics processors. Supply concentrates in Germany, Italy, and China for high-cavitation injection molds and virgin resin feedstock. Raw material dependencies center on Saudi and Qatari propylene derivatives, European color-masterbatch compounds, and Chinese tooling components. Single-source vulnerability from Sacmi equipment concentration extends mold commissioning timelines. Distribution runs through Tangier Med free zone infrastructure for West African re-export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's plastic caps and closures market functions as a stable compounder, with pharmaceutical export demand from Casablanca's generic drug cluster providing steady volume expansion.
For Market Incumbents: Lock in backward integration into resin compounding at Agadir port to defend margin position against propylene price volatility. Secure child-resistant certification capacity ahead of regulatory backlog expansion. Prioritize technical service center investment to capture unbundled closure procurement from preform-integrated bottlers. For New Entrants and Emerging Players: Launch via specialized dropper closure production targeting Marrakech-Safi's underpenetrated metered-dose pharmaceutical segment. Exploit certification queue delays by pre-positioning testing laboratory partnerships. White space concentrates in torque-calibrated dispensing systems for generic drug exporters. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic converters lacking REACH-aligned documentation systems. Long-term viability favors assets with captive recycling infrastructure ahead of extended producer responsibility mandates. Watch Tangier Med free zone capacity utilization as inflection signal for export channel health.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply at Agadir compresses logistics costs for West African export. |
| Child-Resistant Certification Investment | CDSCO-equivalent testing capacity addresses pharmaceutical regulator backlog constraints. |
| Free Zone Manufacturing Expansion | Tangier Med tariff advantages enable just-in-time delivery to Mediterranean bottlers. |
| Dropper Closure Specialization | Metered-dose formats serve underpenetrated Marrakech-Safi pharmaceutical demand. |
| Recycling Infrastructure Pre-Positioning | Extended producer responsibility readiness rewards Casablanca-Rabat corridor early movers. |
Research Methodology
Bottom-up beverage and pharmaceutical modeling reconciled against top-down resin import tracking forms the analytical core of this study. Primary interviews with injection-molding plant managers, mineral water procurement leads, pharmaceutical packaging engineers, and regulatory affairs specialists combined with secondary validation from Moroccan customs records, BSI-equivalent standardization filings, and CDSCO-equivalent regulatory disclosures. Triangulation across these sources calibrated volume estimates against propylene derivative import flows.
Historical trendline analysis of closure production volumes and resin consumption patterns established baseline growth trajectories across the projection horizon. The forecast framework segments by product type, material grade, end-use industry, and regional production cluster, with CAGRs derived from regression analysis against bottling line expansion and pharmaceutical export growth. Industry-specific inputs include PCO thread profile adoption rates and child-resistant certification queue dynamics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polypropylene price spike scenarios or accelerated extended producer responsibility implementation. Periodic stress-testing of base assumptions is recommended against regulatory laboratory capacity constraints and global propylene supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Buttress Closures Market
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
Global Aluminum Caps and Closures Market
Caps and Closures
Shrink Bands Market
Caps and Closures
Caps and Closures Market
Caps and Closures
Snap-On Closures Market
Caps and Closures
End Cap Market
Caps and Closures
Benelux Plastic Caps and Closures Market
Caps and Closures
Flapper Caps Market
Caps and Closures
Gamma Seal Lids Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Gable Top Cap and Closures Market