
 Screw Closure Market | 2026-2036
Screw Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Screw Closure Market Analysis
Pharmaceutical buyers is collapsing the historical beverage-centric demand mix for screw closures. Silgan Holdings Inc. leverages its metal closure infrastructure to serve regulated drug packaging channels. Berry Global Inc. competes through multi-material platforms that span child-resistant and standard formats. Amcor Plc anchors global supply with pharmaceutical-grade barrier technologies certified across FDA and EMA jurisdictions.
A screw closure is a threaded sealing device, typically injection-molded from polypropylene or compression-formed from aluminum, that creates a resealable hermetic seal through helical engagement with a container finish; its primary purpose is to preserve product integrity, enable controlled dispensing, and comply with tamper-evidence and child-safety mandates across liquid and semi-solid packaged goods. Plastic closures dominate volume due to cost scalability, yet aluminum variants command margin pools in premium spirits and pharmaceutical applications where oxygen ingress must stay below specified thresholds. Child-resistant caps represent the fastest-growing closure type as regulatory mandates expand beyond pharmaceuticals into cannabis and household chemical segments.
FDA 21 CFR requirements and EMA MDR standards dictate child-resistant performance testing, while EU REACH and F-Gas Regulation constrain material chemistry and volatile emissions in closure manufacturing. These frameworks elevate R&D spend on compliant resins and force smaller molders toward third-party certification or exit. Stakeholders must monitor evolving state-level cannabis packaging laws and bioplastics certification gaps to anticipate which material platforms will capture next-cycle specification wins.
Market Dynamics
Pharmaceutical serialization mandates and child-resistant certification requirements are compressing supplier margins while concentrating procurement among molders with dual FDA-EMA accreditation.
Growth Catalysts
- EMA MDR and FDA 21 CFR child-resistant standards:Regulatory harmonization across North America and Europe forces brand owners toward pre-certified closure suppliers, locking in multi-year supply agreements.
- India contract manufacturing expansion:CDSCO-compliant facilities serving generic drug exports generate sustained demand for aluminum and polypropylene closures with tamper-evident bands.
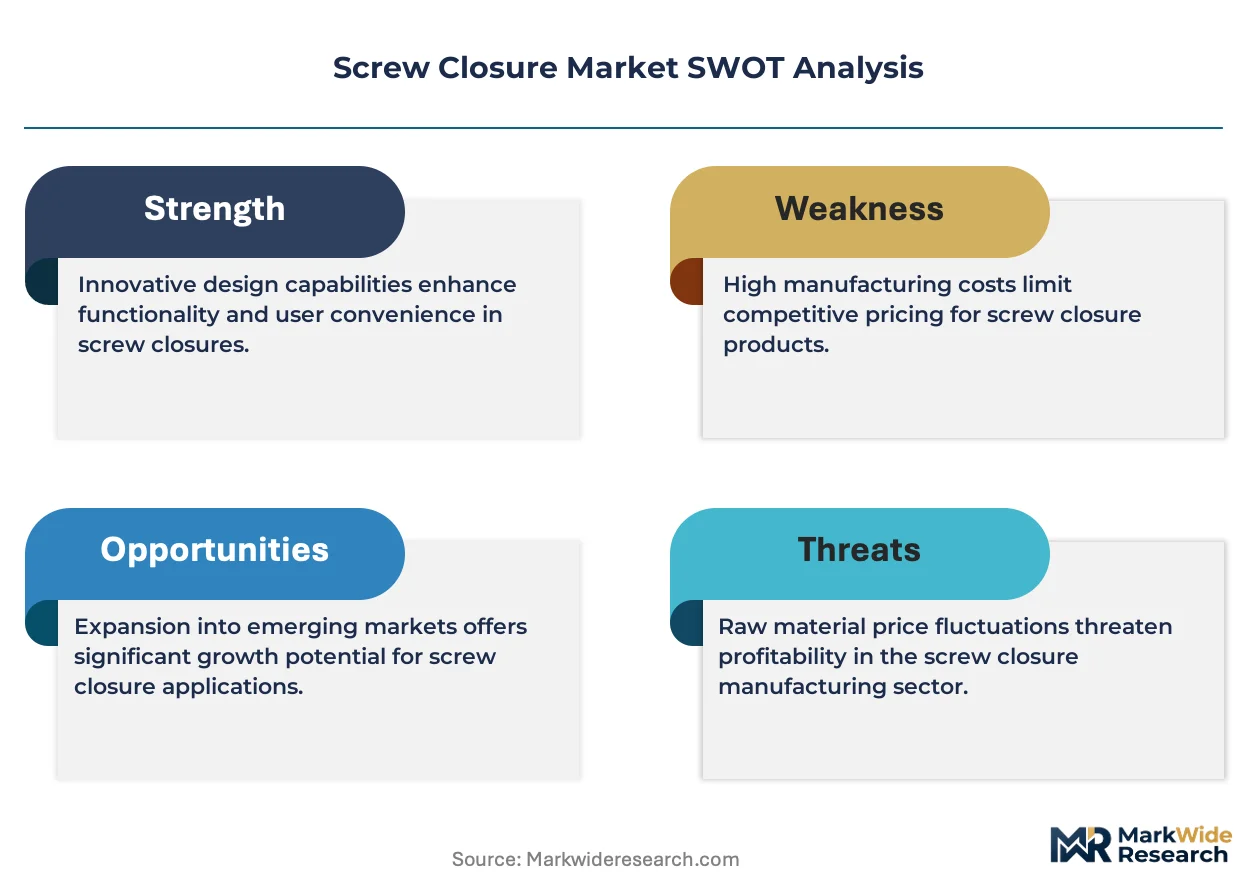
- Bioplastics certification pipelines:EU Green Deal procurement guidelines favor closures carrying OK Compost or DIN CERTCO labels, creating specification premiums for early resin adopters.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer prices track naphtha and natural gas liquid spreads, compressing margins for high-volume injection molders without backward integration into resin production.
- Aluminum supply concentration:Primary aluminum smelting concentrates in China and GCC states, exposing European closure manufacturers to carbon border adjustment mechanism exposure and freight cost spikes.
- Child-resistant testing bottlenecks:ISO 8317 and US 16 CFR 1700.20 protocol backlogs at third-party laboratories extend new product qualification timelines.
Strategic Opportunities
- US state-level cannabis packaging laws:California, Colorado, and Illinois mandate child-resistant exit packaging for recreational products, opening a parallel demand channel beyond pharmaceuticals.
- Smart closure integration:Near-field communication tags and time-temperature indicators converge with standard threaded formats, enabling unit-level traceability in cold-chain biologics.
- Direct-to-pharmacy distribution:Hospital and retail pharmacy consolidation creates volume aggregation points where closure suppliers can bypass traditional distributor markups.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, EMA, and Health Canada submissions require dedicated regulatory affairs capacity that mid-tier molders struggle to staff.
- Legacy equipment retrofit costs:Converting compression molding lines for tamper-evident band integration demands capital outlays that strain family-owned European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screw Closure Market |
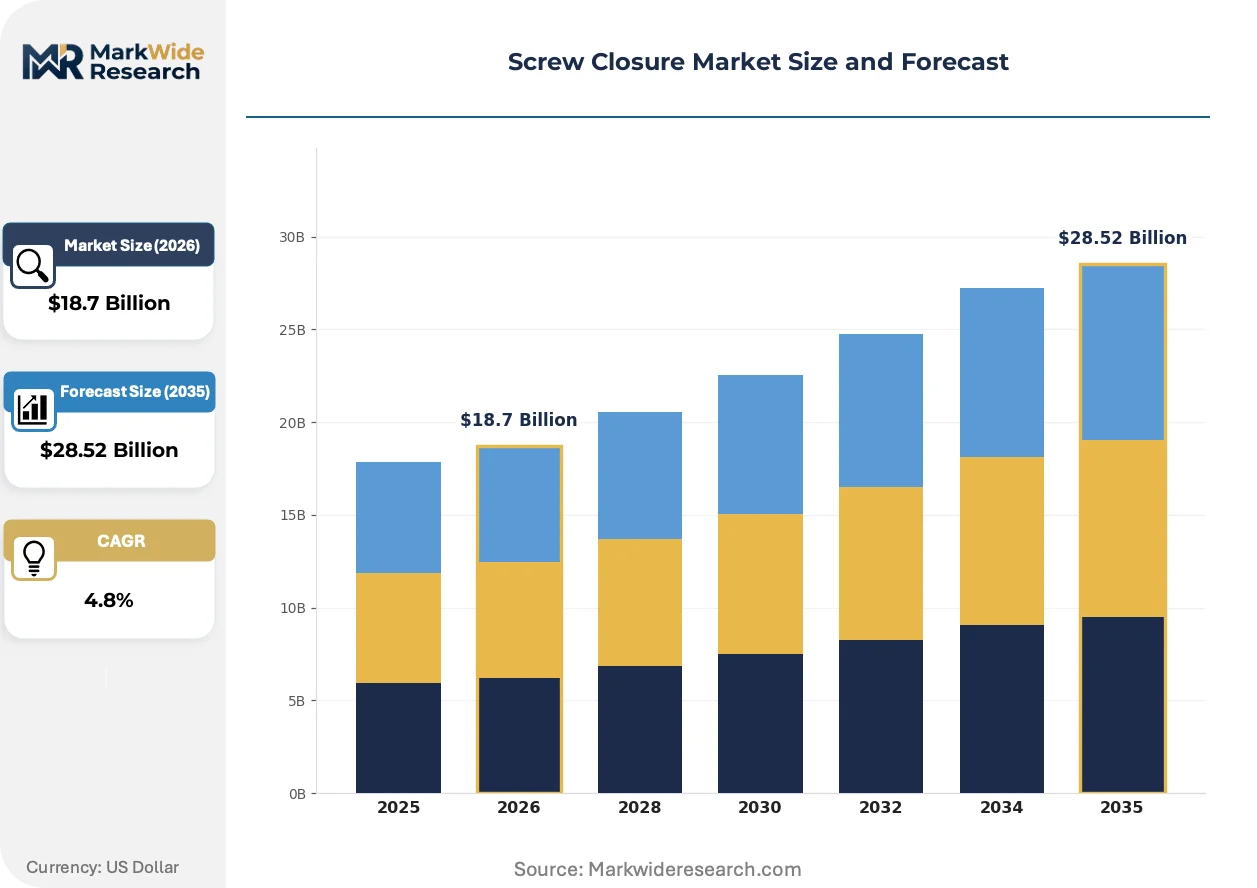
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Closure Type: Screw Cap, Twist Cap, Child-Resistant Cap, Sports Cap Material: Plastic, Metal, Glass, Aluminum End User: Beverage Industry, Pharmaceuticals, Food Packaging, Cosmetics Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Shops |
| Companies Covered | Silgan Holdings Inc., Berry Global Inc., Amcor Plc, AptarGroup Inc., Closure Systems International, Crown Holdings Inc., BERICAP GmbH, Guala Closures Group, Tecnocap Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screw Closure Market Emerging Trajectories
Material science advances and regulatory digitization are compressing product development cycles while fragmenting specification authority across brand owners, contract packagers, and retail pharmacies.
Mono-material polypropylene closures with integrated induction seals are displacing multi-component designs in oral solid dose packaging. Large pharmaceutical contract manufacturers in Germany and the Netherlands specify these formats to streamline recycling compliance under EU Packaging and Packaging Waste Regulation. The shift compresses tooling complexity and reduces assembly station count on high-speed capping lines.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of lubricant additives used in high-torque child-resistant mechanisms. European closure suppliers must validate alternative slip agents without compromising US 16 CFR 1700.20 torque compliance. The regulatory friction most acutely affects suppliers serving dual-continent generic drug portfolios.
Hospital system procurement consortia now specify annual total-cost-of-ownership metrics rather than unit price, bundling closure supply with line efficiency guarantees and inventory holding commitments. This behavior concentrates volume among suppliers with regional warehouse networks and compresses spot-market opportunities. The pattern is most visible in US integrated delivery networks and German hospital purchasing cooperatives.
Screw Closure Market Segmentation
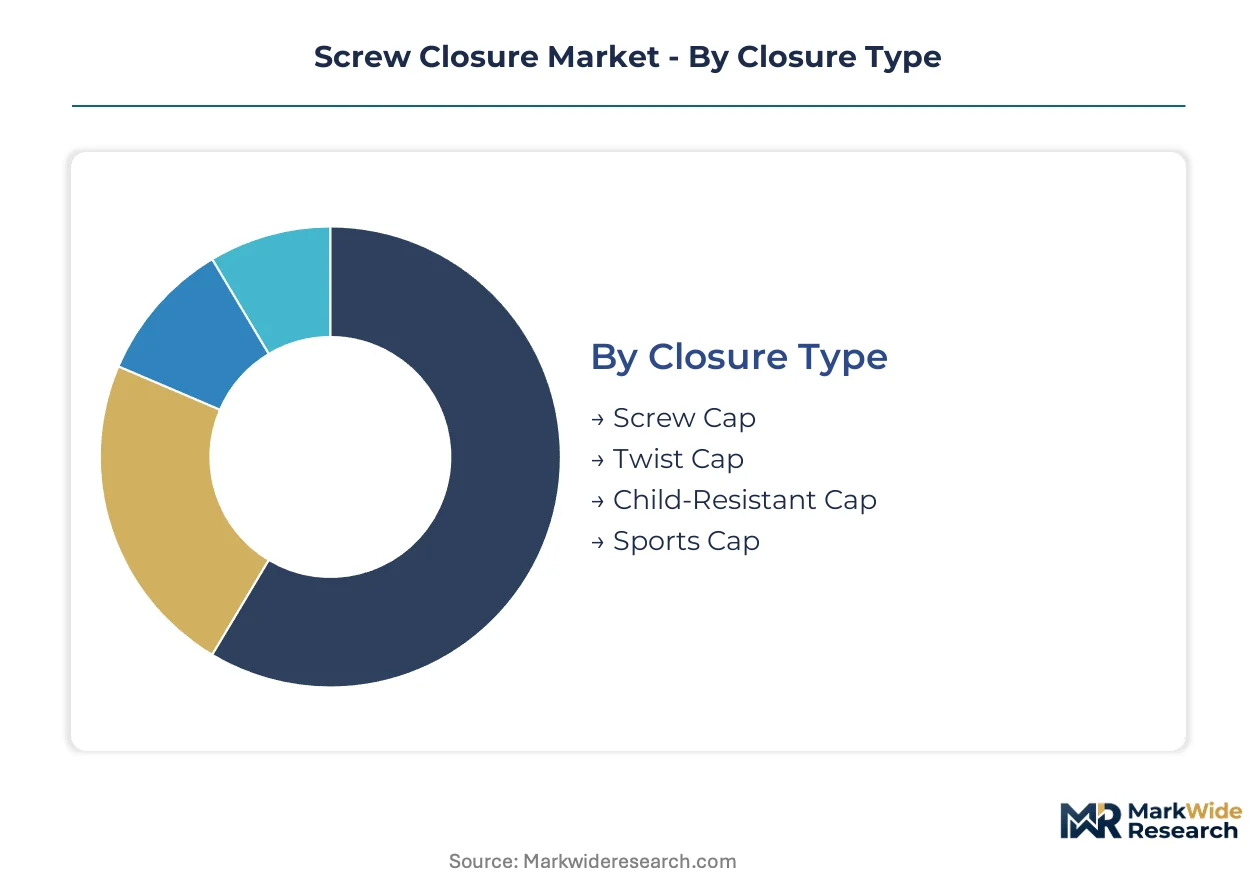
Screw closure procurement patterns diverge sharply across material platforms and regulatory exposure levels. Brand owners segment supplier selection by certification tier, torque performance, and compatibility with automated capping lines.
Closure Type:
FDA 21 CFR and EMA MDR child-resistant testing protocols create tiered supplier qualification barriers that segment procurement pools by certification depth.
- Screw Cap:Standard helical-thread polypropylene designs dominate beverage and food volumes. European bottlers specify DIN 168 GL finish compatibility to ensure interchangeability across filling lines.
- Twist Cap:Partial-turn aluminum formats with breakaway bands serve premium spirits where tamper evidence mandates visual confirmation. Scotland and Kentucky distilleries specify torque ranges that prevent over-tightening on automated corkers.
- Child-Resistant Cap:Push-and-turn mechanisms with dual-action torque requirements represent the steepest expansion trajectory as US state cannabis laws and pharmaceutical serialization tighten packaging mandates. California and Colorado dispensaries now require ISO 8317-certified exit packaging.
- Sports Cap:Flip-top threaded designs with silicone valves target functional hydration bottles. German fitness brands specify dishwasher-cycle durability testing beyond standard closure protocols.
Established volume favors screw caps; emerging adoption favors child-resistant formats.
Material:
Cost tier stratification separates commodity resin supply from premium metal specifications with barrier-grade performance.
- Plastic:Polypropylene homopolymer and copolymer grades offer injection molding scalability at the lowest unit cost. Indian generic pharmaceutical exporters specify CDSCO-compliant plastic closures to meet export documentation requirements.
- Metal:Tinplate and steel closures with compound gaskets serve pasteurized food jars. Italian tomato processor cooperatives specify metal formats for thermal processing compatibility.
- Glass:Ground glass stoppers with threaded collars persist in laboratory chemical packaging where solvent resistance exceeds polymer limits. German industrial chemical distributors maintain glass closure specifications for reactive compounds.
- Aluminum:Compression-formed shells with rolled threads command specification premiums in oxygen-sensitive pharmaceuticals. Swissmedic-certified facilities specify aluminum variants for drug stability protocols.
Plastic captures volume scale; aluminum captures margin premiums.
End User:
Application-specific torque and barrier requirements segment supplier capabilities by sterilization tolerance and cleanroom certification.
- Beverage Industry:Carbonated soft drink and bottled water volumes drive polypropylene screw cap consumption at the highest production speeds. Coca-Cola and PepsiCo bottling systems specify ROPP (roll-on pilfer-proof) aluminum for premium segments.
- Pharmaceuticals:Oral solid dose and liquid prescription packaging demands child-resistant certification and tamper-evident band integration. CDSCO-registered contract manufacturers in Hyderabad and Ahmedabad source closures with dual FDA-EMA dossier support.
- Food Packaging:Retort-pouch and glass jar applications specify heat-resistant polypropylene or metal closures with vacuum seal indicators. Netherlands-based sauce manufacturers specify closures compatible with 121°C sterilization cycles.
- Cosmetics:Skincare and fragrance brands specify aluminum or heavyweight plastic with metallized finishes for shelf differentiation. French luxury houses source custom-color anodized aluminum from Italian closure specialists.
Pharmaceuticals concentrate specification authority; food packaging concentrates unit volume.
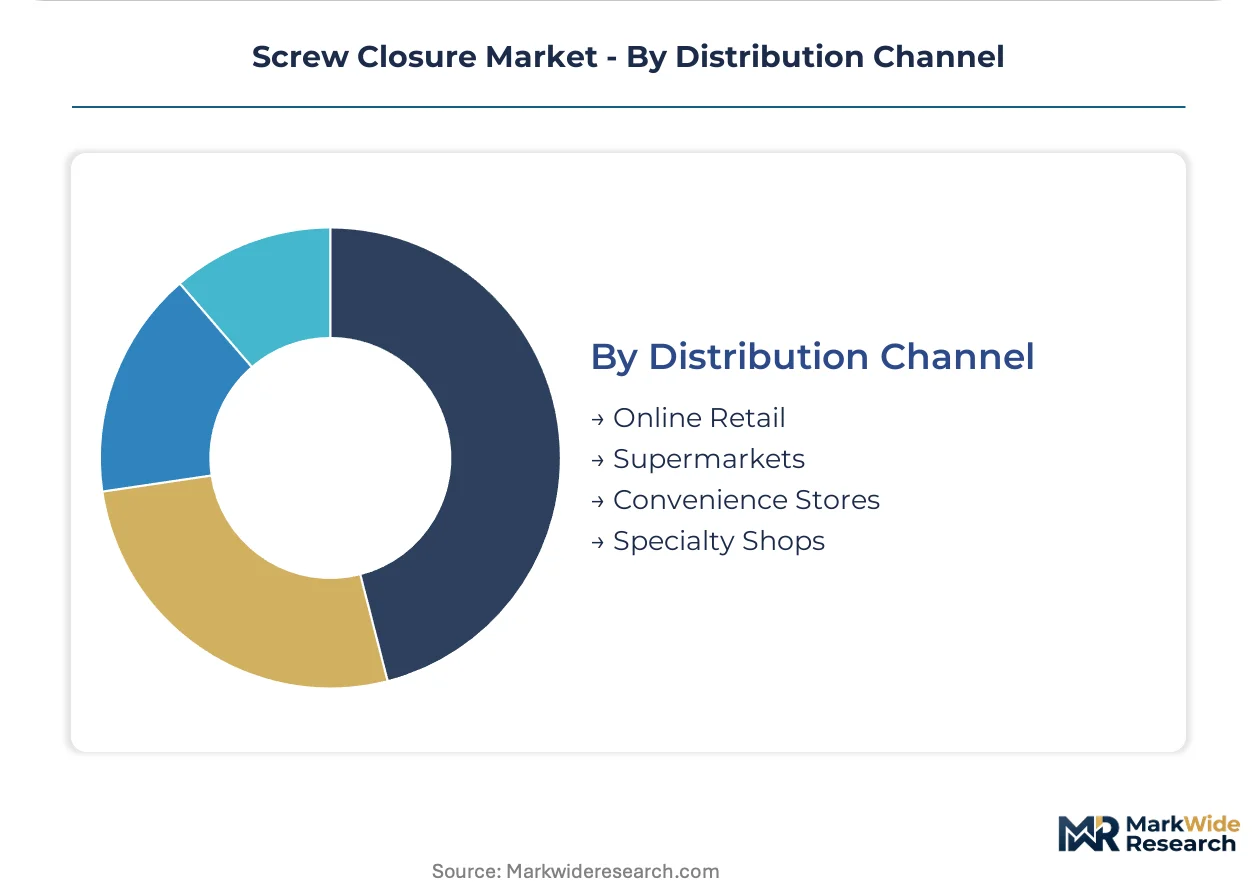
Distribution Channel:
Customer type and order fragmentation patterns segment fulfillment models between bulk contract supply and SKU-intensive retail service.
- Online Retail:Direct-to-consumer supplement and cosmetic brands require small-lot customization with rapid tooling changeover. Amazon-native brands specify closures with printed lot codes for traceability compliance.
- Supermarkets:Private-label beverage and food volumes drive high-volume, long-run contracts with minimal SKU variation. Tesco and Carrefour procurement teams specify standardized neck finishes across supplier portfolios.
- Convenience Stores:Single-serve and impulse-format packaging favors lightweight plastic closures with theft-deterrent tethering. 7-Eleven Japan specifies closures compatible with vending machine dispensing mechanics.
- Specialty Shops:Craft spirits, organic cosmetics, and premium food segments specify custom-color and embossed closures at lower volumes. Brooklyn and Portland craft distilleries source wax-dipped aluminum closures for aesthetic differentiation.
Supermarkets anchor contract manufacturing volumes; specialty shops drive margin through customization premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports screw closures to North American and European pharmaceutical markets, with Hyderabad and Ahmedabad contract manufacturers driving CDSCO-compliant production for generic drug packaging. This trade corridor concentrates specification authority in FDA-EMA dual-certified suppliers.
United States
California and Colorado dispensaries enforce ISO 8317 child-resistant exit packaging for recreational cannabis, expanding demand beyond traditional pharmaceuticals. FDA 21 CFR testing protocols dominate supplier qualification. Kentucky distilleries specify torque-calibrated aluminum closures for premium spirits automation.
Germany
Netherlands-based sauce manufacturers source heat-resistant polypropylene closures through German distributors, while hospital purchasing cooperatives in North Rhine-Westphalia bundle closure supply with inventory guarantees. EU REACH Annex XVII restrictions on PFAS lubricants force additive reformulation. Stuttgart-area molders validate alternative slip agents for dual-continent generic portfolios.
India
Hyderabad and Ahmedabad CDSCO-registered facilities generate sustained demand for aluminum and polypropylene closures with tamper-evident bands serving export markets. PLI scheme incentives support pharmaceutical packaging infrastructure expansion. Gujarat-based contract manufacturers anchor generic drug supply chains to Africa and Latin America.
Switzerland
Swissmedic-certified pharmaceutical facilities specify aluminum variants for oxygen-sensitive drug stability protocols, commanding specification premiums over standard plastic formats. Basel-area packaging clusters source compression-formed closures with sub-threshold oxygen ingress ratings. Domestic suppliers maintain captive relationships with precision drug manufacturers.
China
Primary aluminum smelting concentration exposes European closure manufacturers to carbon border adjustment mechanism exposure and freight volatility. Zhejiang and Jiangsu injection molders supply polypropylene screw caps to Southeast Asian beverage bottlers. NMPA regulatory alignment efforts support domestic pharmaceutical packaging certification pipelines.
Screw Closure Market Vendor Landscape
Player mix skews toward diversified packaging conglomerates with multi-material platforms and specialized closure manufacturers with regulatory certification depth. The market structure concentrates procurement among molders holding dual FDA-EMA accreditation, compressing margins for uncertified competitors. Two strategic archetypes dominate: integrated packaging groups leveraging beverage infrastructure for pharmaceutical crossover, and pure-play closure specialists with child-resistant testing capabilities. Competitive moves center on M&A for certification portfolio expansion and strategic partnerships with contract drug manufacturers.
Within the integrated packaging tier, Silgan Holdings Inc., Berry Global Inc., and Amcor Plc exemplify multi-material platform strategies spanning child-resistant and standard closure formats. Silgan leverages metal closure infrastructure for regulated channels. Berry competes through polypropylene scalability with tamper-evident integration. Amcor anchors global supply with pharmaceutical-grade barrier technologies. These three represent the certification-heavy end of supplier qualification, where regulatory dossier depth determines procurement access.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Berry Global Inc. |
| Amcor Plc |
| AptarGroup Inc. |
| Closure Systems International |
| Crown Holdings Inc. |
| BERICAP GmbH |
| Guala Closures Group |
| Tecnocap Group |
| Others |
Supply Flow & Price Mechanics
Sixty-day inventory cycles for polypropylene resin stockpiles concentrate pricing leverage among backward-integrated molders in India and China, compressing margins for European converters exposed to spot-market propylene volatility. This lead-time asymmetry separates suppliers who captive-source resin from those absorbing feedstock price swings through quarterly contract renegotiations.
Pricing Analysis
Current-generation child-resistant aluminum closures command specification premiums over prior-generation standard polypropylene screw caps, while next-generation smart closures with integrated NFC tags remain pre-commercial. Three-tier pricing structure across premium, standard, and economy levels separates FDA-EMA dual-certified aluminum formats from CDSCO-compliant plastic variants and uncertified commodity caps. Pricing pressure stems from polypropylene feedstock volatility tracking naphtha spreads, with cost compression running through high-volume beverage-grade injection molders lacking resin integration. Generic pharmaceutical exporters in India exhibit highest price sensitivity; Swissmedic-certified facilities show lowest sensitivity due to stability-protocol requirements.
Supply Chain Analysis
Gulf of Aden transit exposure for aluminum ingot shipments from GCC smelters elevates freight cost volatility for European compression-forming specialists. Primary aluminum supply concentrates in China and GCC states, while polypropylene resin production clusters in China, South Korea, and India. Raw material dependencies span propylene monomer, primary aluminum ingot, and PFAS-free lubricant additives. Single-source vulnerability from Chinese aluminum smelting concentration exposes EU manufacturers to carbon border adjustment mechanism compliance costs. Distribution runs through pharmaceutical contract manufacturing clusters in Hyderabad, Ahmedabad, and Basel with direct-to-facility delivery contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Child-resistant certification testing services and inventory-holding guarantees now expand faster than closure hardware sales, converting supplier relationships into recurring-revenue partnerships. This service-attach dynamic repositions molders as packaging compliance partners rather than component vendors.
For Market Incumbents: Compound regulatory dossier depth through simultaneous FDA, EMA, and Health Canada submission capacity to lock in multi-year supply agreements with contract drug manufacturers. Defend margin position by acquiring third-party testing laboratories bottlenecked on ISO 8317 protocol backlogs, securing child-resistant certification throughput that rivals cannot replicate. Prioritize aluminum compression-forming capacity in Gujarat to serve CDSCO-registered exporters with localized production and reduced freight exposure. For New Entrants and Emerging Players: CDSCO fast-track registration for pharmaceutical packaging components opens procurement access to Hyderabad and Ahmedabad contract manufacturers serving African and Latin American generic drug markets. Target US state-level cannabis packaging compliance as the most penetrable white-space channel, where California and Colorado dispensaries mandate ISO 8317-certified exit packaging without incumbent supplier lock-in. Pursue co-development partnerships with Amazon-native supplement brands requiring small-lot customization with printed lot codes for traceability compliance. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates divesting non-core closure divisions to focus on flexible film and rigid container platforms. Mid-tier European molders with EMA MDR certification but lacking FDA accreditation present acquisition opportunities for buyers seeking dual-jurisdiction qualification portfolios. Long-term viability hinges on bioplastics certification pipeline positioning; the signal to watch is OK Compost or DIN CERTCO label adoption rates among German pharmaceutical contract manufacturers bundling sustainability metrics into procurement scorecards.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Jurisdiction Certification Investment | FDA-EMA dossier depth locks in multi-year supply agreements with contract drug manufacturers. |
| Backward Integration into Resin Production | Captive polypropylene supply insulates margins from naphtha-driven feedstock volatility. |
| Smart Closure Technology Development | NFC tag integration enables unit-level traceability for cold-chain biologics distribution. |
| Regional Warehouse Network Expansion | Inventory holding commitments satisfy hospital purchasing cooperative total-cost-of-ownership metrics. |
| PFAS-Free Additive Reformulation | REACH Annex XVII compliance preserves access to EU pharmaceutical packaging procurement pools. |
Methodological Framework
Desk research of FDA 21 CFR guidance documents, EMA MDR technical specifications, and CDSCO packaging compliance circulars preceded structured interviews with regulatory affairs directors at pharmaceutical contract manufacturers, procurement leads at hospital purchasing cooperatives, and plant managers at Indian and Chinese injection molding facilities. Primary fieldwork combined with secondary validation against customs trade data, SEC filings of listed packaging conglomerates, and EU Packaging and Packaging Waste Regulation impact assessments. Bottom-up volume estimates from individual facility capacities triangulated against top-down market sizing from end-use consumption patterns.
Variance decomposition across material platforms, closure types, and regulatory certification tiers shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include child-resistant versus standard formats, aluminum versus polypropylene material grades, pharmaceutical versus beverage end-use applications, and dual-certified versus single-jurisdiction supplier status. CAGRs derived from slope-log regression of historical volume trends adjusted for regulatory mandate implementation timelines. Industry-specific forecast inputs encompassed CDSCO registration pipeline data and US state-level cannabis packaging law enactment schedules.
Decision-makers should treat outputs as directional under assumptions of sustained EMA-FDA regulatory harmonization and stable propylene-naphtha crack spreads; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU carbon border adjustment mechanism implementation and bioplastics certification standard evolution reshape supplier qualification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Child Resistant Pipette Closures Market
Caps and Closures
PET Dome Lids Market
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Aerosol Caps Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Vented Caps Market
Caps and Closures
Reverse Cap Bottles Market
Caps and Closures
Fez Caps Market
Caps and Closures
Lug Caps Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Cap Liner Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Hinged Dispensing Caps Market
Caps and Closures
Dispensing Spouts Market