
 End Cap Market | 2026-2036
End Cap Market Size, Share, and Industry Trends Forecast 2026-2036
End Cap Market Insights
Wholesale distribution channels for pipe fittings is narrowing as manufacturers build direct-to-contractor digital platforms. Charlotte Pipe and Foundry Company leverages its foundry network to sustain domestic casting capacity. JM Eagle anchors the plastic end cap segment with integrated resin-to-fitting production. Spears Manufacturing Company specializes in chemically resistant formulations for aggressive fluid handling.
An end cap is a terminal fitting that seals the end of a pipe, tube, or vessel, typically manufactured through injection molding, die casting, or CNC machining to achieve pressure ratings and dimensional tolerances specified by ANSI or DIN standards. Its primary purpose is to terminate flow paths while containing internal pressure and preventing contamination ingress. Plastic end caps dominate volume in residential plumbing and drainage applications where cost sensitivity and corrosion immunity outweigh thermal limits. Stainless steel variants command premium positioning in pharmaceutical and food-grade installations where surface finish and cleanability standards apply. Press-fit installation types gain traction in commercial HVAC and fire suppression systems where flame-free assembly reduces labor certification burdens and insurance liabilities.
The US EPA regulates leachate thresholds in potable water applications through Safe Drinking Water Act provisions, while OSHA mandates pressure testing protocols for industrial piping assemblies. The EU REACH framework restricts phthalate plasticizers in PVC compounds, forcing reformulation across European supply chains. Stakeholders must monitor evolving PFAS restrictions in fluoropolymer liners and assess adhesive bonded alternatives before compliance deadlines tighten material qualification windows.
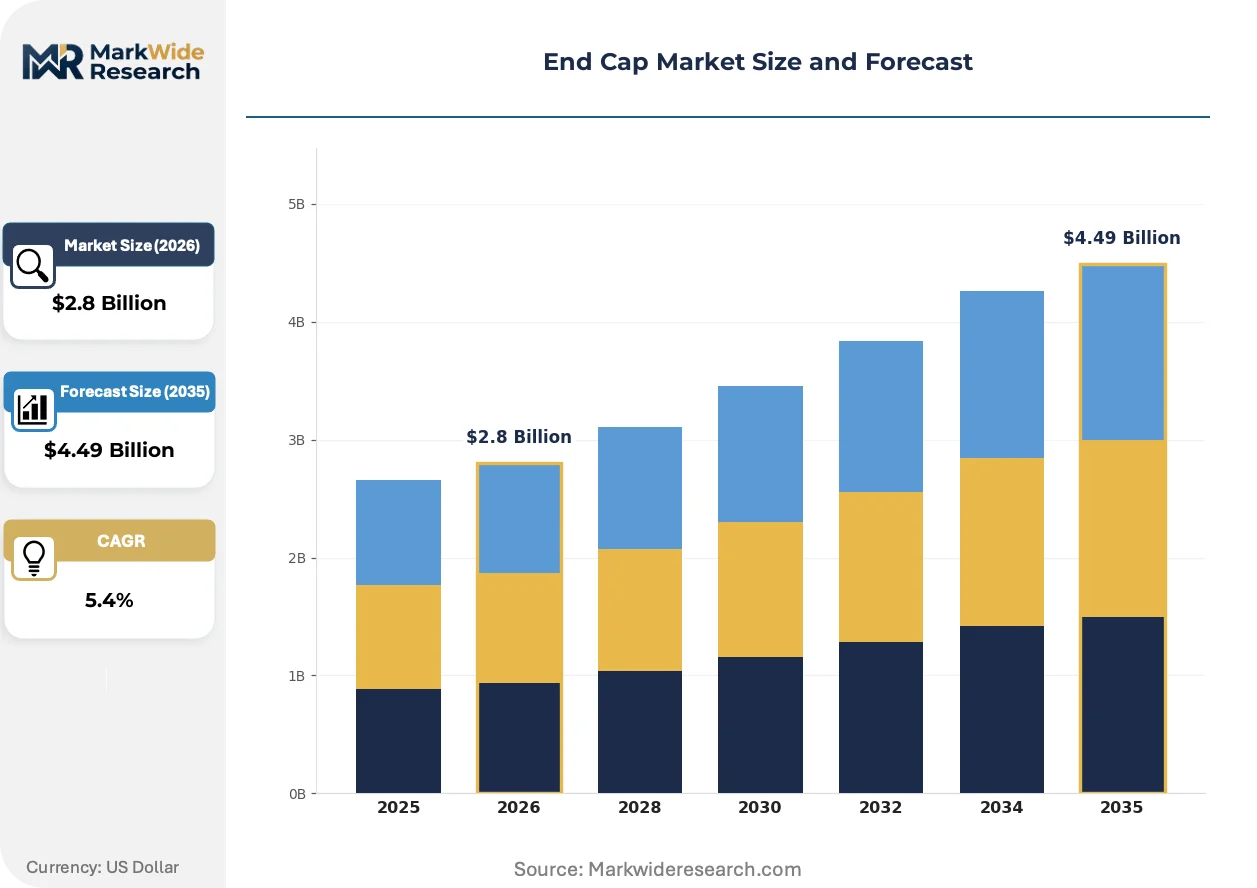
Market Dynamics
Corrosion-resistant polymer formulations are displacing metallic end caps in chemical processing infrastructure as facilities face accelerated replacement cycles driven by EPA and OSHA pressure-leak compliance deadlines.
Growth Catalysts
- REACH phthalate restrictions:EU REACH mandates on PVC plasticizers force reformulation investments that favor specialized compounders with captive polymer science capabilities.
- Flame-free assembly protocols:Press-fit end cap technologies eliminate hot-work permits in commercial HVAC and fire suppression installations, compressing project timelines for mechanical contractors.
- German industrial HVAC retrofit density:Accelerated building energy efficiency mandates in Germany concentrate replacement demand for terminal fittings in aging hydronic distribution networks.
Market Restraints
- Resin price volatility:PVC and polypropylene feedstock costs fluctuate with crude oil indices, compressing margins for injection molders without resin hedging programs.
- Fluoropolymer liner dependency:PFAS restrictions threaten availability of chemically inert PTFE-lined caps for aggressive fluid handling, forcing qualification of adhesive-bonded alternatives.
- Domestic foundry capacity scarcity:Stainless steel casting for high-pressure applications concentrates among limited North American suppliers, extending lead times for ANSI-rated metallic end caps.
Strategic Opportunities
- Direct-to-contractor digital platforms:Manufacturers bypass wholesale distributors by building proprietary e-procurement portals for mechanical contractors with project-based volume pricing.
- Pharmaceutical surface finish standards:Electropolished 316L stainless caps for bioprocessing skid manufacturers command premium positioning as cleanability specifications tighten.
- EU Green Deal embodied carbon tracking:Recycled-content and bio-based polymer caps gain specification preference as EPD documentation becomes mandatory for public infrastructure tenders.
Industry Challenges
- Multi-standard certification complexity:Manufacturers must maintain parallel ANSI, DIN, and JIS dimensional tolerances and pressure ratings to serve fragmented national specification regimes.
- PFAS qualification timeline compression:Accelerating state-level bans on fluorinated compounds in the US force rapid material revalidation before federal alignment eliminates grandfathering provisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | End Cap Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Aluminum, Stainless Steel, Rubber, Composite Application: Piping Systems, Containers, Automotive Assembly, Electrical Enclosures, HVAC Units End User: Construction Firms, Manufacturing Plants, Chemical Processing Units, Packaging Companies Installation Type: Welded, Threaded, Press-Fit, Flanged, Adhesive Bonded |
| Companies Covered | Charlotte Pipe and Foundry Company, NIBCO Inc., LASCO Fittings, Inc., GF Piping Systems, Supreme Industries, Wavin Group, Aliaxis Group, JM Eagle, Spears Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
End Cap Market Trends and Innovations
Material science advances and installation method evolution are compressing traditional product lifecycles while regulatory chemistry restrictions force supply chain reconfiguration across polymer categories.
Glass-reinforced polypropylene compounds with enhanced creep resistance are rendering obsolete cast iron terminal fittings in below-grade drainage applications. Municipal sewer authorities in the US Southeast specify these thermoplastic alternatives for corrosion immunity in aggressive soil conditions. The shift eliminates foundry sourcing dependencies while reducing freight costs through lower unit weights.
OSHA's updated Process Safety Management enforcement memoranda mandate documented pressure testing protocols for industrial piping terminations. Chemical processors must maintain traceable inspection records for end cap installations in hazardous service. Facilities in the Texas and Louisiana Gulf Coast petrochemical corridor invest in RFID-tagged fitting inventories to satisfy audit requirements.
Mechanical contractors increasingly bundle end cap procurement into integrated piping system packages rather than sourcing fittings as standalone commodities. Distributors respond by expanding fabrication services and kitting operations to capture value previously retained by specialized subcontractors. This consolidation concentrates purchasing influence among regional HVAC and plumbing wholesalers with in-house bending and threading capabilities.
End Cap Market Segmentation
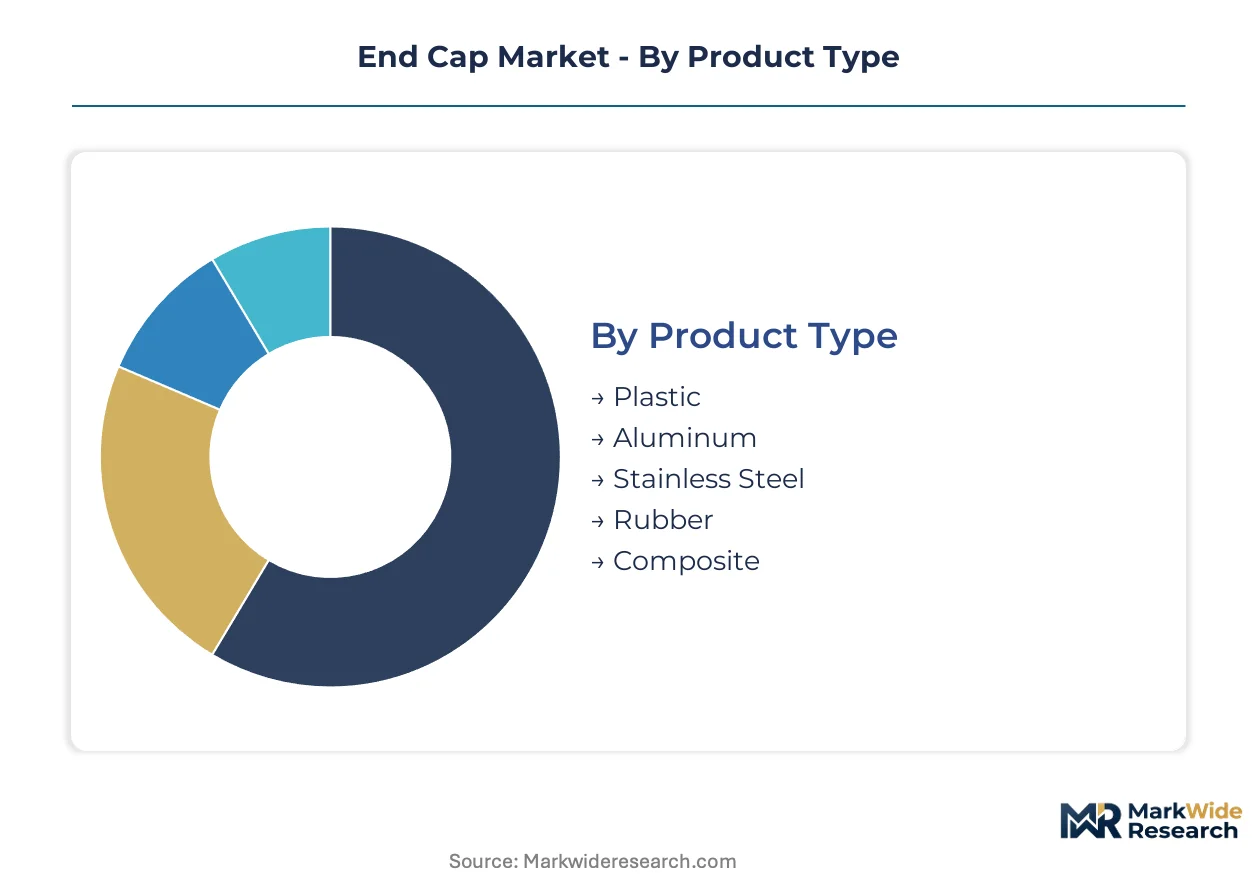
End cap specifications vary sharply across pressure ratings, chemical exposure profiles, and assembly protocols. Segmentation reveals where material science investments concentrate and which installation methods are displacing legacy approaches.
Product Type:
Mature metallic formulations coexist with emerging polymer composites as chemical resistance requirements intensify.
- Plastic:Injection-molded PVC and polypropylene variants dominate residential plumbing and drainage where corrosion immunity outweighs thermal limitations. Municipal sewer authorities in the US Southeast specify glass-reinforced compounds for aggressive soil conditions.
- Stainless Steel:Electropolished 316L grades command premium positioning in pharmaceutical bioprocessing skids where surface finish and cleanability standards apply. FDA validation protocols extend qualification timelines for new suppliers.
- Aluminum:Lightweight die-cast variants serve aerospace and transportation applications requiring strength-to-weight optimization.
- Rubber:Molded elastomer caps seal temporary pipe terminations during construction and hydrostatic testing phases.
- Composite:Fiber-reinforced polymer matrices gain traction in offshore oil and gas infrastructure where galvanic corrosion eliminates metallic options.
Plastic handles the majority of throughput; composite is expanding most quickly on share as offshore project specifications tighten.
Application:
Volume concentrates in fluid handling infrastructure while emerging electrical and thermal applications reshape specification requirements.
- Piping Systems:Terminal fittings seal process lines across water distribution, chemical transfer, and hydrocarbon transport networks. EPA Safe Drinking Water Act leachate thresholds govern material selection for potable service.
- HVAC Units:Press-fit end caps terminate hydronic distribution loops in commercial building retrofits. German industrial energy efficiency mandates accelerate replacement cycles in aging district heating networks.
- Containers:Drum and tank closures contain hazardous materials during storage and transport. UN certification requirements dictate pressure testing documentation.
- Automotive Assembly:Fuel line and brake system terminations demand vibration-resistant sealing under thermal cycling conditions.
- Electrical Enclosures:Cable entry sealing prevents moisture ingress in outdoor switchgear and renewable energy installations.
Piping systems absorb the dominant share of procurement volume; HVAC applications are climbing the fastest as building efficiency mandates proliferate.
End User:
Procurement authority fragments between project-based contractors and asset-owning industrial operators with divergent specification priorities.
- Chemical Processing Units:Aggressive fluid handling drives demand for fluoropolymer-lined and specialty alloy caps. OSHA Process Safety Management mandates pressure testing documentation for hazardous service installations.
- Construction Firms:Residential and commercial builders prioritize cost-efficient plastic fittings with rapid availability through distributor stock programs.
- Manufacturing Plants:General industrial facilities specify standard-pressure metallic caps for compressed air and utility piping.
- Packaging Companies:Drum and container sealing applications require UN-certified closures for hazardous material compliance.
Chemical processing units drive the steepest specification escalation; construction firms remain the volume anchor through project-based procurement.
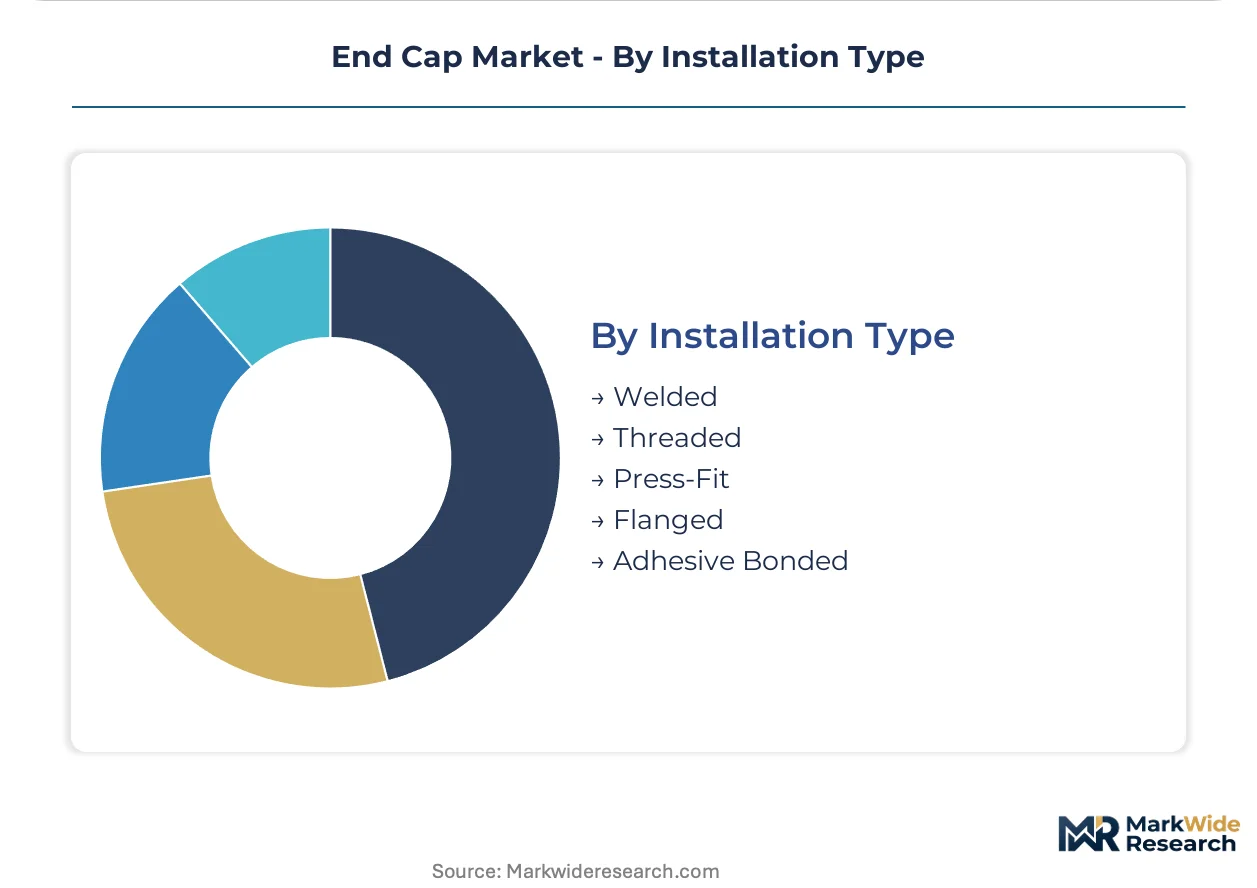
Installation Type:
Assembly method selection hinges on labor certification requirements, insurance liability exposure, and field modification flexibility.
- Press-Fit:Mechanical pressing tools create flame-free joints in commercial HVAC and fire suppression systems. Elimination of hot-work permits compresses project timelines and reduces contractor insurance burdens.
- Threaded:Tapered NPT and parallel BSP connections dominate maintenance-accessible applications requiring future disassembly capability.
- Welded:Socket and butt-weld terminations serve high-pressure process piping where leak integrity is paramount.
- Flanged:Bolted connections facilitate equipment isolation and inspection access in chemical processing skids.
- Adhesive Bonded:Structural epoxy systems replace PTFE-lined caps as PFAS restrictions threaten fluoropolymer availability.
Threaded installation retains the largest installed base; press-fit is gaining share fastest as flame-free protocols spread across mechanical contractor specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel petrochemical corridor anchors North American demand for corrosion-resistant terminal fittings as Gulf Coast processors upgrade pressure-leak containment systems ahead of EPA enforcement deadlines.
United States
Chemical processing clusters along the Texas and Louisiana Gulf Coast drive specification escalation for fluoropolymer-lined caps. OSHA's Process Safety Management enforcement memoranda mandate documented pressure testing protocols for hazardous service installations. Facilities in the Houston-Baytown-Beaumont corridor invest in RFID-tagged fitting inventories to satisfy audit requirements.
Germany
Industrial HVAC retrofit cycles accelerate under building energy efficiency mandates, concentrating replacement demand for press-fit terminal fittings in aging district heating networks. EU REACH phthalate restrictions on PVC plasticizers force reformulation investments that favor specialized compounders with captive polymer science capabilities. The Ruhr industrial basin and Bavarian manufacturing belt lead procurement volume for corrosion-resistant piping infrastructure.
China
Municipal water infrastructure expansion and chemical processing capacity additions drive injection-molded plastic end cap consumption. The country's national environmental regulator tightens leachate thresholds for potable water applications, aligning with international standards. Yangtze River Delta manufacturing clusters prioritize cost-efficient domestic supply chains for standard-pressure drainage applications.
India
Construction activity in residential and commercial building segments sustains volume demand for PVC and polypropylene terminal fittings. The Bureau of Indian Standards updates dimensional tolerance specifications for plastic piping components, forcing importer qualification adjustments. Maharashtra and Gujarat industrial corridors concentrate procurement for chemical processing and pharmaceutical manufacturing installations.
Saudi Arabia
Petrochemical expansion projects and desalination infrastructure drive demand for high-performance metallic and composite terminal fittings. The country's national standards body aligns pressure equipment regulations with ASME and API codes to facilitate international contractor participation. The Eastern Province industrial zone around Jubail anchors procurement for process piping in aggressive fluid handling applications.
End Cap Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a structure that rewards scale in commodity plastics and captive formulation expertise in chemically resistant grades. The vendor base organizes around three archetypes: integrated resin-to-fitting producers with hedged feedstock positions, specialized compounders serving aggressive fluid handling specifications, and foundry-network operators sustaining domestic metallic casting capacity. Competitive moves concentrate on direct-to-contractor digital platform development and backward integration into resin compounding to defend margin positions against crude oil index volatility.
Among North American fabricators, Charlotte Pipe and Foundry Company anchors the metallic segment through foundry-network control, while JM Eagle occupies a scale-driven position in integrated plastic production. Spears Manufacturing Company exemplifies the specialized compounder archetype, representing formulation-intensive suppliers serving chemically aggressive applications. These three entities collectively illustrate how competitive positioning stratifies across material categories and specification intensity tiers.
| Leading Market Players |
|---|
| Charlotte Pipe and Foundry Company |
| NIBCO Inc. |
| LASCO Fittings, Inc. |
| GF Piping Systems |
| Supreme Industries |
| Wavin Group |
| Aliaxis Group |
| JM Eagle |
| Spears Manufacturing Company |
| Others |
Pricing and Supply Chain Analysis
US Gulf Coast resin production clusters anchor global feedstock pricing, funneling margin capture toward integrated manufacturers with captive polymer compounding capabilities while fragmenting returns across distributor intermediaries lacking formulation control.
Pricing Analysis
Volume-discount tiering structures separate electropolished 316L pharmaceutical-grade caps from standard-pressure PVC drainage fittings. Price differentiation rests on ANSI certification level and captive resin compounding, with premium tiers commanding substantial markups for FDA-validated surface finishes. Cost compression in commodity plastic grades is intensifying as crude oil index volatility squeezes injection molders without hedging programs. Mechanical contractors exhibit highest price sensitivity, while bioprocessing skid manufacturers prioritize qualification reliability over unit economics.
Supply Chain Analysis
Upstream PVC and polypropylene feedstock production concentrates in the United States, China, and Germany. Raw material sourcing draws from ethylene crackers along the Texas Gulf Coast, naphtha refineries in the Yangtze River Delta, and propane dehydrogenation facilities in the Ruhr basin. Single-source vulnerability threatens European compounders dependent on imported plasticizers as REACH restrictions tighten. Distribution runs through regional HVAC and plumbing wholesalers with in-house fabrication and kitting capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
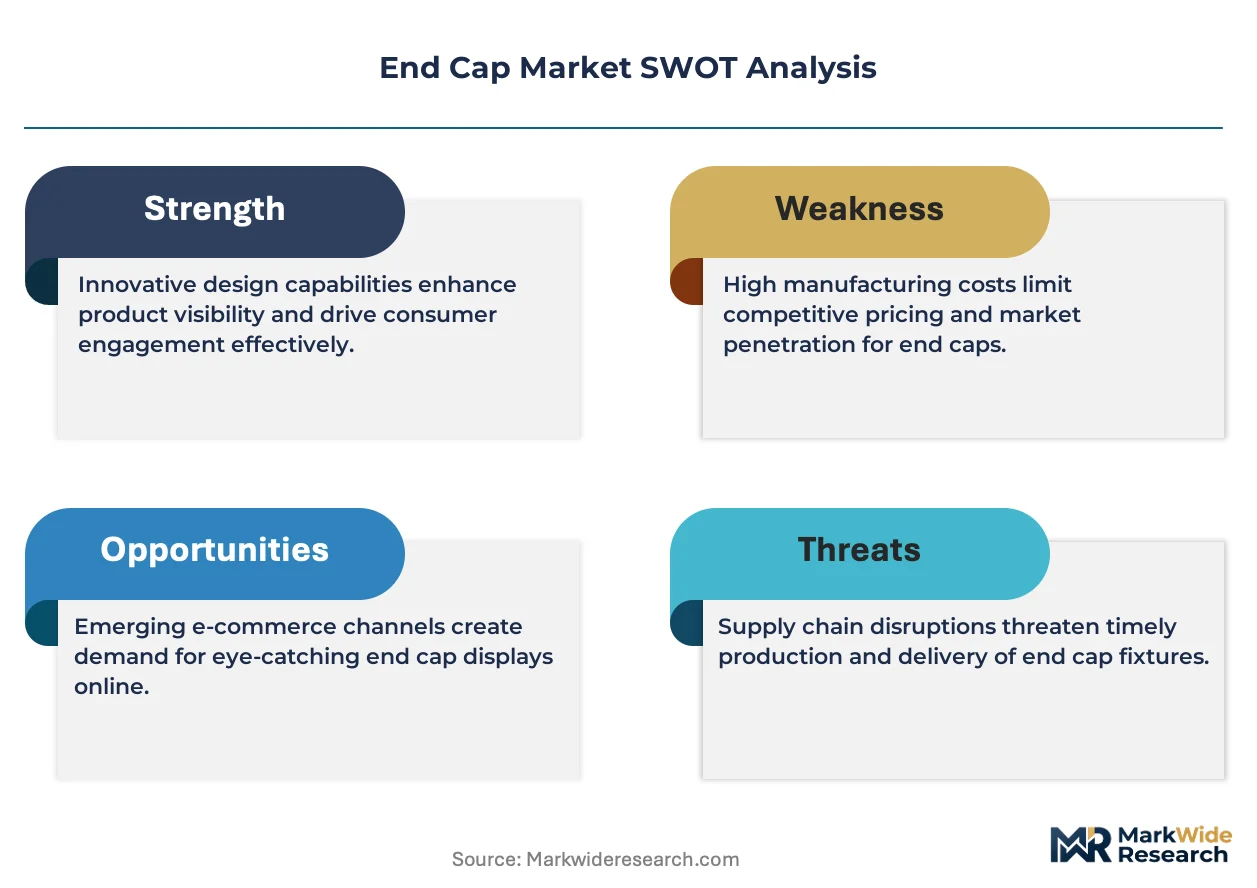
This market operates as a defensive-moat structure where regulatory entrenchment creates substantial switching costs for qualified suppliers in pharmaceutical and chemical processing tiers.
For Market Incumbents: Pre-empt adhesive-bonded cap qualification before PFAS grandfathering provisions expire, locking in specification preference at chemical processors facing accelerated replacement cycles. Deepen backward integration into glass-reinforced polypropylene compounding to defend margin positions against resin price volatility threatening standard-pressure drainage tiers. For New Entrants and Emerging Players: Pursue electropolished stainless steel surface finish capabilities serving bioprocessing skid manufacturers, where FDA validation timelines deter rapid competitive entry. White-space concentration sits with pharmaceutical-grade installations in India and Saudi Arabia, where international contractor presence creates specification transfer opportunities from established Western suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialized compounders holding captive polymer science capabilities and established REACH-compliant formulations. Long-term viability favors targets with qualification depth in fluoropolymer alternatives and pharmaceutical surface finish standards. The signal to watch is state-level PFAS ban acceleration compressing material revalidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polymer science capabilities defend margins against crude oil index volatility. |
| Direct-to-Contractor Digital Platform Launch | Proprietary e-procurement portals bypass wholesale distributors for mechanical contractor volume. |
| Adhesive-Bonded Cap Qualification | PTFE alternative development secures specification preference before PFAS restrictions tighten. |
| Electropolished Surface Finish Investment | FDA-validated 316L capabilities command premium positioning in bioprocessing skid supply chains. |
| RFID-Tagged Inventory Systems | Traceable fitting documentation satisfies OSHA Process Safety Management audit requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across mechanical contractors, chemical processing plant engineers, pharmaceutical bioprocessing specialists, and regional HVAC wholesalers. Secondary validation drew from EPA enforcement memoranda, OSHA safety directives, EU REACH substance restrictions, customs trade data for polymer feedstock flows, and SEC filings from integrated resin-to-fitting producers. Bottom-up project pipeline assessments and top-down macroeconomic indicators were triangulated to anchor volume estimates.
Calibration against historical replacement cycle data and regulatory compliance deadline clustering shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material grade tier, installation protocol type, end-use industry intensity, and regional regulatory cluster. CAGRs were derived from installed base depreciation schedules and specification escalation trajectories, with particular weighting applied to German HVAC retrofit mandates and Gulf Coast chemical processor upgrade timelines.
Sensitivities concentrate around PFAS restriction acceleration, resin price volatility spikes, and domestic foundry capacity constraints for high-pressure metallic grades. Cross-checking against ASME pressure equipment certification databases and EPA enforcement action records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Aluminium ROPP Closures Market
Caps and Closures
Spout Closures Market
Caps and Closures
Latin America Plastic Caps and Closure Market
Caps and Closures
Overcaps Market
Caps and Closures
Hinged Dual Flap Caps Market
Caps and Closures
Disc Top Caps Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
Push Pull Closure Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Bag Closures Market
Caps and Closures
PET Dome Lids Market
Caps and Closures
France Plastic Caps and Closures Market
Caps and Closures
Flapper Caps Market
Caps and Closures
Brush Caps Market