
 Brazil Plastic Caps and Closures Market | 2026-2036
Brazil Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Plastic Caps and Closures Market Insights
Multi-source procurement among large beverage fillers is expanding as brands hedge against resin volatility and logistics disruption. Silgan Holdings Inc. leverages its continental molding footprint to anchor supply contracts with multinational bottlers. Innova S/A sustains dominant positions in regional dairy and juice segments through customized color-matching capabilities. Bral-Max Tampas Plasticas competes on short-run flexibility, serving mid-tier personal care brands that require rapid tooling changes.
Plastic caps and closures are threaded or snap-fit sealing devices, typically injection-molded or compression-molded from thermoplastic resins, designed to preserve contents, enable controlled dispensing, and comply with tamper-evidence requirements. Screw caps retain the largest volume share across Brazilian food and beverage lines due to proven reseal reliability and compatibility with high-speed capping equipment. Dispensing caps are gaining structural importance in personal care and household chemicals as brands prioritize consumer convenience and dosing precision over basic open-and-close formats. PE and PP together absorb the majority of material demand, with PP displacing PE in hot-fill applications where thermal resistance determines specification compliance.
ANVISA governs food-contact migration thresholds and child-resistant packaging mandates for pharmaceuticals, while ABNT technical standards align with Mercosur testing protocols for closure integrity. The national solid waste policy and emerging extended producer responsibility frameworks are pressuring converters to validate recyclability claims and reduce multi-material assemblies. Stakeholders must monitor how state-level environmental enforcement in São Paulo and Rio de Janeiro tightens ahead of federal harmonization, reshaping capital allocation for tooling and resin selection.
Market Dynamics
ANVISA's updated migration limits for food-contact materials are compressing converter tolerance for resin variability, pushing São Paulo and Minas Gerais bottlers toward validated PP and PET supply chains with documented compliance trails.
Growth Catalysts
- ANVISA Migration Thresholds:Tighter food-contact limits are forcing converters to upgrade testing protocols, creating procurement pull for certified resin grades with full traceability documentation.
- Southeast Manufacturing Corridor:Petrochemical feedstock access and converter density in São Paulo state generate clustering economies that reduce logistics costs for beverage bottlers.
- Lightweight Dispensing Formats:Personal care brands are specifying precision-dose closures with reduced gram weight, driving mold engineering investment at Brazilian tooling houses.
Market Restraints
- Resin Price Volatility:Propylene feedstock swings tied to global oil markets compress converter margins, particularly for small-batch personal care orders with fixed-price contracts.
- Southeast Supply Concentration:Overreliance on São Paulo and Rio de Janeiro state production clusters exposes buyers to localized logistics disruptions and port congestion.
- Hot-Fill PE Limitations:Polyethylene thermal performance caps remain incompatible with aseptic juice processing above 85°C, restricting material options for tropical beverage lines.
Strategic Opportunities
- Northeast Dairy Expansion:Pernambuco and Bahia state processors are underpenetrated for tamper-evident closures, opening territory for converters with regional distribution partnerships.
- Extended Producer Responsibility:Emerging federal waste frameworks will reward converters validating mono-material recyclability, creating first-mover advantage for PP-only closure designs.
- Amazon E-Commerce Channel:Direct-to-consumer household chemical brands are bypassing traditional retail, demanding small-lot customization with rapid tooling turnaround.
Industry Challenges
- Mold Engineering Talent Scarcity:São Paulo tooling houses report acute shortages of hot-runner specialists capable of optimizing cycle times for lightweight dispensing formats.
- ABNT Certification Timelines:Closure integrity testing under Mercosur-aligned protocols extends validation cycles, delaying new product launches for pharmaceutical and infant nutrition clients.
- Multi-Material Disassembly:Child-resistant pharmaceutical closures with metal springs complicate mechanical recycling streams, requiring redesign investment ahead of enforcement tightening.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Plastic Caps and Closures Market |
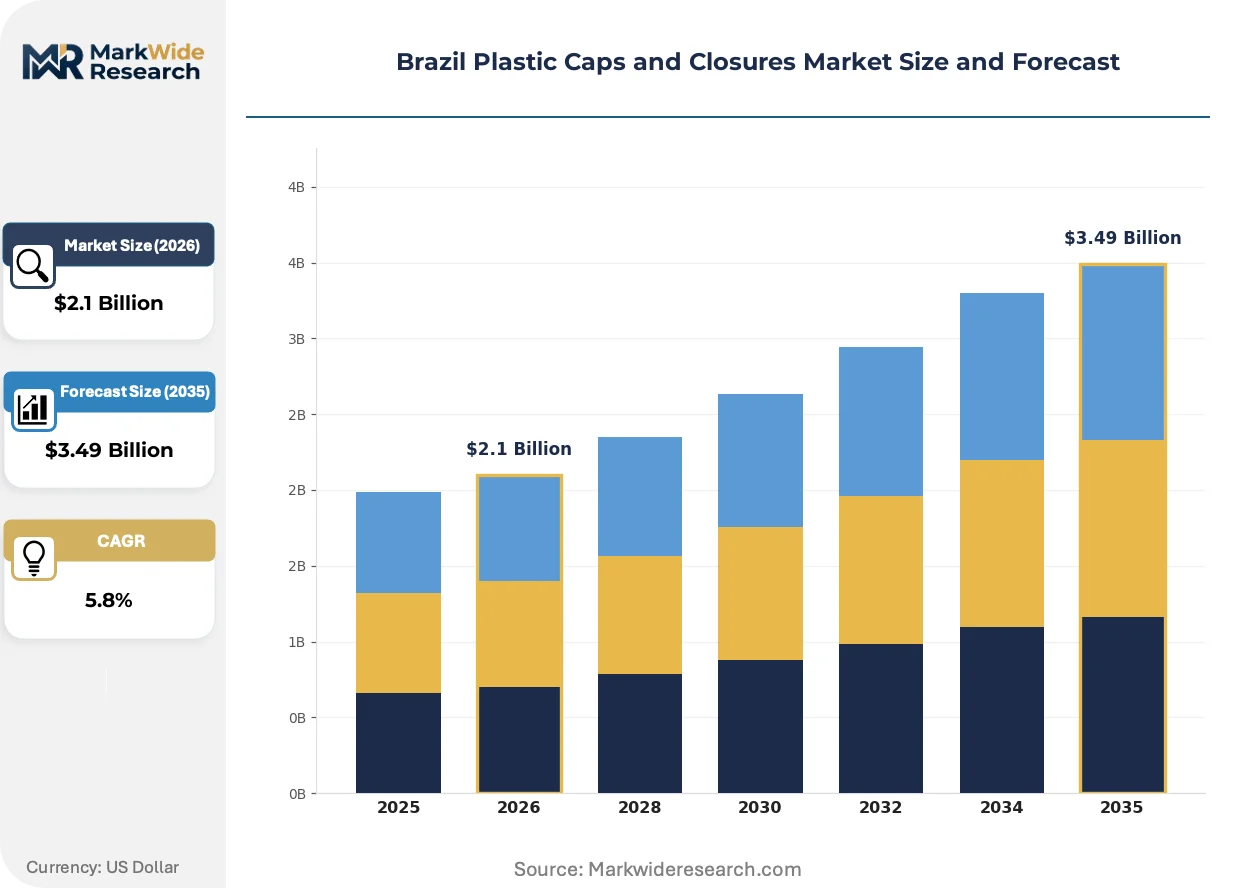
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-on Caps, Dispensing Caps, Child-resistant Caps Application: Food & Beverage, Personal Care, Pharmaceuticals, Household Chemicals Material: PE, PP, PET, PVC End User: Manufacturers, Distributors, Retailers, Exporters |
| Companies Covered | Silgan Holdings Inc., Innova S/A, Bericap Holding GmbH, Bral-Max Tampas Plasticas, Sonoco Products Company, Berry Global Inc., Amcor Group GmbH, Tetra Pak International S.A., AptarGroup Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Plastic Caps and Closures Market Trends and Innovations
Digital manufacturing and regulatory compliance automation are compressing development cycles for Brazilian converters, while sustainability verification reshapes resin procurement criteria across beverage and personal care segments.
Biobased PP feedstocks derived from sugarcane ethanol are integrating into closure specifications for premium beverage brands seeking carbon footprint differentiation. Minas Gerais bottlers are piloting these grades in sparkling water lines. The material is integrating into supply contracts as a compliance hedge against future federal bio-content mandates.
ANVISA's 2024 updated Resolution RDC 326 tightens heavy metal migration thresholds for colored closures, forcing pigment reformulation at compounding partners. Converters must resubmit technical files for existing SKUs. Pharmaceutical and pediatric nutrition segments are absorbing the highest retesting costs, with some suppliers exiting colored closure production entirely.
Multi-source resin qualification is replacing single-supplier relationships among large beverage fillers seeking to de-risk propylene volatility. Procurement teams in São Paulo are maintaining approved vendor lists across three resin producers minimum. This pattern is most visible in carbonated soft drink bottling, where annual volume commitments justify parallel validation investments.
Brazil Plastic Caps and Closures Market Segmentation
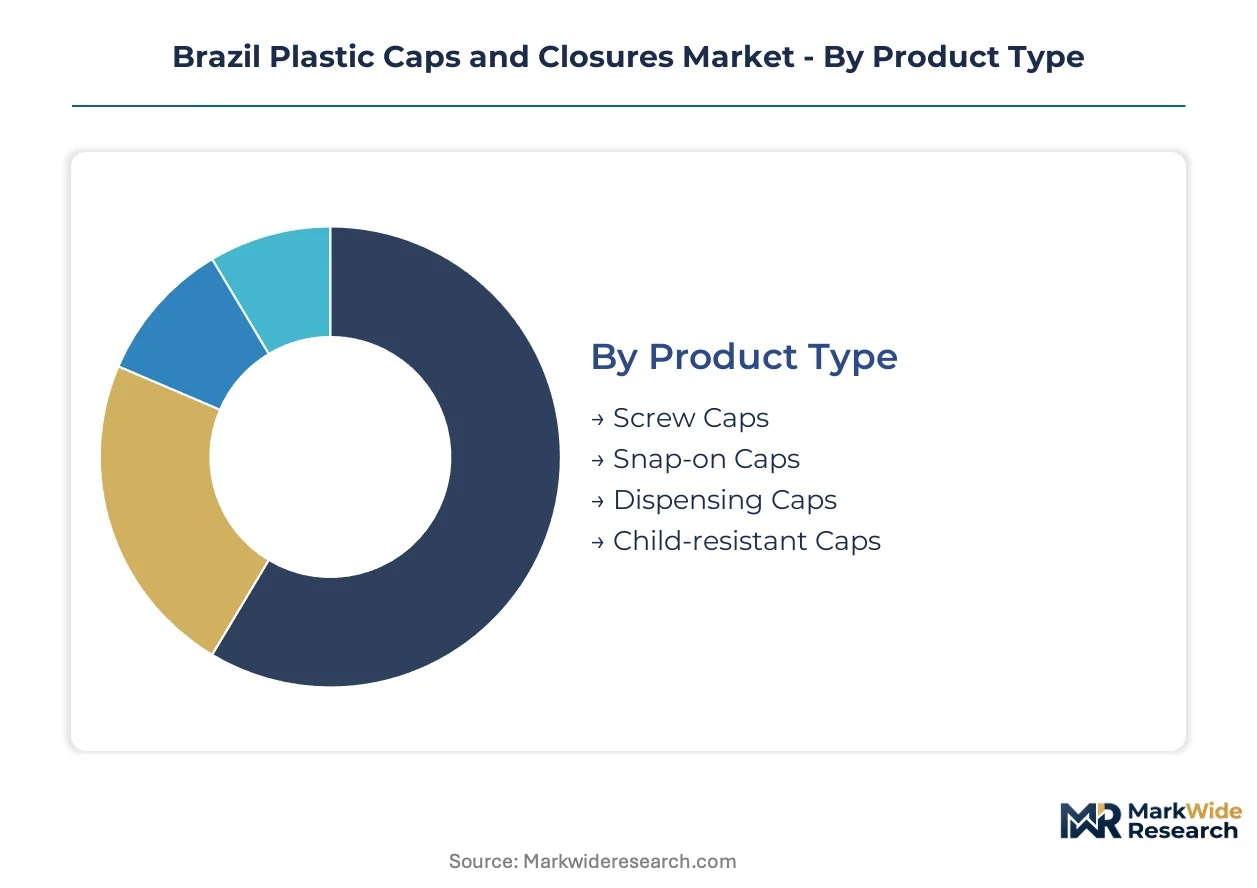
Segmentation in Brazil's plastic caps and closures market reveals how converter capabilities align with distinct technical requirements across beverage bottling, pharmaceutical compliance, and personal care convenience. Understanding these divisions exposes where resin specification, mold engineering investment, and regulatory validation concentrate procurement decisions.
Product Type:
Upgrade cycles in capping equipment and shifting consumer convenience expectations are redrawing the competitive map among closure formats, with lightweight precision-dose designs displacing legacy open-and-close systems in high-margin segments.
- Screw Caps:Threaded closures injection-molded from PP or HDPE deliver proven reseal reliability across carbonated soft drink and still water lines. São Paulo bottlers specify these for compatibility with high-speed rotary capping equipment running above 600 bottles per minute. ANVISA migration compliance documentation now accompanies every resin lot.
- Dispensing Caps:Precision-orifice designs with flip-top or push-pull actuation enable controlled dosing for shampoo, conditioner, and household chemical brands. Minas Gerais personal care fillers are expanding orders for reduced-gram-weight formats that cut resin content without sacrificing functional integrity.
- Snap-on Caps:Compression-molded LDPE closures press-fit onto container finishes serve dairy and juice segments where reseal is secondary to tamper evidence. Pernambuco processors favor these for cost-sensitive UHT milk lines.
- Child-resistant Caps:Push-and-turn or squeeze-and-turn mechanisms with internal metal springs comply with ANVISA pharmaceutical mandates. Rio de Janeiro compounding pharmacies absorb premium pricing for validated CR designs.
Screw caps sit at the top of the volume ranking, with dispensing caps climbing the fastest as personal care brands prioritize dosing precision over basic sealing.
Application:
End-use concentration in Brazil's Southeast manufacturing corridor shapes converter specialization, with beverage bottlers in São Paulo state consuming the majority of high-throughput closure output.
- Food & Beverage:Carbonated soft drinks, bottled water, and aseptic juice lines demand closures validated for hot-fill compatibility above 85°C. PP displacement of PE is most advanced here. ANVISA's updated migration thresholds have forced pigment reformulation across colored beverage caps.
- Personal Care:Shampoo, conditioner, and body wash brands specify precision-dose dispensing formats with customized color-matching. Bahia state processors remain underpenetrated for tamper-evident designs, opening territory for regional distribution partnerships.
- Pharmaceuticals:Child-resistant and senior-friendly closures for prescription and OTC medications face extended ABNT certification timelines under Mercosur-aligned testing protocols. Retesting costs for ANVISA Resolution RDC 326 compliance have pushed some suppliers out of colored closure production.
- Household Chemicals:Bleach, disinfectant, and surface cleaner brands require chemical-resistant PP or HDPE closures with venting features to prevent pressure buildup. Amazon direct-to-consumer channels are bypassing traditional retail, demanding small-lot customization with rapid tooling turnaround.
Food and beverage commands the largest share of converter capacity, while household chemicals through e-commerce channels are expanding most quickly.
Material:
Resin selection in Brazilian closure production tracks thermal performance requirements and recyclability pressures, with biobased feedstocks from sugarcane ethanol entering premium beverage specifications.
- PP:Polypropylene dominates hot-fill and aseptic applications where thermal resistance above 100°C determines specification compliance. Minas Gerais sparkling water bottlers are piloting biobased PP grades as a hedge against future federal bio-content mandates.
- PE:Polyethylene retains cost-sensitive dairy and non-hot-fill juice segments, though its thermal ceiling below 85°C excludes aseptic processing lines. HDPE serves screw cap applications; LDPE serves snap-on formats.
- PET:Polyester closures for carbonated beverages and pharmaceutical bottles offer clarity and oxygen barrier properties. São Paulo converters are qualifying PET grades with full traceability documentation for ANVISA compliance trails.
- PVC:Polyvinyl chloride persists in limited pharmaceutical and household chemical applications where chemical resistance outweighs recyclability concerns. Emerging extended producer responsibility frameworks are pressuring phase-out.
PP leads material demand by volume, with PET gaining share fastest as beverage bottlers diversify resin sources to hedge propylene volatility.
End User:
Channel structure in Brazil's closure market reflects the dominance of integrated beverage bottlers with direct converter relationships, contrasting with fragmented personal care and pharmaceutical procurement patterns.
- Manufacturers:Integrated beverage bottlers in São Paulo and Minas Gerais maintain approved vendor lists across three resin producers minimum, running parallel validation investments for multi-source qualification. Annual volume commitments justify captive tooling arrangements.
- Distributors:Regional stocking intermediaries serve mid-tier personal care and household chemical brands lacking direct converter relationships. Northeast Brazil distribution partnerships are opening territory for tamper-evident closure penetration.
- Retailers:Private-label retail chains for bottled water and basic personal care products source through converter-direct arrangements with simplified specification requirements. Price pressure is most intense at this tier.
- Exporters:Mercosur-bound shipments demand ABNT-certified closures aligned with regional testing protocols. Rio de Janeiro port congestion exposes exporters to logistics disruption risks.
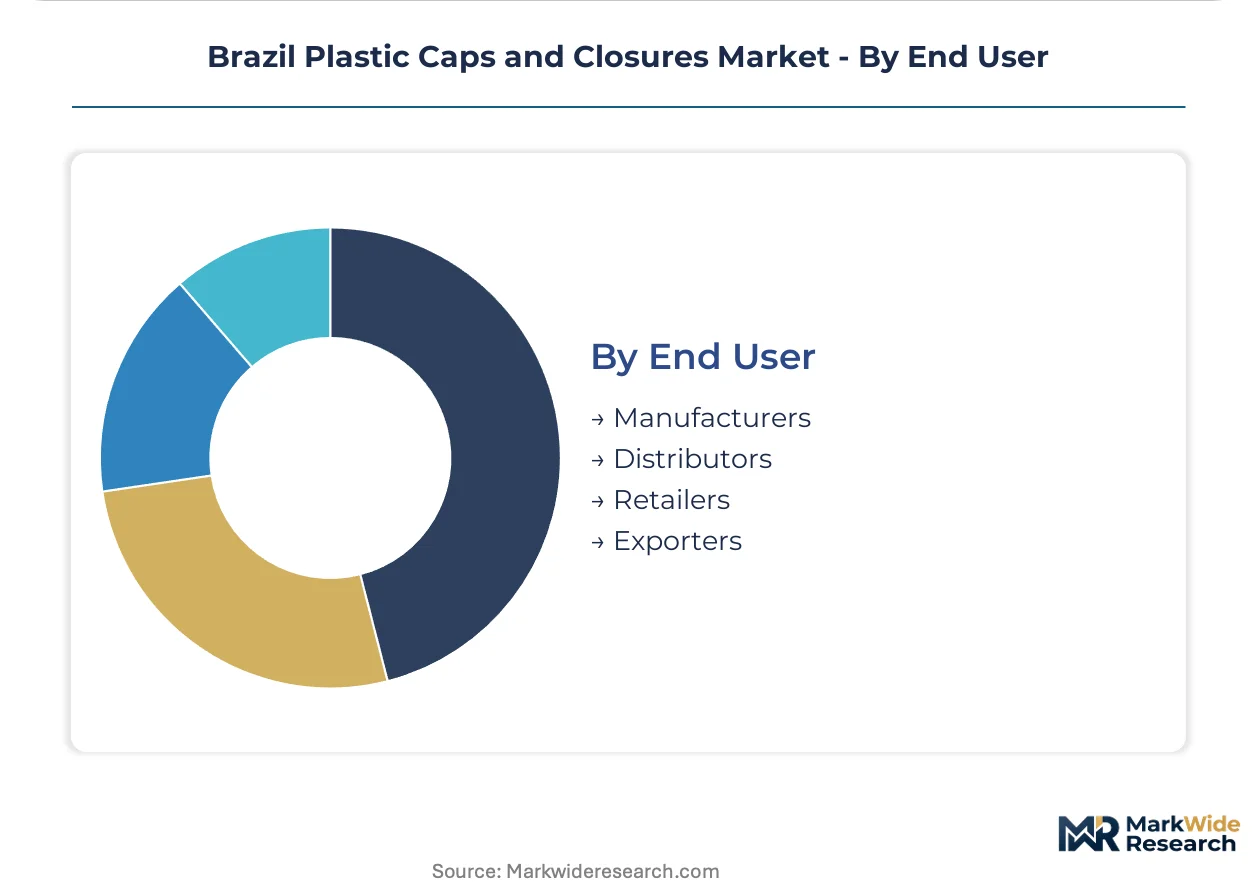
Manufacturers absorb the majority of converter output, with exporters representing the steepest expansion trajectory as Mercosur trade integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography in Brazil's plastic caps and closures sector, as converters migrate toward states with streamlined ANVISA compliance pathways and lower cost-of-compliance thresholds.
São Paulo
Carbonated soft drink bottlers and high-speed capping lines dominate procurement volumes, driving demand for PP screw caps validated above 600 bottles per minute. ANVISA's updated migration limits have forced pigment reformulation across colored beverage closures. The ABC Paulista industrial corridor anchors converter density, with petrochemical feedstock access reducing logistics costs for resin qualification.
Minas Gerais
Sparkling water brands are piloting biobased PP grades derived from regional sugarcane ethanol supply chains. The state's dairy processors favor snap-on LDPE closures for cost-sensitive UHT milk lines. Belo Horizonte's tooling houses report mold engineering investment for lightweight dispensing formats.
Rio de Janeiro
Pharmaceutical compounding pharmacies absorb premium pricing for child-resistant closure designs. ABNT certification timelines under Mercosur-aligned protocols extend validation cycles for pediatric nutrition clients. Port congestion at Rio de Janeiro exposes exporters to logistics disruption risks for Mercosur-bound shipments.
Bahia
Personal care processors remain underpenetrated for tamper-evident dispensing closures, opening territory for regional distribution partnerships. Northeast dairy expansion in Salvador's industrial zone drives procurement pull for snap-on formats. State-level environmental enforcement is tightening ahead of federal harmonization.
Pernambuco
Juice processors are qualifying PP grades for aseptic hot-fill compatibility above 85°C, displacing PE thermal limitations. Recife's converter base competes on short-run flexibility for mid-tier household chemical brands. Emerging extended producer responsibility frameworks are pressuring mono-material closure designs.
Brazil Plastic Caps and Closures Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized dispensing and sustainability-certified segments. The vendor base clusters around three strategic archetypes: multinational molding networks with continental footprint, regional specialists with customized color-matching capabilities, and flexible short-run operators serving fragmented personal care demand. Dominant competitive moves include multi-source resin qualification to hedge propylene volatility and mold engineering investment for lightweight gram-weight reduction.
Among multinational holding companies, Silgan Holdings Inc. and Bericap Holding GmbH represent the scale-driven archetype with continental supply contracts. Innova S/A and Bral-Max Tampas Plasticas exemplify regional specialists competing on customization velocity and short-run tooling agility. Sonoco Products Company, Berry Global Inc., and Amcor Group GmbH occupy diversified packaging conglomerate positions across adjacent substrate categories.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Innova S/A |
| Bericap Holding GmbH |
| Bral-Max Tampas Plasticas |
| Sonoco Products Company |
| Berry Global Inc. |
| Amcor Group GmbH |
| Tetra Pak International S.A. |
| AptarGroup Inc. |
| Others |
Pricing and Supply Chain Analysis
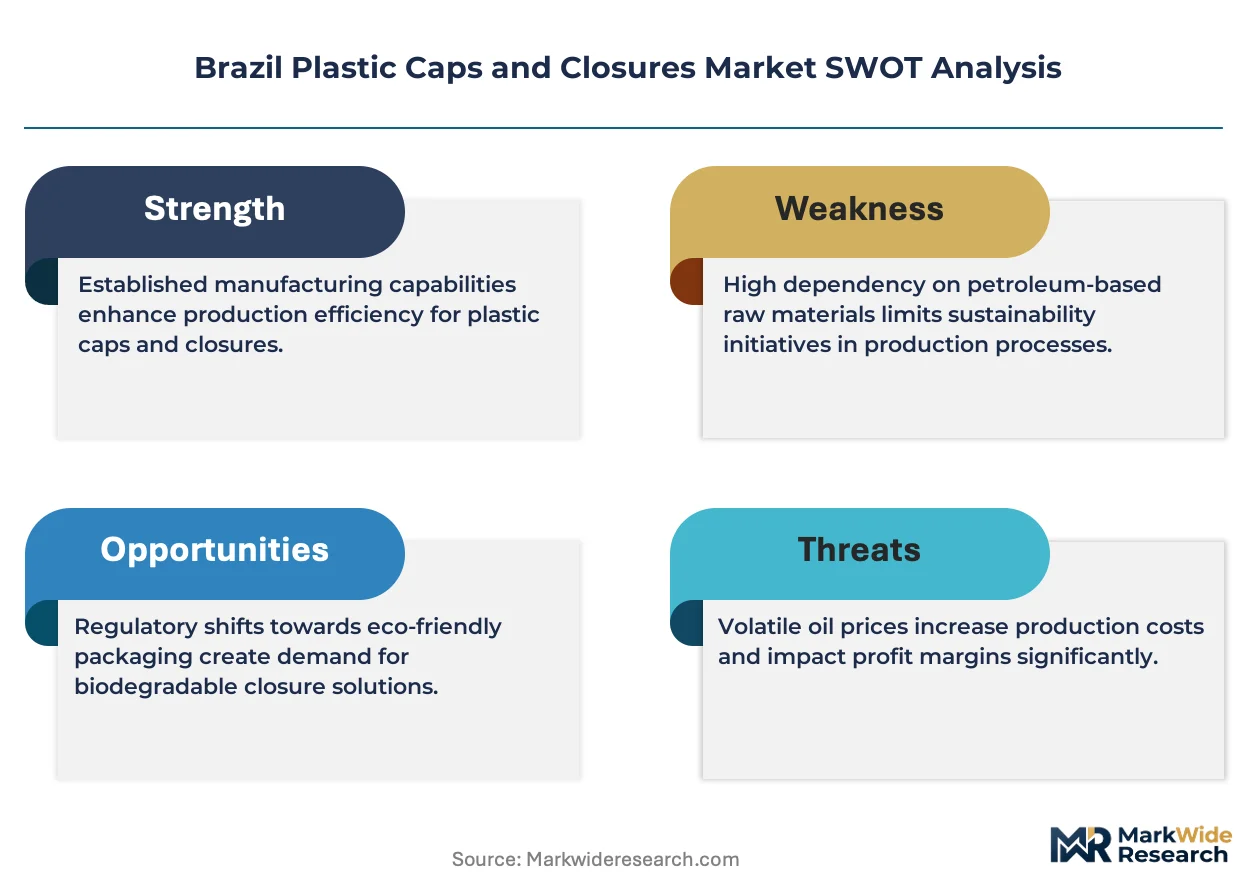
Family-owned mid-cap converters in São Paulo's ABC Paulista corridor anchor supply discipline through generational capital allocation that resists short-term margin erosion, while their direct relationships with Braskem and other petrochemical producers lock in resin access that insulates pricing from spot-market volatility.
Pricing Analysis
Distributor margin layers in Brazil's closure market absorb 12-18 percent between converter gate and end-user plant, with direct-to-OEM arrangements commanding 8-12 percent discounts for annual volume commitments above 50 million units. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-certified pharmaceutical closures from basic beverage caps and commodity dairy formats. Cost compression in personal care dispensing segments is intensifying because lightweight gram-weight specifications require mold engineering investment that smaller converters cannot amortize. Mid-tier household chemical brands exhibit highest price sensitivity, while pharmaceutical compounding pharmacies absorb premium pricing for validated child-resistant designs.
Supply Chain Analysis
Propylene feedstock supply rests on Braskem's integrated petrochemical complexes in São Paulo and Rio Grande do Sul, with imported resin drawing from US Gulf Coast and Middle Eastern producers when domestic pricing diverges. Raw material dependencies center on polymer-grade propylene, masterbatch pigments reformulated for ANVISA's updated migration thresholds, and hot-runner mold components sourced from German and Italian tooling houses. Single-source vulnerability concentrates in specialized hot-runner systems where São Paulo tooling houses report acute shortages of cycle-time optimization specialists. Distribution runs through converter-direct relationships with integrated beverage bottlers, supplemented by regional stocking intermediaries serving fragmented personal care and household chemical demand in Northeast states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's plastic caps and closures market functions as a stable compounder where ANVISA's tightening regulatory trajectory generates sustained upgrade demand across converter installed base.
For Market Incumbents: Extend mold engineering capabilities into lightweight dispensing formats before personal care brands consolidate supplier relationships around precision-dose specialists. Deepen backward integration into captive pigment compounding to hedge ANVISA retesting costs that have already pushed competitors out of colored closure production. Threat substitution from aluminum and biobased alternatives demands accelerated biobased PP qualification to maintain specification relevance. For New Entrants and Emerging Players: Capture underpenetrated tamper-evident dispensing closure demand in Bahia and Pernambuco state personal care processors through regional distribution partnerships that bypass São Paulo converter dominance. Northeast dairy expansion in Salvador's industrial zone offers white-space entry for snap-on LDPE formats with short-run flexibility that incumbent high-volume lines cannot economically serve. Go-to-market angle should emphasize rapid tooling turnaround for Amazon direct-to-consumer household chemical brands. For Investors and Strategic Acquirers: Packaging conglomerates with adjacent substrate diversification are the most active acquirer in this space, seeking closure capabilities to complete integrated beverage packaging systems. Five-to-ten year viability hinges on mono-material recyclability validation ahead of federal extended producer responsibility enforcement. Target acquisition archetype: regional specialists with customized color-matching capabilities and established ANVISA technical file libraries. Signal to watch is state-level environmental enforcement tightening in São Paulo and Rio de Janeiro ahead of federal harmonization.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Recyclability Validation | First-mover advantage in PP-only designs hedges emerging federal waste framework enforcement. |
| Biobased PP Supply Contracting | Sugarcane ethanol-derived grades secure carbon footprint differentiation for premium beverage brands. |
| Hot-Runner Mold Engineering Investment | Cycle-time optimization capabilities address acute talent scarcity in São Paulo tooling houses. |
| Multi-Source Resin Qualification | Parallel validation across three resin producers minimum de-risks propylene feedstock volatility. |
| Northeast Distribution Partnership | Regional stocking intermediaries open territory for tamper-evident penetration in underpenetrated states. |
Research Methodology
Bottom-up beverage bottler and personal care processor modeling reconciled against top-down resin consumption and converter capacity tracking forms the analytical core of this study. Primary interviews with plant managers at integrated bottling operations, procurement leads at downstream personal care brands, distribution channel partners in Northeast states, and technical R&D directors at compounding houses were cross-validated against secondary sources including ANVISA regulatory filings, ABNT technical standards documentation, Braskem and petrochemical producer disclosures, and customs trade data for resin imports.
Input-output matrices mapping propylene feedstock through polymerization, compounding, and injection molding stages generated volume and value estimates across the projection horizon. Segmentation dimensions modeled include closure product type, application end-use, material resin grade, and regional production cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trajectories, with biobased PP adoption curves and ANVISA compliance cost pass-throughs incorporated as scenario variables.
Resin price volatility, regulatory enforcement acceleration, and mold engineering talent scarcity are the dominant revision risks to forecast assumptions. Material deviation in named triggers warrants pause and re-evaluation of converter margin and capacity expansion timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Disc Top Caps Market
Caps and Closures
China Plastic Caps and Closures Market
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Non-Aerosol Overcaps Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
Germany Plastic Caps and Closures Market
Caps and Closures
Mexico Plastic Caps and Closures Market
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
Dropper Caps Market
Caps and Closures
Europe Metal Caps and Closures Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Bar Top Corks Market