
 Sport Caps and Closures Market | 2026-2036
Sport Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Sport Caps and Closures Market Analytics
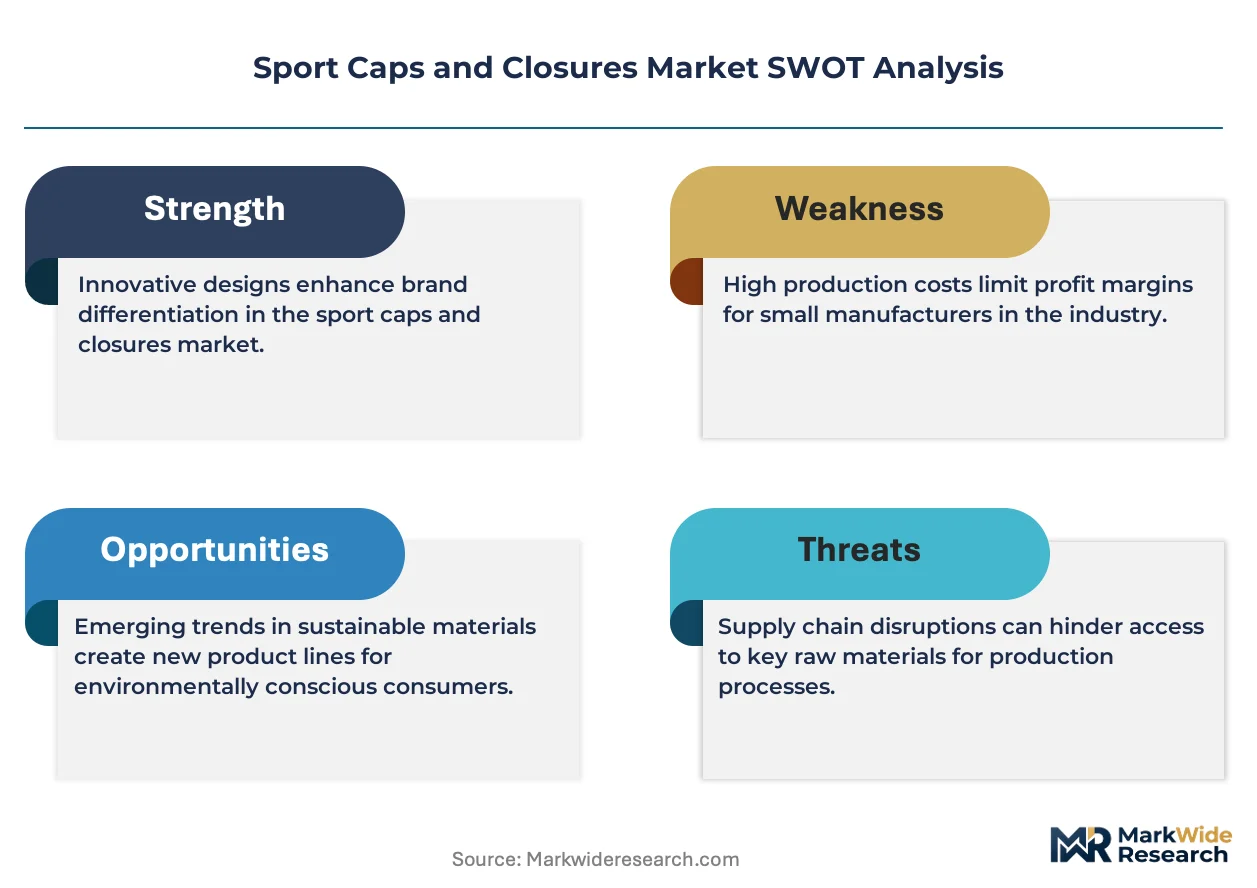
Sports beverage packaging is expanding its share of closure procurement as functional hydration products displace conventional soft drinks in retail coolers. BERICAP Holding GmbH leverages its European manufacturing footprint to supply tamper-evident solutions to major bottlers. Silgan Holdings Inc. sustains North American market presence through high-volume injection-molded cap production for carbonated and non-carbonated sports drinks. Guala Closures S.p.A differentiates through specialized sports closures with integrated pour-control features for premium energy and protein beverage segments.
Sport caps and closures are precision-engineered dispensing and sealing devices, typically manufactured through injection molding or compression molding processes using polyethylene, polypropylene, or aluminum substrates, designed to maintain carbonation integrity, prevent contamination, and enable controlled consumption during physical activity. Screw caps dominate volume deployment across mass-market sports drinks due to resealability and cost efficiency, while flip caps command premium positioning in single-serve functional beverages where one-handed operation drives consumer preference. Tamper-evident closure designs carry concentrated margin pools as brand owners prioritize safety authentication and regulatory compliance in direct-to-consumer channels.
The FDA enforces food-contact substance regulations that govern migration limits and material safety for plastic sport closures in the United States, while the EU Green Deal and REACH framework restrict certain additives and mandate recyclability disclosures across European supply chains. China's SAMR implements national food packaging standards that foreign closure suppliers must satisfy for market access. Stakeholders must monitor evolving extended producer responsibility schemes and material substitution timelines to align capital allocation with compliance-driven specification changes.
Market Dynamics
The EU Single-Use Plastics Directive is compressing specification timelines across European bottling operations, forcing converters to accelerate bio-based material validation and recyclability certification ahead of enforcement deadlines in Germany, France, and Italy.
Growth Catalysts
- Regulatory mandates:The EU Green Deal and REACH framework restrict virgin polymer use in beverage packaging, compelling brand owners to specify closures with certified recycled content and driving converter investment in chemical recycling partnerships.
- Material innovation:Bio-based polyethylene derived from sugarcane and second-generation feedstocks achieves performance parity with fossil-derived resins, enabling drop-in replacement at German and Brazilian bottling facilities without line revalidation.
- China:SAMR food-contact standards enforcement tightens import requirements for foreign closure suppliers, creating captive demand for domestic manufacturers with certified GB-compliant production lines.
Market Restraints
- Resin price volatility:Polypropylene feedstock costs fluctuate with naphtha and propylene spot markets, compressing converter margins and forcing quarterly price adjustment clauses in multi-year bottler contracts.
- Tooling concentration:High-cavitation injection mold fabrication concentrates among specialized suppliers in Germany and Japan, creating 16-24 week lead times that constrain capacity expansion for tamper-event closure programs.
- Performance ceiling:Current bio-based materials exhibit oxygen transmission rates 15-40% higher than conventional resins, limiting deployment in carbonated sports drinks requiring extended shelf stability.
Strategic Opportunities
- India:FSSAI packaging regulations are tightening ahead of 2026 implementation, creating first-mover advantage for converters establishing local compounding and molding operations to serve emerging functional beverage bottlers.
- Connected packaging integration:NFC-enabled closures combining tamper-evidence with consumer engagement are rewriting premium sports nutrition positioning, with protein shake brands in the United States piloting loyalty-program integration.
- Refill infrastructure:Sports venue and gym dispensing networks in Germany and the Netherlands are expanding, generating demand for standardized 38mm thread closures compatible with reusable bottle pooling systems.
Industry Challenges
- Migration testing bottlenecks:FDA and EFSA notification timelines for novel food-contact substances extend 12-18 months, delaying commercialization of post-consumer recycled content formulations.
- Multi-material separation:Sport closures incorporating silicone valves, metal springs, and mixed polymer bodies complicate automated sortation at materials recovery facilities, threatening compliance with extended producer responsibility targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sport Caps and Closures Market |
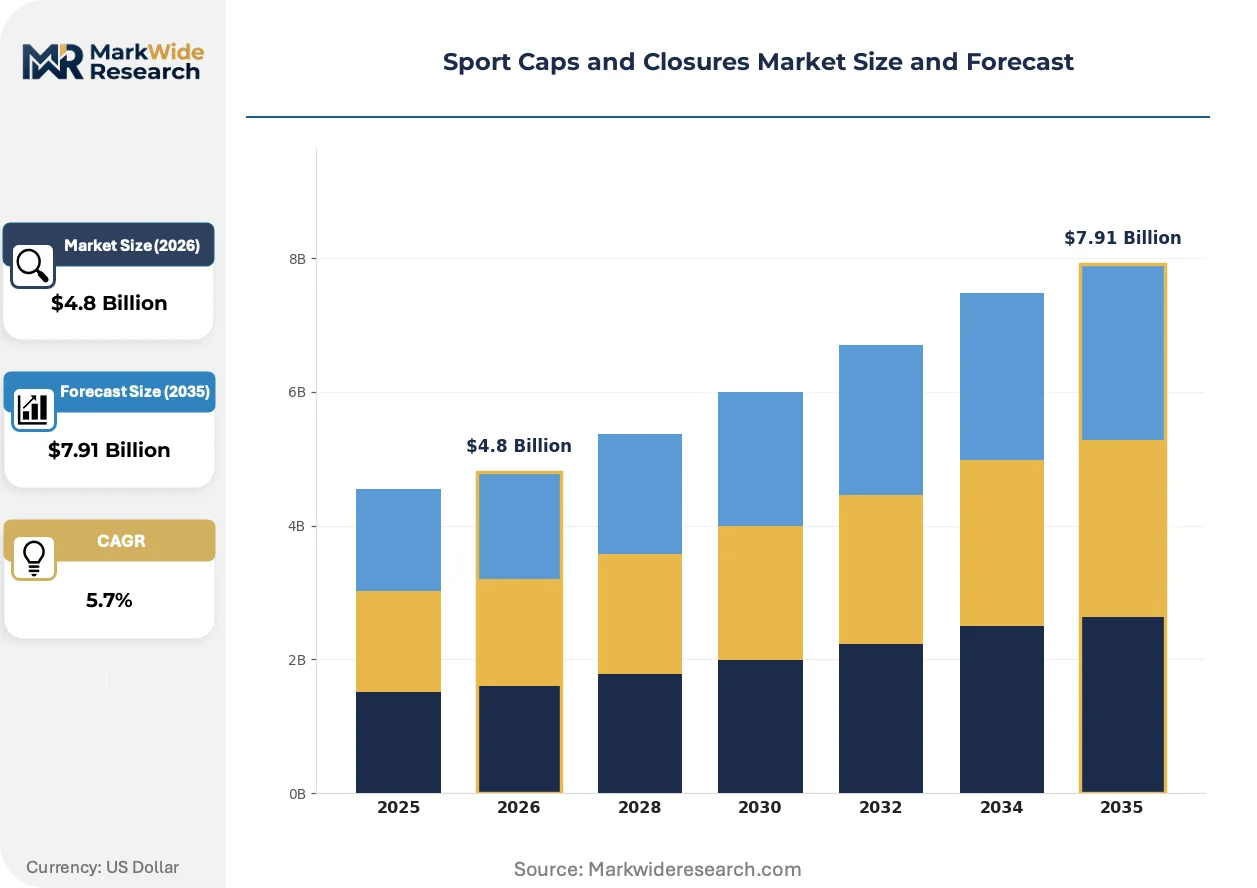
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snap Caps, Screw Caps, Flip Caps, Corks Material: Plastic, Metal, Glass, Silicone Closure Design: Child-Resistant, Tamper-Evident, Easy-Open, Standard End User: Manufacturers, Distributors, Retailers, Wholesalers |
| Companies Covered | AptarGroup, Inc., BERICAP Holding GmbH, Silgan Holdings Inc., Berry Global Inc., Closure Systems International, Inc., United Caps, Crown Holdings, Inc., Guala Closures S.p.A, Plastipak Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sport Caps and Closures Market Evolving Landscape
Closure engineering is converging with digital authentication and circular material flows, compressing development cycles and redefining value capture points between resin suppliers, converters, and brand owners.
Mono-material polypropylene closures with integrated living hinges and pour-control features are rewriting performance standards for functional beverage dispensing. Premium protein and energy drink brands in the United States and United Kingdom specify these designs to eliminate silicone components and satisfy recyclability claims. The elimination of secondary materials reduces sortation complexity at materials recovery facilities while maintaining one-handed operation.
The EU Green Deal's packaging and packaging waste regulation revision tightens recyclability definitions and mandates minimum recycled content thresholds. Closure converters serving German and French bottlers must validate post-consumer recycled polypropylene streams through EFSA safety assessments. The compliance burden falls heaviest on small-to-mid converters lacking in-house regulatory affairs capabilities.
Direct-to-consumer subscription models for powdered sports nutrition are reshaping closure specification priorities. Brands ship concentrated formulations requiring precise dosing and moisture protection, driving demand for child-resistant, desiccant-integrated closures. This channel expansion concentrates in the United States and United Kingdom, where fulfillment infrastructure supports recurring delivery schedules.
Sport Caps and Closures Market Segmentation
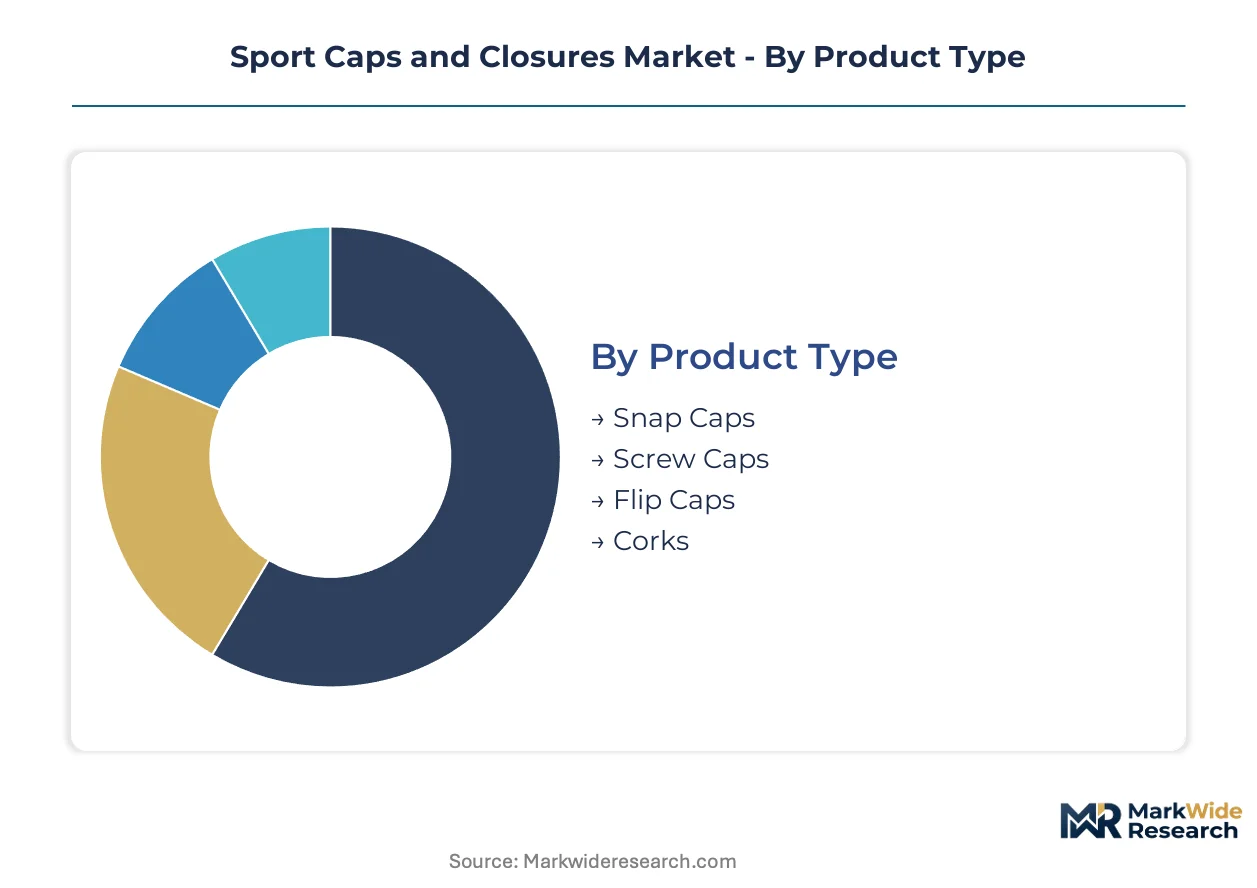
Sport caps and closures serve distinct functional requirements across beverage categories, from carbonation retention in mass-market drinks to precise dosing in sports nutrition. Specification choices cascade through material selection, regulatory compliance, and recyclability certification.
Product Type:
Standalone dispensing mechanisms dominate high-volume bottling, while embedded closure systems integrate with bottle design for premium positioning.
- Screw Caps:Threaded polypropylene designs with liner systems maintain carbonation integrity across extended distribution chains. German bottlers specify these for mass-market isotonic drinks where resealability and cost efficiency intersect.
- Flip Caps:Living-hinge mechanisms enable one-handed operation during physical activity. Demand concentrates in United States premium functional beverages where gym and trail consumption patterns favor convenience.
- Snap Caps:Press-fit designs with audible engagement confirmation suit single-serve formats with shorter consumption windows.
- Corks:Natural and synthetic variants retain niche positioning in premium sparkling sports hydration with wine-category aesthetic associations.
Screw caps lead volumes today; flip caps are gaining share fastest.
Material:
Cost tiers separate commodity-grade specifications from certified sustainable alternatives commanding procurement premiums.
- Plastic:Polyethylene and polypropylene formulations dominate through injection molding scalability. REACH-compliant recycled content streams are displacing virgin resins in French and Italian bottling contracts.
- Metal:Aluminum screw shells and roll-on pilfer-proof designs serve carbonated drinks requiring oxygen barrier performance. Chinese manufacturers leverage domestic aluminum supply chains for cost-competitive export production.
- Glass:Ceramic and glass stopper assemblies occupy ultra-premium positioning with negligible volume share.
- Silicone:Valve and seal components enable pour-control functionality in protein shake closures, though multi-material construction complicates recyclability compliance.
Plastic commands absolute volume; metal is climbing the fastest on sustainability credentialing.
Closure Design:
Application context determines whether safety certification or accessibility takes priority in specification.
- Tamper-Evident:Break-band and shrink-sleeve designs provide visual authentication of seal integrity. FDA food-contact substance regulations govern migration limits for these direct-consumer safety features.
- Child-Resistant:Push-and-turn or squeeze-and-turn mechanisms satisfy Poison Prevention Packaging Act requirements for concentrated sports nutrition products in United States direct-to-consumer channels.
- Easy-Open:Reduced torque specifications and ergonomic wing designs address aging demographic needs in Japanese functional beverage markets.
- Standard:Unmodified screw or snap configurations serve cost-optimized bulk formats with minimal regulatory burden.
Tamper-evident designs lead volumes today; child-resistant specifications are expanding most quickly.
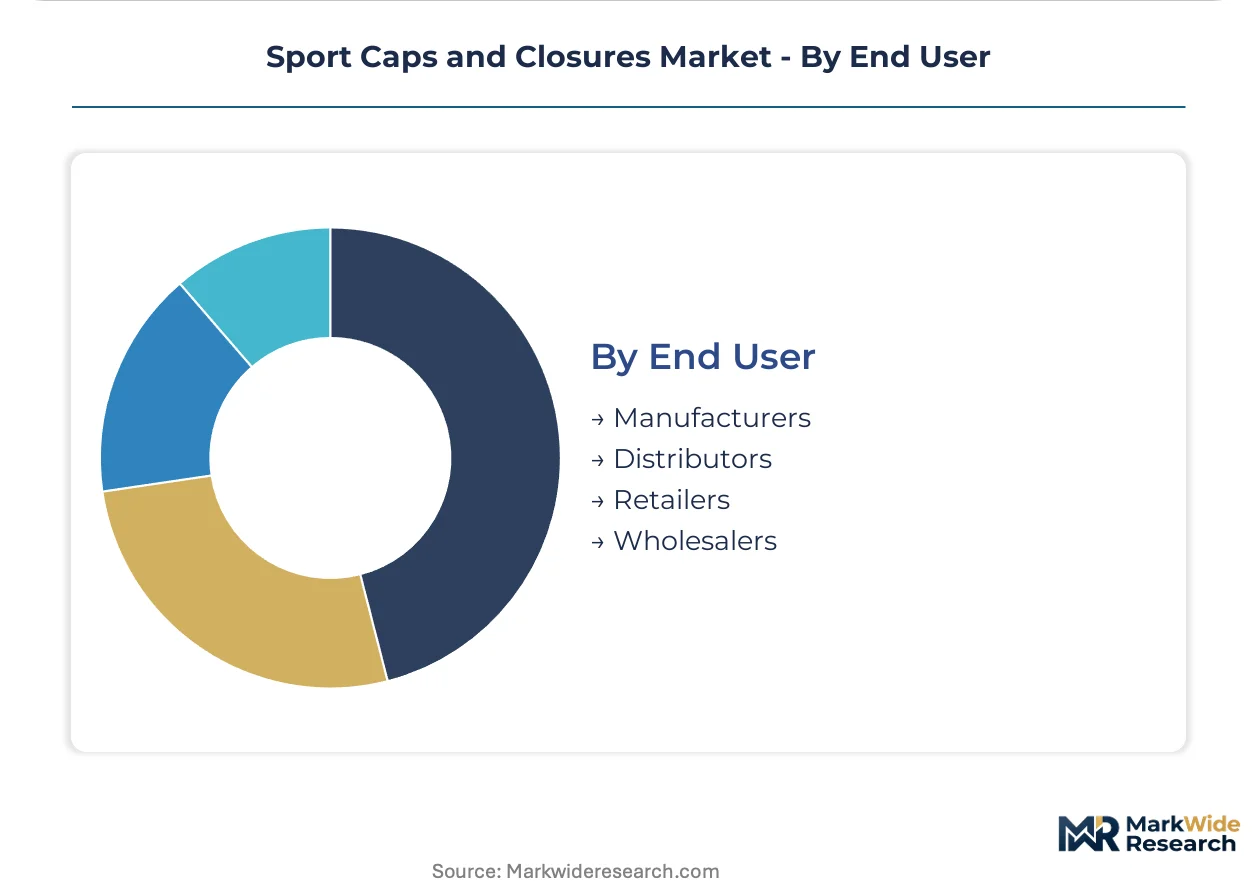
End User:
Customer type shapes order scale, customization requirements, and inventory velocity expectations.
- Manufacturers:Brand-owning bottlers specify closures through multi-year supply agreements with volume commitments and line compatibility requirements.
- Distributors:Third-party logistics providers aggregate demand across smaller bottlers, emphasizing standardization and rapid replenishment.
- Retailers:Private-label sports drink programs at German and United Kingdom grocery chains drive specification for shelf differentiation.
- Wholesalers:Foodservice and vending channel suppliers prioritize durability and theft-deterrence in high-throughput environments.
Manufacturers lead volumes today; retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bottling clusters anchor demand concentration for precision-engineered sport closures, with regulatory pressure from Brussels and Beijing reshaping procurement patterns across three continents.
United States
Functional beverage subscription models and direct-to-consumer sports nutrition channels drive specification shifts toward child-resistant and desiccant-integrated designs. FDA food-contact substance regulations govern migration limits for post-consumer recycled content formulations. Texas and California bottling corridors concentrate injection-molded cap demand from protein shake and energy drink brands.
Germany
Mass-market isotonic drinks and reusable bottle pooling systems at sports venues sustain high-volume screw cap procurement. EU Green Deal packaging regulations mandate minimum recycled content thresholds and EFSA safety assessments for closure converters. North Rhine-Westphalia and Bavaria host the continent's densest converter-to-bottler supply chains.
China
Domestic aluminum supply chains and carbonated sports drink expansion support metal closure fabrication for oxygen-sensitive formulations. SAMR food-contact standards enforcement tightens import requirements, privileging GB-compliant domestic manufacturers. Yangtze River Delta molding operations serve both local bottlers and export markets.
India
Emerging functional beverage bottlers and tightening FSSAI packaging regulations ahead of 2026 implementation create first-mover opportunities for local compounding operations. Maharashtra and Gujarat industrial corridors attract converter investment to serve domestic sports nutrition brands.
Brazil
Bio-based polyethylene from sugarcane feedstocks achieves performance parity with fossil-derived resins at major bottling facilities. ANVISA pharmaceutical and food packaging standards govern closure safety for sports nutrition imports. São Paulo state concentrates converter capacity for Latin American beverage exports.
Sport Caps and Closures Market Competitive Landscape
Capacity expansion dominates the current landscape as converters race to install high-cavitation injection molding lines ahead of EU enforcement deadlines. The vendor base stratifies across three tiers: integrated resin-to-closure conglomerates with captive compounding, mid-scale specialists focused on tamper-evident and child-resistant designs, and regional fabricators serving single-country bottling operations. Two competitive vectors define positioning: backward integration into resin compounding to secure certified recycled content streams, and geographic expansion through toll manufacturing partnerships in India and Southeast Asia.
Among European-based specialists, BERICAP Holding GmbH and Guala Closures S.p.A occupy positions within the premium functional beverage tier, exemplifying converter archetypes that differentiate through specialized dispensing features rather than commodity volume. Silgan Holdings Inc. represents the North American scale-driven archetype, anchoring high-throughput supply relationships with major carbonated and non-carbonated bottlers. These three entities collectively illustrate how geographic footprint and regulatory proximity shape competitive positioning across the Atlantic divide.
| Leading Market Players |
|---|
| AptarGroup, Inc. |
| BERICAP Holding GmbH |
| Silgan Holdings Inc. |
| Berry Global Inc. |
| Closure Systems International, Inc. |
| United Caps |
| Crown Holdings, Inc. |
| Guala Closures S.p.A |
| Plastipak Holdings Inc. |
| Others |
Value Network & Pricing Analysis
Polypropylene feedstock indices cascading through naphtha and propylene spot markets compress converter margins and force quarterly price adjustment clauses into multi-year bottler contracts. This cost pass-through mechanism stratifies the market into three distinct procurement tiers based on volume scale and certification compliance.
Pricing Analysis
Input-cost pass-through dominates contract structures, with resin price volatility transmitted directly to brand owners through indexed pricing mechanisms. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified recycled content closures from virgin-resin specifications and uncertified imports. Pricing pressure stems from bio-based material validation costs ahead of EU enforcement deadlines. Mass-market bottlers exhibit highest price sensitivity, while premium functional beverage brands absorb certification premiums for tamper-evident and child-resistant designs.
Supply Chain Analysis
Single-source vulnerability sits with specialized high-cavitation injection mold fabricators concentrated in Germany and Japan, creating extended lead times that constrain capacity expansion. Raw material supply draws from Saudi Arabian and Qatari polypropylene feedstock, Brazilian sugarcane-derived bio-polyethylene, and domestic aluminum smelters in China. Tariff exposure threatens cross-border resin flows between major manufacturing clusters. Distribution runs through converter-direct relationships with multinational bottlers, supplemented by regional distributors serving private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with regulatory mandates for sustainable packaging materials ensuring predictable demand displacement toward certified closure suppliers.
For Market Incumbents: Deepen backward integration into resin compounding to secure captive supply of post-consumer recycled polypropylene streams ahead of EFSA notification bottlenecks. Expand high-cavitation molding capacity in North Rhine-Westphalia to defend against Asian competitors leveraging domestic aluminum supply chains. Prioritize in-house regulatory affairs capabilities to absorb compliance burdens falling heaviest on smaller converters. For New Entrants and Emerging Players: The EU Single-Use Plastics Directive in Germany, France, and Italy opens a window for bio-based material specialists to establish toll manufacturing partnerships with bottlers seeking drop-in replacement validation. Target India's Maharashtra and Gujarat corridors ahead of FSSAI packaging regulation implementation. Pursue connected packaging integration as a go-to-market angle, combining NFC-enabled authentication with tamper-evidence for premium sports nutrition subscription channels. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale tamper-evident and child-resistant closure specialists possessing EFSA-compliant production lines but lacking geographic scale. Five-to-ten-year viability hinges on material substitution timelines and extended producer responsibility scheme maturation. Monitor chemical recycling partnership announcements as the primary inflection indicator for converter margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Secures certified recycled polypropylene streams for EU Green Deal compliance ahead of EFSA safety assessments. |
| High-Cavitation Molding Expansion | Addresses 16-24 week tooling lead times that constrain tamper-evident closure program capacity in German clusters. |
| Connected Packaging Integration | Combines NFC-enabled authentication with loyalty-program functionality for premium protein shake brands. |
| Toll Manufacturing Partnership | Enables geographic expansion into India and Southeast Asia without capital-intensive greenfield facility investment. |
| Mono-Material Design Conversion | Eliminates silicone valve components to satisfy automated sortation requirements at materials recovery facilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with closure converter plant managers, brand owner procurement leads, beverage bottler supply chain directors, and regulatory affairs specialists at EFSA and FDA with secondary validation. Sources included customs and trade data on resin and aluminum flows, EU packaging directive implementation timelines, SEC 10-K filings from listed packaging conglomerates, and SAMR food-contact standard notifications. Bottom-up volume modeling from individual converter capacity and top-down demand estimation from beverage production data were triangulated to anchor projections.
Comparable historical periods anchored the forecast window, with growth rates derived from regression analysis against beverage volume trends and regulatory implementation schedules. Segmentation dimensions modeled encompassed product type, material substrate, closure design functionality, and end-user channel across the projection horizon. Industry-specific inputs included bio-based material oxygen transmission rate improvements, chemical recycling capacity buildout timelines, and extended producer responsibility fee structures.
Revisions become necessary when bio-based resin performance achieves full parity with fossil-derived alternatives, when EFSA streamlines novel food-contact substance notification timelines, or when major bottlers accelerate reusable bottle pooling system deployment. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Linerless Closures Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Box Latch Market
Caps and Closures
Cap Liner Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
Shrink Bands Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
United Arab Emirates Plastic Caps and Closures Market
Caps and Closures
Plastic Tamper Evident Closures Market