
 Cap Seals Market | 2026-2036
Cap Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Cap Seals Market Analytics
Polyethylene terephthalate (PET) is shifting from glass and metal in beverage closures, reducing unit weight and transportation costs. Berry Global leverages vertical integration across resin sourcing and thermoforming to sustain cost leadership in North American push-on formats. Amcor anchors premium pharmaceutical induction seal portfolios through multilayer laminate expertise. Crown Holdings competes in aluminum screw-on segments with deep draw-redraw manufacturing scale.
Cap seals are mechanical or adhesive closure devices engineered to 0.1-0.3 mm tolerance ranges, employing compression-set elastomers or heat-activated polymer layers to create hermetic barriers against moisture, oxygen, and microbial ingress. Screw-on caps occupy the largest value pool across food and beverage applications due to resealability requirements and established capping line infrastructure. Induction seals represent the fastest-expanding product category within pharmaceutical packaging, driven by tamper-evidence mandates and extended shelf-life claims for moisture-sensitive drug formulations.
FDA 21 CFR regulations on child-resistant packaging and EMA Annex 1 sterile manufacturing guidelines directly determine material selection and validation protocols for cap seal suppliers. India's CDSCO and BIS standards for pharmaceutical primary packaging are tightening import certification requirements, constraining market access for uncertified foreign manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and state-level plastic content restrictions in the United States to anticipate material substitution timelines and compliance-driven procurement shifts.
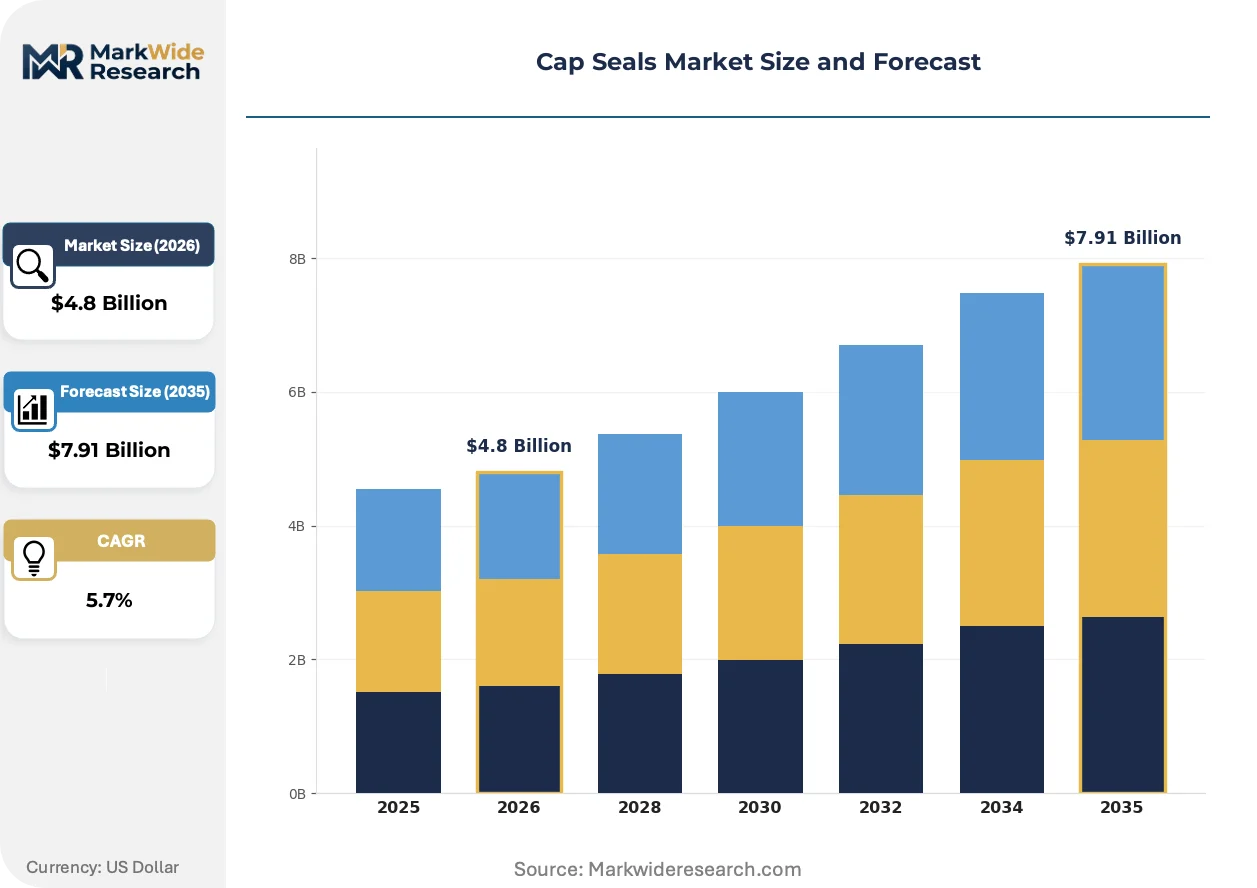
Market Dynamics
Pharmaceutical serialization mandates and child-resistance requirements are restructuring procurement priorities, forcing converters to validate multilayer induction seal formats against tightening FDA and EMA protocols while beverage packers accelerate PET lightweighting programs.
Growth Catalysts
- FDA 21 CFR child-resistant mandates:Pharmaceutical packaging lines must deploy induction-sealed closures for analgesics and prescription containers, expanding validated supplier rosters.
- Polymer substitution in beverage closures:PET compression-molded caps displace metal formats in carbonated soft drinks, cutting unit weights and freight costs for bottlers.
- India's pharmaceutical cluster expansion:CDSCO import certification requirements redirect procurement toward domestic converters with BIS-validated cleanroom capabilities.
Market Restraints
- Resin cost volatility:Polypropylene and polyethylene feedstock prices track naphtha and natural gas liquids, compressing margins for non-integrated converters.
- Aluminum supply concentration:Deep-draw redraw capacity for screw-on beverage closures concentrates among a handful of North American and European metalformers.
- Validation timeline friction:EMA Annex 1 sterile manufacturing guidelines demand 12-18 month qualification cycles for new seal suppliers.
Strategic Opportunities
- Southeast Asian manufacturing relocation:Vietnam and Indonesia offer tariff-advantaged export platforms for pharmaceutical seals serving EU and US markets.
- Connected packaging integration:NFC-enabled induction seals combining tamper evidence with authentication are attracting luxury cosmetics brands.
- EU Green Deal material mandates:Extended producer responsibility frameworks incentivize mono-material PET seal designs eligible for mechanical recycling streams.
Industry Challenges
- Multilayer laminate expertise scarcity:Pharmaceutical induction seals require coextrusion and adhesive lamination skills concentrated among limited technical workforces in Germany and Switzerland.
- Legacy capping line retrofit costs:Beverage bottlers face capital outlays to accommodate lighter-weight PET closure formats on existing high-speed equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cap Seals Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push-On Caps, Screw-On Caps, Snap-Fit Caps, Induction Seals Material: Plastic, Aluminum, Rubber, Composite Application: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals End User: Manufacturers, Distributors, Retailers, Wholesalers |
| Companies Covered | Berry Global, Amcor, Crown Holdings, Silgan Holdings, AptarGroup, Guala Closures, BERICAP, Closure Systems International, RPC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cap Seals Market Evolving Landscape
Digital validation protocols and material traceability systems are compressing supplier qualification timelines while enabling real-time compliance monitoring across pharmaceutical packaging networks.
Laser-etched serialization on induction seal liners is automating track-and-trace compliance for pharmaceutical exporters. Contract packagers in India and Germany are retrofitting lines with vision systems that verify code integrity at 600 units per minute. This automation is compressing the validation window for new drug launches from months to weeks.
EMA's updated Annex 1 sterile manufacturing guidelines now mandate barrier integrity testing for all parenteral packaging seals. European converters are investing in helium leak detection and dye penetration validation suites. Parenteral vial and syringe segments are absorbing these compliance costs through premium pricing on validated multilayer formats.
Direct procurement relationships between pharmaceutical multinationals and specialized seal converters are displacing traditional distributor intermediaries. Large molecule drug manufacturers in Switzerland and Massachusetts now negotiate multi-year supply agreements specifying resin grade and cleanroom certification tier. This channel consolidation is most advanced in biologics packaging, where batch traceability requirements favor sole-source arrangements with vertically qualified suppliers.
Cap Seals Market Segmentation
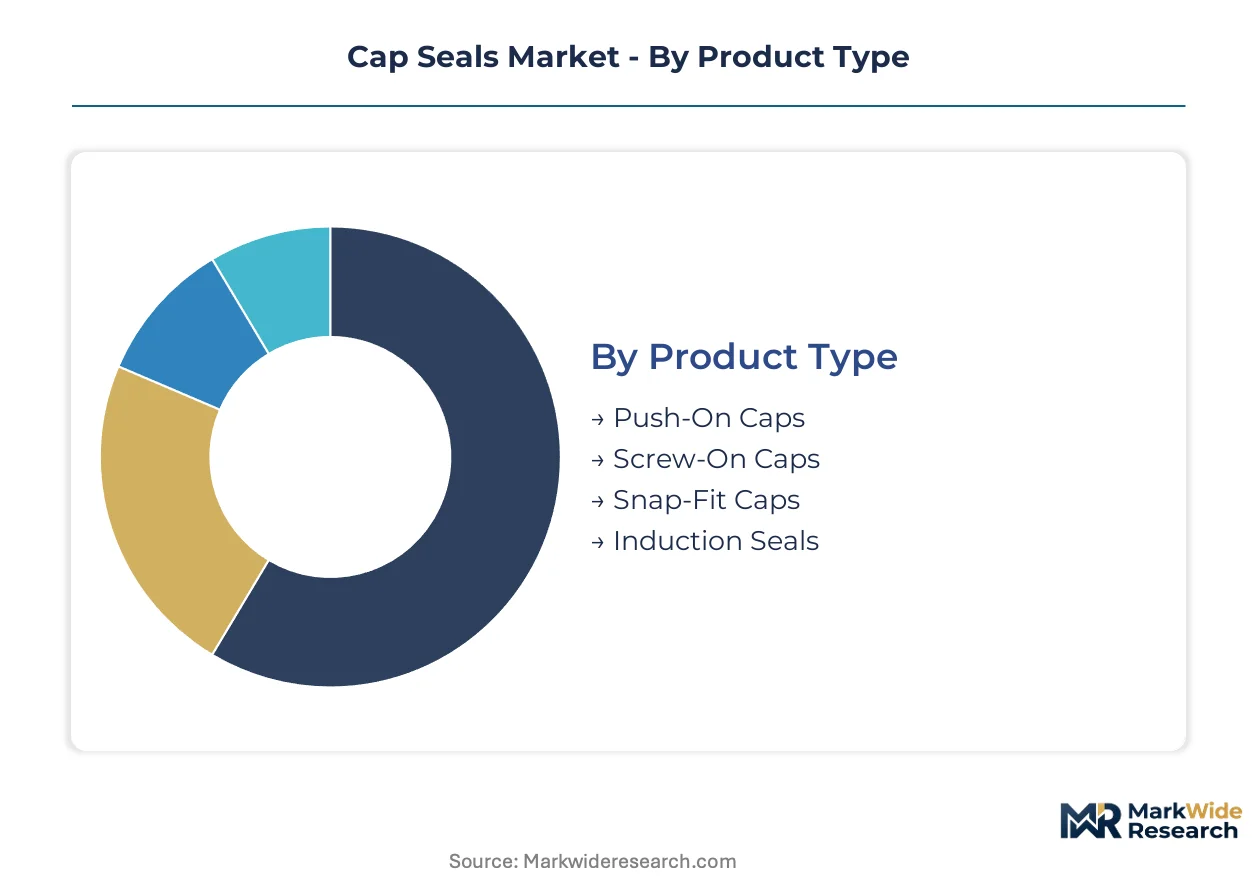
Cap seal procurement patterns diverge sharply across product architectures, material substrates, and regulatory exposure levels. Pharmaceutical serialization mandates and beverage lightweighting programs are fragmenting supplier portfolios into specialized validation tiers.
Product Type:
Supply concentration for validated pharmaceutical formats sits with European and North American converters holding FDA Master File registrations, while beverage closures face margin compression from resin volatility.
- Screw-On Caps:Threaded closure systems employing compression-set elastomeric liners achieve 0.1-0.3 mm torque tolerances for repeatable hermetic sealing. Demand concentrates in Germany's chemical corridor and India's pharmaceutical clusters, where resealability requirements and established capping infrastructure sustain volume leadership despite aluminum supply bottlenecks.
- Induction Seals:Multilayer laminate structures fuse aluminum foil to heat-activated polymer substrates, creating tamper-evident barriers via electromagnetic induction. FDA child-resistance mandates for analgesics and EMA Annex 1 sterile manufacturing guidelines are accelerating qualification cycles for parenteral drug applications in Switzerland and Massachusetts biologics corridors.
- Push-On Caps:Compression-fit designs for single-serve beverage containers leverage PET lightweighting to cut freight costs.
- Snap-Fit Caps:Integral hinge mechanisms serve cosmetics and household chemical segments requiring one-handed dispensing.
Today's leader: Screw-On Caps. Tomorrow's challenger: Induction Seals.
Material:
Cost tier differentiation separates commodity resin converters from premium laminate specialists with cleanroom certification.
- Plastic:Polypropylene and polyethylene compression-molded caps dominate beverage volumes through PET substitution programs displacing metal formats. Berry Global's captive resin sourcing sustains cost leadership in North American push-on segments despite naphtha feedstock volatility.
- Aluminum:Deep-draw redraw manufacturing for screw-on beverage closures concentrates among limited North American and European metalformers, constraining capacity expansion for craft brewery and sparkling water segments.
- Rubber:Chlorobutyl and bromobutyl elastomers serve parenteral vial seals requiring gas barrier properties.
- Composite:Multilayer induction seal constructions combine foil, polymer, and adhesive layers for pharmaceutical barrier integrity.
Plastic commands current volume. Composite commands future premium.
Application:
Regulatory intensity determines margin structure, with pharmaceutical validation requirements creating defensible supplier moats.
- Pharmaceuticals:Induction-sealed closures for oral solids and parenteral packaging must demonstrate child-resistance per FDA 21 CFR and barrier integrity per EMA Annex 1. CDSCO import certification requirements in India are redirecting procurement toward domestic converters with BIS-validated cleanroom capabilities.
- Food & Beverage:Carbonated soft drink bottlers accelerate PET compression-molded cap adoption to reduce unit weights and transportation costs, retrofitting legacy high-speed capping lines for lighter formats.
- Cosmetics:Luxury brands pilot NFC-enabled induction seals combining tamper evidence with authentication functionality.
- Chemicals:Agrochemical and industrial solvent packaging requires chemical-resistant screw-on formats with vented liner options.
Pharmaceuticals set the margin ceiling. Food & Beverage sets the volume floor.
End User:
Channel consolidation favors direct procurement relationships between pharmaceutical multinationals and vertically qualified seal converters.
- Manufacturers:Large molecule drug producers in Switzerland and Massachusetts negotiate multi-year supply agreements specifying resin grade and cleanroom certification tier, displacing traditional distributor intermediaries through sole-source arrangements.
- Distributors:Generalist packaging distributors retain relevance in beverage and cosmetics segments with lower validation barriers.
- Retailers:Private-label food brands source standard screw-on formats through consolidated procurement.
- Wholesalers:Regional chemical packaging intermediaries serve fragmented agrochemical formulators.
Manufacturers capture strategic value. Distributors capture transactional volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's chemical corridor anchors pharmaceutical screw-on cap demand, while India's pharmaceutical clusters redirect procurement toward domestic converters under tightening import certification rules. FDA child-resistance mandates in the United States and EMA serialization requirements in Switzerland are restructuring validated supplier rosters across three continents.
United States
FDA 21 CFR child-resistant packaging mandates for analgesics and prescription containers are expanding induction-sealed closure volumes. Massachusetts biologics corridors negotiate multi-year supply agreements specifying cleanroom certification tiers. Berry Global leverages vertical integration across resin sourcing to sustain cost leadership in North American push-on formats.
Germany
Screw-on cap demand concentrates in the chemical corridor serving industrial solvent and agrochemical packaging segments. EMA Annex 1 sterile manufacturing guidelines demand barrier integrity testing for parenteral seals. Heidelberg and Mannheim host converters investing in helium leak detection validation suites for pharmaceutical applications.
India
CDSCO import certification requirements are redirecting procurement toward domestic converters with BIS-validated cleanroom capabilities. Maharashtra and Gujarat pharmaceutical clusters absorb compliance costs through premium pricing on validated multilayer formats. Mumbai-based contract packagers retrofit lines with vision systems verifying code integrity at high speeds.
Switzerland
Large molecule drug manufacturers negotiate sole-source arrangements with vertically qualified seal suppliers. Swissmedic regulations on sterile manufacturing reinforce barrier integrity requirements for parenteral vial seals. Basel biologics corridors favor direct procurement relationships displacing traditional distributor intermediaries.
China
NMPA serialization requirements and GB standards for pharmaceutical primary packaging are tightening domestic certification barriers. Yangtze River Delta manufacturing bases supply PET compression-molded caps displacing metal formats in carbonated soft drinks. Shanghai converters face margin compression from polypropylene feedstock tracking naphtha volatility.
Cap Seals Market Competitive Landscape
Global majors compete with regional champions across validation tiers and material substrates. The vendor base separates into consolidated laminate specialists holding FDA Master File registrations and fragmented resin converters serving beverage lightweighting programs. Three archetypes dominate: vertically integrated resin-to-closure operators, multilayer induction seal specialists with cleanroom certification, and aluminum deep-draw metalformers with redraw manufacturing scale. Capacity expansion and strategic partnerships represent the dominant competitive moves as converters seek geographic diversification and qualification timeline compression.
Among North American packaging conglomerates, Berry Global and Amcor exemplify contrasting strategic positions. Berry Global anchors cost leadership in commodity resin formats through captive supply chains. Amcor occupies a position within premium pharmaceutical portfolios leveraging multilayer laminate expertise. Crown Holdings represents the metalforming archetype competing in aluminum screw-on segments.
| Leading Market Players |
|---|
| Berry Global |
| Amcor |
| Crown Holdings |
| Silgan Holdings |
| AptarGroup |
| Guala Closures |
| BERICAP |
| Closure Systems International |
| RPC Group |
| Others |
Value Network & Pricing Analysis
Captive resin sourcing by Berry Global and Amcor anchors supply position and pricing power across North American beverage and pharmaceutical cap seal tiers. This backward integration into polypropylene feedstock insulates converters from naphtha volatility while enabling premium capture on FDA-validated induction seal formats.
Pricing Analysis
Polypropylene and polyethylene feedstock pass-through dominates contract negotiations for non-integrated beverage converters. Three-tier pricing structure across premium, standard, and economy levels separates FDA Master File holders from commodity resin molders. Cost compression in standard-tier push-on caps is intensifying because of PET lightweighting mandates and freight cost reduction targets. Beverage bottlers exhibit highest price sensitivity, while Swiss biologics manufacturers accept premium multilayer laminates for parenteral barrier integrity.
Supply Chain Analysis
Regional distribution centers in Germany, India, and the United States feed hub-and-spoke patterns serving pharmaceutical clusters and chemical corridors. Manufacturing draws from aluminum deep-draw redraw capacity concentrated among North American and European metalformers, plus multilayer laminate expertise anchored in Germany and Switzerland. Single-source vulnerability for parenteral-grade chlorobutyl elastomers creates qualification bottlenecks. Distribution runs through direct procurement relationships between pharmaceutical multinationals and vertically qualified converters, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cap seals market functions as a regulatory compounder, with FDA 21 CFR child-resistance mandates and EMA Annex 1 sterile manufacturing guidelines continuously expanding validated supplier rosters and premium pricing tiers.
For Market Incumbents: Deploy certification tier expansion to defend against Southeast Asian entrants targeting EU and US pharmaceutical export markets. Incumbents should deepen backward integration into resin sourcing and accelerate helium leak detection validation suite investments in Heidelberg and Mannheim to compress EMA qualification timelines. Barrier integrity testing capabilities represent the critical lever for sole-source arrangements with Swiss biologics manufacturers. For New Entrants and Emerging Players: NFC-enabled tamper-evident authentication offers a technology-first wedge into luxury cosmetics packaging, where brand protection budgets exceed pharmaceutical cost sensitivity. Vietnam and Indonesia tariff-advantaged export platforms present white-space targets for induction seals serving EU serialization requirements. Contract packaging partnerships with Mumbai-based vision system retrofitters provide the fastest go-to-market path for CDSCO-certified domestic supply to Maharashtra pharmaceutical clusters. For Investors and Strategic Acquirers: Roll-up economics work for multilayer induction seal specialists because FDA Master File registrations and EMA validation cycles create defensible moats against commodity competition. Platform consolidation across German and Swiss converters with cleanroom certification tiers offers 5-10 year viability under continued regulatory tightening. Watch for CDSCO import certification deadline acceleration as the inflection signal redirecting procurement toward BIS-validated domestic Indian manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Master File Registration | Validates induction seal suppliers for child-resistant analgesic packaging mandates. |
| Helium Leak Detection Suite Investment | Enables EMA Annex 1 compliance for parenteral barrier integrity testing in Basel. |
| Southeast Asian Manufacturing Relocation | Positions Vietnam converters for tariff-advantaged pharmaceutical seal exports to EU markets. |
| NFC-Enabled Authentication Integration | Captures luxury cosmetics brand budgets combining tamper evidence with digital verification. |
| Direct Procurement Channel Consolidation | Displaces distributor intermediaries through sole-source agreements with Massachusetts biologics corridors. |
Research Methodology
Multiple input streams — primary interviews with packaging procurement managers, regulatory affairs leads at pharmaceutical multinationals, and cleanroom operations directors; secondary validation through FDA 510(k) filings, EMA submission databases, and CDSCO import certification records; plus customs trade data and SEC 10-K disclosures from listed converters — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from plant engineers and category buyers to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include product architecture, material substrate, regulatory exposure tier, and end-use application intensity. CAGRs were derived from trend extrapolation moderated by validation cycle friction and resin cost elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA Annex 1 guideline revisions, polypropylene feedstock volatility, and CDSCO certification timeline shifts. Outputs reflect documented assumptions about regulatory enforcement intensity and material substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
PET Dome Lids Market
Caps and Closures
PCR Closures Market
Caps and Closures
Nigeria Plastic Caps and Closures Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
Dispensing Caps Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Lug Caps Market
Caps and Closures
Heat Shrink Bands Market
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
Snap-On Closures Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Saudi Arabia Plastic Caps and Closures Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
End Cap Market