
 Canada Plastic Caps and Closures Market | 2026-2036
Canada Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Plastic Caps and Closures Market Insights
A shift from single-source resin supply contracts to multi-source procurement is broadening the vendor base for Canadian converters. Berry Global, Inc. leverages its North American resin hedging infrastructure to stabilize input costs across Ontario plants. Silgan Holdings, Inc. anchors its position through captive blow-molding capacity in the province. TricorBraun Canada competes by maintaining specialized distribution channels for mid-tier beverage clients.
Plastic caps and closures are threaded or snap-fit sealing devices molded from thermoplastic resins, typically featuring land widths of 28 mm to 38 mm for standard beverage bottles and torque-release specifications measured in inch-pounds. Their primary purpose is to preserve product integrity, enable controlled dispensing, and satisfy retail shelf-life requirements across liquid and semi-solid consumer goods. Screw caps dominate volume in carbonated soft drinks and bottled water, where cost efficiency and line-speed compatibility matter most. Dispensing closures represent the fastest-growing category in household products, driven by pump-actuated and flip-top formats that reduce waste and improve dosing precision. Polypropylene leads material selection for hot-fill applications due to its thermal stability and chemical resistance against acidic beverages.
Health Canada enforces child-resistant packaging standards under the Consumer Chemicals and Containers Regulations, directly shaping closure design requirements for household and pharmaceutical products. Environment and Climate Change Canada's plastics registry and proposed extended producer responsibility frameworks are pressuring converters to incorporate post-consumer recycled content into cap formulations. Stakeholders must monitor how provincial blue-box modernization in Ontario and British Columbia alters resin certification requirements and sorting infrastructure investments.
Market Dynamics
Extended producer responsibility frameworks in Ontario and British Columbia are forcing converters to redesign cap formulations around post-consumer recycled content thresholds, compressing margins while demanding capital retooling across the Greater Toronto Area's molding corridor.
Growth Catalysts
- Health Canada child-resistance mandates:Tightened packaging standards for pharmaceuticals and household chemicals are driving replacement cycles for non-compliant legacy closures.
- Tamper-evident technology:Beverage bottlers in Ontario and Quebec are expanding procurement of break-band and induction-seal formats for premium water and ready-to-drink categories.
- Hot-fill compatibility:Polypropylene's thermal stability above 85°C is enabling expansion into acidic juice and functional beverage segments previously served by glass.
Market Restraints
- Resin price volatility:Polypropylene and polyethylene input costs fluctuate with Alberta petrochemical feedstock pricing and US Gulf Coast supply disruptions.
- Sorting infrastructure gaps:Provincial blue-box modernization lags behind PCR content mandates, creating certification bottlenecks for converters seeking recycled resin verification.
- Aluminum substitution:Craft beverage producers are piloting crown cork and screw-cap metal alternatives for perceived sustainability premiums.
Strategic Opportunities
- Dispensing closure expansion:Pump-actuated and flip-top formats for household cleaners represent underpenetrated share in Prairie province retail channels.
- Regulatory tailwinds:Environment and Climate Change Canada's plastics registry creates first-mover advantage for converters with verified PCR supply chains.
- Smart packaging convergence:Near-field communication chips embedded in pharmaceutical caps are automating adherence tracking for Health Canada-regulated products.
Industry Challenges
- Mold maintenance expertise:Multi-cavity hot-runner systems for 28 mm beverage closures require specialized technicians scarce in Quebec's secondary labor markets.
- Compliance timeline compression:Child-resistance certification cycles under Consumer Chemicals and Containers Regulations now exceed typical product development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Plastic Caps and Closures Market |
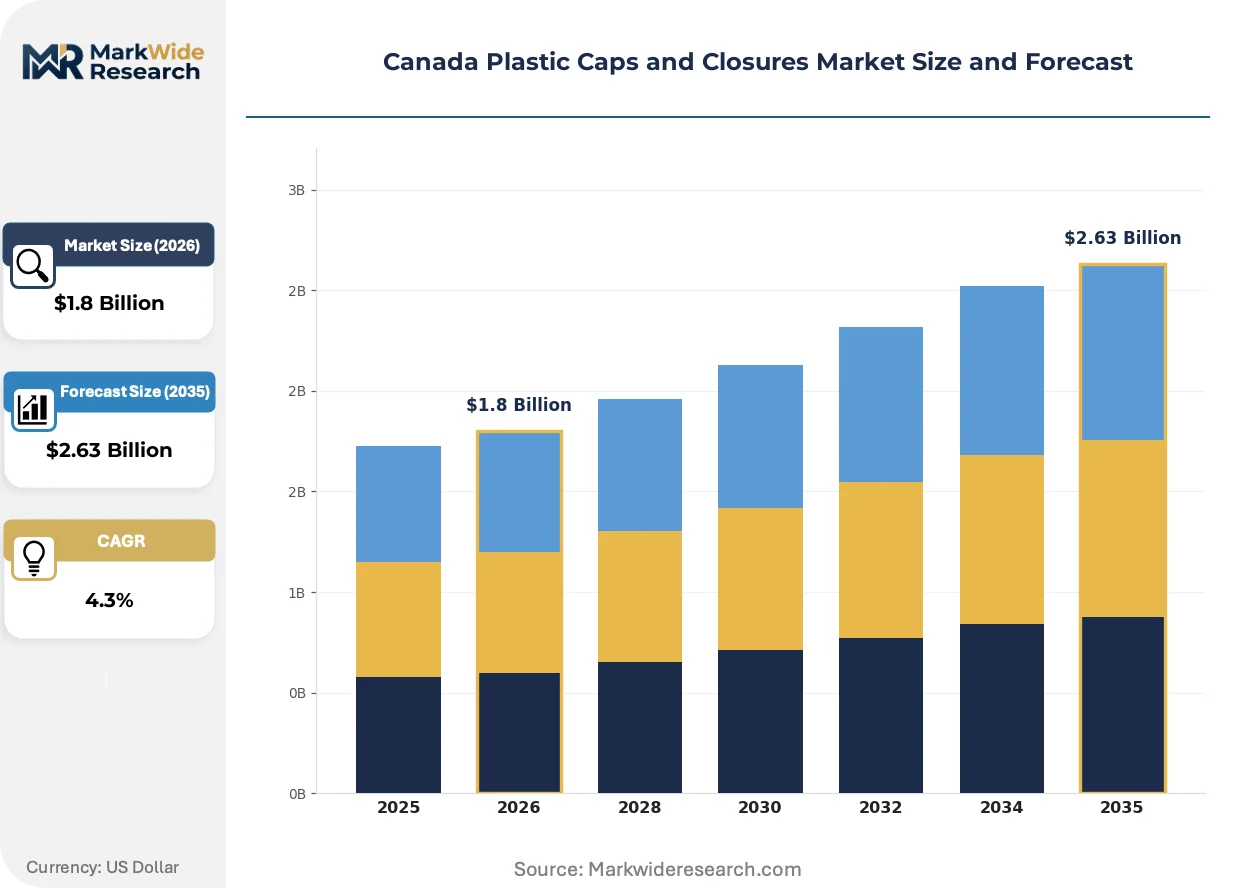
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.63 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-on Caps, Dispensing Closures, Flip-top Caps End User: Beverages, Pharmaceuticals, Food Packaging, Household Products Material: Polyethylene, Polypropylene, Polystyrene, PVC Closure Design: Child-resistant, Tamper-evident, Easy-open, Custom shapes |
| Companies Covered | Berry Global, Inc., TricorBraun Canada, Silgan Holdings, Inc., Amcor Plc, Pano Cap Canada Ltd., Bericap Inc., Polytainers Inc., Phoenix Closures, Inc., IPL Plastics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Plastic Caps and Closures Market Trends and Innovations
Automation and material science are converging to reshape Canadian closure manufacturing, with regulatory pressure accelerating adoption of verification technologies and recycled feedstock integration.
Vision-guided robotic sorting is automating quality control for post-consumer regrind streams at Ontario recycling facilities. Blow-molding operators in the Golden Horseshoe are retrofitting lines with spectral resin identification to maintain PCR purity thresholds. This automation is compressing certification timelines for converters supplying Loblaws and Sobeys private-label programs.
Health Canada's Consumer Chemicals and Containers Regulations are mandating torque-release testing protocols that exceed previous voluntary standards. Pharmaceutical contract packagers in Mississauga are redesigning senior-friendly child-resistant formats to meet dual accessibility requirements. The household products segment bears the heaviest compliance burden, with reformulation costs concentrated among mid-tier Ontario converters.
Beverage procurement is consolidating around direct converter relationships that bypass traditional distribution intermediaries. Craft breweries in British Columbia's Okanagan Valley are negotiating specification-grade contracts for custom 38 mm closures. This disintermediation is most pronounced in Western Canada, where regional bottlers seek faster turnaround on seasonal SKUs than national distributors provide.
Canada Plastic Caps and Closures Market Segmentation
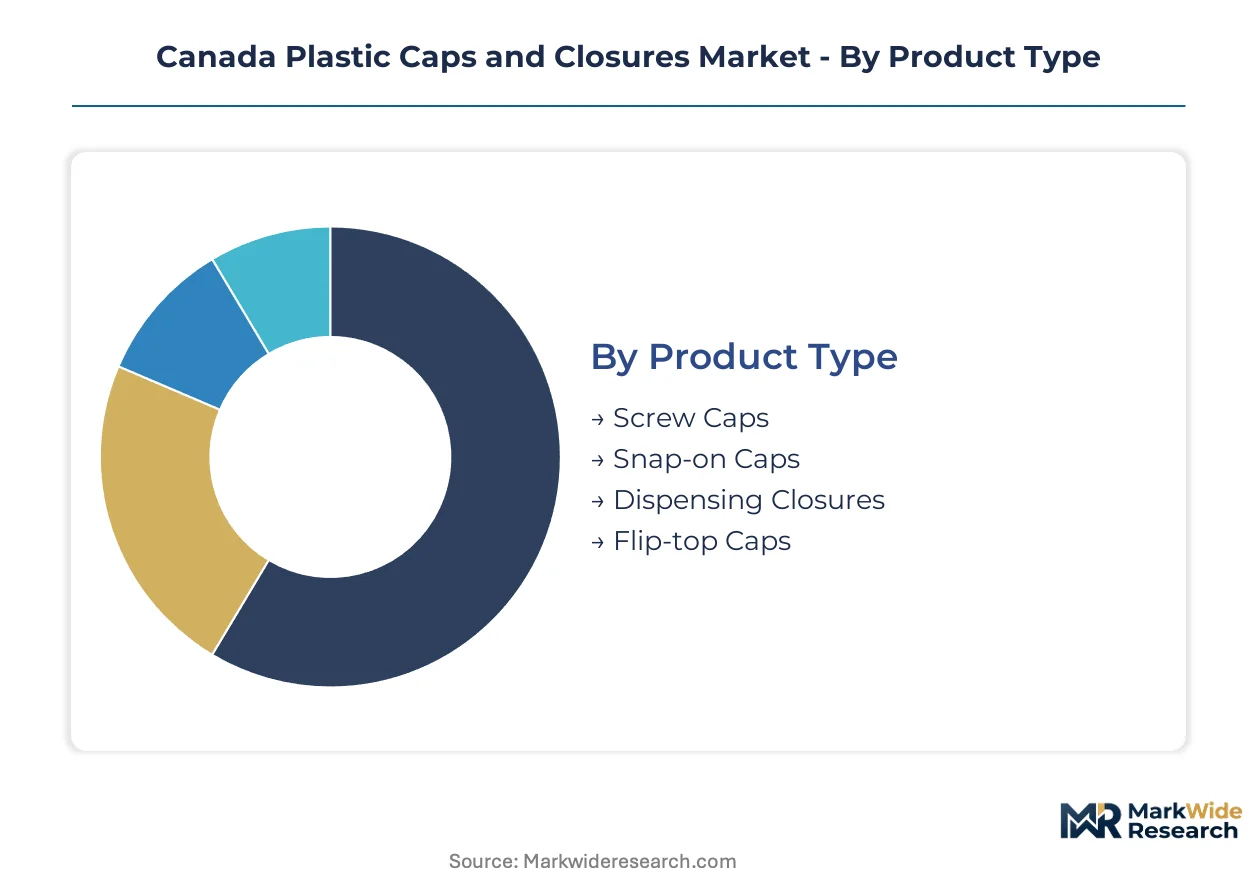
Segmentation in the Canadian plastic caps and closures market reveals how regulatory pressure and end-use requirements fragment manufacturing capabilities. Converters must align resin selection, torque specifications, and certification pathways with distinct procurement channels across beverages, pharmaceuticals, and household chemicals.
Product Type:
Screw caps dominate volume procurement for carbonated beverages and bottled water, while dispensing closures command premium positioning in functional drinks and household products. The cost-to-performance spectrum separates commodity threaded formats from specialized actuated designs.
- Screw Caps:Threaded closures molded from polypropylene or HDPE with standardized 28 mm and 38 mm land widths. Beverage bottlers in Ontario's Golden Horseshoe specify these for line-speed compatibility exceeding 1,200 bottles per minute on rotary capping equipment.
- Dispensing Closures:Pump-actuated and flip-top mechanisms enabling controlled dosing for viscous liquids. Prairie province retailers are expanding shelf space for these formats in concentrated cleaner and personal care categories where waste reduction drives repurchase rates.
- Snap-on Caps:Press-fit designs common in dairy and refrigerated juice applications requiring hermetic seals without torque application.
- Flip-top Caps:Hinged single-piece constructions popular in sports drinks and condiments, balancing convenience with material efficiency.
Mature deployment sits with screw caps across mass-market beverage lines. Newer deployment is concentrated in dispensing closures for premium household and personal care brands.
End User:
Application requirements dictate resin certification, torque tolerances, and regulatory compliance intensity. Pharmaceutical and household chemical segments impose the strictest child-resistance mandates, while food and beverage procurement prioritizes line efficiency and tamper-evidence.
- Beverages:Carbonated soft drinks, bottled water, juices, and ready-to-drink formulations requiring pressure retention and induction-seal compatibility. Quebec and Ontario bottlers are consolidating procurement around direct converter relationships for seasonal SKU flexibility.
- Pharmaceuticals:Prescription and over-the-counter medications subject to Health Canada child-resistance protocols. Mississauga contract packagers are redesigning senior-friendly formats to satisfy dual accessibility requirements under tightened Consumer Chemicals and Containers Regulations.
- Food Packaging:Condiments, sauces, and dairy applications where oxygen barrier properties and hot-fill stability determine resin selection.
- Household Products:Cleaners, solvents, and automotive chemicals bearing the heaviest compliance burden for chemical resistance and child-safety certification.
Volume concentrates in beverage procurement across the Greater Toronto Area corridor. Margin expansion is accelerating most quickly in pharmaceutical closures where regulatory barriers limit qualified supplier pools.
Material:
Resin selection balances thermal performance, chemical resistance, and post-consumer recycled content compatibility. Alberta petrochemical feedstock pricing directly influences converter margins across material categories.
- Polypropylene:Semi-crystalline thermoplastic with thermal stability above 85°C enabling hot-fill juice and functional beverage applications. Its chemical resistance against acidic formulations displaces glass in premium segments.
- Polyethylene:HDPE and LDPE grades dominating cold-fill beverage and dairy applications where flexibility and impact resistance outweigh thermal demands.
- Polystyrene:Crystal and impact grades for cosmetic and pharmaceutical applications requiring rigidity and moisture barrier properties.
- PVC:Specialized formulations for chemical resistance in industrial and agricultural chemical packaging, though facing substitution pressure from polyolefin alternatives.
Polypropylene anchors premium positioning in hot-fill and pharmaceutical segments. Polyethylene maintains volume leadership in standard beverage and food applications.
Closure Design:
Design complexity escalates with regulatory stringency and end-user accessibility requirements. Health Canada mandates and provincial extended producer responsibility frameworks are accelerating design refresh cycles.
- Child-resistant:Push-and-turn or squeeze-and-turn mechanisms requiring coordinated force application. Health Canada's tightened testing protocols are extending certification timelines for Ontario converters serving pharmaceutical and household chemical markets.
- Tamper-evident:Break-band rings and induction-seal liners providing visual evidence of package integrity. British Columbia craft beverage producers are specifying custom 38 mm formats for premium positioning.
- Easy-open:Reduced torque and ergonomic profiles for senior-accessible pharmaceutical and food applications.
- Custom shapes:Proprietary geometries for brand differentiation in premium spirits and functional beverages.
Regulatory compliance drives child-resistant and tamper-evident deployment in pharmaceutical and household channels. Brand differentiation is expanding most quickly in custom shapes for craft beverage and premium personal care segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian demand for plastic caps and closures concentrates in Ontario's Golden Horseshoe and Quebec's industrial corridor, where beverage bottlers and pharmaceutical packagers drive procurement volumes. Provincial extended producer responsibility frameworks are reshaping converter operations across all major manufacturing regions.
Ontario
Beverage bottlers in the Greater Toronto Area are expanding tamper-evident closure procurement for premium water and ready-to-drink categories. Health Canada's tightened child-resistance standards under the Consumer Chemicals and Containers Regulations are forcing Mississauga pharmaceutical contract packagers to redesign senior-friendly formats. The Golden Horseshoe molding corridor hosts the highest concentration of multi-cavity hot-runner systems for 28 mm beverage closures.
Quebec
Food processing clusters in Montreal and surrounding regions generate sustained demand for hot-fill compatible polypropylene closures. The province's blue-box modernization program is accelerating post-consumer recycled content mandates for converters serving Loblaws and Sobeys private-label programs. Specialized mold maintenance technicians remain scarce in secondary labor markets outside Montreal.
British Columbia
Craft beverage producers in the Okanagan Valley are piloting specification-grade contracts for custom 38 mm closures, bypassing traditional distribution intermediaries. Environment and Climate Change Canada's plastics registry is pressuring Vancouver-area converters to verify PCR supply chains ahead of provincial deadlines. Direct converter relationships are expanding fastest in Western Canada for seasonal SKU flexibility.
Alberta
Petrochemical feedstock pricing from Alberta's industrial heartland directly influences polypropylene and polyethylene input costs for converters nationwide. Prairie province retailers are expanding shelf space for dispensing closures in concentrated cleaner categories. Calgary and Edmonton distribution hubs are consolidating procurement for mid-tier household product brands seeking waste-reduction formats.
Atlantic Canada
Seafood processing and dairy applications in Nova Scotia and New Brunswick sustain demand for snap-on and hermetic seal closures. Regional converters are adapting to Environment and Climate Change Canada's extended producer responsibility timelines with limited local recycling infrastructure. Halifax serves as the primary Atlantic gateway for imported closure technologies serving niche pharmaceutical packaging requirements.
Canada Plastic Caps and Closures Market Competitive Landscape
Capacity expansion dominates the current landscape as converters retool for post-consumer recycled content thresholds. The vendor base stratifies across three tiers: multinational resin-hedging specialists with captive blow-molding infrastructure, mid-tier regional fabricators with specialized distribution channels, and niche custom-mold operators serving craft beverage segments. Strategic archetypes include scale-driven resin stabilizers, compliance-focused pharmaceutical specialists, and agility-oriented seasonal SKU suppliers. Competitive moves center on multi-source procurement transitions and direct converter relationships that disintermediate traditional distributors.
Among North American headquartered operators, Berry Global, Inc. and Silgan Holdings, Inc. exemplify the scale-driven archetype with integrated resin management capabilities. TricorBraun Canada occupies a position within the specialized distribution tier, serving mid-tier beverage clients through targeted channel relationships. These three entities represent contrasting strategic postures: resin-hedging vertical integration, captive manufacturing capacity, and distribution-centric flexibility.
| Leading Market Players |
|---|
| Berry Global, Inc. |
| TricorBraun Canada |
| Silgan Holdings, Inc. |
| Amcor Plc |
| Pano Cap Canada Ltd. |
| Bericap Inc. |
| Polytainers Inc. |
| Phoenix Closures, Inc. |
| IPL Plastics |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between Health Canada-compliant child-resistant closures and commodity beverage screw caps manifests in both pricing power and supply chain configuration. Premium pharmaceutical formats command resin hedging and dedicated mold maintenance infrastructure, while standard beverage closures compete on Alberta feedstock-linked spot pricing and line-speed throughput.
Pricing Analysis
Volume concentrates in 28 mm screw caps for carbonated beverages and bottled water, where polypropylene spot pricing from Alberta petrochemical feedstock governs margins. Margin expansion concentrates in child-resistant pharmaceutical closures, where Health Canada certification timelines and specialized torque-release testing create supplier scarcity. Cost compression intensifies in household product segments as Environment and Climate Change Canada's PCR content mandates force reformulation investment. Beverage bottlers in Ontario's Golden Horseshoe exhibit highest price sensitivity, while Mississauga pharmaceutical contract packagers prioritize compliance assurance over unit cost.
Supply Chain Analysis
Regional distribution centers in Calgary, Toronto, and Vancouver anchor hub-and-spoke patterns for resin delivery and finished closure shipment. Manufacturing concentrates in Ontario's Golden Horseshoe, Quebec's Montreal corridor, and British Columbia's Lower Mainland. Raw material dependencies rest on Alberta propylene feedstock, US Gulf Coast polyethylene supply, and post-consumer regrind streams from provincial blue-box programs. Single-source vulnerability runs through specialized hot-runner mold components sourced from German and Japanese precision engineering suppliers. Distribution runs through direct converter relationships that disintermediate traditional wholesale channels, particularly for craft beverage producers in British Columbia's Okanagan Valley.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada plastic caps and closures market sits in a material-transition phase, with post-consumer recycled content mandates displacing virgin resin formulations and automated quality verification replacing manual inspection protocols.
For Market Incumbents: Anchor market position through captive blow-molding capacity expansion in Ontario and Quebec, paired with spectral resin identification systems that accelerate PCR certification timelines. Aluminum substitution threats from craft beverage metal crown cork pilots demand counter-positioning through tamper-evident induction-seal innovation. Backward integration into Alberta resin hedging infrastructure stabilizes input cost volatility against US Gulf Coast supply disruptions. For New Entrants and Emerging Players: Capture white-space opportunity in Prairie province dispensing closure distribution, where concentrated cleaner categories remain underpenetrated by pump-actuated formats. British Columbia's direct converter relationship trend offers entry path through seasonal SKU agility for craft beverage producers. Go-to-market angle should emphasize rapid custom 38 mm specification turnaround versus national distributor lead times. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to North American packaging conglomerates seeking Health Canada certification capabilities and Golden Horseshoe manufacturing footprint. Long-term viability favors converters with verified PCR supply chains and pharmaceutical torque-release testing infrastructure. Watch provincial blue-box modernization timelines as inflection indicator for recycled resin certification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| PCR Supply Chain Verification | Environment and Climate Change Canada's plastics registry rewards first-movers with certified post-consumer recycled content streams. |
| Hot-Runner Mold Retrofit | Multi-cavity systems for 28 mm beverage closures improve line-speed compatibility with rotary capping equipment at Ontario bottlers. |
| Child-Resistance Certification Investment | Health Canada's tightened Consumer Chemicals and Containers Regulations extend qualified supplier scarcity in pharmaceutical segments. |
| Direct Converter Relationship Expansion | Bypassing distribution intermediaries captures craft beverage procurement in British Columbia's Okanagan Valley seasonal SKU cycles. |
| Spectral Resin Identification Deployment | Automated quality control for post-consumer regrind streams compresses certification timelines for Loblaws and Sobeys private-label programs. |
Research Methodology
Document review covered trade association filings, Environment and Climate Change Canada regulatory notices, and provincial extended producer responsibility framework documents, complemented by interviews with plant managers at Ontario and Quebec molding facilities, procurement leads at beverage bottlers, pharmaceutical contract packaging executives, and distribution channel partners. Secondary validation drew from customs and trade data, SEC 10-K disclosures of North American packaging conglomerates, and Health Canada regulatory guidance documents. Bottom-up capacity and demand estimates were triangulated against top-down market sizing from resin consumption patterns.
Cross-referencing historical pricing volatility against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-use application, material grade, and closure design complexity, with provincial regulatory cluster as an additional geographic dimension. CAGRs were derived from trend extrapolation adjusted for regulatory implementation timelines and capital expenditure cycles in molding infrastructure. Industry-specific forecast inputs incorporated Alberta petrochemical feedstock pricing sensitivity and Health Canada certification backlog estimates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to provincial blue-box modernization delays, US Gulf Coast resin supply disruptions, and aluminum substitution acceleration in craft beverage segments. Forecasts reflect documented assumptions around regulatory implementation timelines and recycling infrastructure investment rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Twist Caps Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
PCR Closures Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Polypropylene Screw Caps Market
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
Cap Liner Market
Caps and Closures
Global Aluminum Caps for Packaging Market
Caps and Closures
Non-Aerosol Overcaps Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
Snap-On Closures Market
Caps and Closures
Beverage Caps and Closures Market