
 Meat Protein Chips Market | 2026-2036
Meat Protein Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Protein Chips Market Insights
Retail shelf-space allocation from conventional salty snacks toward functional protein alternatives is reshaping margin distribution across the snacking aisle. Jack Link's leverages its jerky manufacturing infrastructure to dominate beef chip production at scale. Hormel Foods Corporation anchors its position through backward integration into pork processing, securing captive supply of raw material. Quest Nutrition differentiates via formulation science developed for its legacy protein bar portfolio.
Meat protein chips are thin-sliced or extruded dried meat products, typically containing 10–15 grams of protein per serving, manufactured through low-temperature dehydration or high-pressure extrusion to preserve amino acid integrity and achieve brittle texture. Their primary commercial purpose is to deliver portable, shelf-stable protein consumption occasions beyond refrigerated meat snacks. Beef chips occupy the dominant revenue position due to established consumer familiarity with bovine jerky formats and higher per-unit protein density. Online retailers represent the fastest-expanding sales channel as direct-to-consumer subscription models reduce retail slotting fee burdens and enable flavor customization. Pouch packaging commands margin preference for its lightweight shipping economics and resealability.
USDA Food Safety and Inspection Service regulations mandate pathogen controls and labeling standards that elevate compliance costs for new entrants. FDA nutrition labeling requirements under the Nutrition Facts panel govern protein content claims and serving size disclosures, directly influencing front-of-package marketing strategies. Stakeholders must monitor evolving positions on processed meat classifications by WHO and national health authorities, as advisory shifts could redirect consumer preference toward poultry-based alternatives or plant-blended formulations.
Market Dynamics
Retail shelf-space reallocation from conventional salty snacks toward functional protein alternatives is compressing margin structures and forcing incumbent snack manufacturers to defend position through rapid portfolio pivots into meat-based formats.
Growth Catalysts
- USDA FSIS Pathogen Control Standards:Elevated compliance requirements filter out subscale competitors, consolidating shelf access for certified processors with existing inspection infrastructure.
- Fitness-Tracking Integration:Wearable device ecosystems now surface protein intake metrics, creating automated demand triggers for portable high-protein snacks among quantified-self consumers.
- Dehydration Technology Maturation:Low-temperature vacuum drying systems preserve amino acid profiles while achieving brittle textures that replicate conventional chip mouthfeel.
Market Restraints
- Beef Input Cost Volatility:Feedlot capacity constraints and drought cycles in the Great Plains generate raw material price swings that compress processor margins.
- Cold Chain Dependency:Pre-dehydration meat handling requires refrigerated logistics, limiting production site flexibility and elevating energy costs.
- WHO Processed Meat Classifications:Advisory positions linking cured meat consumption to health risks create consumer hesitation and complicate front-of-package messaging.
Strategic Opportunities
- Poultry-Based Formulation Expansion:Turkey and chicken chips carry lower processed-meat stigma while delivering comparable protein density per serving.
- Subscription Direct-to-Consumer Channels:Recurring revenue models bypass slotting fee structures and enable flavor customization based on consumption pattern data.
- Clean-Label Processing Certification:Third-party validation of minimal-ingredient formulations commands price premiums in natural grocery channels.
Industry Challenges
- Food Safety Culture Implementation:USDA mandates for hazard analysis training create persistent workforce development burdens for mid-scale processors.
- Extrusion Equipment Lead Times:High-pressure forming machinery faces 12-18 month delivery backlogs, constraining capacity expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Protein Chips Market |
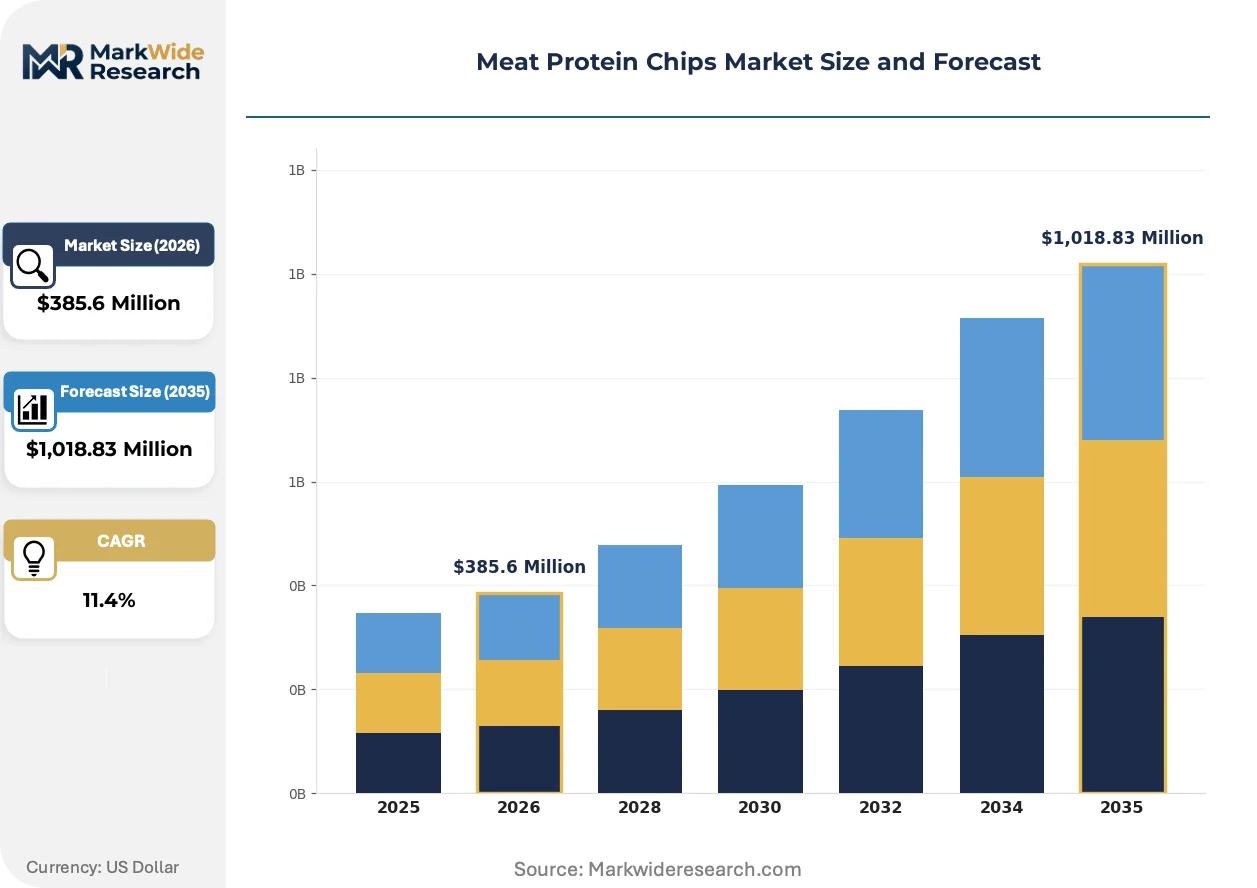
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,018.83 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef Chips, Pork Chips, Chicken Chips, Turkey Chips Flavor Profile: Barbecue, Spicy, Original, Honey Mustard Packaging Type: Bag, Box, Pouch, Canister Sales Channel: Supermarkets, Online Retailers, Specialty Stores, Convenience Stores |
| Companies Covered | Jack Link's, Hormel Foods Corporation, Conagra Brands, Tyson Foods, Quest Nutrition, Post Holdings, General Mills, Oberto Brands, Power Crunch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Protein Chips Market Trends and Innovations
Formulation science and processing hardware are converging to collapse the sensory gap between meat-based snacks and their starch-based predecessors, while regulatory scrutiny and channel fragmentation reshape go-to-market economics.
High-pressure extrusion technology is collapsing the texture barrier that previously relegated meat snacks to chewy jerky formats. Equipment manufacturers in Germany and Italy now supply systems capable of achieving brittle fracture mechanics comparable to potato chips. Fitness-oriented consumers in the United States and Australia are adopting these formats at rates that justify dedicated production lines.
EU EFSA nutrition claim regulations are tightening evidentiary requirements for protein content assertions on front-of-package labels. Processors must now submit amino acid scoring data to support density claims, elevating analytical chemistry costs. Export-oriented manufacturers in Brazil and Argentina are restructuring formulation targets to preempt compliance failures in European distribution.
Subscription box curation is displacing impulse purchase as the dominant trial mechanism for novel flavors. Direct-to-consumer platforms aggregate consumption data to predict reorder cycles and customize variety assortments. This pattern concentrates in coastal United States metro markets where delivery density supports economical last-mile economics.
Meat Protein Chips Market Segmentation
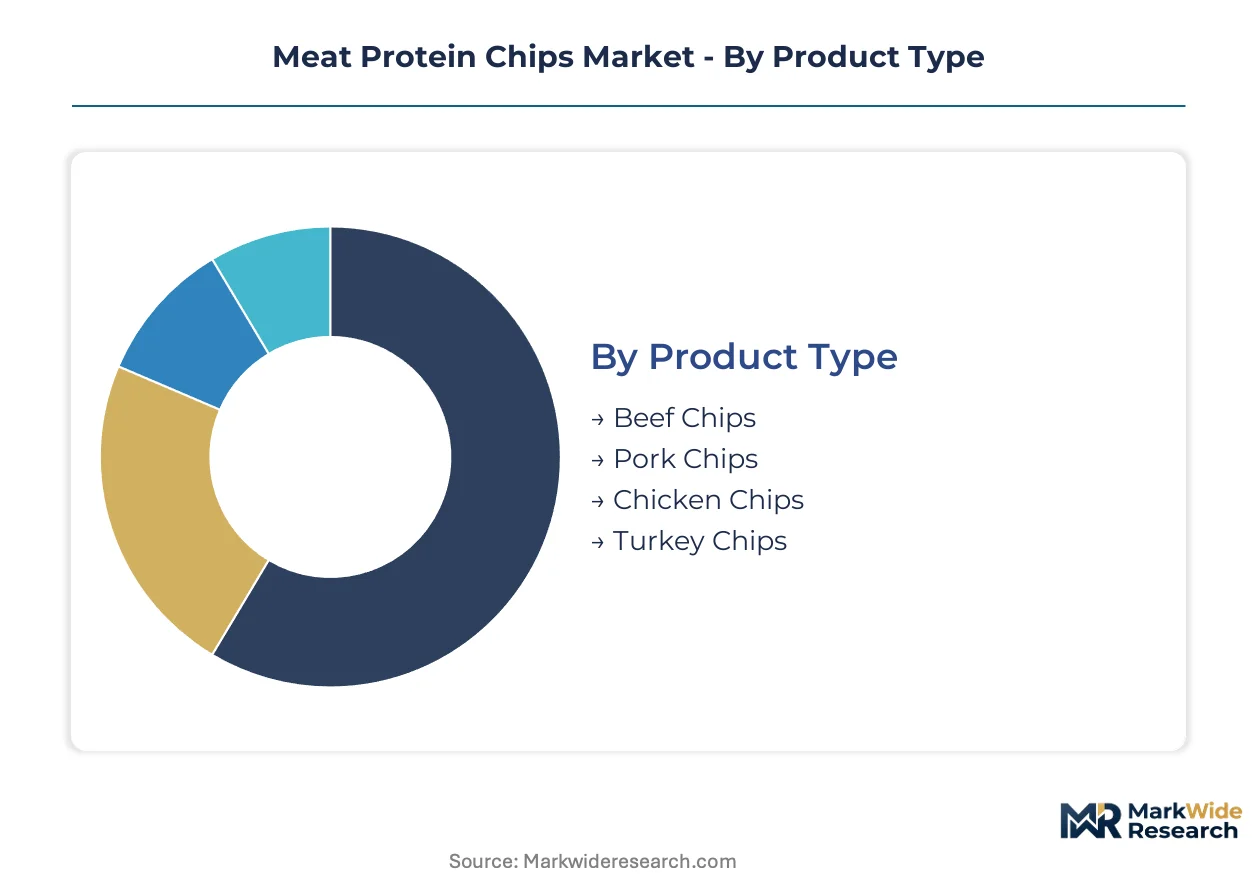
Segmentation in the meat protein chips market reveals how protein source preferences, flavor innovation, and channel economics create distinct competitive battlegrounds. Each dimension carries different margin profiles and regulatory exposure, forcing processors to prioritize investments across incompatible production requirements.
Product Type:
Mature formats built on established jerky familiarity coexist with emerging poultry alternatives that sidestep processed-meat stigma.
- Beef Chips:Thin-sliced dehydrated beef delivers 10–15 grams of protein per serving with amino acid profiles preserved through low-temperature vacuum drying. United States consumers concentrated in fitness-oriented coastal metro markets drive volume, though feedlot cost volatility compresses processor margins during drought cycles in the Great Plains.
- Pork Chips:Hormel Foods leverages captive pork processing infrastructure to secure raw material supply at scale, achieving cost structures that undercut beef-dependent competitors. Backward integration into hog farming insulates margin exposure from commodity price swings.
- Chicken Chips:Lower processed-meat advisory risk from WHO classifications enables cleaner front-of-package messaging in health-conscious retail channels.
- Turkey Chips:Lean protein density appeals to calorie-restricted diet protocols without sacrificing shelf-stable portability.
Beef chips retain volume leadership; turkey chips hold the steepest expansion curve.
Flavor Profile:
Application-driven segmentation separates impulse-trial formats from habitual-repurchase anchors in consumer pantries.
- Barbecue:Smoked-sweet formulations dominate convenience store placements where familiarity reduces purchase friction. United States southern states show disproportionate velocity, with repeat rates exceeding other flavor variants in rural distribution.
- Spicy:Capsicum-forward heat levels attract younger demographics in direct-to-consumer subscription channels where customization algorithms surface bold profiles. Australian fitness communities demonstrate parallel adoption patterns.
- Original:Unflavored base recipes serve clean-label positioning in natural grocery channels.
- Honey Mustard:Sweet-tangy balance targets afternoon snacking occasions in office vending installations.
Original commands the widest retail distribution; spicy posts the highest velocity in digital-native channels.
Packaging Type:
Cost tier stratification separates premium positioning from economy access across divergent shipping economics.
- Pouch:Lightweight flexible film with resealable zipper closures minimizes dimensional weight charges in direct-to-consumer fulfillment. Subscription box curation concentrates in United States coastal metros where delivery density supports economical last-mile economics.
- Bag:Standard pillow pouches dominate supermarket shelf-ready displays with lower unit cost but inferior protection against moisture ingress.
- Box:Rigid carton structures enable gift-set assembly and variety pack configurations in specialty retail.
- Canister:Cylindrical rigid containers protect brittle extruded textures through extended supply chain handling.
Pouch captures margin preference in digital channels; bag maintains cost leadership in brick-and-mortar.
Sales Channel:
Customer type fragmentation splits between planned-stockpile behavior and immediate-consumption triggers.
- Online Retailers:Direct-to-consumer platforms bypass slotting fee structures that consume 15–25 percent of revenue in conventional retail. Consumption pattern data enables predictive reorder cycles and flavor customization based on individual protein intake tracking.
- Supermarkets:National chain buyers control shelf-space allocation decisions that determine category visibility for emerging brands.
- Specialty Stores:Natural grocery channels validate clean-label claims through third-party certification requirements.
- Convenience Stores:Impulse placement at checkout counters captures unplanned protein snack occasions.
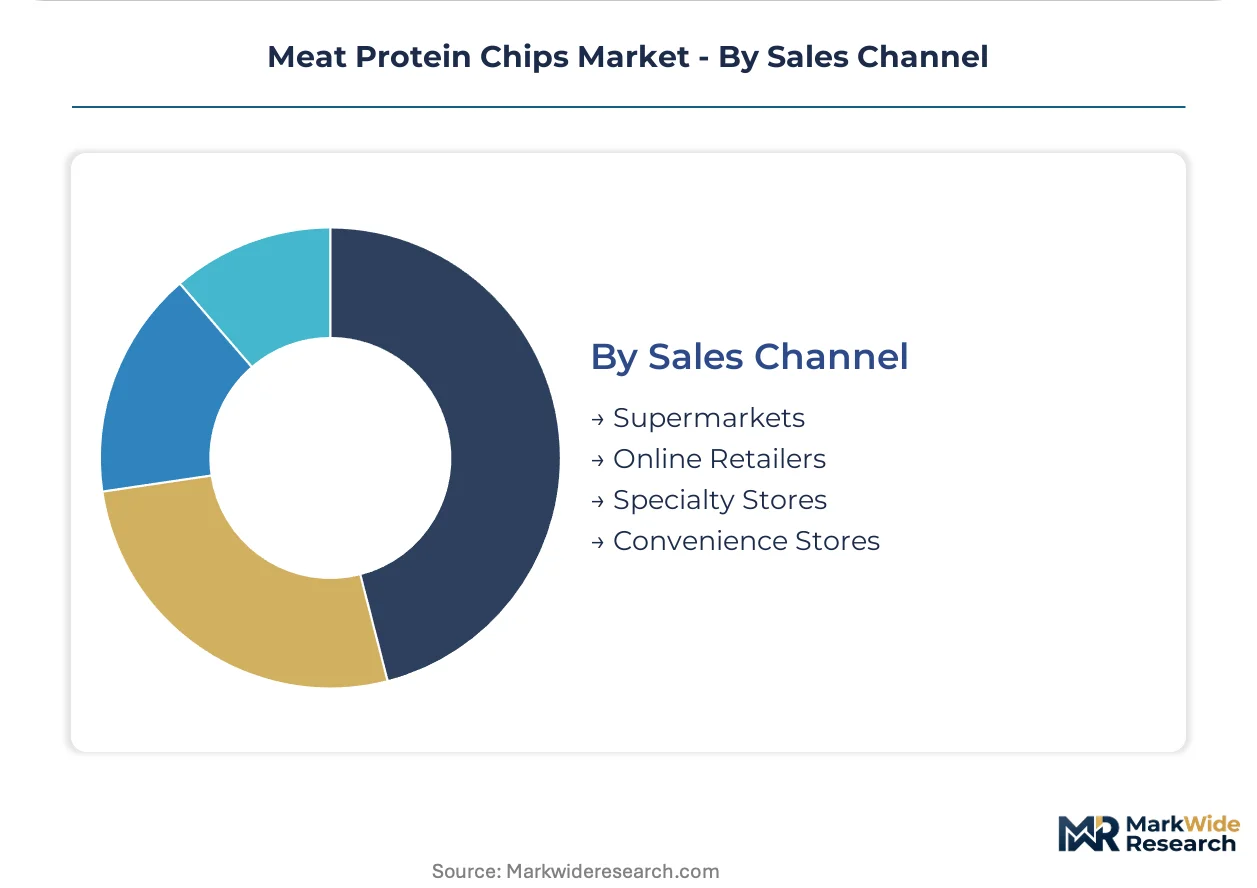
Supermarkets anchor absolute volume; online retailers climb the fastest in revenue contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies: developed markets absorb premium positioning while emerging economies demand volume-accessible formats. This demand-elasticity contrast shapes where processors invest in dehydration capacity versus where they license production.
United States
Fitness-tracking integration and protein-forward snacking culture drive per-capita consumption leadership. USDA FSIS inspection infrastructure elevates compliance costs that filter out subscale competitors. Texas and Nebraska host concentrated feedlot-to-processor corridors where drought cycles in the Great Plains periodically compress margins.
Germany
EFSA nutrition claim regulations tighten evidentiary requirements for protein density assertions on front-of-package labels. Clean-label processing certification commands price premiums in natural grocery channels concentrated in Bavaria and North Rhine-Westphalia. Stuttgart-based equipment manufacturers supply high-pressure extrusion systems achieving brittle textures.
Australia
Wearable device ecosystems surface protein intake metrics among quantified-self consumers in Sydney and Melbourne metro markets. TGA labeling standards govern health claim substantiation for export-oriented processors. Queensland beef processing infrastructure supports dehydration capacity expansion serving Asia-Pacific distribution.
Brazil
Feedlot cost advantages relative to North American competitors enable competitive export pricing for beef chip formulations. ANVISA processed food regulations structure labeling requirements for regional distribution. São Paulo state anchors domestic consumption while southern cattle regions supply raw material.
Japan
Calorie-restricted diet protocols drive turkey chip adoption for lean protein density without refrigerated logistics. PMDA and Ministry of Health standards govern functional food classifications affecting import clearance. Tokyo-Osaka corridor convenience retail channels test flavor innovation for regional palate adaptation.
Meat Protein Chips Market Competitive Landscape
Capability concentration sits with specialized dehydration technology developers; scale advantage sits with diversified protein processors possessing captive raw material supply. The market structures around three tiers: legacy jerky manufacturers leveraging existing USDA inspection infrastructure, diversified food conglomerates integrating meat chip portfolios into broader snacking divisions, and direct-to-consumer specialists optimizing subscription economics. Dominant competitive moves include backward integration into hog farming to secure margin insulation, and capacity expansion into poultry-based formulations to sidestep processed-meat advisory stigma.
Among legacy jerky specialists, Jack Link's exemplifies scale-driven manufacturing infrastructure repurposed for chip formats. Hormel Foods Corporation occupies a position representing backward-integrated pork processing advantage. Quest Nutrition sits within the formulation-science archetype, translating protein bar expertise into snack texture innovation.
| Leading Market Players |
|---|
| Jack Link's |
| Hormel Foods Corporation |
| Conagra Brands |
| Tyson Foods |
| Quest Nutrition |
| Post Holdings |
| General Mills |
| Oberto Brands |
| Power Crunch |
| Others |
Pricing and Supply Chain Analysis
Nebraska's feedlot-to-processor corridors anchor raw material availability, with drought cycles in the Great Plains periodically constraining beef supply and amplifying spot-price volatility for dehydration-dependent chip manufacturers. This geographic concentration of upstream protein sourcing translates directly into margin compression risks for processors lacking captive supply arrangements or long-term contract coverage.
Pricing Analysis
Subscription recurring revenue drives lifetime value capture as direct-to-consumer platforms bypass conventional retail slotting fees that consume substantial revenue share. Three-tier pricing structure across premium, standard, and economy levels separates clean-label certified products from conventional formulations and private-label alternatives. Pricing pressure stems from feedlot capacity constraints and energy cost inflation in refrigerated pre-processing logistics. Budget-conscious convenience store buyers exhibit highest price sensitivity, while fitness-tracking integrated consumers in coastal metros absorb premium positioning.
Supply Chain Analysis
Supplier-financing facilities from equipment manufacturers in Germany and Italy extend payment terms for high-pressure extrusion systems facing extended delivery backlogs. Raw material sourcing draws from United States beef feedlots, Brazilian cattle regions, and Queensland processing infrastructure. Critical dependencies include vacuum drying equipment, flexible film packaging substrates, and amino acid testing reagents. Single-source vulnerability concentrates in Italian extrusion machinery suppliers. Distribution runs through direct-to-consumer fulfillment centers, national supermarket distribution networks, and convenience store wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wearable device ecosystem integration transforms protein snacking from impulse purchase into data-driven replenishment, with fitness platform APIs enabling automated reorder triggers based on logged activity and intake gaps.
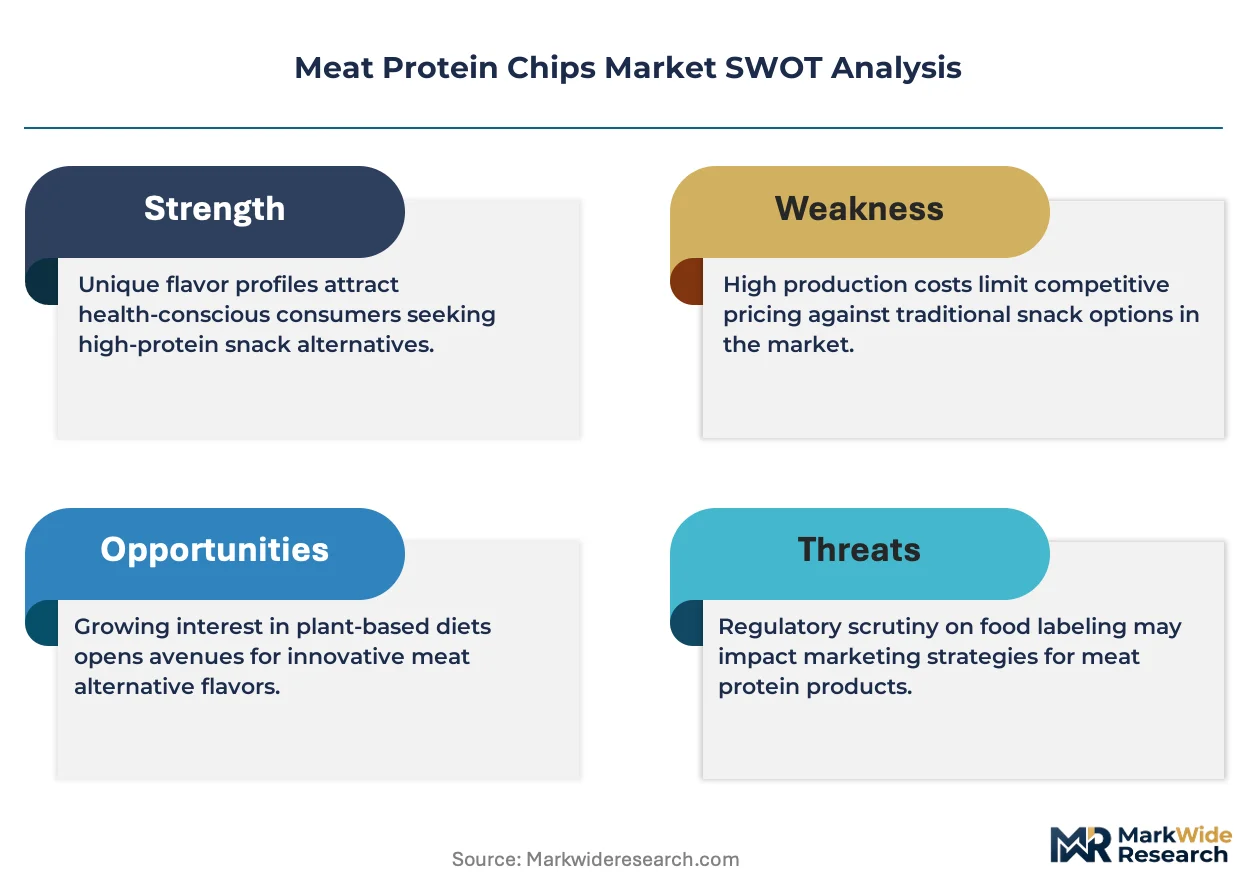
For Market Incumbents: Insulate margin structures through backward integration into hog farming or captive poultry processing, securing raw material supply against commodity volatility. Expand dehydration capacity in Texas and Nebraska corridors to reduce logistics costs. Defend shelf position against emerging plant-blended entrants by accelerating clean-label certification timelines. For New Entrants and Emerging Players: Turkey and chicken chip white space in natural grocery channels represents the most penetrable entry point, sidestepping WHO processed-meat advisory stigma that constrains beef-focused competitors. Direct-to-consumer subscription models with flavor customization algorithms offer lower customer acquisition costs than conventional retail slotting fee structures. Target quantified-self consumers in Sydney and Melbourne metro markets where wearable ecosystem density supports automated demand triggers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized dehydration equipment developers with proprietary high-pressure extrusion IP. Five-to-ten year viability hinges on regulatory trajectory for processed meat classifications and clean-label certification standardization. Acquisition target archetypes include mid-scale processors with existing USDA FSIS inspection infrastructure and underutilized capacity. Monitor EFSA amino acid scoring enforcement as signal for European market access barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Poultry-Based Formulation Expansion | Turkey and chicken alternatives sidestep WHO advisory stigma while maintaining protein density claims. |
| Backward Integration into Hog Farming | Hormel's captive pork supply demonstrates margin insulation against commodity price swings. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models bypass slotting fees and enable consumption-pattern-driven flavor customization. |
| Clean-Label Processing Certification | Third-party validation commands price premiums in natural grocery channels concentrated in Bavaria. |
| High-Pressure Extrusion Capacity Addition | German and Italian equipment achieves brittle textures that replicate conventional chip mouthfeel. |
Research Methodology
A standing panel of dehydration technology engineers, USDA FSIS compliance officers, retail category buyers, and direct-to-consumer subscription platform operators provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA nutrition labeling guidance documents, USDA Agricultural Marketing Service livestock price reports, EFSA nutrition claim substantiation databases, and customs records tracking dried meat product trade flows. Bottom-up volume modeling triangulated against top-down protein snacking expenditure estimates.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions including protein source, flavor profile, packaging format, and sales channel. CAGRs derived from fitted growth curves applied to historical protein snack adoption patterns, calibrated by wearable device penetration rates and fitness-tracking ecosystem expansion. Forecast inputs incorporated feedlot capacity utilization cycles, extrusion equipment delivery backlogs, and evolving WHO processed meat advisory positions.
Practitioners should monitor drought severity indices in the Great Plains, EFSA amino acid scoring enforcement timelines, and wearable platform API integration expansions for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
North America Frozen Snacks Market
Snacks
Granola Market
Snacks
Cheese Snacks Market
Snacks
Europe Nuts and Cereal Snacks Bar Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
No Fat Snacks Market
Snacks
Pretzel Salts Market
Snacks
Crackers Market
Snacks
North America Cereal Bar Market
Snacks
Europe Cereal Bar Market
Snacks
Snack Pellets Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Austria Snack Bar Market
Snacks
Saudi Arabia French Fries Market
Snacks
Duck Neck (Chinese Snack) Market
Snacks
Energy Balls Market